
 Global Smart Leak Detection Solutions Market | 2026-2036
Global Smart Leak Detection Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Leak Detection Solutions Market Foresight
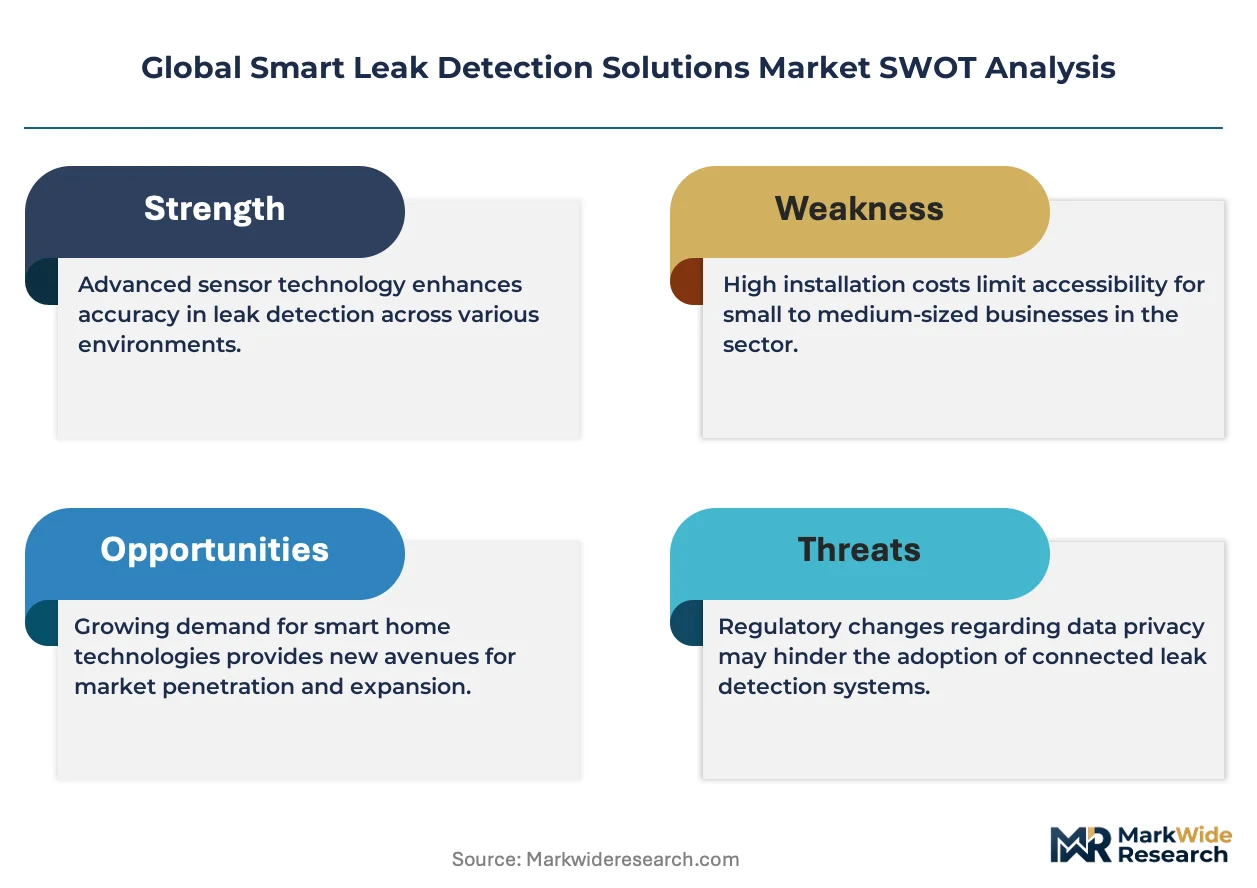
The EU F-Gas Regulation is restructuring compliance costs for leak detection vendors serving HVAC and industrial refrigeration clients across Europe. Honeywell leverages its building automation portfolio to integrate refrigerant monitoring with existing climate control infrastructure. Siemens sustains engineering depth in acoustic sensor arrays for oil and gas transmission corridors. Pure Technologies Ltd specializes in fiber optic distributed sensing for water pipeline integrity, anchoring its position in municipal utility tenders.
Smart leak detection solutions combine sensor hardware, connectivity protocols, and analytics software to identify fluid or gas escapes in pressurized systems before catastrophic failure. Acoustic sensors detect pressure wave anomalies propagating through metallic and non-metallic pipe walls, with detection thresholds typically spanning 0.1 to 10 liters per minute depending on pipe material and sensor spacing. Pressure sensors dominate retrofit installations in water supply networks where capital budgets constrain full infrastructure replacement. Cloud-based deployment modes are capturing expanding share among municipal utilities seeking centralized visibility across geographically dispersed distribution grids.
The EPA enforces lead and copper rule revisions compelling US water utilities to inventory and replace service lines, directly stimulating sensor procurement for leak pinpointing prior to excavation. EMA and national regulators across Europe incorporate ISO 50001 energy management standards that reward continuous monitoring of steam and compressed air systems for unplanned losses. REACH compliance adds material traceability requirements for sensor housings deployed in chemical processing environments. Stakeholders must weigh edge computing architectures against satellite-enabled backhaul as pipeline operators prioritize sub-second alert latency over cloud analytics sophistication.
Market Dynamics
Acoustic sensor arrays paired with edge computing architectures are compressing alert latency from minutes to sub-second intervals, forcing vendors to reengineer hardware-software integration or surrender municipal utility contracts to faster competitors.
Growth Catalysts
- EPA lead service line replacement mandates:US water utilities must inventory and replace aging infrastructure, triggering sensor procurement for pre-excavation leak pinpointing across thousands of distribution systems.
- EU F-Gas Regulation phase-down schedules:HVAC and industrial refrigeration operators face escalating compliance costs for refrigerant leaks, accelerating demand for continuous monitoring systems integrated with building automation.
- German drought resilience programs:Municipal utilities in water-stressed regions deploy fiber optic distributed sensing to reduce non-revenue water losses below 10% thresholds required by federal performance benchmarks.
Market Restraints
- Capital intensity of full-grid sensor deployment:Municipal utilities with constrained rate bases cannot finance simultaneous pipeline replacement and monitoring infrastructure, forcing phased retrofit approaches that delay revenue recognition for vendors.
- Technical limitation in non-metallic pipe detection:Acoustic wave propagation attenuates rapidly in PVC and HDPE materials, degrading detection thresholds to 5-10 liters per minute versus 0.1-1 liter sensitivity in cast iron or steel.
- REACH material traceability requirements:Sensor housings deployed in chemical processing environments require documented supply chain compliance for restricted substances, extending procurement cycles by 4-6 months.
Strategic Opportunities
- India's smart city mission expansion:Urban local bodies in Bengaluru, Hyderabad, and Pune are piloting IoT-enabled water distribution monitoring with central government co-funding, creating first-mover advantages for vendors establishing local calibration facilities.
- Technology convergence of satellite backhaul and edge analytics:Pipeline operators in remote extraction corridors are testing hybrid architectures that prioritize alert transmission over cloud sophistication, opening new deployment models for midstream oil and gas.
- California's Senate Bill 555 water loss performance standards:Urban retail water suppliers must validate system-wide audits every five years, institutionalizing recurring sensor maintenance contracts and software subscription revenue streams.
Industry Challenges
- Scarcity of certified field technicians:Installation and calibration of distributed acoustic sensing systems requires specialized training in fiber optic handling and signal interpretation, with certification programs lagging deployment timelines in multiple markets.
- Integration complexity with SCADA legacy systems:Municipal utilities operate decades-old control architectures with proprietary protocols, forcing vendors to develop middleware layers that extend implementation cycles and inflate project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Leak Detection Solutions Market |
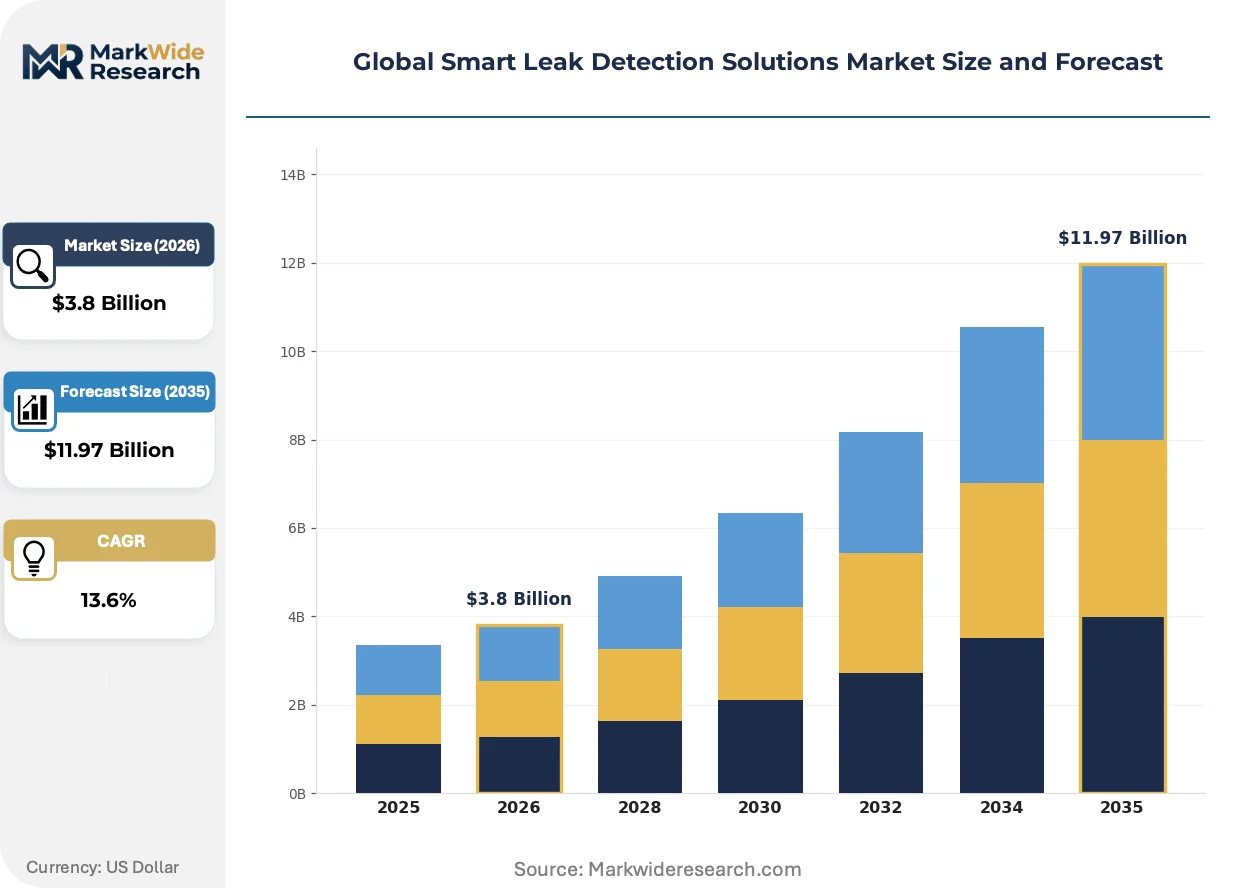
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Acoustic Sensors, Pressure Sensors, Ultrasonic Detectors, Infrared Sensors, Fiber Optic Sensors, Electromagnetic Sensors Application Sector: Water Supply Networks, Oil & Gas Pipelines, HVAC Systems, Chemical Processing, Fire Protection Systems, Manufacturing Facilities Deployment Mode: Cloud-Based, On-Premises, Hybrid Systems, Edge Computing, Wireless Networks, Satellite-Enabled End User Industry: Municipal Utilities, Petrochemical Firms, Facility Management, Environmental Agencies, Construction Firms, Agricultural Enterprises |
| Companies Covered | Flume, Fibaro, Honeywell, LeakSMART, D-Link, Siemens, Phyn, Pure Technologies Ltd, Moen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Leak Detection Solutions Market Shifts & Advancements
Machine learning inference at the sensor node is collapsing the traditional boundary between detection hardware and analytics platforms, enabling autonomous leak classification without cloud dependency.
Distributed acoustic sensing using fiber optic cables as continuous sensor elements is automating pipeline surveillance across hundreds of kilometers from single interrogator units. Midstream oil and gas operators in the Permian Basin and North Sea corridors are deploying these systems at accelerating pace, replacing discrete point sensors with linear coverage that eliminates blind spots between monitoring nodes. The technology is automating shift from scheduled inspection rounds to continuous integrity monitoring, compressing incident response from hours to seconds.
REACH compliance deadlines for per- and polyfluoroalkyl substances are restructuring material specifications for sensor housings and seals in European chemical processing environments. Industrial operators must validate that leak detection equipment contacting process fluids contains no restricted fluorinated compounds, forcing vendors to reformulate product lines and recertify existing installations. Germany's chemical cluster along the Rhine and Netherlands' Rotterdam port complex are experiencing the most acute procurement friction as replacement deadlines approach.
Subscription-based software licensing is displacing perpetual ownership models in municipal utility procurement. California water districts and German municipal utilities now prioritize vendors offering predictive analytics dashboards with annual renewal terms over capital-intensive hardware purchases, transferring technology obsolescence risk from buyer to supplier. This shift is most visible in cloud-based deployment modes where centralized visibility across geographically dispersed grids justifies ongoing operational expenditure over depreciable asset accounting.
Global Smart Leak Detection Solutions Market Segmentation
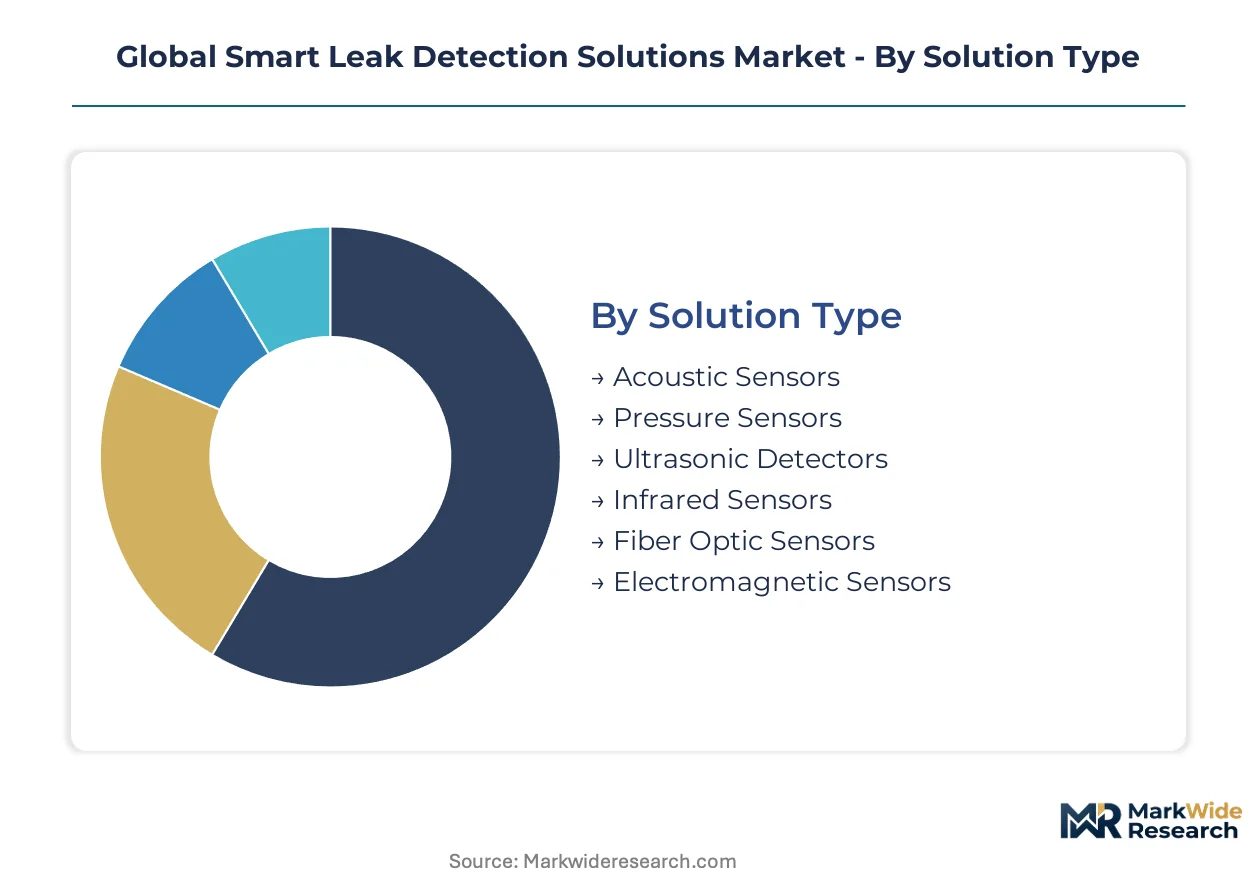
Technology selection in smart leak detection hinges on pipe material compatibility, alert latency requirements, and integration complexity with legacy control systems. Procurement patterns diver sharply between municipal utilities prioritizing capital efficiency and oil and gas operators demanding sub-second response times across remote corridors.
Solution Type:
Capital allocation and detection sensitivity thresholds drive sensor selection across infrastructure vintages and fluid types.
- Acoustic Sensors:Pressure wave anomaly detection spans 0.1 to 10 liters per minute depending on pipe material and sensor spacing. Demand concentrates in German municipal water networks where federal benchmarks mandate non-revenue water losses below 10 percent. Cast iron and steel pipelines transmit acoustic signatures with minimal attenuation, enabling precise leak pinpointing prior to excavation.
- Pressure Sensors:Retrofit installations dominate water supply networks where capital budgets constrain full infrastructure replacement. California urban retail water suppliers deploy these for Senate Bill 555 compliance, validating system-wide audits every five years with recurring maintenance contracts.
- Ultrasonic Detectors:Non-invasive flow measurement suits HVAC and industrial refrigeration applications facing EU F-Gas Regulation phase-down schedules.
- Infrared Sensors:Thermal imaging identifies refrigerant and gas escapes in building automation integrations across European commercial facilities.
- Fiber Optic Sensors:Distributed acoustic sensing automates pipeline surveillance across hundreds of kilometers from single interrogator units in Permian Basin and North Sea corridors.
- Electromagnetic Sensors:Metal pipe detection in aging water infrastructure serves pre-excavation leak location under EPA lead service line replacement mandates.
Volume sits with pressure sensors; growth tilts toward fiber optic distributed sensing.
Application Sector:
Regulatory compliance timelines and asset criticality shape deployment intensity across verticals.
- Water Supply Networks:Municipal utilities across Germany and California anchor procurement volumes. Drought resilience programs and federal performance benchmarks accelerate fiber optic and acoustic sensor deployment to reduce distribution losses.
- Oil & Gas Pipelines:Midstream operators in remote extraction corridors prioritize hybrid satellite-edge architectures for sub-second alert transmission. Distributed acoustic sensing eliminates blind spots between discrete monitoring nodes across North Sea and Permian Basin infrastructure.
- HVAC Systems:EU F-Gas Regulation compliance costs escalate for refrigerant leaks, driving continuous monitoring integration with building automation.
- Chemical Processing:REACH material traceability requirements extend procurement cycles for sensor housings in Rhine corridor and Rotterdam port complex facilities.
- Fire Protection Systems:Pressurized sprinkler network monitoring serves commercial and industrial facility insurance compliance.
- Manufacturing Facilities:ISO 50001 energy management standards reward steam and compressed air loss monitoring across European industrial operations.
Deployment value concentrates in water networks; steepest expansion trajectory emerges in oil and gas pipeline automation.
Deployment Mode:
Connectivity architecture trade-offs pit analytics sophistication against alert latency in geographically dispersed operations.
- Cloud-Based:Centralized visibility across geographically dispersed distribution grids justifies operational expenditure over depreciable asset accounting. California water districts and German municipal utilities prioritize predictive analytics dashboards with annual renewal terms.
- Edge Computing:Machine learning inference at the sensor node enables autonomous leak classification without cloud dependency. Pipeline operators prioritize sub-second alert latency over centralized analytics sophistication.
- On-Premises:Air-gapped installations serve critical infrastructure operators with cybersecurity constraints.
- Hybrid Systems:Middleware layers bridge decades-old SCADA architectures with modern sensor networks, extending implementation cycles.
- Wireless Networks:Cellular and LoRaWAN backhaul suits urban distribution grids with existing telecommunications coverage.
- Satellite-Enabled:Remote extraction corridors in the Permian Basin and North Sea test hybrid satellite-edge architectures where terrestrial connectivity is unavailable.
Subscription revenue concentrates in cloud-based deployment; edge computing architectures gain share fastest among latency-sensitive operators.
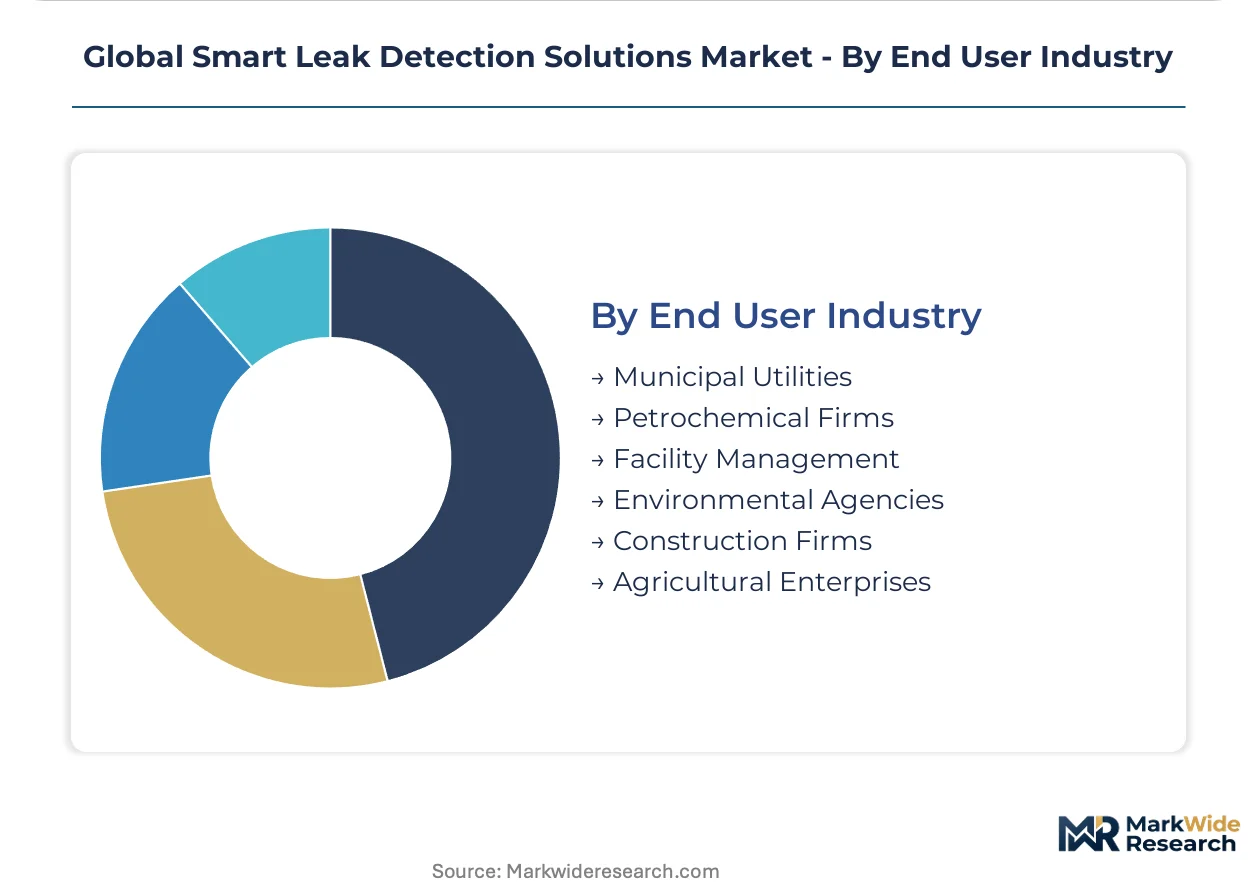
End User Industry:
Budget authority and regulatory exposure determine procurement velocity and contract structure preferences.
- Municipal Utilities:Constrained rate bases force phased retrofit approaches that delay vendor revenue recognition. EPA lead service line replacement mandates and California Senate Bill 555 institutionalize recurring sensor maintenance contracts.
- Petrochemical Firms:Pipeline integrity management drives distributed acoustic sensing procurement across extraction and transmission corridors.
- Facility Management:Building automation integration demands from HVAC and refrigeration operators accelerate under EU F-Gas Regulation compliance timelines.
- Environmental Agencies:Water loss audit validation and enforcement activities stimulate sensor procurement for regulatory oversight.
- Construction Firms:Pre-commissioning leak testing and infrastructure replacement projects generate project-based sensor rental demand.
- Agricultural Enterprises:Irrigation network monitoring serves water-stressed regions with federal or state conservation funding support.
Contract volume sits with municipal utilities; margin expansion tilts toward petrochemical pipeline operators demanding premium latency performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free economic zones in the UAE and special industrial parks in South Korea concentrate manufacturing capacity for sensor components serving leak detection system integrators worldwide.
United States
EPA lead service line replacement mandates and California Senate Bill 555 water loss audits drive municipal utility procurement. Urban retail water suppliers in Los Angeles and San Diego deploy fiber optic distributed sensing to validate system-wide infrastructure integrity. The Permian Basin anchors midstream oil and gas pipeline automation demand.
Germany
Federal non-revenue water benchmarks below 10 percent and drought resilience programs accelerate acoustic sensor deployment. The Rhine corridor chemical cluster faces REACH compliance deadlines for sensor housing materials. Munich and Hamburg municipal utilities pioneer subscription-based predictive analytics contracts.
China
Dual carbon goals and smart city initiatives in Yangtze River Delta cities stimulate IoT-enabled water distribution monitoring. National regulators enforce industrial energy efficiency standards rewarding steam and compressed air loss detection. Shenzhen and Shanghai host calibration facilities for fiber optic sensing equipment.
India
Smart city mission expansion in Bengaluru, Hyderabad, and Pune pilots municipal water monitoring with central government co-funding. The Bureau of Indian Standards develops certification protocols for acoustic sensor arrays. Gujarat and Maharashtra industrial corridors test edge computing architectures for sub-second alert latency.
United Kingdom
Ofwat performance commitments on leakage reduction compel water utilities to deploy pressure sensor networks across aging distribution infrastructure. The Thames Tideway super sewer project stimulates pre-commissioning leak testing demand. Scottish Water advances satellite-enabled backhaul trials for remote highland pipeline corridors.
Global Smart Leak Detection Solutions Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology segments, creating a tiered structure where scale advantages in building automation integration clash with engineering depth in niche sensing modalities. The vendor base organizes around three strategic archetypes: industrial automation conglomerates leveraging cross-selling synergies, sensing technology specialists defending positions through proprietary hardware-software integration, and emerging IoT-native challengers attacking with subscription-first commercial models. Consolidation pressure intensifies as municipal utilities consolidate procurement around full-stack providers capable of spanning sensor deployment through predictive maintenance software.
Within the industrial automation tier, Honeywell and Siemens exemplify conglomerate strategies that embed leak detection within broader building and infrastructure control portfolios. Pure Technologies Ltd occupies a distinct position as a sensing specialist concentrated on fiber optic distributed sensing for pipeline integrity applications. These three anchors represent divergent competitive vectors: cross-platform integration, discrete engineering excellence, and vertical technology concentration.
| Leading Market Players |
|---|
| Flume |
| Fibaro |
| Honeywell |
| LeakSMART |
| D-Link |
| Siemens |
| Phyn |
| Pure Technologies Ltd |
| Moen |
| Others |
Supply & Pricing Matrix
Municipal utilities with constrained rate bases dominate procurement volumes, anchoring the market to subscription-based software licensing with annual renewal terms rather than capital-intensive hardware purchases. This buyer concentration transfers technology obsolescence risk from ratepayers to vendors while compressing upfront margins in favor of recurring revenue streams.
Pricing Analysis
Short lead-time premiums command substantial markups over standard delivery schedules as utilities facing EPA lead service line replacement deadlines prioritize rapid deployment. Pricing stratifies across premium, standard, and economy tiers differentiated by sensor sensitivity thresholds and after-sales service bundling. Cost compression in the economy tier is intensifying because Chinese sensor component imports are flooding calibration-light pressure sensor segments. Municipal utilities remain the most price-sensitive buyers, while petrochemical pipeline operators absorbing distributed acoustic sensing systems show minimal elasticity for sub-second latency guarantees.
Supply Chain Analysis
Regional distribution centers in Germany, South Korea, and the United States anchor hub-and-spoke fulfillment patterns serving system integrators across three continents. Manufacturing draws from specialized fiber optic cable production in China, precision acoustic transducer fabrication in Japan, and semiconductor components from Taiwan. Single-source vulnerability concentrates in rare earth-doped fiber production for distributed sensing applications. Distribution runs through authorized system integrators who handle field calibration and SCADA middleware integration, extending fulfillment cycles by 4-6 months for complex municipal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified field technician scarcity props pricing power for vendors with captive training infrastructure, creating a supply-constrained environment where installation capacity bottlenecks limit market expansion regardless of sensor manufacturing scale.
For Market Incumbents: Hedge against IoT-native challengers attacking with subscription-first commercial models by deepening backward integration into fiber optic cable production and acquiring regional calibration facilities in India and the United Arab Emirates. Lock municipal utilities into multi-year predictive analytics contracts before pure-play specialists consolidate procurement around full-stack providers. For New Entrants and Emerging Players: Municipal water authorities in India's smart city mission cities represent the most penetrable channel partner type for establishing local presence without competing against entrenched European and North American incumbents. Target Bengaluru and Hyderabad with government co-funded pilot programs, then leverage proven deployment records to access private industrial water users in Gujarat's chemical corridor. For Investors and Strategic Acquirers: The window for entry favors vertically integrated sensing specialists with proprietary fiber optic interrogator technology and established utility relationships over hardware-agnostic software platforms. Monitor India's Bureau of Indian Standards certification protocol finalization as the inflection indicator determining which foreign vendors can access central government co-funded tenders at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Optic Cable Production | Captive supply of distributed sensing cores eliminates single-source dependency on Chinese rare-earth doped fiber manufacturers. |
| Local Calibration Facility Establishment | Bengaluru and Hyderabad facilities satisfy India's Bureau of Indian Standards proximity requirements for smart city mission eligibility. |
| SCADA Middleware Platform Acquisition | Proprietary protocol translation layers compress municipal utility implementation cycles currently extended by decades-old control architectures. |
| Predictive Analytics Dashboard Development | Annual renewal terms transfer technology obsolescence risk from California and German municipal ratepayers to vendor balance sheets. |
| Satellite-Edge Hybrid Architecture Pilot | Permian Basin and North Sea trials validate sub-second alert transmission without terrestrial connectivity infrastructure. |
Research Methodology
Trade association filings, customs records, and SEC 10-K disclosures formed the secondary backbone, supplemented by primary interviews with municipal utility engineering directors, SCADA integration specialists, fiber optic sensor calibration technicians, and industrial refrigeration compliance officers. Bottom-up and top-down triangulation validated sensor shipment volumes against utility capital expenditure disclosures and regulatory compliance timelines.
Historical trendline analysis across technology adoption curves in water infrastructure and oil and gas pipeline automation informed the projection framework. Modeled dimensions span solution type, deployment mode, application sector, and regional regulatory cluster, with CAGRs derived from segment-level growth rate convergence analysis. Forecast inputs incorporate EPA lead service line replacement mandate implementation pacing and EU F-Gas Regulation phase-down schedule compliance cost trajectories.
Caveats apply where REACH material traceability deadline extensions or Bureau of Indian Standards certification protocol delays could materially shift the outlook for European chemical processing and Indian municipal procurement respectively. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Drain Camera Market
Sensors
Handheld RFID Readers Market
Sensors
Vibration Monitoring Market
Sensors
Underground Service Locator Market
Sensors
Weigh-In-Motion System Market
Sensors
Cloud Camera Market
Sensors
Mobile Mapping Systems Market
Sensors
Asset Tags Market
Sensors
Fixed RFID Readers Market
Sensors
Global Heat Stress Monitor (HSM) Market
Sensors
Global Real-Time Locating Systems (RTLS) Market
Sensors
Alcohol Sensor Market
Sensors
Eye Tracking Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market
Sensors
Personal Navigation Devices Market
Sensors
Smart Mat Market