
 Automated Weather Observation System Market | 2026-2036
Automated Weather Observation System Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Weather Observation System Market Analysis
Airport operators and meteorological agencies is redrawing procurement patterns across the Automated Weather Observation System landscape. Vaisala Oyj anchors its position through deep vertical integration in sensor manufacturing and calibration services. Campbell Scientific, Inc. competes by specializing in ruggedized field instrumentation for remote deployment environments. Coastal Environmental Systems differentiates through concentrated focus on military and maritime aviation applications with hardened system architectures.
An Automated Weather Observation System constitutes an integrated meteorological sensor suite that autonomously measures, processes, and transmits atmospheric parameters including visibility, ceiling height, wind velocity, temperature, humidity, and barometric pressure with reporting intervals typically under one minute for aviation safety applications. Stationary systems dominate installed base volumes at major international airports while remote sensing systems represent the fastest-expanding category as lidar and ceilometer networks replace human observers for cloud base detection. Within end users, the aviation sector commands the largest dedicated budget flows, though agriculture is emerging as a structurally distinct growth corridor where automated stations support precision irrigation and frost protection decisions.
The FAA mandates AWOS certification under Advisory Circular 150/5220-16D while EASA enforces comparable sensor performance standards through CS-ADR-DSN aerodrome design specifications, and China's CAAC aligns domestic airport upgrades with GB standards for meteorological equipment interoperability. These regulatory frameworks directly determine product qualification timelines, sensor redundancy requirements, and market access eligibility for system integrators. Stakeholders must monitor evolving certification harmonization between FAA and EASA protocols, as divergence in ice detection and lightning proximity standards would fragment R&D roadmaps and complicate multinational deployment strategies.
Market Dynamics
Regulatory mandates from the FAA and EASA are compressing sensor certification timelines while lidar networks displace human observers for cloud base detection, forcing incumbent suppliers to requalify hardware architectures at accelerated cadences.
Growth Catalysts
- FAA NextGen Weather Technology:Precision approach mandates under Advisory Circular 150/5220-16D require airports to install automated runway visibility systems, creating immediate replacement demand at hub facilities.
- Precision Agriculture Irrigation:Automated stations for frost protection and variable-rate irrigation are penetrating row-crop operations in the US Corn Belt and Australian wheat belts.
- Lidar Ceilometer Networks:Remote sensing deployments are displacing manual observation protocols at secondary airfields, reducing operational labor costs while tightening reporting intervals.
Market Restraints
- Sensor Calibration Input Costs:Platinum resistance thermometers and barometric reference standards face price volatility tied to precious metals markets and specialized foundry capacity.
- Concentrated Lidar Component Supply:Eye-safe laser diode arrays and avalanche photodiode receivers concentrate in German and Japanese component houses, exposing integrators to single-source risk.
- EASA-FAA Divergence on Ice Detection:Inconsistent certification requirements for supercooled large droplet sensors fragment R&D roadmaps and delay multinational product launches.
Strategic Opportunities
- India Regional Airport Modernization:UDAN scheme subsidies and DGFT duty exemptions on meteorological equipment create entry points for AWOS providers at underserved airfields.
- Maritime Aviation Platforms:Hardened system architectures for offshore helicopter operations represent an underpenetrated segment with distinct procurement budgets from civil aviation authorities.
- GB Standards Alignment:China's CAAC harmonization with international sensor performance benchmarks accelerates domestic airport retrofit programs and opens qualification pathways for certified foreign suppliers.
Industry Challenges
- Meteorological Sensor Calibration Expertise:Shortages of technicians trained in traceable humidity and pressure reference procedures extend commissioning timelines at remote installations.
- Legacy Analog System Integration:Retrofit projects at aging airfields require protocol translation layers between modern digital sensor buses and existing copper-wire telemetry infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Weather Observation System Market |
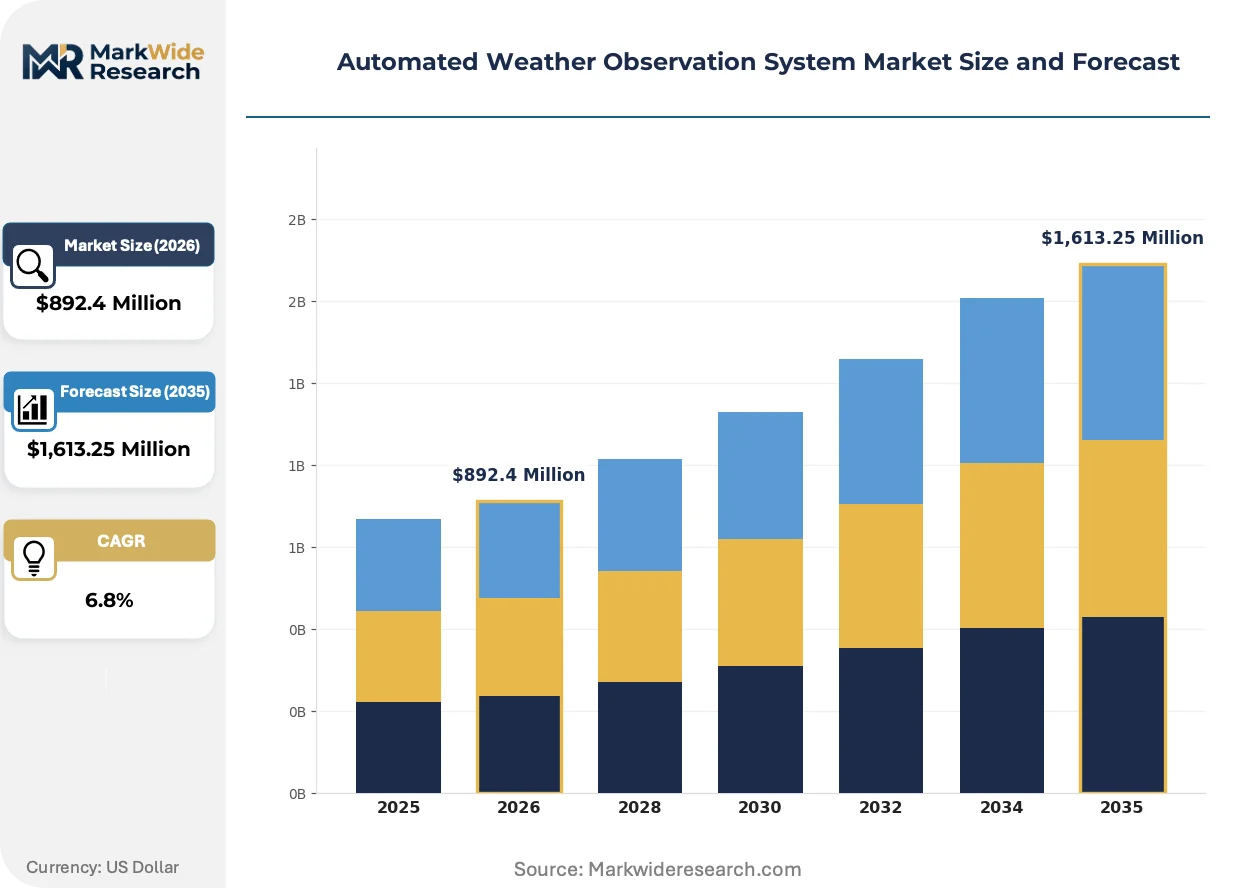
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Systems, Portable Systems, Remote Sensing Systems, Wireless Sensors End User: Government Agencies, Research Institutions, Aviation Sector, Agriculture Technology: Optical Sensors, Radar Systems, Data Loggers, Satellite Communication Application: Weather Forecasting, Climate Research, Disaster Management, Environmental Monitoring |
| Companies Covered | Vaisala Oyj, All Weather, Inc., Campbell Scientific, Inc., Coastal Environmental Systems, Optical Scientific Inc., AJY Engineering, Inc., Columbia Weather Systems Inc., OTT HydroMet, Gill Instruments Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Weather Observation System Market Emerging Trajectories
Sensor fusion architectures and edge computing deployments are compressing the physical footprint of field instrumentation while regulatory bodies tighten interoperability mandates across jurisdictions.
Solid-state wind sensors using ultrasonic time-of-flight measurement are miniaturizing. Regional airlines and general aviation airports are adopting these compact units for unattended remote installations. The technology is miniaturizing enclosure volumes by sixty percent versus mechanical cup-and-vane assemblies, enabling rooftop and tower-mount deployments previously precluded by structural load limits.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in refrigeration-dependent humidity sensors, forcing manufacturers to transition to chilled-mirror or polymer capacitive alternatives. Industrial consequence includes accelerated obsolescence of legacy probe designs and qualification delays for replacement architectures. Meteorological equipment suppliers serving European airports are responding with dual-certification programs that satisfy both REACH substance restrictions and EASA aerodrome design specifications.
Airport authorities are unbundling sensor maintenance from original equipment procurement, creating standalone service contracts with third-party calibration laboratories. Equipment distributors and regional integrators are capturing recurring revenue streams previously retained by manufacturers. This pattern is most visible in Germany and the United Kingdom, where civil aviation authorities have liberalized technical service provider accreditation.
Automated Weather Observation System Market Segmentation
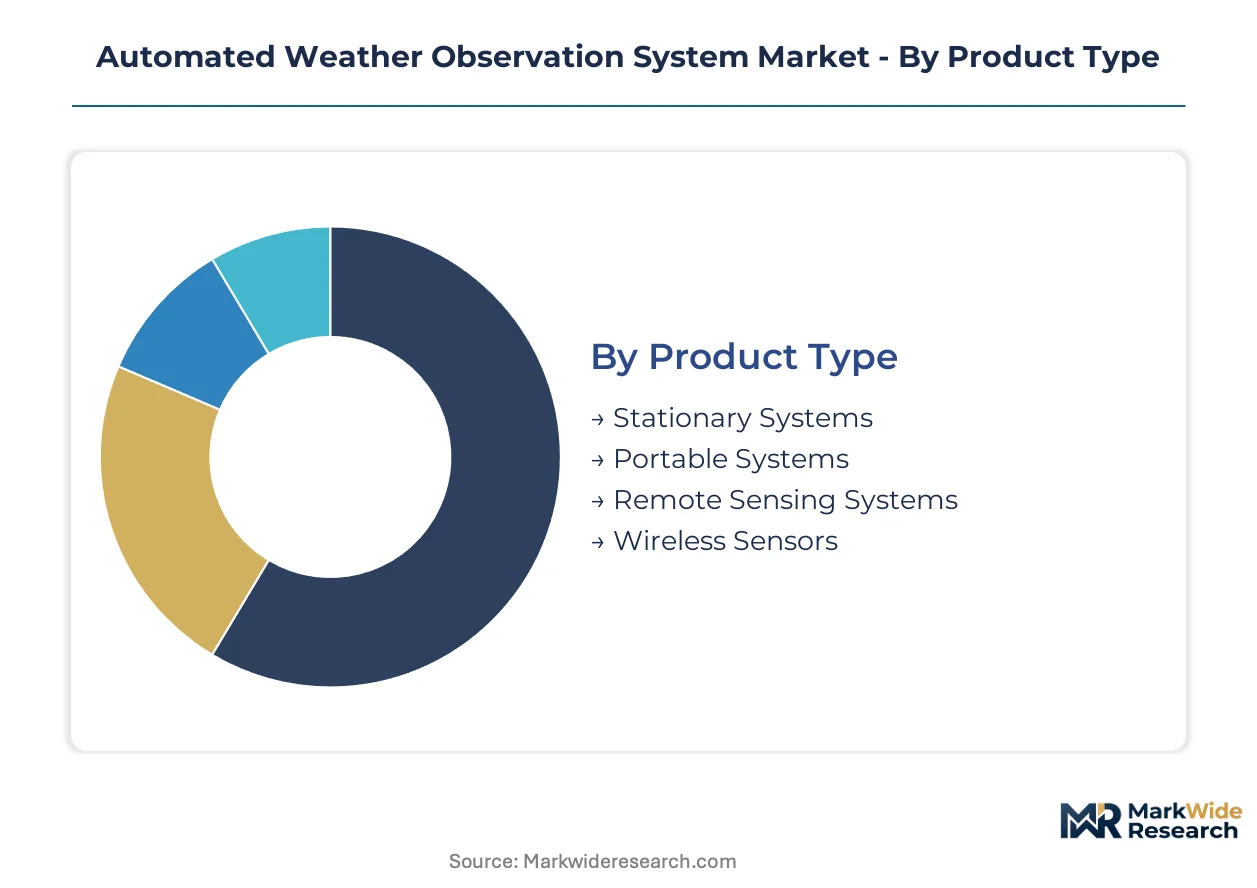
Automated Weather Observation System procurement patterns diverge sharply across installation contexts, with certification requirements from the FAA, EASA, and China's CAAC creating distinct qualification pathways that reshape competitive positioning in each segment. Understanding these structural divisions reveals where capital deployment concentrates and which technology architectures capture emerging budget flows.
Product Type:
FAA Advisory Circular 150/5220-16D mandates specific sensor redundancy levels for certified installations, while EASA aerodrome design specifications impose parallel but non-identical hardware architectures that fragment supplier qualification roadmaps across jurisdictions.
- Stationary Systems:Fixed installations at major international airports integrate platinum resistance thermometers, barometric pressure sensors, and ceilometers into hardened enclosures with dual-path telemetry. Hub facilities in the United States, Germany, and China drive replacement demand as legacy analog networks reach end-of-life, though sensor calibration expertise shortages extend commissioning timelines at remote sites.
- Remote Sensing Systems:Lidar ceilometer networks and optical precipitation detectors displace human observers for cloud base and visibility measurement, transmitting data via fiber or cellular backhaul. Secondary airfields across Europe adopt these configurations fastest under EASA cost-reduction directives, compressing reporting intervals below one minute while eliminating observer labor.
- Portable Systems:Rapid-deployment units serve military contingency operations and emergency response scenarios with battery-backed operation and collapsible masts.
- Wireless Sensors:Mesh-networked nodes enable dense spatial coverage for agricultural microclimate monitoring without trenching costs.
Stationary systems handle the majority of throughput; remote sensing systems are expanding most quickly on share as lidar costs decline.
End User:
Budget authority and procurement timelines vary dramatically across customer types, with aviation authorities operating under statutory safety mandates that override cost sensitivity.
- Aviation Sector:Civil aviation authorities and airport operators command dedicated capital budgets for runway visibility and wind shear detection under regulatory compliance deadlines. Precision approach upgrades at hub facilities in the United States and China concentrate procurement volumes, with NextGen and GB standards alignment accelerating replacement cycles.
- Agriculture:Row-crop operators and vineyard managers deploy automated stations for frost protection alerts and variable-rate irrigation scheduling. The US Corn Belt and Australian wheat belts show fastest uptake where commodity prices justify capital expenditure, though price volatility in platinum-based sensors creates input cost uncertainty.
- Government Agencies:National meteorological services maintain synoptic observation networks with standardized equipment specifications.
- Research Institutions:Universities and climate laboratories procure specialized configurations for boundary-layer studies and model validation campaigns.
Aviation commands the largest dedicated budget flows; agriculture is climbing the fastest as precision farming adoption accelerates.
Technology:
Component supply concentration in German and Japanese laser diode houses exposes integrators to single-source risk, while EU F-Gas Regulation forces humidity sensor architecture transitions.
- Optical Sensors:Forward-scatter visibility meters and laser ceilometers dominate cloud base and runway visual range measurement, with eye-safe 905nm and 1550nm wavelengths displacing legacy incandescent sources. EASA and FAA certification harmonization efforts determine qualification timelines for next-generation photodiode receiver arrays.
- Radar Systems:Doppler wind profilers and precipitation radars provide volumetric atmospheric data for terminal area forecasting and severe weather detection.
- Data Loggers:Ruggedized acquisition units with redundant storage meet aviation-grade availability requirements.
- Satellite Communication:Iridium and Inmarsat backhaul enable Antarctic, maritime, and remote continental deployments beyond cellular coverage.
Optical sensors anchor the installed base; radar systems are gaining share fastest as wind profiling demand intensifies.
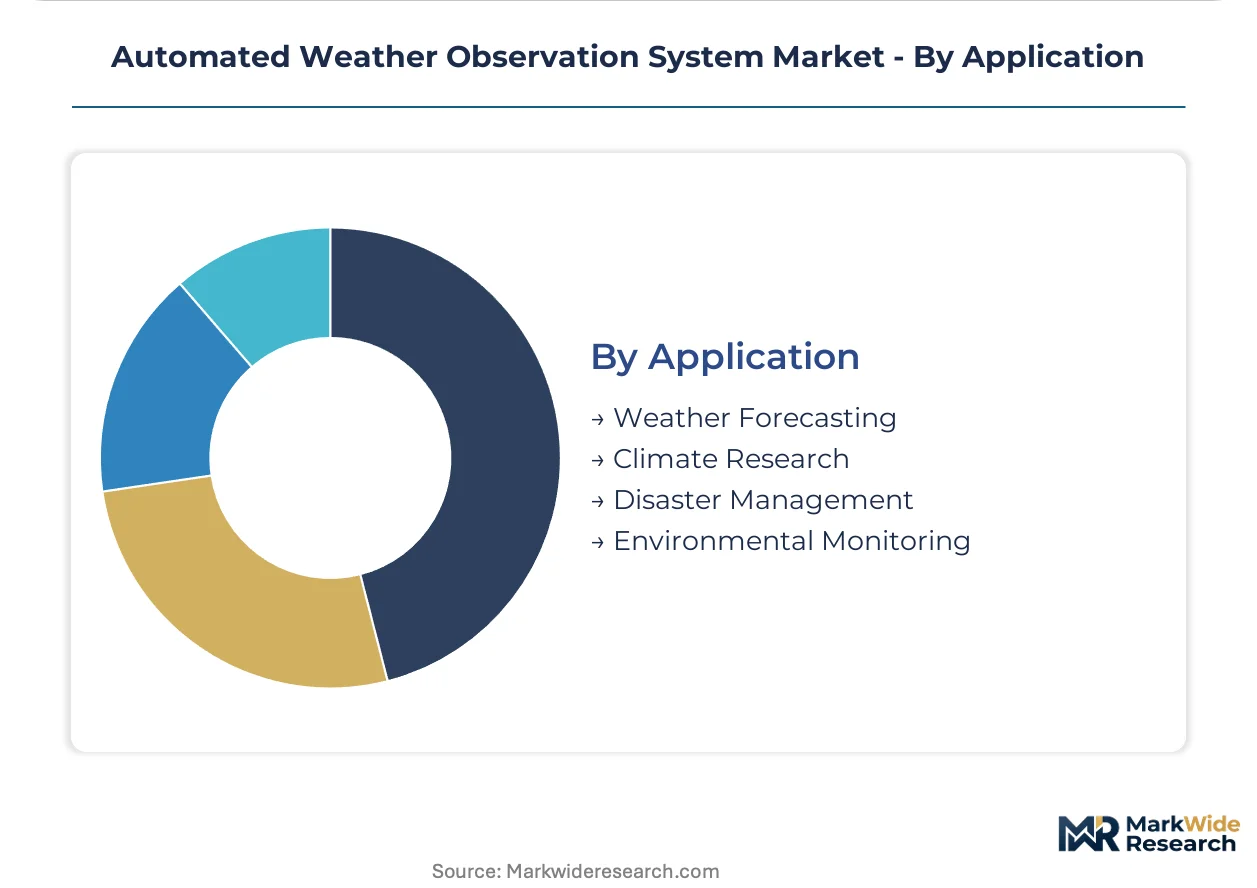
Application:
Performance specifications and reporting intervals diverge by use case, with aviation safety applications demanding sub-minute latency while climate research tolerates hourly aggregation.
- Weather Forecasting:Numerical weather prediction initialization requires dense surface observation networks with WMO-compliant data formats and quality-controlled telemetry. National meteorological services in Germany and the United Kingdom drive standardization, with third-party calibration laboratory accreditation liberalizing maintenance procurement.
- Disaster Management:Flash flood and wildfire response teams deploy rapid-installation networks for event monitoring and evacuation timing.
- Climate Research:Long-term trend detection demands traceable calibration continuity across decadal instrument generations.
- Environmental Monitoring:Industrial compliance and urban heat island studies utilize lower-cost configurations with relaxed accuracy tolerances.
Weather forecasting handles the majority of throughput; disaster management is the fastest mover on share as climate volatility intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA's NextGen weather infrastructure underwrites United States demand for automated runway visibility systems, while hub airports in Germany and China retrofit legacy analog networks under parallel EASA and GB standards alignment.
United States
Hub airports in Atlanta, Chicago, and Dallas-Fort Worth drive replacement demand as legacy copper-wire telemetry systems reach end-of-life. FAA Advisory Circular 150/5220-16D mandates precision approach upgrades, compressing procurement timelines for certified sensor suites. Secondary airfields across the Mountain West adopt remote sensing configurations fastest under cost-reduction directives.
Germany
Frankfurt and Munich airports anchor procurement volumes for stationary systems with dual-path telemetry and platinum resistance thermometer arrays. EASA aerodrome design specifications enforce sensor redundancy requirements that fragment supplier qualification roadmaps from FAA protocols. The civil aviation authority's liberalization of third-party calibration laboratory accreditation unbundles maintenance from original equipment procurement.
China
Beijing Capital and Shanghai Pudong retrofit programs concentrate demand as CAAC aligns domestic standards with international sensor performance benchmarks. GB standards for meteorological equipment interoperability accelerate qualification pathways for certified foreign suppliers. Secondary hub construction in Chengdu and Xi'an expands addressable market for fully automated networks.
India
UDAN scheme subsidies and DGFT duty exemptions on meteorological equipment create entry points at underserved regional airfields. The Directorate General of Civil Aviation's modernization push targets 50-plus airports for automated weather system installation. Procurement concentrates in Maharashtra and Karnataka where aviation infrastructure expansion outpaces legacy human observer capacity.
United Kingdom
Heathrow and Gatwick replacement cycles drive demand for lidar ceilometer networks that displace manual observation protocols. The Civil Aviation Authority's technical service provider accreditation liberalization enables standalone calibration contracts with regional integrators. Scottish and Northern Irish regional airports adopt remote sensing configurations under EASA cost-reduction harmonization.
Automated Weather Observation System Market Vendor Landscape
Concentration sits with vertically integrated sensor manufacturers and specialized field instrumentation suppliers. The vendor base stratifies across three tiers: multinational conglomerates with captive calibration services, mid-cap specialists in ruggedized hardware, and regional integrators capturing unbundled maintenance contracts. Dominant competitive moves include backward integration into laser diode and photodiode receiver supply, plus geographic expansion through EASA-FAA dual-certification programs to reduce multinational product launch delays.
Among Finnish and US-based instrumentation specialists, Vaisala Oyj and Campbell Scientific, Inc. exemplify the vertically integrated archetype with in-house sensor manufacturing and traceable calibration capabilities. Coastal Environmental Systems occupies a position within the hardened-system tier, representing suppliers concentrated on military and maritime aviation procurement channels with distinct technical specifications from civil aviation authorities.
| Leading Market Players |
|---|
| Vaisala Oyj |
| All Weather, Inc. |
| Campbell Scientific, Inc. |
| Coastal Environmental Systems |
| Optical Scientific Inc. |
| AJY Engineering, Inc. |
| Columbia Weather Systems Inc. |
| OTT HydroMet |
| Gill Instruments Limited |
| Others |
Supply Flow & Price Mechanics
FAA Advisory Circular 150/5220-16D certification requirements gate both supplier qualification and price differentiation simultaneously, with only certified integrators commanding premium positioning while uncertified competitors compete on project cost alone. Platinum resistance thermometer arrays and eye-safe laser diode modules constitute the primary cost drivers, with buyers facing steep premiums for dual-path telemetry redundancy at major hub airports.
Pricing Analysis
Volume-discount tiering separates full AWOS suite deployments from single-sensor replacements, with hub airports capturing 15-20% unit economics advantages over regional airfields. Price differentiation hinges on EASA-FAA dual-certification status and bundled calibration service contracts, with certified integrators extracting margin premiums while standalone hardware vendors face cost compression from unbundled maintenance procurement in Germany and the United Kingdom. Regional airlines and general aviation airports exhibit highest price sensitivity, whereas civil aviation authorities under statutory safety mandates demonstrate lowest sensitivity to unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for German and Japanese-sourced photodiode receivers and avalanche photodiode arrays. Component manufacturing concentrates in Germany, Japan, and the United States, with eye-safe laser diode arrays and platinum resistance thermometers drawing from specialized foundry capacity. Single-source vulnerability in 1550nm laser diode supply creates structural risk for lidar ceilometer integrators. Distribution runs through original equipment manufacturers with captive calibration services, though third-party laboratory accreditation in Europe is fragmenting aftermarket service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automated Weather Observation System market is experiencing high-growth disruption as lidar ceilometer networks displace human observers under EASA cost-reduction directives, compressing procurement timelines and reshaping competitive economics.
For Market Incumbents: Shield installed base relationships by embedding proprietary calibration protocols into long-term service contracts before third-party laboratory accreditation fully liberalizes European maintenance markets. Deepen backward integration into photodiode receiver supply to mitigate single-source exposure from Japanese component houses, while accelerating EASA-FAA dual-certification programs to reduce multinational product launch delays.
For New Entrants and Emerging Players: Differentiate on rapid-deployment portable configurations for military contingency operations and offshore helicopter platforms, where hardened system architectures command distinct procurement budgets from civil aviation authorities. Target India's UDAN-subsidized regional airfields with cost-optimized stationary systems, leveraging DGFT duty exemptions to undercut established supplier pricing.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across remote sensing system manufacturing as lidar component qualification timelines extend under harmonizing FAA-EASA protocols. Acquisition targets should exhibit captive calibration capabilities and existing dual-certification status, with the signal to watch being divergence or convergence in ice detection sensor standards between regulatory bodies.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Program | EASA-FAA alignment accelerates multinational deployment and reduces qualification duplication costs. |
| Backward Integration | In-house photodiode receiver production mitigates supply concentration risk in German and Japanese component houses. |
| Calibration Service Unbundling | Standalone laboratory contracts capture recurring revenue streams as European authorities liberalize technical service accreditation. |
| Portable System Development | Battery-backed rapid-deployment units penetrate military and maritime aviation procurement channels with distinct specifications. |
| Regional Airport Targeting | India's UDAN subsidies and DGFT exemptions create entry points at underserved airfields with compressed competition. |
Methodological Framework
Desk research of regulatory filing databases, customs trade records, and aerodrome design specifications preceded structured interviews with airport operations directors, civil aviation authority certification engineers, meteorological equipment procurement managers, and third-party calibration laboratory technical leads. Primary intelligence was cross-validated against FAA Advisory Circular documentation, EASA aerodrome design specifications, and CAAC GB standards publications. Bottom-up sensor shipment estimates and top-down aviation infrastructure budget allocations were triangulated to reconcile volume and value figures.
Variance decomposition across product type, end user, technology, and application segments shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion, with inputs including regulatory compliance deadline schedules, airport modernization program announcements, and platinum group metals price trajectory assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained FAA NextGen implementation and EASA-EU F-Gas Regulation enforcement; material deviation in certification harmonization timelines or precious metals supply would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Digital Olfaction Products Market
Sensors
Global Smart Leak Detection Solutions Market
Sensors
Heat Stress Meter Market
Sensors
Conveyor Monitoring Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
Vibration Monitoring Market
Sensors
Wireless Synchronized Clocks Market
Sensors
2D Barcode Reader Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Lidar in Mapping Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Residential Water Leak Detection System Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Fixed RFID Readers Market
Sensors
APAC Wireless Sensors Market
Sensors
Global RFID Market