
 Voice Sounders Market | 2026-2036
Voice Sounders Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Sounders Market Analytics
The fire safety distribution channel is narrowing as specification consultants and system integrators consolidate procurement authority across multi-site industrial contracts. Honeywell International Inc. leverages its captive fire alarm portfolio to bundle voice sounders with detection systems, while Siemens AG anchors European specification through its Cerberus Pro platform integration. Johnson Controls International Plc competes by extending its Metasys building automation reach into mass notification specifications.
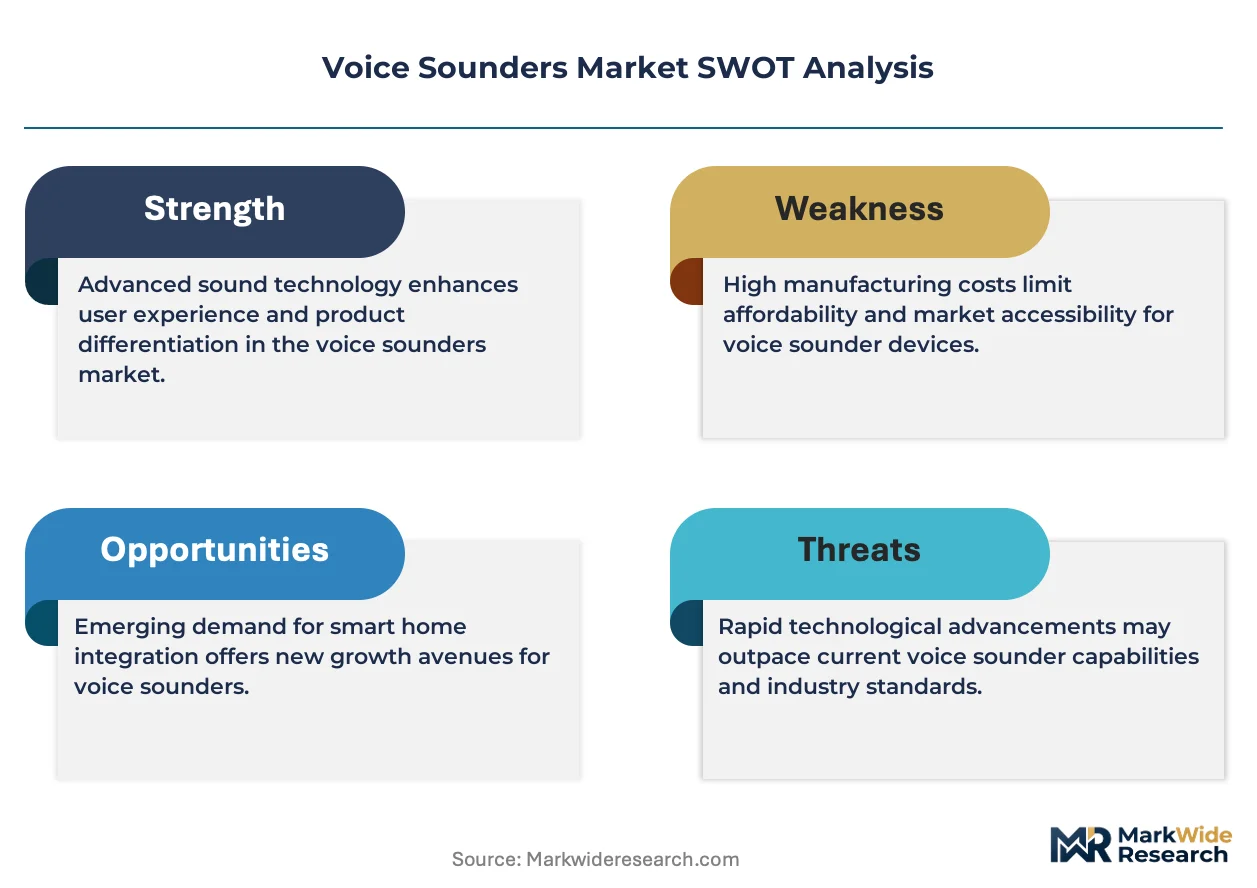
Voice sounders are electroacoustic warning devices that convert electrical signals into intelligible spoken announcements or tone patterns, typically operating between 75 dB and 120 dB sound pressure level depending on ambient noise conditions and enclosure rating. These devices serve critical life safety and operational notification functions where visual alarms prove insufficient due to high-occupancy density, hearing-impaired accessibility requirements, or environments with obstructed sightlines. The connected product segment captures expanding margin pools as IoT-enabled devices allow remote self-testing and fault reporting that reduces maintenance labor costs. Industrial notifications applications lead volume demand, though marine safety specifications are tightening as SOLAS amendments push for louder, more directional voice projection in engine rooms and cargo holds. Wall-mounted installations dominate retrofit activity, while ceiling-mounted configurations gain share in new commercial construction where aesthetic integration matters.
The National Fire Protection Association's NFPA 72 standard governs voice intelligibility requirements across North American installations, forcing manufacturers to invest in STI-PA testing certification. Europe's Construction Products Regulation and ECHA restrictions on hazardous substances in electronics reshape material selection for housings and circuit assemblies. Stakeholders must monitor evolving cyber-resilience mandates for connected notification systems, as network-hardened voice sounders become prerequisite for critical infrastructure contracts.
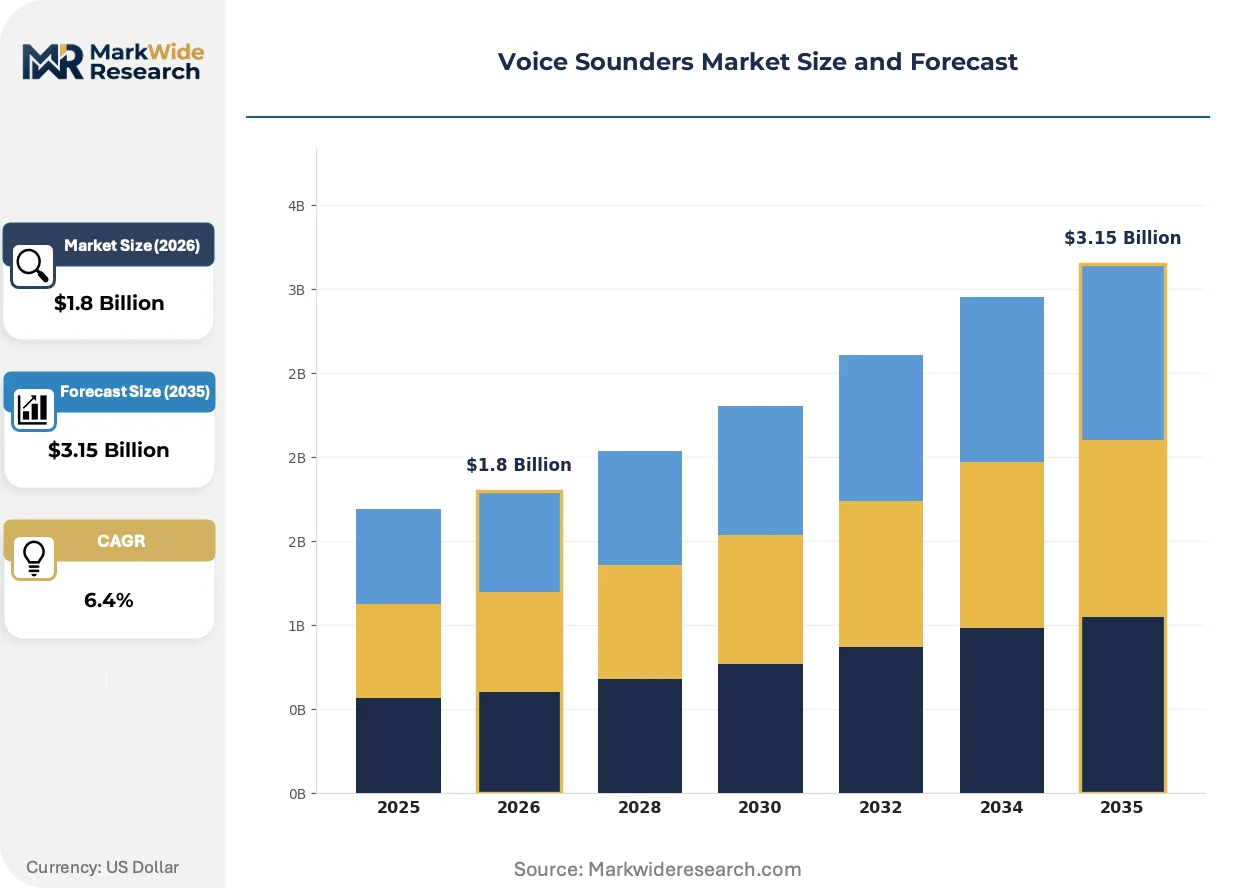
Market Dynamics
The Voice Sounders Market faces structural pressure from IEC 60268 audio standard updates in Europe and NFPA 72 intelligibility mandates in the United States, forcing manufacturers to retest legacy portfolios and recertify production lines ahead of compliance deadlines.
Growth Catalysts
- Factory automation intensity:Germany's industrial corridor drives specification of IP-rated voice sounders for hazardous manufacturing environments where audible warnings must penetrate high ambient noise.
- SOLAS maritime amendments:International Maritime Organization mandates for louder, more directional voice projection in engine rooms and cargo holds tighten marine safety specifications and expand replacement cycles.
- IoT-enabled remote diagnostics:Connected notification devices allow self-testing and fault reporting that reduces maintenance labor costs in multi-site industrial contracts.
Market Restraints
- STI-PA certification costs:Speech Transmission Index for Public Address testing requirements under NFPA 72 impose capital-intensive laboratory investments that constrain mid-tier manufacturers.
- ECHA substance restrictions:European Chemicals Agency limits on hazardous substances in electronics force housing and circuit assembly material substitutions that extend R&D timelines.
- Acoustic engineering talent scarcity:Specialized expertise in directional sound projection and intelligibility optimization concentrates in Germany, the United Kingdom, and Massachusetts, creating recruitment bottlenecks.
Strategic Opportunities
- Critical infrastructure cyber-resilience:Network-hardened voice sounders are becoming prerequisite for power generation and water treatment contracts as operators harden notification systems against intrusion.
- Ceiling-mounted aesthetic integration:New commercial construction in urban centers favors flush-mount configurations that displace traditional wall-mounted retrofit installations.
- Building automation convergence:Integration with BACnet and Modbus protocols allows voice sounders to function as nodes in unified facility management platforms rather than standalone safety devices.
Industry Challenges
- Legacy system protocol fragmentation:Proprietary communication standards from incumbent fire alarm manufacturers complicate third-party voice sounder integration and extend commissioning timelines.
- Multi-standard compliance overlap:Simultaneous adherence to NFPA 72, IEC 60268, and marine-specific regulations requires parallel certification tracks that strain quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Sounders Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Integrated, Connected, Remote Application: Security Systems, Alarm Notification, Marine Safety, Industrial Notifications End User: Manufacturing, Education, Transportation, Healthcare Installation Type: Wall-Mounted, Ceiling-Mounted, Portable, Built-in |
| Companies Covered | Honeywell International Inc., Johnson Controls International Plc, Siemens AG, Robert Bosch GmbH, ABB Ltd., TOA Corp., Eaton Corp plc, Hochiki America Corp., Mircom Group of Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Sounders Market Evolving Landscape
Digital signal processing architectures are displacing analog circuitry as the dominant platform for voice sounder design, compressing hardware footprints while expanding software-configurable functionality. This shift redefines competitive advantage around firmware capabilities rather than electroacoustic component sourcing.
Beam-steering array technology is digitizing directional sound projection by enabling electronically adjustable coverage patterns without mechanical aiming. Oil and gas facilities in the North Sea and Gulf of Mexico are adopting these systems to address reflective surfaces and high ambient noise. The technology is compressing installation labor costs by eliminating trial-and-error positioning during commissioning.
Europe's Construction Products Regulation and ECHA RoHS restrictions are tightening substance disclosure requirements for housings and circuit assemblies. Manufacturers must document material composition through supply chains or risk market withdrawal. German industrial buyers are now requiring full material declarations as standard procurement terms, displacing spot-check compliance approaches.
Specification authority is consolidating among multi-site industrial operators who negotiate framework agreements directly with voice sounder manufacturers. System integrators and fire safety distributors are losing procurement influence as buyers centralize technical standards across facility portfolios. This concentration is most visible in automotive manufacturing chains spanning Stuttgart, Wolfsburg, and Detroit.
Voice Sounders Market Segmentation
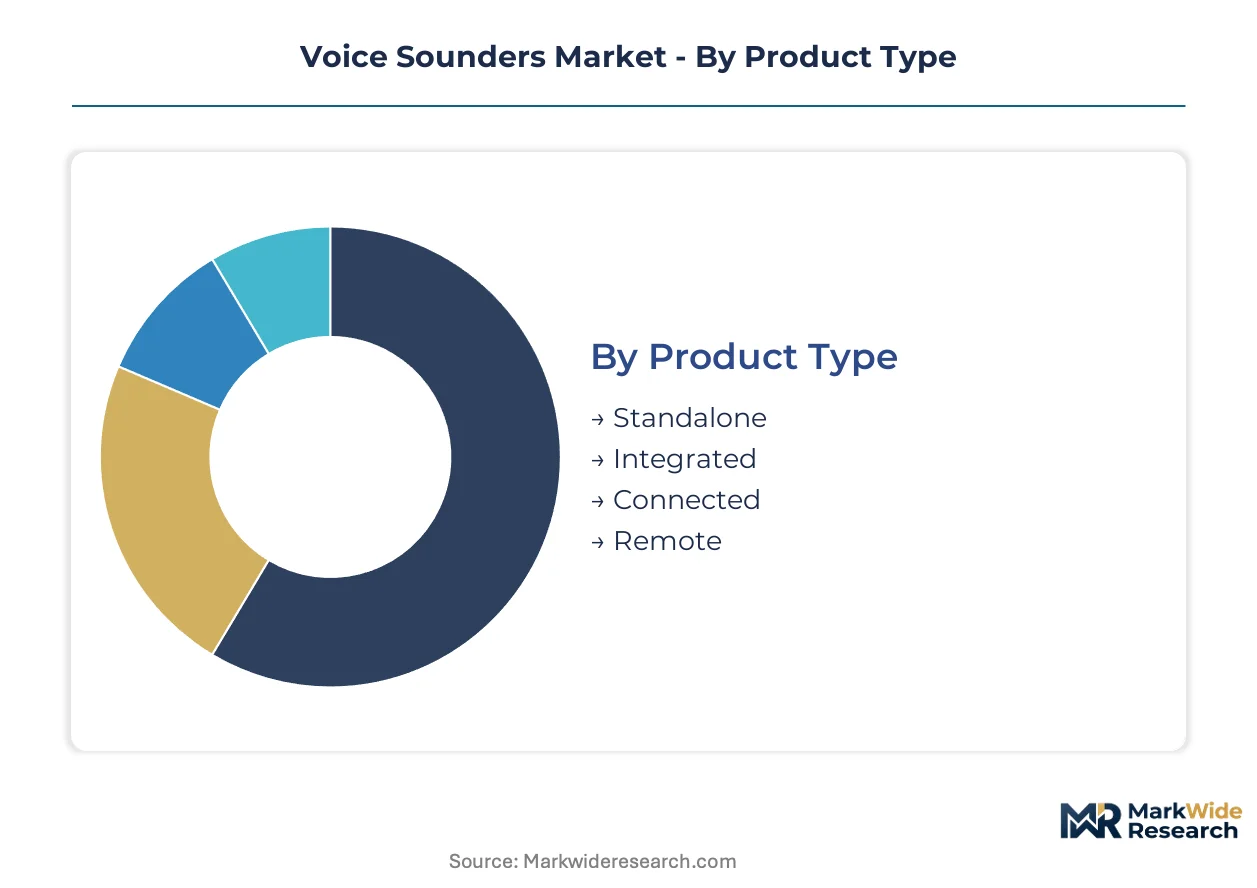
Voice sounder procurement patterns diverge sharply across installation contexts and connectivity requirements. Manufacturers configure product portfolios around four distinct axes—hardware form factor, deployment environment, buyer vertical, and mounting topology—each carrying different margin profiles and certification burdens.
Product Type:
Cost tier differentiation separates legacy hardware from software-enabled platforms that command premium positioning through remote diagnostics.
- Standalone:Self-contained units with onboard amplification and stored message libraries require no external control infrastructure. Demand concentrates in retrofit installations across Germany's manufacturing belt where legacy fire panels lack addressable loops, constrained by NFPA 72 intelligibility testing costs that favor established suppliers.
- Connected:IoT-enabled devices with Ethernet or wireless backhaul support centralized self-testing and fault reporting. These configurations are expanding most quickly in multi-site industrial contracts across the United States, driven by OSHA maintenance recordkeeping requirements and labor cost reduction mandates.
- Integrated:Modules designed for embedding within third-party fire alarm or building automation panels. Automotive manufacturing chains in Stuttgart and Wolfsburg specify these for aesthetic consolidation with detection hardware.
- Remote:Satellite units dependent on centralized amplification and signal processing. Marine safety applications in the North Sea favor these for weight reduction in offshore platform installations.
Standalone holds installed capacity. Connected is rotating up the share rankings.
Application:
Functional deployment context determines acoustic specification intensity and regulatory compliance layering.
- Industrial Notifications:High-decibel, directional projection systems engineered for ambient noise penetration in manufacturing environments. Germany's industrial corridor drives specification of IP66-rated enclosures with STI-PA certification, particularly in chemical processing facilities where ECHA substance restrictions constrain housing material selection.
- Marine Safety:Corrosion-resistant voice projection systems for engine rooms and cargo holds. SOLAS amendments mandate louder, more directional output, tightening replacement cycles in Gulf of Mexico offshore installations and North Sea supply vessels.
- Security Systems:Integration with access control and intrusion detection for synchronized audio-visual deterrence. Transportation hubs in the United Kingdom deploy these for crowd management.
- Alarm Notification:Fire and emergency evacuation systems governed by NFPA 72 intelligibility standards. Healthcare facilities in Massachusetts face Joint Commission scrutiny on speech clarity metrics.
Industrial Notifications anchors volume demand. Marine Safety is climbing the fastest on regulatory replacement pull.
End User:
Customer type dictates procurement centralization, technical specification authority, and framework agreement structures.
- Manufacturing:Multi-site operators with consolidated technical standards across facility portfolios. Automotive chains spanning Detroit, Stuttgart, and Wolfsburg negotiate direct manufacturer agreements, displacing distributor influence.
- Transportation:Airports, rail terminals, and maritime operators requiring synchronized mass notification. TSA and Coast Guard directives in the United States harden cyber-resilience requirements for connected systems.
- Healthcare:Hospitals and aged-care facilities with hearing-impaired accessibility mandates. Joint Commission audits in Massachusetts and California enforce NFPA 72 intelligibility compliance.
- Education:K-12 and university campuses with lockdown notification requirements. District-level procurement in Texas and Florida favors ceiling-mounted aesthetic integration in new construction.
Manufacturing concentrates procurement authority. Transportation is gaining share fastest on infrastructure security spending.
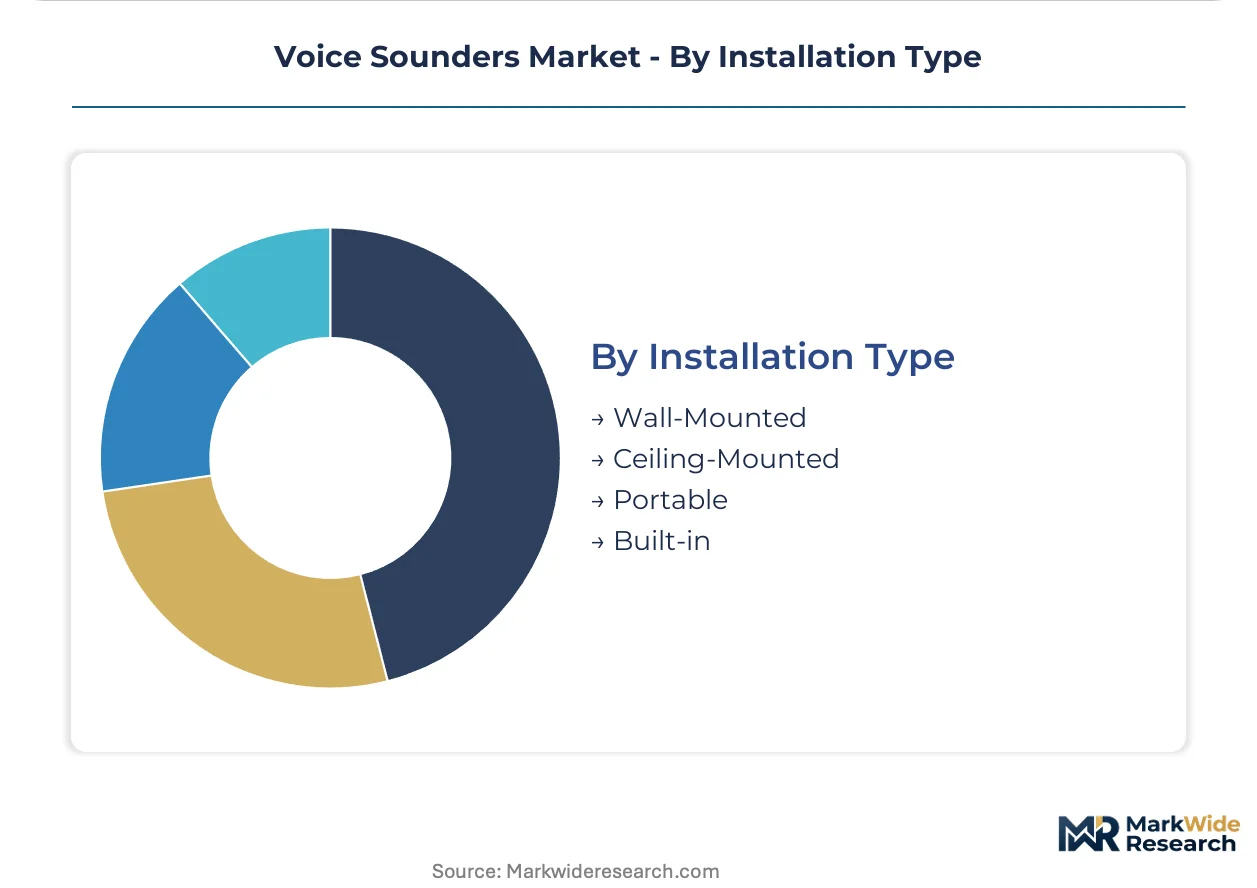
Installation Type:
Mounting topology determines aesthetic integration potential and labor cost structures across new construction versus retrofit.
- Wall-Mounted:Surface or recessed enclosures dominating retrofit activity in existing industrial facilities. Germany's manufacturing belt shows persistent preference for these in hazardous environment deployments where ceiling access is constrained.
- Ceiling-Mounted:Flush-mount configurations gaining share in new commercial construction across urban United States centers. Architects in Boston and San Francisco specify these for aesthetic integration with lighting and HVAC systems.
- Portable:Battery-powered or temporary power units for construction sites and emergency response. Oil and gas facilities in the Gulf of Mexico deploy these during turnaround maintenance.
- Built-in:Custom-integrated solutions for OEM equipment manufacturers. Marine vessel builders in Norway embed these in bridge and engine room consoles.
Wall-Mounted retains retrofit dominance. Ceiling-Mounted is expanding most quickly on new construction share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling systems anchor European demand for intelligible emergency notification in high-noise logistics environments. Germany's industrial corridor connects to this hub through Rhine freight networks, while North American port automation at Long Beach and Newark drives parallel specification cycles.
United States
OSHA maintenance recordkeeping requirements drive IoT-enabled voice sounder adoption across multi-site manufacturing contracts. NFPA 72 intelligibility mandates force STI-PA certification investments that favor established suppliers. Massachusetts healthcare clusters face Joint Commission scrutiny on speech clarity metrics in Boston-area hospital expansions.
Germany
Factory automation intensity in Stuttgart and Wolfsburg automotive chains concentrates procurement authority for IP-rated hazardous environment devices. ECHA substance restrictions on housing materials reshape supplier qualification criteria. The Ruhr industrial belt specifies ceiling-mounted configurations for new commercial construction in Düsseldorf and Cologne.
United Kingdom
Transportation hub security spending at Heathrow and Crossrail terminals accelerates mass notification system upgrades. The Construction Products Regulation tightens material disclosure requirements for electronics. Scottish North Sea oil platforms adopt beam-steering arrays for directional voice projection in reflective engine room environments.
Japan
METI industrial safety directives push voice intelligibility standards in precision manufacturing facilities around Nagoya and Osaka. JIS certification requirements create barriers for non-domestic suppliers in building automation integration. Tokyo's dense commercial construction favors flush-mount aesthetic configurations over surface-mounted retrofit units.
China
GB standards for fire alarm systems are tightening intelligibility requirements in high-occupancy infrastructure across the Yangtze River Delta. MIIT cybersecurity mandates for connected devices reshape firmware architecture in notification systems. Shenzhen's electronics manufacturing clusters supply DSP components for beam-steering array production.
Voice Sounders Market Competitive Landscape
On the supply side, the industry is consolidating around bundled fire safety platforms that integrate detection, control, and notification functions. Specification authority has shifted toward multi-site industrial operators who negotiate framework agreements directly with manufacturers, compressing distributor margins. Two strategic archetypes dominate: diversified conglomerates leveraging captive building automation portfolios, and specialized electroacoustic engineers focused on STI-PA certification excellence. Competitive moves center on BACnet and Modbus protocol convergence for unified facility management integration, plus cyber-resilience hardening for critical infrastructure contracts.
Among diversified conglomerates, Honeywell International Inc., Johnson Controls International Plc, and Siemens AG exemplify the platform-integration archetype. These entities anchor competitive positioning through building automation ecosystem control rather than standalone notification hardware. Honeywell's captive fire alarm portfolio enables bundled specification, while Siemens leverages Cerberus Pro platform integration across European industrial corridors. Johnson Controls extends Metasys automation reach into mass notification specifications, representing the convergence strategy that displaces point-product vendors in multi-site contracts.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Johnson Controls International Plc |
| Siemens AG |
| Robert Bosch GmbH |
| ABB Ltd. |
| TOA Corp. |
| Eaton Corp plc |
| Hochiki America Corp. |
| Mircom Group of Co. |
| Others |
Value Network & Pricing Analysis
Shenzhen's DSP component manufacturing clusters anchor global beam-steering array production, concentrating amplification module supply and compressing input costs for voice sounder assemblers in Germany and the United States. This geographic concentration grants Chinese substrate suppliers outsized leverage over mid-tier manufacturers facing NFPA 72 recertification deadlines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by STI-PA certification status and IoT connectivity depth. Premium tiers command positioning through embedded cybersecurity hardening and BACnet protocol integration, while economy tiers compete on per-unit transactional pricing for standalone retrofit installations. Cost compression in the standard tier is intensifying because ECHA substance restrictions force housing material substitutions that extend R&D timelines. Manufacturing buyers negotiating multi-site framework agreements exhibit lowest price sensitivity; small facility retrofit operators show highest.
Supply Chain Analysis
Export-control restrictions on advanced digital signal processors limit component flows from United States fabs to Chinese assembly plants, creating supply friction for beam-steering array manufacturers. Voice sounder production draws from China for DSP substrates, Germany for precision acoustic transducers, and Japan for high-reliability capacitors. Single-source vulnerability concentrates in Shenzhen's substrate etching capacity. Distribution runs through specification consultants and system integrators who consolidate procurement authority across multi-site industrial contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Voice sounders sit in early-cycle expansion as factory automation intensity in Germany's industrial corridor accelerates specification of IP-rated hazardous environment devices. SOLAS maritime amendments and NFPA 72 intelligibility mandates create regulatory tailwinds that expand replacement cycles and tighten compliance windows.
For Market Incumbents:Entrench platform control by deepening Cerberus Pro and Metasys integration capabilities that bundle notification with building automation ecosystems. Invest in STI-PA testing laboratory capacity ahead of NFPA 72 enforcement waves to capture mid-tier manufacturers exiting the certification race. Vertical integration into DSP firmware development insulates against Shenzhen substrate supply friction.
For New Entrants and Emerging Players:Establish a beachhead in marine safety applications where SOLAS amendment-driven replacement cycles outpace incumbent response times. Target ceiling-mounted aesthetic integration segments in Boston and San Francisco new commercial construction where architect specification authority displaces distributor influence. Lead with cyber-resilience hardening as the go-to-market wedge for critical infrastructure water treatment and power generation contracts.
For Investors and Strategic Acquirers:Long-term, this sits as a regulatory-compliance compounder play because intelligibility mandates and substance restrictions continuously raise barriers to supply. Acquisition targets should show STI-PA certification excellence and embedded firmware capabilities rather than electroacoustic component sourcing relationships. Watch for IEC 60268 audio standard update finalization as the signal indicating which mid-tier manufacturers will exit versus consolidate.
| Strategic Initiative | Industry Significance |
|---|---|
| STI-PA Certification Investment | NFPA 72 intelligibility mandates force laboratory capital deployment that eliminates mid-tier competitors. |
| Beam-Steering Array Launch | Oil and gas facilities in the North Sea adopt electronically adjustable coverage for reflective engine room environments. |
| BACnet Protocol Integration | Unified facility management platforms displace standalone safety devices in automotive manufacturing chains. |
| Cyber-Resilience Hardening | TSA and Coast Guard directives make network-hardened voice sounders prerequisite for transportation infrastructure contracts. |
| Ceiling-Mounted Aesthetic Expansion | Flush-mount configurations capture architect-specified share in Boston and San Francisco new commercial construction. |
Research Methodology
Desk research of IEC 60268 standard documentation, NFPA 72 code revision filings, and SOLAS amendment records preceded structured interviews with fire safety specification consultants, industrial facility maintenance directors, marine classification society surveyors, and building automation system integrators. Secondary validation drew from SEC 10-K filings of diversified conglomerates, ECHA substance restriction databases, and customs records of electroacoustic component trade flows. Bottom-up voice sounder shipment estimates triangulated against top-down industrial notification equipment market sizing.
Assumptions held fixed across the modeling period include continued factory automation intensity in Germany's automotive corridor and progressive tightening of NFPA 72 intelligibility enforcement in Massachusetts healthcare clusters. Variables allowed to fluctuate encompass SOLAS amendment implementation timelines and ECHA substance restriction scope expansion. Segmentation dimensions modeled include product connectivity tier, application context, end-user vertical procurement centralization, and mounting topology preference. CAGRs derived from installed base replacement cycles and new construction penetration rates, with beam-steering array adoption curves and cyber-resilience mandate compliance timelines as industry-specific inputs.
Stress conditions across marine safety specification timelines, ECHA substance restriction enforcement intensity, and DSP substrate supply availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory implementation pacing and industrial capital expenditure continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Lidar in Construction Market
Sensors
Asset Tracking Market
Sensors
Body Area Network Market
Sensors
Industrial Automation Sensors Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Heat Stress Meter Market
Sensors
Sensor Landscape in Robotics and ADAS Vehicle Market
Sensors
Eye Tracking Solutions Market
Sensors
Digital Olfaction Products Market
Sensors
Safety Motion Control System Market
Sensors
Industrial Barcode Scanners Market
Sensors
India Asset Tracking Market
Sensors
Alcohol Sensor Market
Sensors
Cloud Camera Market
Sensors
Yield Monitoring Systems Market
Sensors
Smart Pest Monitoring Management System Market