
 AR & VR in Aviation Market | 2026-2036
AR & VR in Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
AR & VR in Aviation Market Insights
Project finance for full-flight simulator fleets is reconfiguring competitive entry barriers, allowing smaller flight schools to lease cloud-based VR modules rather than purchase multi-million dollar hardware. CAE Inc. leverages its installed base of physical simulators to anchor hybrid deployment models, while Microsoft Corporation competes through Azure-hosted streaming infrastructure for low-latency headset delivery. Elbit Systems Ltd. dominates military aviation applications with ruggedized AR helmet systems purpose-built for fighter pilot training.
AR and VR in aviation encompass head-mounted displays, spatial computing software, and motion-capture environments that overlay digital information onto physical cockpits or generate fully synthetic flight scenarios with six-degrees-of-freedom tracking. These systems replicate instrument panels, weather conditions, and emergency procedures without fuel burn or airspace clearance, serving airlines, manufacturers, and defense operators seeking repeatable, measurable training outcomes. Pilot Training applications lead current revenue as carriers face accelerated captain upgrade pipelines, while Maintenance Support segments show the fastest expansion as AR-guided line checks reduce aircraft-on-ground intervals. Cloud-Based Systems deployment is displacing on-premises installations among regional carriers seeking subscription-based scaling.
FAA Part 60 standards and EASA CS-FSTD regulations govern simulator qualification levels, directly determining which VR platforms gain credit toward type-rating certification and thus shaping procurement budgets at flight schools. The EU AI Act and emerging MEE guidelines in China add compliance layers for adaptive training algorithms that adjust difficulty based on biometric feedback. Stakeholders must monitor whether regulators extend full credit to standalone VR devices or preserve hardware-centric qualification paths that favor incumbent simulator manufacturers.
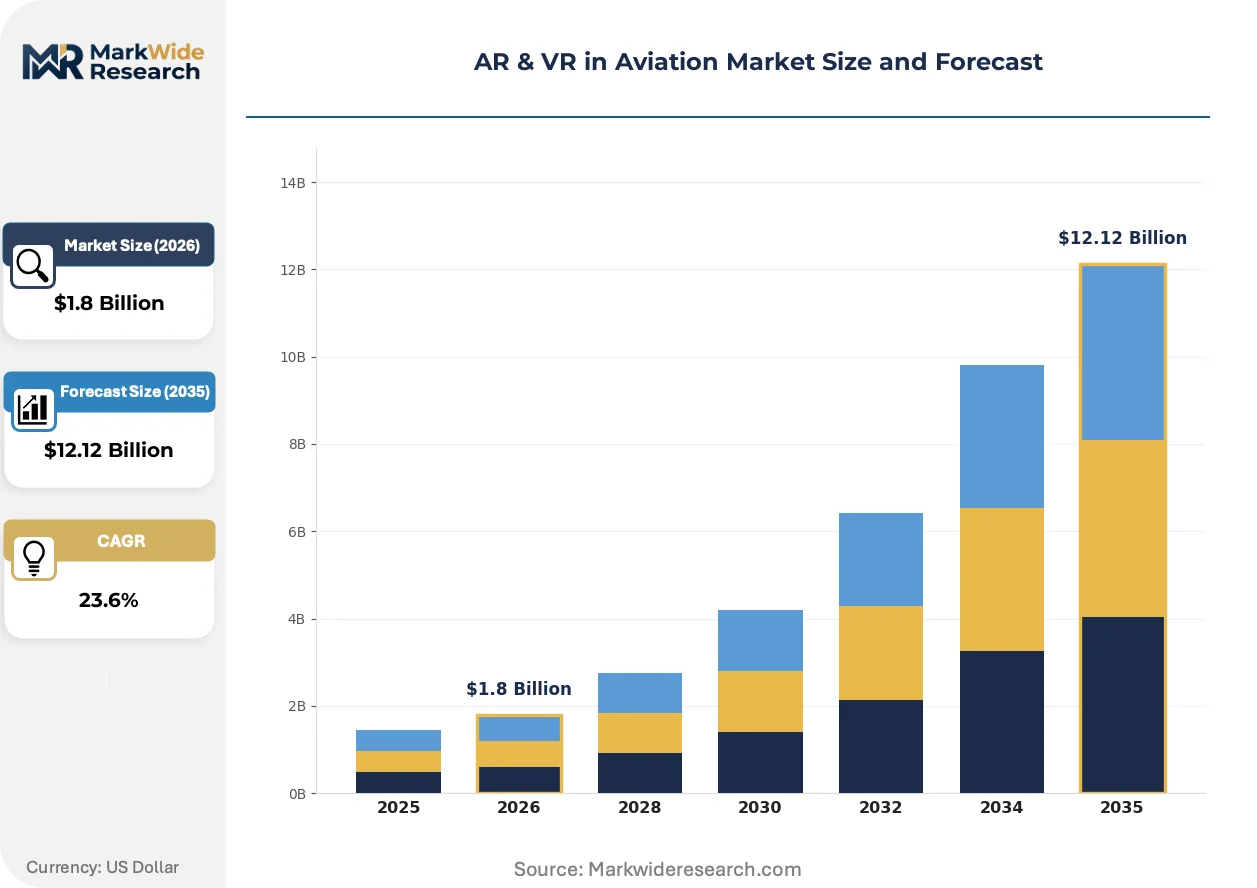
Market Dynamics
Cloud-based VR streaming infrastructure is fragmenting the historical simulator duopoly, enabling regional flight schools to access FAA-creditable training modules without capital-intensive hardware procurement. This shift compresses entry barriers while forcing incumbent OEMs to defend installed bases through hybrid physical-digital service bundles.
Growth Catalysts
- EASA CS-FSTD pathway expansion:The European regulator's evolving stance on virtual reality device qualification is unlocking procurement budgets at Eastern European flight schools previously excluded from synthetic training credit.
- Airline maintenance outsourcing:Third-party MRO providers in the United States are deploying AR-guided line inspections to compress aircraft-on-ground intervals and win carrier contracts.
- Biometric-adaptive algorithms:Machine learning systems that adjust simulator difficulty based on pilot heart-rate variability and eye-tracking data are improving training throughput metrics.
Market Restraints
- Optical waveguide supply concentration:Military-grade transparent display substrates depend on a limited supplier base in Japan and Germany, creating input cost volatility for AR helmet manufacturers.
- FAA Part 60 hardware bias:Current qualification standards preserve credit pathways favoring motion-platform simulators, structurally disadvantaging standalone VR device vendors.
- Latency tolerance thresholds:Real-time multiplayer training scenarios demand sub-20-millisecond motion-to-photon latency, a technical limitation constraining cloud-streamed deployment at scale.
Strategic Opportunities
- India's civil aviation expansion:The country's projected fleet growth and DGCA regulatory modernization create white space for VR-based type-rating programs at emerging training organizations.
- Convergence of haptics and spatial audio:Integration of force-feedback gloves with three-dimensional sound fields enables emergency procedure rehearsal without physical cockpit mockups.
- Subscription-based fleet access:Pay-per-hour cloud simulator models allow regional carriers to match training capacity to seasonal hiring cycles without fixed asset ownership.
Industry Challenges
- Certification timeline compression:New entrant VR platforms face multi-year FAA and EASA qualification processes that lag hardware development cycles, delaying revenue recognition.
- Legacy simulator integration friction:Hybrid deployments require data bridge architecture connecting 1990s-era host computers with modern game-engine renderers, complicating system validation.
- Instructional designer scarcity:The specialized skill set combining aviation domain expertise with immersive content authoring outpaces current training program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR & VR in Aviation Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.12 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Augmented Reality, Virtual Reality, Mixed Reality, Simulated Environment Application: Pilot Training, Maintenance Support, Cabin Crew Training, Cabin Design, Flight Simulation End User: Airlines, Aerospace Manufacturers, Flight Schools, Military Aviation, Ground Support Providers Deployment: On-Premises, Cloud-Based Systems, Hybrid Models, Mobile Platforms, Standalone Devices |
| Companies Covered | The Boeing Company, Airbus SE, CAE Inc., Honeywell International Inc., Microsoft Corporation, Sony Corporation, Google LLC, Elbit Systems Ltd., Bohemia Interactive Simulations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR & VR in Aviation Market Trends and Innovations
Immersive training architecture is pivoting from monolithic simulators toward modular, software-defined environments that decouple visual rendering from physical motion systems. This reconfiguration is compressing deployment timelines and redistributing value capture across the supply chain.
Varjo's mixed-reality headsets are hybridizing photorealistic passthrough video with synthetic instrument overlays, allowing pilots to train in physical cockpits while interacting with virtual weather and traffic scenarios. Major carriers in Germany and the United States are piloting these devices for recurrent training cycles. The technology is hybridizing the historical divide between full-flight simulators and fixed-base training devices, forcing qualification standard revisions.
China's MEE guidelines on adaptive training algorithms are mandating algorithmic transparency and bias auditing for systems that adjust scenario difficulty based on biometric feedback. This regulatory layer adds compliance cost but creates competitive differentiation for vendors with pre-certified explainable AI architectures. Military aviation procurement in the country is most affected, with state-owned training centers demanding documentation packages that civilian-focused exporters struggle to assemble.
Leasing consortia are emerging as the dominant channel for VR training infrastructure, with flight schools pooling subscription commitments to secure enterprise-grade service-level agreements. This model displaces the traditional capital purchase pathway that favored balance-sheet-heavy incumbent simulator lessors. The shift is most visible among regional carriers in the United States seeking to match training capacity to cyclical hiring without stranded asset risk.
AR & VR in Aviation Market Segmentation
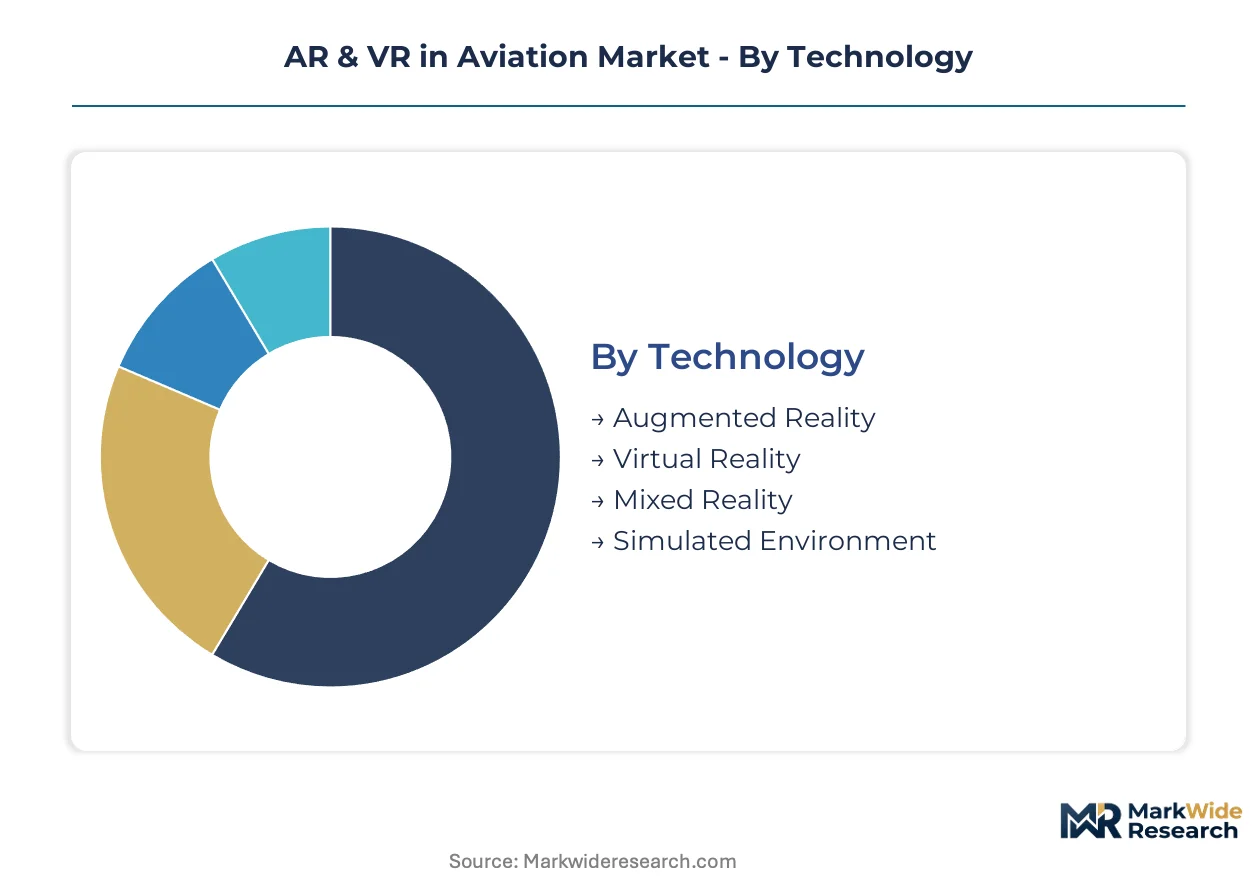
Segmentation in AR and VR aviation systems reveals how technology maturity, regulatory credit pathways, and capital intensity fragment procurement patterns across training, maintenance, and design functions. Each dimension carries distinct margin profiles and certification requirements that shape vendor positioning.
Technology:
Use-case spectrum spans from heads-up display overlays in active cockpits to fully synthetic environments for procedure rehearsal, with hardware specifications determining FAA and EASA qualification eligibility.
- Augmented Reality:Optical waveguide displays project flight parameters and maintenance schematics onto transparent lenses, with demand concentrating in military aviation for helmet-mounted cueing systems and line maintenance for hands-free inspection protocols. Fighter pilot training programs in the United States and Germany drive procurement volumes, constrained by waveguide substrate supply concentration in Japan and Germany.
- Virtual Reality:Fully immersive headsets with six-degrees-of-freedom tracking replicate instrument panels and emergency scenarios without physical mockups. Flight schools in the United States deploy these for instrument rating preparation, though FAA Part 60 hardware bias limits standalone VR credit toward type-rating certification.
- Mixed Reality:Photorealistic passthrough video blended with synthetic overlays enables training in physical cockpits with virtual weather and traffic. German carriers pilot these for recurrent training cycles.
- Simulated Environment:Large-scale dome projection systems with motion platforms serve full-flight simulator qualification levels. Legacy installed bases at major OEMs anchor this segment.
The dominant share belongs to Virtual Reality, while Mixed Reality is closing the gap fastest.
Application:
Cost tier stratification separates capital-intensive full-flight simulation from subscription-based modular training and per-inspection AR maintenance tools.
- Pilot Training:Synthetic flight hours toward type ratings and recurrent checks consume the largest procurement budgets, with accelerated captain upgrade pipelines at US and Chinese carriers compressing training timelines. Cloud-based streaming is fragmenting the historical simulator duopoly among regional flight schools.
- Maintenance Support:AR-guided line inspections reduce aircraft-on-ground intervals, with third-party MRO providers in the United States deploying these systems to win carrier contracts. This application expands most quickly as outsourcing deepens.
- Cabin Crew Training:VR emergency procedure rehearsal and customer service scenarios reduce live drill costs and scheduling complexity.
- Cabin Design:Spatial computing enables iterative interior configuration reviews without physical mockup construction, serving aerospace manufacturers in Germany and the United States.
- Flight Simulation:Engineering-grade aerodynamic modeling supports aircraft development programs, with demand tied to new platform introductions at major OEMs.
Pilot Training commands the largest revenue pool, though Maintenance Support is gaining share fastest.
End User:
Customer type determines procurement authority, with military programs favoring ruggedized hardware and commercial operators prioritizing operational expenditure flexibility.
- Airlines:Network carriers deploy hybrid physical-digital training to balance regulatory credit requirements with cost reduction, with seasonal hiring cycles driving interest in subscription-based fleet access.
- Aerospace Manufacturers:Engineering and test pilot training programs at major OEMs sustain demand for highest-fidelity simulation systems.
- Flight Schools:Regional training organizations in the United States and emerging markets adopt cloud-based VR modules to avoid multi-million dollar simulator capital commitments. Leasing consortia are displacing traditional purchase pathways.
- Military Aviation:State-owned training centers in China and defense procurement programs in the United States and Germany demand ruggedized AR helmet systems with algorithmic transparency documentation under MEE guidelines.
- Ground Support Providers:Third-party MRO operators deploy AR-guided inspections to compress turnaround times and secure airline contracts.
Airlines represent the largest addressable base, while Flight Schools are scaling fastest through cloud-based adoption.
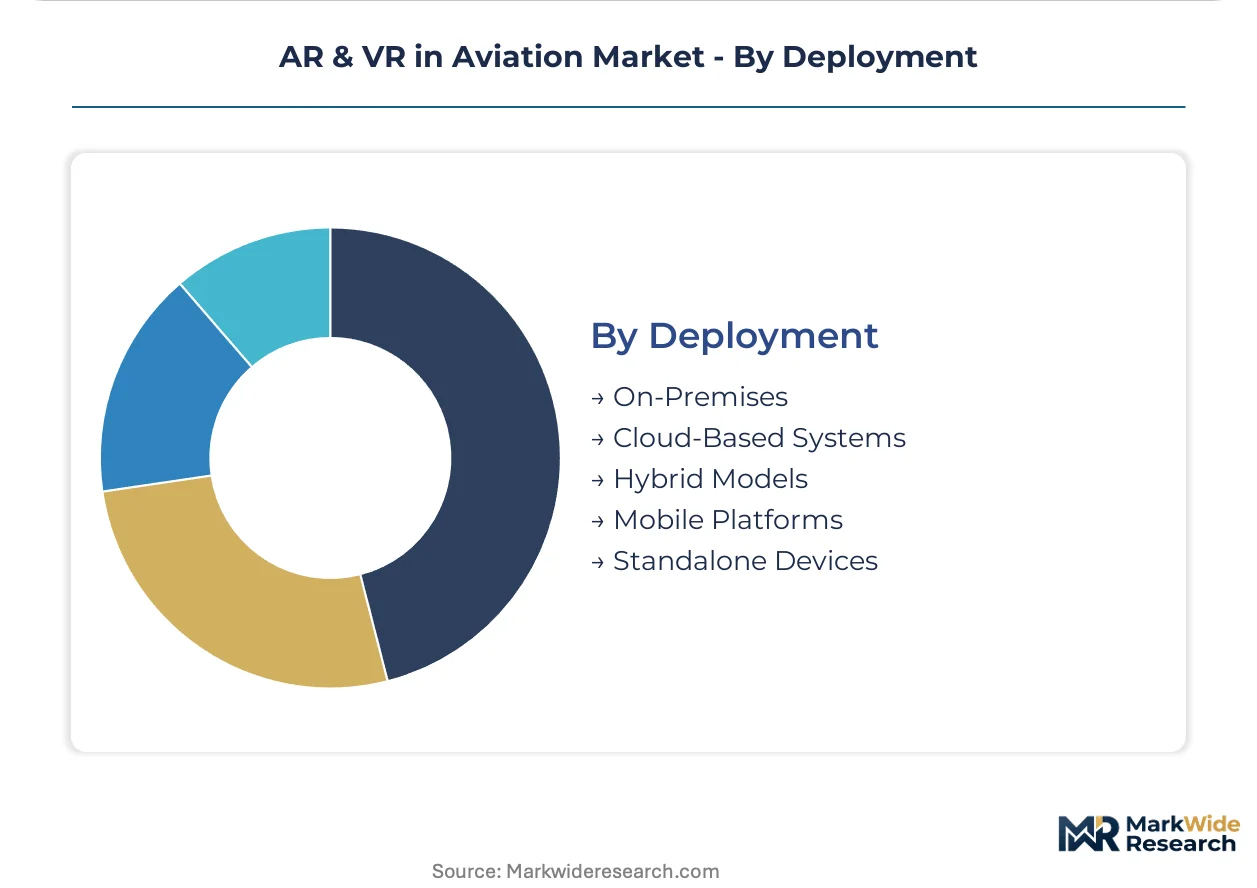
Deployment:
Supply concentration in streaming infrastructure and motion platform manufacturing shapes available deployment architectures.
- On-Premises:Traditional simulator installations with dedicated motion systems and visual domes remain necessary for highest qualification levels, anchored by incumbent OEM installed bases.
- Cloud-Based Systems:Azure-hosted streaming infrastructure enables low-latency headset delivery without local hardware procurement, with regional US carriers adopting subscription models to match capacity to hiring cycles. Latency tolerance thresholds below 20 milliseconds constrain multiplayer scenario scale.
- Hybrid Models:Physical cockpit shells with VR visual systems bridge regulatory credit requirements and cost reduction, requiring data bridge architecture between legacy host computers and modern renderers.
- Mobile Platforms:Tablet-based AR maintenance tools support line inspections without dedicated headset deployment.
- Standalone Devices:Untethered headsets enable flexible training location but face FAA and EASA qualification timeline compression that delays revenue recognition.
On-Premises retains the largest installed base, while Cloud-Based Systems are expanding most quickly among new entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airlines and defense procurement agencies in the United States, Germany, and China command the largest training technology budgets, with flight schools and MRO providers in these markets driving platform-specific demand for qualified synthetic training devices.
United States
Network carriers operate the world's largest commercial fleet and face compressed captain upgrade timelines that strain training capacity. FAA Part 60 standards govern simulator qualification levels and currently preserve credit pathways favoring motion-platform hardware over standalone VR systems. Dallas-Fort Worth and Atlanta anchor major airline training centers where hybrid physical-digital deployment models are displacing traditional capital purchase pathways.
Germany
Lufthansa Group and major aerospace OEMs sustain demand for highest-fidelity simulation systems tied to new aircraft platform introductions. EASA CS-FSTD regulations are evolving toward expanded virtual reality device qualification, unlocking procurement budgets at Eastern European flight schools previously excluded from synthetic training credit. Hamburg and Munich concentrate engineering-grade aerodynamic modeling capabilities serving development programs.
China
State-owned training centers and military aviation procurement programs drive demand for ruggedized AR helmet systems with algorithmic transparency documentation. MEE guidelines mandate bias auditing for adaptive training algorithms that adjust scenario difficulty based on biometric feedback. Beijing-Tianjin-Hebei and the Yangtze River Delta host the country's largest civil aviation training infrastructure expansion.
Japan
Optical waveguide substrate suppliers concentrate manufacturing capacity for military-grade transparent display components, creating input cost volatility that propagates through AR helmet supply chains. METI industrial policy supports domestic aerospace technology development while limiting foreign vendor penetration in defense applications. Nagoya's aerospace cluster integrates immersive training systems into manufacturing quality protocols.
India
DGCA regulatory modernization and projected fleet growth create white space for VR-based type-rating programs at emerging training organizations. The country's civil aviation expansion outpaces installed simulator capacity, forcing carriers to outsource pilot training to foreign facilities or adopt cloud-based modular alternatives. Mumbai and Delhi-NCR concentrate airline headquarters procurement authority for training technology decisions.
AR & VR in Aviation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority structures. Incumbent full-flight simulator manufacturers defend installed bases through hybrid service bundles, while cloud-streaming infrastructure providers compress regional flight school entry barriers. Three archetypes dominate: legacy motion-platform OEMs anchoring regulatory credit pathways, hyperscale cloud providers enabling subscription-based fleet access, and ruggedized defense specialists capturing military procurement programs. Competitive moves concentrate on strategic partnerships linking hardware qualification expertise with streaming infrastructure, plus portfolio diversification into biometric-adaptive training algorithms.
Among North American technology conglomerates, Microsoft Corporation occupies a position exemplifying cloud-native streaming infrastructure deployment, while CAE Inc. anchors the legacy simulator manufacturer archetype defending hybrid physical-digital service models. Elbit Systems Ltd. represents the defense-specialist tier with military-grade AR helmet system positioning. These three companies collectively illustrate the competitive tension between regulatory-credit-preserving incumbents and cloud-based challengers reshaping procurement economics at regional flight schools.
| Leading Market Players |
|---|
| The Boeing Company |
| Airbus SE |
| CAE Inc. |
| Honeywell International Inc. |
| Microsoft Corporation |
| Sony Corporation |
| Google LLC |
| Elbit Systems Ltd. |
| Bohemia Interactive Simulations |
| Others |
Pricing and Supply Chain Analysis
Optical waveguide substrate suppliers in Japan and Germany anchor upstream margin capture for AR helmet manufacturers, with downstream pricing power flowing toward flight schools and MRO operators able to substitute cloud-based VR modules for capital-intensive hardware procurement.
Pricing Analysis
Certification level under FAA Part 60 and EASA CS-FSTD creates the primary spread between motion-platform simulators and standalone VR devices, with three-tier pricing structure across qualified full-flight devices, hybrid physical-digital systems, and subscription-based cloud modules. Hardware-centric qualification pathways preserve premium pricing for incumbent OEMs while compressing margins for uncertified VR entrants. Cost compression in cloud-streamed tiers is intensifying because hyperscale infrastructure providers compete on latency guarantees. Regional flight schools exhibit highest price sensitivity due to capital constraints, whereas military aviation programs show lowest sensitivity given ruggedization requirements and algorithmic transparency documentation mandates.
Supply Chain Analysis
Extended payment terms from optical component suppliers in Japan and Germany are filtering through to AR headset manufacturers, with supply-chain finance facilities becoming critical for working capital management. Manufacturing concentrates in Japan for waveguide substrates, Germany for precision optics, and China for headset assembly and display panels. Critical inputs include rare-earth phosphors for transparent displays, lithium-niobate wafers for optical modulators, and high-refresh-rate OLED microdisplays. Single-source vulnerability in military-grade waveguide supply creates procurement risk for defense contractors. Distribution runs through leasing consortia and direct OEM sales to airline training centers, with cloud-based platforms disintermediating traditional simulator lessors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward regional flight schools as cloud-based subscription models fragment the historical simulator duopoly, consolidating procurement leverage among training organizations previously excluded from synthetic training credit.
For Market Incumbents: Entrench regulatory credit pathways by accelerating hybrid physical-digital certification investments that bridge legacy motion platforms with modern VR renderers, defending against cloud-native entrants threatening to commoditize visual simulation. Deepen backward integration into optical waveguide supply through long-term offtake agreements with Japanese and German substrate manufacturers, securing input cost stability as military procurement volumes expand. For New Entrants and Emerging Players: India's DGCA-regulated flight schools represent the most penetrable entry point, with fleet growth outpacing installed simulator capacity and carrier outsourcing creating demand for modular VR type-rating programs. Biometric-adaptive training algorithms for emergency procedure rehearsal offer a second white-space target, as EASA and MEE guidelines mature but certification timelines lag hardware development. A direct-to-flight-school SaaS go-to-market model bypasses incumbent OEM sales channels. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-streaming infrastructure providers with established latency-optimized delivery networks and existing Azure or AWS partnerships, positioned to capture recurring revenue from regional carrier adoption. The long-term viability window favors vendors with pre-certified explainable AI architectures capable of satisfying MEE algorithmic transparency mandates. Watch for FAA Part 60 revision announcements as the critical inflection signal determining whether standalone VR devices gain full type-rating credit.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Certification Investment | Bridges legacy FAA Part 60 hardware requirements with modern VR renderers to defend incumbent positioning. |
| Cloud Streaming Partnership | Azure-hosted infrastructure enables low-latency headset delivery without multi-million dollar capital commitments. |
| Optical Component Backward Integration | Long-term offtake agreements with Japanese and German waveguide suppliers stabilize input cost volatility. |
| Biometric-Adaptive Algorithm Development | Pre-certified explainable AI architectures satisfy MEE transparency mandates for military procurement programs. |
| Regional Flight School Consortium Formation | Pooled subscription commitments secure enterprise-grade SLAs and displace traditional capital purchase pathways. |
Research Methodology
Cross-validation between regulatory filing analysis and flight school procurement records anchors the qualitative findings, combining primary interviews with airline training directors, FAA certification specialists, MRO operations managers, and VR platform engineers with secondary validation against EASA CS-FSTD guidance documents, FAA Part 60 advisory circulars, and MEE algorithmic transparency guidelines. Bottom-up triangulation aggregates individual training device deployments by carrier and flight school, while top-down approaches cross-reference OEM revenue disclosures and hyperscale infrastructure capex allocations.
Calibration against historical simulator procurement cycles and cloud adoption curves in adjacent training verticals shapes the analytical framework across the projection horizon, with segmentation modeled by technology tier, application function, end-user type, and deployment architecture. CAGRs derive from installed base replacement rates, regulatory credit pathway expansion assumptions, and cloud infrastructure latency improvement trajectories. Industry-specific inputs include pilot training pipeline compression metrics at US and Chinese carriers, plus MRO outsourcing depth indices.
Practitioners should monitor EASA qualification stance evolution and FAA Part 60 revision timelines for early signals of regulatory credit pathway shifts. Forecasts reflect assumptions regarding cloud latency reduction, waveguide supply expansion, and biometric algorithm certification efficiency. Macroeconomic contraction affecting airline training budgets, regulatory deviation preserving hardware-centric qualification, or optical component supply disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Mobile Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market
Virtual Reality (VR) and Augmented Reality (AR)
Smart Augmented Reality Glasses for B2B Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Book Market
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market