
 Smart Barcode Readers Market | 2026-2036
Smart Barcode Readers Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Barcode Readers Market Insights
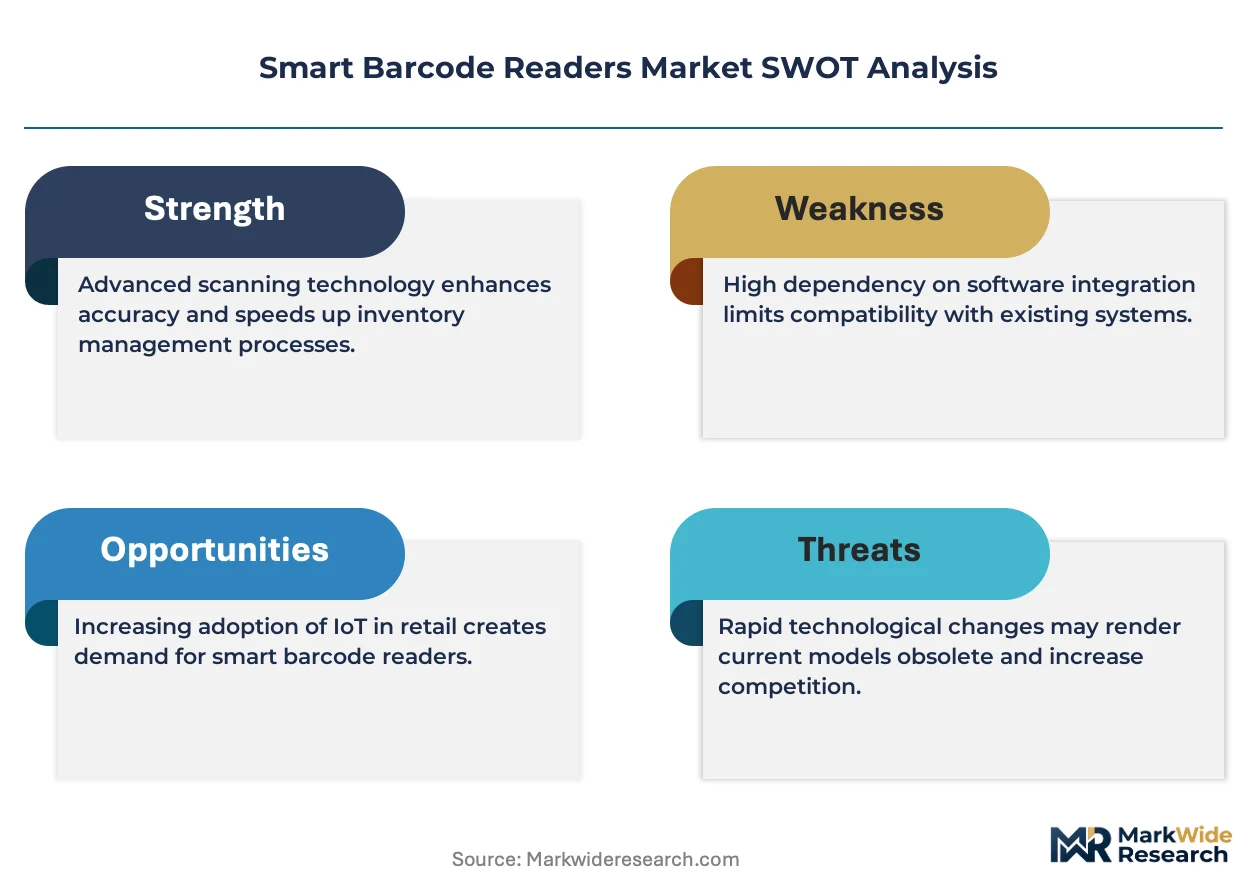
Equipment-as-a-service leasing is reconfiguring competitive entry barriers for mid-sized warehouse operators that previously deferred capital expenditure on automated identification infrastructure. Zebra Technologies leverages its channel density to bundle hardware with managed services contracts across North American distribution centers. Honeywell International anchors its position through backward integration into custom image-processing chipsets that reduce reliance on third-party sensor suppliers.
Smart barcode readers are electro-optical devices that decode one-dimensional and two-dimensional symbologies using laser diodes or CMOS image sensors, typically achieving read rates exceeding sixty frames per second at working distances from ten centimeters to over ten meters. Their primary commercial purpose is to eliminate manual data entry, synchronize inventory records with enterprise resource planning systems, and enforce chain-of-custody documentation in regulated supply chains. Handheld readers still dominate installed base volumes, yet wearable scanners are capturing disproportionate attention where hands-free operation directly improves worker productivity metrics. Image capture technology leads R&D allocation as two-dimensional matrix codes displace linear barcodes in pharmaceutical serialization and medical device labeling mandates.
The Federal Communications Commission governs radio-frequency emissions from Bluetooth and Wi-Fi enabled units, while the FDA enforces unique device identification requirements that mandate barcode readability standards for medical products distributed in the United States. REACH compliance in Europe restricts hazardous substances in printed circuit board assemblies, compelling Asian contract manufacturers to reformulate solder and coating chemistries for export-bound devices. Stakeholders must weigh whether to prioritize firmware subscription revenue models or preserve traditional hardware-margin economics as connectivity becomes standard across all price tiers.
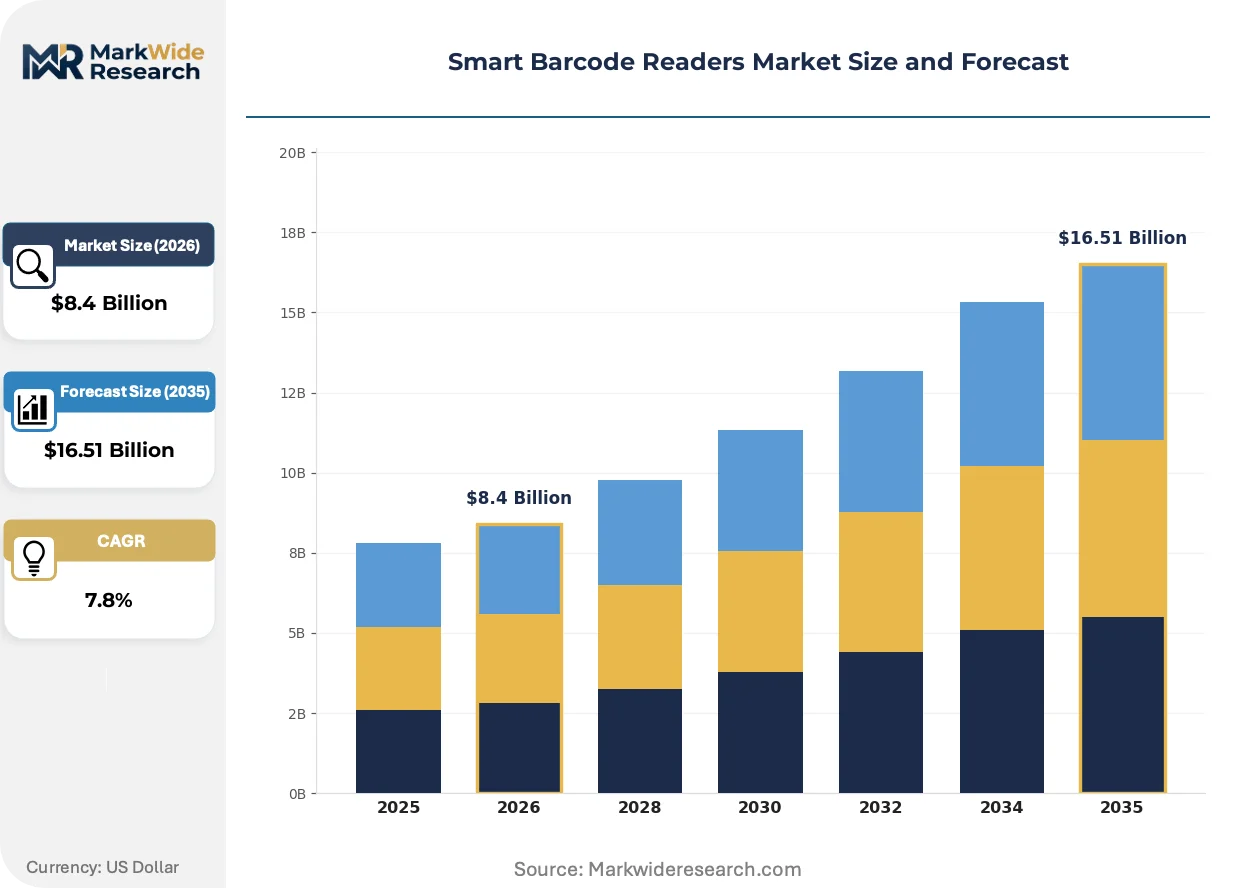
Market Dynamics
Wearable scanning hardware and modular repairable architectures are compressing replacement cycles while EU ecodesign mandates force hardware redesigns across the installed base. Logistics operators now treat barcode infrastructure as productivity leverage rather than cost center.
Growth Catalysts
- Pharmaceutical serialization mandates:FDA unique device identification requirements and EU MDR labeling rules compel healthcare distributors to upgrade to two-dimensional matrix-capable readers. Medical device traceability now demands sub-millisecond decode reliability.
- Warehouse labor optimization:Third-party logistics providers in Germany deploy voice-directed picking integrated with ring scanners to cut pick times. Hands-free operation reduces worker fatigue in high-velocity fulfillment centers.
- REACH compliance reformulation:Asian contract manufacturers requalify solder chemistries and conformal coatings for European-bound devices. Export compliance creates captive demand for certified hardware assemblies.
Market Restraints
- CMOS sensor supply concentration:Image sensor fabrication clusters in Taiwan and South Korea create single-source vulnerability for mid-tier reader manufacturers. Foundry allocation priorities favor smartphone and automotive volumes.
- Laser diode obsolescence cost:Linear barcode infrastructure in legacy warehousing requires full reader replacement rather than firmware upgrade. sunk hardware investments delay technology refresh decisions.
- Bluetooth spectrum congestion:FCC Part 15 unlicensed device density in dense logistics facilities introduces interference-driven read failures. Co-channel operation degrades real-time inventory synchronization.
Strategic Opportunities
- Indian pharmaceutical cold chain:CDSCO track-and-trace regulations for temperature-sensitive biologics create demand for ruggedized mobile readers with GPS logging. Domestic 3PL networks lack automated identification coverage.
- Computer vision convergence:Edge AI inference engines embedded in scanning hardware enable package damage detection concurrent with barcode decode. Dual-function devices displace separate quality inspection stations.
- Equipment-as-a-service channel:Leasing models with bundled maintenance and firmware subscriptions unlock mid-sized warehouse operators previously priced out of automated infrastructure. Service revenue stabilizes manufacturer cash flows.
Industry Challenges
- Embedded systems firmware talent:Real-time image pipeline optimization requires specialized computer vision engineering scarce outside semiconductor hubs. Contract manufacturers struggle to staff qualified validation teams.
- Multi-protocol integration complexity:Warehouse management system interfaces must reconcile Zebra, Honeywell, and Datalogic proprietary data formats with SAP and Oracle ERP schemas. Custom middleware development extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Barcode Readers Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Readers, Fixed Mount Readers, Mobile Scanners, Wearable Scanners Technology: Laser Scanning, Image Capture, RFID, 2D Barcode Scanning End User: Retail, Healthcare, Manufacturing, Logistics Connection Type: Bluetooth, USB, Wired, Wi-Fi |
| Companies Covered | Honeywell International, Zebra Technologies, Cognex, Datalogic, Denso Wave, Opticon Sensors, CipherLAB, Newland, SICK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Barcode Readers Market Trends and Innovations
Hardware architectures are fragmenting between disposable low-cost units and premium modular platforms, while regulatory pressure accelerates standardization around two-dimensional symbologies. Connectivity integration is becoming baseline rather than differentiator.
Decode algorithms are migrating from dedicated DSP chips to software-defined pipelines running on ARM Cortex-M class microcontrollers. Tier-two logistics operators in Poland and Czechia adopt these lower-cost platforms for seasonal volume surges. The shift compresses gross margins for established sensor suppliers while enabling white-label assembly entrants.
ECHA REACH substance restrictions on hexavalent chromium and certain phthalates in printed circuit board finishes force redesign of flex cable assemblies and connector plating. German automotive suppliers now demand full material disclosure documentation extending upstream to component vendors. Medical device OEMs face the tightest compliance timelines with MDR technical file submissions.
Buyer preference is consolidating around multi-year total-cost-of-ownership contracts rather than upfront hardware procurement. North American e-commerce fulfillment networks now specify uptime guarantees and spare-pool availability as primary selection criteria. Equipment financiers are embedding themselves earlier in vendor selection processes, reshaping competitive evaluation workflows.
Smart Barcode Readers Market Segmentation
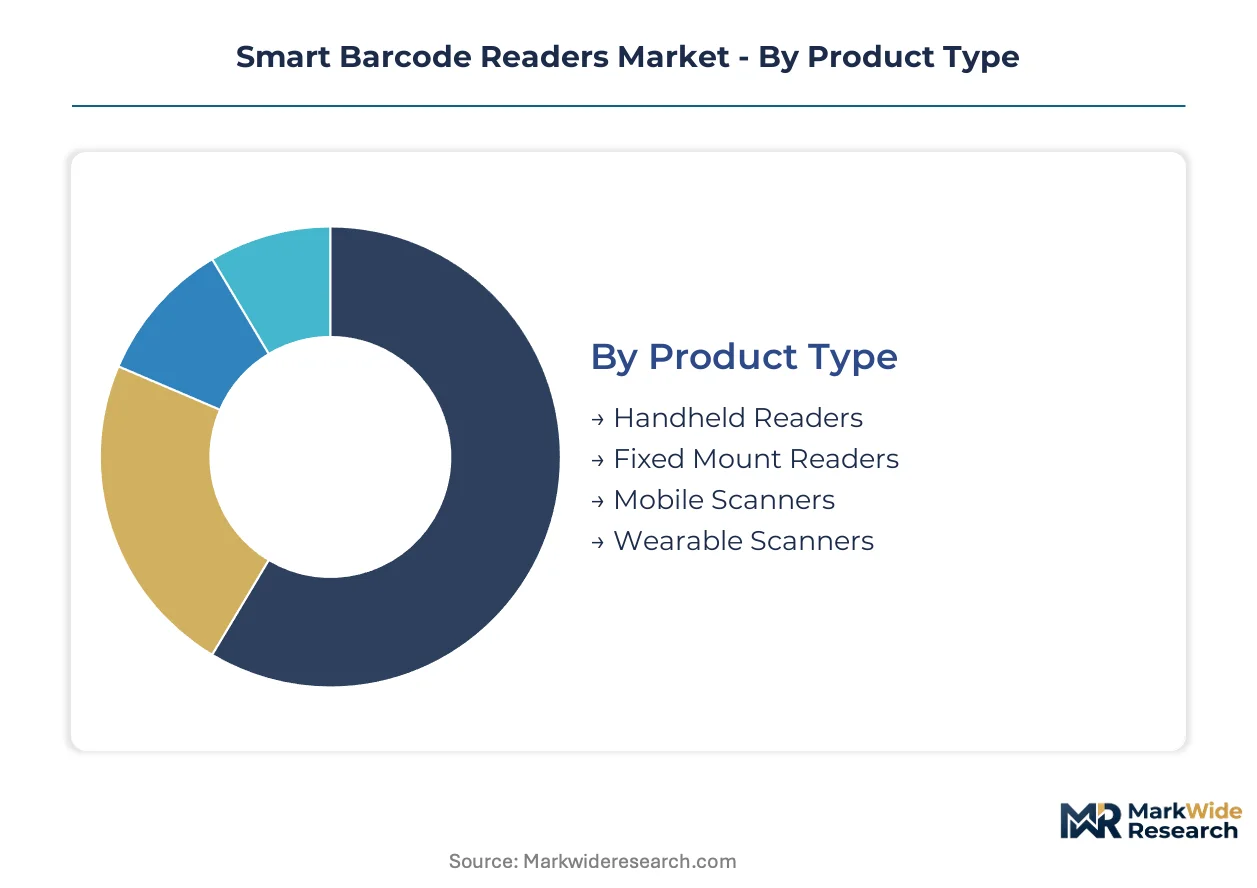
Smart barcode reader procurement decisions hinge on total cost of ownership calculations where firmware maintenance, spare-pool availability, and field service response times often exceed hardware depreciation in multi-year contracts. Segmentation reveals how after-sales intensity varies dramatically across product architectures and deployment environments.
Product Type:
After-sales service intensity escalates with device mobility and exposure to physical stress, creating divergent margin structures across hardware categories.
- Handheld Readers:Pistol-grip laser or imager units with trigger-actuated scanning dominate installed base volumes across warehouse and retail floors. German automotive parts distributors specify IP65-sealed variants with hot-swap battery systems to sustain three-shift operations without charging downtime.
- Fixed Mount Readers:Stationary units with automated trigger integration anchor high-speed conveyor applications in parcel sortation hubs. Demand concentrates in Benelux e-commerce fulfillment centers where decode reliability above sixty frames per second directly determines line throughput economics.
- Mobile Scanners:Vehicle-mounted or cart-attached units combine scanning with computing for inventory management in yard operations.
- Wearable Scanners:Ring-style or glove-integrated devices enable hands-free picking in voice-directed workflows.
Handheld readers hold the largest share; momentum sits with wearable scanners.
Technology:
Technology selection dictates sensor supply chain exposure and determines whether decode algorithms run on dedicated DSPs or software-defined ARM pipelines.
- Laser Scanning:Oscillating mirror and laser diode assemblies deliver linear barcode decode at extended range with minimal power draw. Legacy warehousing infrastructure in Poland and Czechia sustains replacement demand as operators defer full imager upgrades during margin compression.
- Image Capture:CMOS sensor-based platforms decode two-dimensional matrix codes and damaged labels through software-defined pipelines. Pharmaceutical serialization mandates in the United States and European Union compel healthcare distributors to prioritize sub-millisecond reliability for Data Matrix and QR symbologies.
- RFID:Radio-frequency identification readers supplement optical scanning for non-line-of-sight tag detection in asset tracking.
- 2D Barcode Scanning:Dedicated imager configurations optimized for two-dimensional symbology density in compact labeling applications.
Image capture holds the largest share; RFID is expanding most quickly in closed-loop asset tracking.
End User:
End-use verticals impose divergent compliance burdens and uptime requirements that reshape procurement evaluation criteria.
- Retail:Point-of-sale and backroom inventory applications prioritize ergonomic design and Bluetooth roaming stability. French hypermarket chains specify multi-protocol readers reconciling proprietary formats with SAP ERP schemas across distributed store networks.
- Healthcare:FDA unique device identification and EU MDR labeling rules mandate two-dimensional matrix decode capability with full audit trail documentation. Hospital pharmacies in Germany demand medical-grade disinfectant-ready housings and encrypted data transmission for patient safety workflows.
- Manufacturing:Work-in-process tracking and quality control integration drive demand for industrial-rated housings.
- Logistics:Third-party providers optimize for total cost per scan across high-velocity fulfillment operations.
Logistics holds the largest share; healthcare is gaining share fastest on regulatory compulsion.
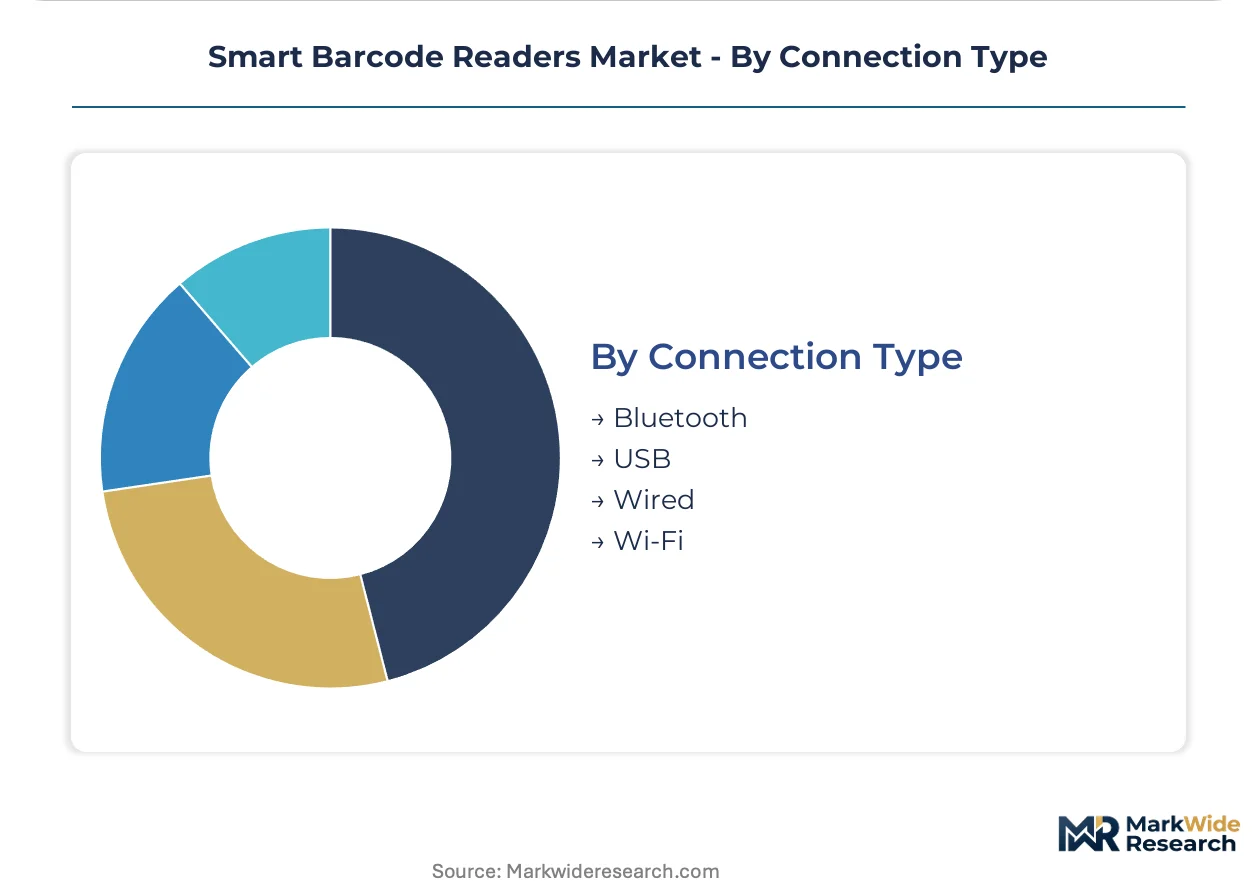
Connection Type:
Connectivity architecture determines deployment flexibility and spectrum management complexity in dense radio-frequency environments.
- Bluetooth:Unlicensed 2.4 GHz operation enables cordless mobility with smartphone and tablet pairing. FCC Part 15 device density in North American distribution centers introduces co-channel interference risks that degrade real-time inventory synchronization.
- USB:Tethered connectivity delivers guaranteed bandwidth and eliminates battery maintenance for fixed workstation applications. High-volume retail checkout lanes in the United States specify USB-HID emulation for plug-and-play POS integration without driver installation.
- Wired:RS-232 and Ethernet configurations persist in industrial automation requiring deterministic latency.
- Wi-Fi:802.11 enterprise roaming supports real-time data synchronization across large facilities.
Bluetooth holds the largest share; Wi-Fi shows steepest expansion trajectory in campus-scale deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive and pharmaceutical distribution networks in Germany concentrate the most acute buyer demand for high-fidelity traceability systems. Equipment-as-a-service leasing is reconfiguring competitive entry barriers for mid-sized warehouse operators across North America and Europe.
United States
Third-party logistics providers deploy voice-directed picking integrated with ring scanners to cut pick times in high-velocity fulfillment centers. The FDA enforces unique device identification requirements that mandate barcode readability standards for medical products. Distribution clusters in the Midwest and Southeast specify uptime guarantees and spare-pool availability as primary selection criteria.
Germany
Automotive parts distributors specify IP65-sealed handheld variants with hot-swap battery systems to sustain three-shift operations without charging downtime. The Ecodesign for Sustainable Products Regulation presses manufacturers toward modular, repairable hardware architectures. Pharmaceutical distribution networks in Baden-Württemberg and Bavaria require sub-millisecond decode reliability for Data Matrix compliance.
China
Contract manufacturers requalify solder chemistries and conformal coatings for European-bound devices under REACH substance restrictions. MIIT standards govern radio-frequency emissions from Bluetooth and Wi-Fi enabled units in domestic logistics facilities. Yangtze River Delta electronics clusters supply CMOS sensor assemblies for mid-tier reader manufacturers.
India
Domestic 3PL networks lack automated identification coverage for temperature-sensitive biologics under CDSCO track-and-trace regulations. The PLI scheme incentivizes local assembly of ruggedized mobile readers with GPS logging. Mumbai and Ahmedabad pharmaceutical cold chain operators represent the fastest-growing demand vector for certified hardware.
Japan
Work-in-process tracking drives demand for industrial-rated housings in automotive component plants. METI standards influence enterprise roaming specifications for 802.11-enabled campus deployments. Kansai and Chubu manufacturing belts prioritize deterministic latency in fixed-mount conveyor applications.
Smart Barcode Readers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent go-to-market strategies. The vendor base organizes into three tiers: multinational platform providers with managed services bundling, sensor-technology specialists with backward integration into custom chipsets, and regional assembly houses serving seasonal volume surges. Consolidation pressures favor players with captive firmware subscription revenue. Dominant competitive moves include strategic partnerships with warehouse management system vendors and geographic expansion through equipment financier relationships.
Within the multinational platform tier, Zebra Technologies and Honeywell International occupy positions defined by channel density and upstream control over image-processing components. Denso Wave exemplifies the industrial-automation specialist archetype rooted in Japanese manufacturing technology. These three anchors sit within a competitive set where differentiation hinges on total-cost-of-ownership contracting rather than hardware specifications alone.
| Leading Market Players |
|---|
| Honeywell International |
| Zebra Technologies |
| Cognex |
| Datalogic |
| Denso Wave |
| Opticon Sensors |
| CipherLAB |
| Newland |
| SICK |
| Others |
Pricing and Supply Chain Analysis
CMOS sensor fabrication concentration in Taiwan and South Korea determines both pricing tier spreads and supply chain shape, compressing margins for mid-tier reader manufacturers while forcing tier-one players toward captive silicon strategies.
Pricing Analysis
Cost-plus contracts with semiconductor foundry indexation dominate procurement for image-capture platforms. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade disinfectant-ready units with encrypted transmission from Polish warehouse operators' seasonal low-cost ARM-based devices. Pricing pressure stems from software-defined pipeline migration that compresses gross margins for established DSP suppliers. Third-party logistics providers in Germany exhibit lowest price sensitivity due to uptime guarantee requirements, while Indian cold chain operators represent the most price-constrained buyer segment.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for contract manufacturers. CMOS sensor assemblies draw from Yangtze River Delta clusters, laser diodes from Japanese and German precision optics houses, and ARM-class microcontrollers from Taiwanese foundries. Single-source vulnerability in image sensor allocation priorities—where smartphone and automotive volumes preempt barcode reader demand—creates procurement bottlenecks during capacity crunches. Distribution runs through equipment financiers embedding earlier in vendor selection workflows across North American and European fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical serialization mandates and EU ecodesign regulations are reshaping competitive positioning, creating a high-growth disruption where firmware subscription revenue models displace traditional hardware-margin economics.
For Market Incumbents: Harden defensive positions through backward integration into custom image-processing chipsets that reduce reliance on Taiwanese foundry allocation priorities. Deepen channel control by bundling hardware with managed services contracts specifying spare-pool availability and field service response guarantees. Prioritize certification investment for REACH-compliant modular architectures ahead of MDR technical file deadlines. For New Entrants and Emerging Players: Build out white-label assembly capabilities targeting Polish and Czechia seasonal volume surges where software-defined ARM pipelines enable rapid cost repositioning. Penetrate the Indian pharmaceutical cold chain through ruggedized mobile readers with GPS logging for CDSCO track-and-trace compliance. Pursue equipment-as-a-service leasing relationships with domestic 3PL networks lacking automated identification coverage. For Investors and Strategic Acquirers: The market sits at a regulatory-compulsion phase that favors sensor-technology specialists with upstream control over decode algorithms. Long-term viability over the projection horizon rests on firmware subscription retention rather than hardware shipment volumes. Target acquisition archetypes combining edge AI inference capabilities with established warehouse management system integration partnerships. Monitor FDA unique device identification enforcement intensity as the primary inflection indicator for healthcare segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Custom Chipsets | Honeywell's image-processing silicon reduces Taiwanese foundry dependency for healthcare-grade readers. |
| Equipment-as-a-Service Channel Expansion | Zebra's managed services bundling unlocks mid-sized warehouse operators previously deferring capital expenditure. |
| Edge AI Inference Engine Embedding | Dual-function devices enable package damage detection concurrent with barcode decode in Benelux sortation hubs. |
| REACH Compliance Modular Redesign | German automotive suppliers now demand full material disclosure extending upstream to flex cable vendors. |
| Warehouse Management System Partnership | Middleware integration with SAP and Oracle ERP schemas compresses deployment timelines for voice-directed picking. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and semiconductor foundry allocation disclosures. Interviews with warehouse operations directors, biomedical engineers at German hospital pharmacies, procurement leads at third-party logistics providers, and aftermarket service heads at automotive distributors informed demand-side validation. Bottom-up shipment analysis triangulates against top-down enterprise resource planning system penetration estimates across the projection horizon.
Forecast inputs span product type mobility tiers, decode technology architectures, end-use compliance burdens, and connectivity protocol adoption curves. Volume and value outputs derive from segment-level CAGRs calibrated against pharmaceutical serialization mandate timelines and EU ecodesign implementation phases. Modeled variables include CMOS sensor supply elasticity, firmware subscription attach rates, and equipment-as-a-service contract penetration across mid-sized warehouse operator segments.
Stress conditions across foundry allocation priority shifts, REACH substance restriction enforcement intensity, and Bluetooth spectrum congestion thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory compulsion timelines and substitution elasticity between laser and imager platforms. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Smart Beacon Market
Sensors
Global Real-Time Locating Systems (RTLS) Market
Sensors
Ultrasonic Technologies Market
Sensors
Europe Lidar Market
Sensors
IO-Link Technology Market
Sensors
Conveyor Monitoring Market
Sensors
Machine Health Monitoring Market
Sensors
Weigh-In-Motion System Market
Sensors
Lidar Market
Sensors
Mobile Mapping Systems Market
Sensors
Lidar in Construction Market
Sensors
APAC Wireless Sensors Market
Sensors
Digital Olfaction Products Market
Sensors
Traffic Sensor Market
Sensors
Portable Iris Recognition Scanner Market
Sensors
Handheld RFID Readers Market