
 Industrial Barcode Scanners Market | 2026-2036
Industrial Barcode Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Barcode Scanners Market Foresight
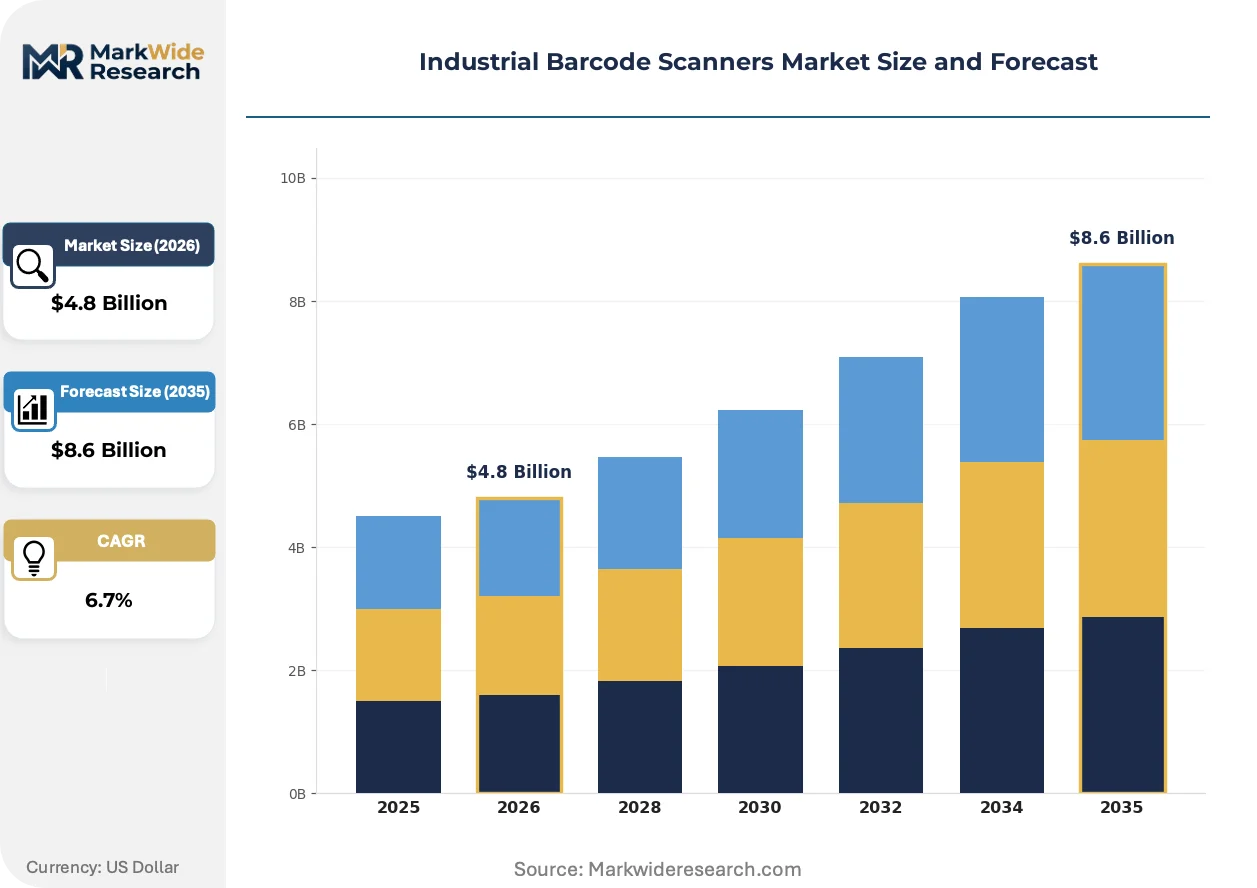
CMOS image sensors are expanding their share in industrial barcode scanners as manufacturers phase out laser diode assemblies for cost and durability reasons. Zebra Technologies Corporation leverages its captive semiconductor sourcing to protect margin pools in mobile computer segments. Honeywell International Inc. sustains dominant positions in ruggedized handheld lines through its Intelligrated distribution arm. Cognex Corporation differentiates via machine vision integration, anchoring premium pricing in quality control applications.
Industrial barcode scanners are electro-optical data capture devices that convert printed symbologies into digital signals using charge-coupled device or complementary metal-oxide semiconductor arrays, typically operating at decode speeds exceeding sixty frames per second for high-velocity conveyor integration. Their primary commercial purpose is to eliminate manual data entry errors while enabling real-time inventory visibility across distributed supply chain nodes. Handheld scanners occupy the largest volume tier, though mobile computers command superior margin profiles due to embedded computing and wireless connectivity bundling. Imaging technology leads new installations as 2D barcode penetration in pharmaceutical and defense traceability mandates displaces legacy laser-only architectures.
The Federal Communications Commission governs radio frequency emissions from wireless scanner models in the United States, while the European Union's Radio Equipment Directive and CE marking framework dictate electromagnetic compatibility and safety standards for devices sold across member states. Japan's Ministry of Economy, Trade and Industry enforces JIS standards for industrial equipment durability that directly influence scanner ingress protection ratings and vibration tolerance specifications. Stakeholders must monitor evolving battery chemistry regulations and right-to-repair legislation, as these frameworks increasingly determine hardware modularity requirements and aftermarket service revenue potential.
Market Dynamics
The transition from laser diode to solid-state imaging architectures is compressing component costs while elevating performance floors across warehouse and manufacturing deployments.
Growth Catalysts
- CE marking migration:The EU's Radio Equipment Directive accelerates imaging-based scanner replacements, as legacy laser systems face electromagnetic compatibility recertification hurdles.
- Automotive traceability mandates:Germany's automotive manufacturing corridor demands precision tracking for component genealogy, pulling high-speed decode capabilities into assembly line retrofits.
- CMOS sensor maturation:Semiconductor foundries in Taiwan and South Korea now produce industrial-grade image sensors at yields that undercut laser assembly bill-of-materials.
Market Restraints
- Semiconductor supply concentration:Foundry capacity for specialized industrial sensors clusters in East Asia, exposing procurement timelines to geopolitical friction.
- RoHS compliance costs:The EU's Restriction of Hazardous Substances directive forces redesign of solder joints and connector plating, adding engineering validation cycles.
- Mobile computer substitution:Ruggedized smartphones with integrated scanning modules erode standalone handheld volume in light-duty warehouse applications.
Strategic Opportunities
- Indian manufacturing corridors:The country's PLI scheme for electronics assembly creates first-mover advantage for scanner OEMs establishing local calibration facilities.
- Machine vision convergence:Quality control stations increasingly combine barcode decode with dimensional inspection, collapsing two capital expenditures into one.
- Right-to-repair tailwinds:Battery replacement mandates in France and Germany enable aftermarket service revenue streams previously captured by sealed-unit replacements.
Industry Challenges
- Optical engineering talent scarcity:Industrial lens design expertise concentrates in aging workforces across Japan and Germany, constraining product development velocity.
- Legacy system integration friction:Warehouse management software written for serial-port laser scanners requires middleware layers to accommodate USB-C imaging devices.
- IP fragmentation in decode algorithms:Patent thickets around 2D symbology processing force licensing negotiations that delay regional product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Barcode Scanners Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Scanners, Stationary Scanners, Mobile Computers, Fixed Mount Scanners Technology: Laser, Imaging, RFID, 2D Barcode End User: Manufacturing, Retail, Healthcare, Logistics Application: Inventory Management, Quality Control, Product Tracking, Shipping Logistics |
| Companies Covered | Honeywell International Inc., Zebra Technologies Corporation, Cognex Corporation, Datalogic S.p.A., SATO Holdings Corporation, Toshiba TEC Corporation, Newland Digital Technology Co. Ltd., OMRON Corp., Opticon Sensors Europe BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Barcode Scanners Market Shifts & Advancements
Imaging technology is collapsing the boundary between barcode capture and machine vision, forcing hardware architectures to absorb computational workloads previously handled by downstream systems.
Edge AI inference engines are integrating directly into scanner system-on-chip designs, enabling real-time package damage detection without external computing nodes. Pharmaceutical distributors in the United States deploy these units to satisfy FDA track-and-trace mandates while eliminating separate inspection stations. The decode-to-decision latency compression is integrating quality control into material handling workflows that previously required sequential processing stages.
The EU's F-Gas Regulation is restricting refrigerants in cold-chain logistics infrastructure, indirectly elevating ingress protection requirements for scanners operating in retrofit warehouse environments. Equipment deployed in frozen food distribution must now demonstrate sealed thermal management without maintenance access panels that breach IP ratings. German cold-storage operators are responding by specifying scanners with potted electronics and solid-state components that eliminate venting requirements.
Buyer concentration among third-party logistics providers is compressing procurement cycles and unbundling after-sales service contracts from hardware purchases. Amazon and DHL negotiate direct spare parts availability rather than maintenance subscriptions, shifting margin pools from service attach rates to upfront equipment pricing. This behavior is most pronounced in the United States, where logistics real estate investment trusts standardize equipment specifications across multi-tenant fulfillment centers.
Industrial Barcode Scanners Market Segmentation
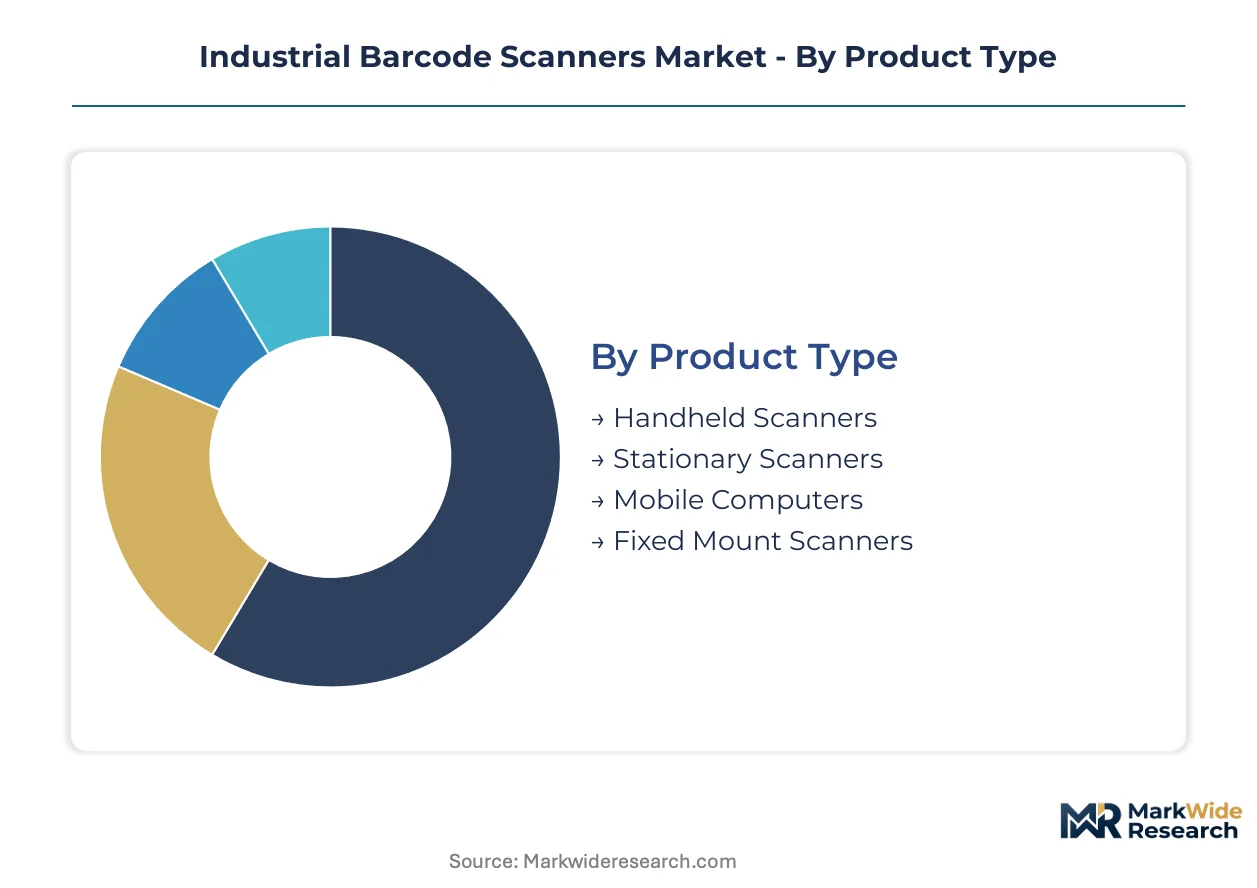
Industrial barcode scanner segmentation reveals how hardware architectures map to operational complexity tiers. Integration depth separates standalone peripherals from embedded computing nodes, determining procurement patterns and margin structures across supply chain environments.
Product Type:
Standalone peripherals dominate light-duty workflows, while embedded systems absorb computing and connectivity into unified platforms for mission-critical deployments.
- Handheld Scanners:Pistol-grip or pen-style electro-optical devices with tethered or Bluetooth connectivity, typically deployed for intermittent scanning tasks. Demand concentrates in German automotive supplier parks where BMW and Siemens enforce component-level traceability across tiered supplier networks.
- Mobile Computers:Ruggedized Android or Windows devices integrating decode engines with cellular, Wi-Fi, and application processing. These command premium pricing in United States third-party logistics where Amazon and DHL standardize on single-vendor fleets to simplify fleet management software integration.
- Stationary Scanners:Countertop or presentation-style units for fixed-position checkout and receiving stations.
- Fixed Mount Scanners:Industrial-grade units sealed to IP65+ ratings for conveyor integration in high-velocity distribution centers.
Handheld scanners lead volumes today; mobile computers are gaining share fastest.
Technology:
Decode architectures stratify by symbology complexity and environmental tolerance, with solid-state imaging displacing coherent light systems across new installations.
- Imaging:CMOS or CCD array-based capture supporting 1D and 2D symbologies with damage tolerance and omnidirectional reading. Taiwan and South Korean foundry capacity is undercutting laser assembly costs, accelerating adoption in pharmaceutical distribution for FDA track-and-trace compliance.
- 2D Barcode:Specialized decode engines optimized for Data Matrix, QR Code, and Aztec symbologies with error correction. EU Falsified Medicines Directive enforcement in France and Germany is mandating these capabilities for pharmaceutical serialization at unit level.
- Laser:Rotating mirror or linear diode systems limited to 1D symbologies, now relegated to legacy retrofit markets.
- RFID:Radio-frequency identification readers operating at UHF or HF bands for non-line-of-sight bulk capture in apparel and asset tracking.
Imaging technology anchors new procurement; 2D Barcode capabilities show steepest expansion trajectory.
End User:
Vertical specialization drives feature prioritization, with regulatory intensity determining ruggedization and connectivity specifications.
- Manufacturing:Shop-floor deployments requiring vibration tolerance, oil resistance, and seamless PLC integration. Germany's automotive corridor demands precision tracking for component genealogy, pulling high-speed decode into assembly line retrofits.
- Logistics:High-velocity warehouse and transportation environments prioritizing read range, battery endurance, and fleet management scalability. United States cold-chain operators specify potted electronics to satisfy EU F-Gas Regulation impacts on retrofit infrastructure.
- Retail:Point-of-sale and backroom inventory applications emphasizing ergonomic design and cost efficiency.
- Healthcare:Patient identification and medication administration requiring antimicrobial housings and FDA 21 CFR Part 11 compliance.
Logistics commands the largest equipment volumes; manufacturing shows the fastest technology refresh cycles.
Application:
Use case specificity determines decode speed requirements and downstream system integration depth.
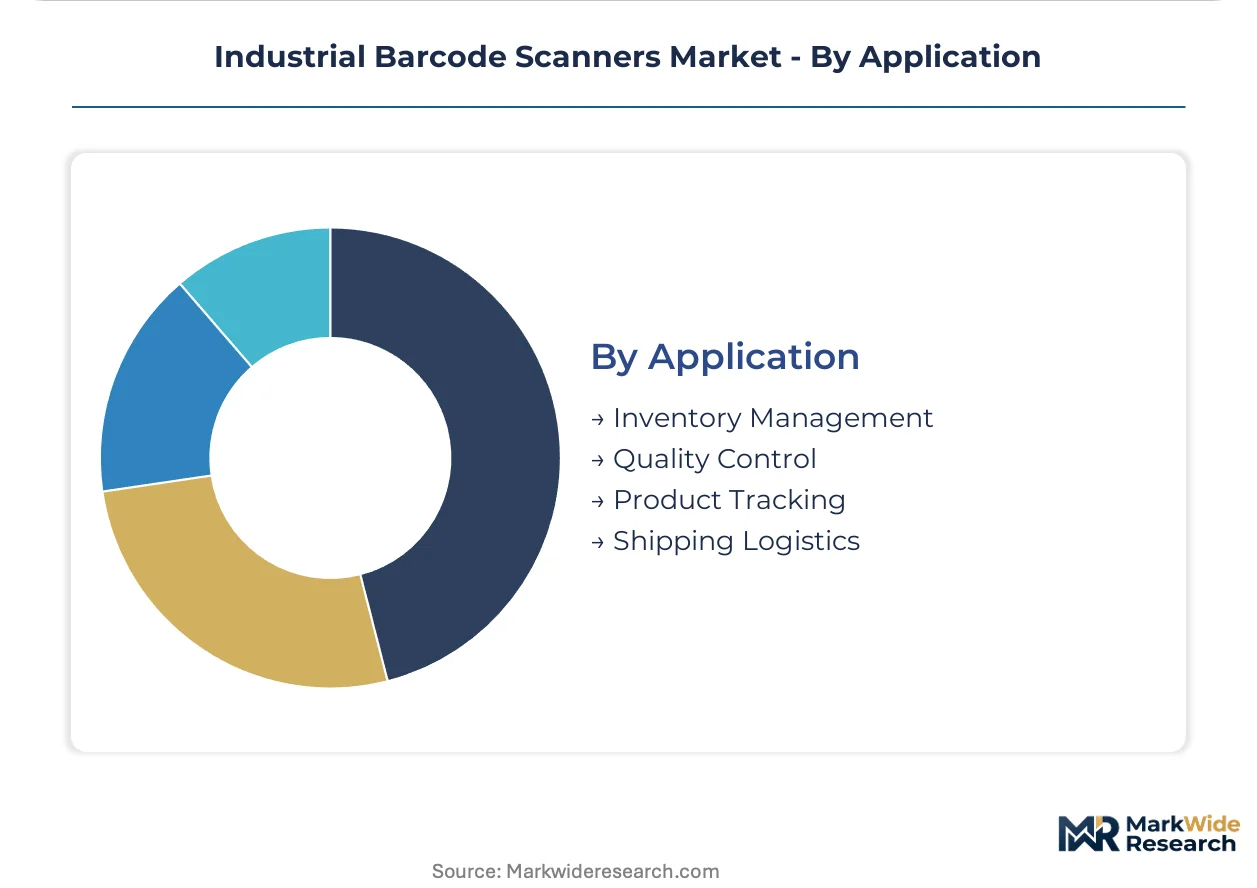
- Inventory Management:Cyclic counting, receiving, and put-away operations requiring batch or real-time data upload to WMS platforms. Indian electronics manufacturing zones under PLI scheme incentives are deploying these systems for first-mile visibility.
- Quality Control:Inline inspection combining barcode verification with dimensional or cosmetic defect detection. Edge AI integration is collapsing separate machine vision stations into unified capture nodes in United States pharmaceutical distribution.
- Product Tracking:Serialized item-level traceability across supply chain nodes for recall management and authenticity verification.
- Shipping Logistics:Manifest verification, sortation induction, and last-mile delivery confirmation prioritizing read range and motion tolerance.
Inventory Management leads deployment counts; Quality Control is climbing fastest as vision convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridor anchors scanner demand through BMW and Siemens precision tracking requirements, pulling high-speed decode capabilities into assembly line retrofits. Warehouse automation investments by Amazon and DHL concentrate procurement power in logistics hubs. Regulatory divergence across jurisdictions is fragmenting product certification requirements.
United States
Third-party logistics providers drive fleet standardization across multi-tenant fulfillment centers. The FCC governs radio frequency emissions from wireless scanner models, mandating electromagnetic compatibility testing. Cold-chain operators in the Midwest specify potted electronics to satisfy thermal management requirements in retrofit warehouse environments.
Germany
Automotive traceability mandates from BMW and Siemens enforce component-level genealogy tracking across tiered supplier networks. The EU's CE marking and Radio Equipment Directive accelerate imaging-based replacements as legacy laser systems face recertification hurdles. Bavaria's manufacturing clusters anchor precision decode requirements in assembly line retrofits.
China
Electronics assembly zones under industrial upgrading programs deploy scanners for first-mile visibility in component tracking. The country's national standards body enforces GB standards for industrial equipment durability that influence ingress protection specifications. Yangtze River Delta logistics hubs concentrate demand for high-velocity conveyor integration.
India
The PLI scheme for electronics assembly creates first-mover advantage for OEMs establishing local calibration facilities. The Bureau of Indian Standards enforces equipment durability criteria that directly influence scanner vibration tolerance specifications. Maharashtra and Gujarat manufacturing corridors are deploying inventory management systems for supplier network visibility.
Japan
Pharmaceutical distributors deploy edge AI-integrated units to satisfy track-and-trace mandates while eliminating separate inspection stations. METI enforces JIS standards for industrial equipment durability that determine scanner ingress protection ratings. Kanto region logistics operators specify solid-state components that eliminate venting requirements in sealed thermal management designs.
Industrial Barcode Scanners Market Competitive Landscape
Global majors compete with regional champions across technology integration depth, with consolidated positions in mobile computing segments and fragmented competition in handheld peripherals. Three strategic archetypes dominate: semiconductor-captive diversified technology conglomerates, machine vision specialists converging barcode and quality inspection, and regional component fabricators serving price-sensitive volume tiers. Competitive moves center on captive sensor sourcing to protect margin pools and machine vision convergence to collapse separate capital expenditures into unified capture nodes.
Within the diversified technology tier, Honeywell International Inc. and Zebra Technologies Corporation exemplify semiconductor-captive positioning, while Cognex Corporation anchors the machine vision convergence archetype. Honeywell sustains positions in ruggedized handheld lines through distribution arm integration. Zebra leverages captive semiconductor sourcing to protect margin pools in mobile computer segments. Cognex differentiates via machine vision integration, anchoring premium positioning in quality control applications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Zebra Technologies Corporation |
| Cognex Corporation |
| Datalogic S.p.A. |
| SATO Holdings Corporation |
| Toshiba TEC Corporation |
| Newland Digital Technology Co. Ltd. |
| OMRON Corp. |
| Opticon Sensors Europe BV |
| Others |
Supply & Pricing Matrix
Buyer consolidation among Amazon and DHL is forcing component suppliers to absorb warranty extension costs while maintaining decode speed specifications, compressing margin pools for mid-tier handheld manufacturers unable to source CMOS sensors at Taiwan foundry rates.
Pricing Analysis
Semiconductor foundry pricing in Taiwan and South Korea passes directly into mobile computer bill-of-materials, with imaging-based architectures commanding premium positioning over legacy laser systems. Three-tier pricing structure across premium, standard, and economy levels separates machine vision-integrated units from basic decode peripherals from refurbished legacy fleets. Price differentiation hinges on CE marking certification tier and after-sales service bundling. Cost compression in economy handhelds is intensifying because ruggedized smartphones with integrated scanning modules erode standalone volume in light-duty warehouse applications. Third-party logistics providers show least price sensitivity due to fleet standardization mandates, while Indian electronics assembly zones under PLI scheme incentives drive hardest bargaining for volume procurement.
Supply Chain Analysis
Freight cost volatility from East Asian semiconductor hubs to German automotive corridors and United States Midwest distribution centers is elevating landed cost uncertainty for imaging sensor-dependent manufacturers. Supply concentrates in Taiwan, South Korea, and China for CMOS sensors, with secondary assembly in Mexico and Vietnam for North American market access. Raw material dependencies span industrial-grade glass optics, lithium-ion battery cells, and RoHS-compliant solder alloys. Single-source vulnerability around Taiwan foundry capacity exposes procurement timelines to geopolitical friction. Distribution runs through direct OEM relationships with Amazon and DHL for volume tiers, supplemented by Intelligrated and regional distributor networks for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Pharmaceutical traceability mandates and FDA track-and-trace compliance requirements are pulling specifications toward premium imaging-based architectures with embedded edge AI.
For Market Incumbents: Cement positions in ruggedized mobile computing segments through captive semiconductor sourcing agreements with Taiwan foundries, insulating margin pools from spot-market volatility. Deepen calibration facility footprints in India under PLI scheme incentives to capture local procurement preferences. Prioritize machine vision convergence R&D to collapse separate quality control stations into unified capture nodes before Cognex Corporation extends premium positioning downward. For New Entrants and Emerging Players: Launch via white-label partnerships with Indian electronics manufacturing corridors targeting inventory management deployments under PLI scheme incentives. Focus on stationary scanner retrofits for cold-chain logistics operators in Germany responding to EU F-Gas Regulation thermal management requirements. Exploit optical engineering talent scarcity in Japan and Germany by recruiting from aging workforces at distressed component fabricators. For Investors and Strategic Acquirers: Asymmetric upside sits with machine vision specialists possessing decode algorithm IP and pharmaceutical regulatory compliance track records. Long-term viability favors converged barcode-quality inspection platforms over standalone peripheral manufacturers facing mobile computer substitution. Watch for inflection signals in right-to-repair legislation enforcement across France and Germany, which would unlock aftermarket service revenue streams previously captured by sealed-unit replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CMOS Sensor Sourcing | Captive Taiwan foundry relationships protect margin pools in mobile computer segments against spot-market volatility. |
| Machine Vision Convergence Development | Edge AI integration collapses separate quality control stations into unified capture nodes for pharmaceutical distributors. |
| Indian Calibration Facility Establishment | PLI scheme incentives create first-mover advantage for OEMs serving Maharashtra and Gujarat manufacturing corridors. |
| Right-to-Repair Service Infrastructure Buildout | Battery replacement mandates in France and Germany enable aftermarket revenue streams from previously sealed units. |
| Cold-Chain Thermal Management Certification | Potted electronics specifications satisfy EU F-Gas Regulation impacts on retrofit warehouse infrastructure. |
Research Methodology
Direct dialogue with warehouse operations directors, automotive plant engineers, pharmaceutical distribution managers, and aftermarket service heads grounded qualitative findings in operational reality. Primary insights were cross-referenced against secondary sources including FCC equipment authorization databases, EU Radio Equipment Directive compliance filings, FDA track-and-trace guidance documents, and Taiwan semiconductor foundry capacity disclosures. Bottom-up unit shipment estimates by product tier and technology architecture were triangulated against top-down market value reconstructions.
Bottom-up modeling segmented volume and value across handheld scanners, mobile computers, stationary units, and fixed-mount installations, further disaggregated by imaging, 2D barcode, laser, and RFID technology architectures. End-user splits captured manufacturing, logistics, retail, and healthcare verticals with regulatory intensity adjustments. CAGRs were derived from installed base replacement cycles, technology transition curves from laser to imaging, and penetration assumptions for edge AI integration. Forecast inputs incorporated BMW and Siemens precision tracking requirements, Amazon and DHL fleet standardization behaviors, and EU CE marking migration timelines.
Several conditions sit outside the modeled scope, including sudden Taiwan Strait logistics disruptions, abrupt RoHS directive amendments affecting solder chemistry, and unforeseen 2D symbology patent litigation outcomes. Forecasts reflect assumptions around semiconductor foundry yield stability and logistics real estate investment trust equipment specification continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Remote Sensing Technology Market
Sensors
Machine Health Monitoring Market
Sensors
Indoor Location Market
Sensors
Eye Tracking Market
Sensors
Residential Water Leak Detection System Market
Sensors
Weigh-In-Motion System Market
Sensors
Global Tunnel Monitoring System Market
Sensors
Eye Tracking Solutions Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
Portable Iris Recognition Scanner Market
Sensors
Europe RFID Market
Sensors
Global Equipment Monitoring Market
Sensors
Vibration Monitoring Market
Sensors
Bluetooth Photo Capture Device Market
Sensors
Gesture Recognition in Retail Market
Sensors
Ultrasonic Technologies Market