
 Eye Tracking Market | 2026-2036
Eye Tracking Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Tracking Market Intelligence
The eye tracking industry is recalibrating around a sharp split between research-grade precision hardware and mass-market automotive integration. Tobii AB dominates the premium research tier with infrared-based lab systems that sustain pricing power through proprietary calibration algorithms. Seeing Machines anchors the automotive safety segment with driver monitoring systems that compete on regulatory certification breadth across multiple type-approval regimes.
Eye tracking measures ocular movement and gaze fixation through pupil-corneal reflection tracking, typically operating at sampling rates between 60 Hz and 2000 Hz depending on hardware class, with primary commercial purpose in human-computer interaction analysis and real-time attention quantification. Remote trackers lead volume in academic and marketing applications where non-contact deployment preserves natural behavior, while wearable trackers capture the fastest expansion as VR headset manufacturers integrate optical gaze estimation directly into display assemblies. Hybrid technology architectures concentrate margin pools by combining infrared illumination with video-based processing to serve both low-latency automotive alerts and high-fidelity research protocols.
The European Union's General Safety Regulation mandates driver drowsiness and distraction monitoring in new vehicle types, pushing automotive manufacturers toward certified gaze-tracking suppliers. The U.S. NHTSA issues guidance on advanced driver monitoring performance while academic institutions navigate institutional review board protocols for human subjects research involving biometric data collection. Stakeholders must monitor divergence between ISO 26262 functional safety requirements for automotive deployments and the less standardized ethical review frameworks governing research and consumer VR applications.
Market Dynamics
The automotive sector's Euro NCAP safety protocol compliance is compressing procurement cycles for driver monitoring systems while research-grade hardware defends margins through proprietary calibration IP.
Growth Catalysts
- Euro NCAP distraction protocols:European vehicle type-approval mandates gaze-tracking integration for five-star safety ratings, forcing OEM validation partnerships with certified suppliers.
- VR headset integration:Optical gaze estimation embedded directly into display assemblies creates captive demand from immersive hardware manufacturers seeking foveated rendering capability.
- Academic research clusters:University behavioral science departments in Germany, Sweden, and the United States sustain replacement demand for sub-degree accuracy systems.
Market Restraints
- Indium gallium arsenide sensor costs:Near-infrared detector materials face price volatility from semiconductor foundry capacity constraints in East Asian supply chains.
- Calibration labor intensity:Research-grade systems require operator-assisted participant setup protocols that resist full automation and limit throughput scaling.
- Biometric data governance:GDPR Article 9 special category processing rules impose consent documentation burdens on European consumer-facing deployments.
Strategic Opportunities
- Aviation pilot training:Crew resource management simulation programs represent underpenetrated demand for gaze-pattern analysis during high-workload scenarios.
- Healthcare diagnostic screening:Neurological assessment protocols are converging eye movement analytics with cognitive load measurement for early disease detection.
- ISO 26262 functional safety certification:Automotive suppliers achieving ASIL-D ratings unlock premium positioning in driver monitoring system procurement.
Industry Challenges
- Optical engineering talent scarcity:Pupil-tracking algorithm development requires specialized computer vision expertise concentrated in limited geographic talent pools.
- Multi-domain certification timelines:Suppliers must sequence automotive type-approval, medical device registration, and aviation safety assessments with non-overlapping review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Tracking Market |
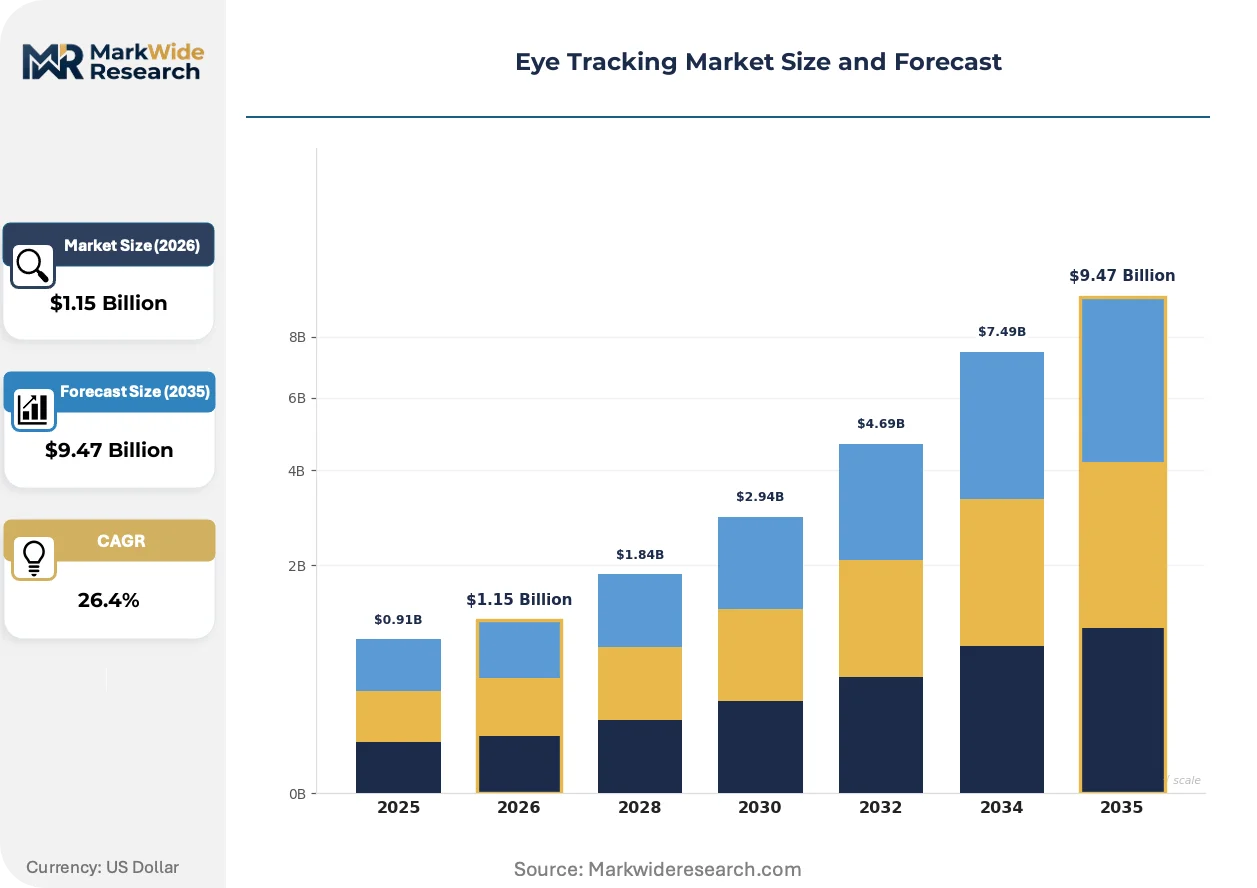
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $9.47 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Trackers, Wearable Trackers, Mobile Trackers, Integrated Trackers Technology: Infrared, Video-Based, Electro-oculography, Optical, Hybrid Application: Psychology Research, Automotive Safety, Marketing Analysis, Virtual Reality, Assistive Technology End User: Academic Institutions, Automotive Manufacturers, Advertising Agencies, VR Developers, Medical Clinics |
| Companies Covered | Tobii AB, Seeing Machines, Smart Eye AB, SR Research Ltd., EyeTech Digital Systems, EyeTracking, Inc., Ergoneers GmbH, iMotions, Pupil Labs GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Tracking Market Strategic Shifts & Innovations
Hardware architectures are collapsing the historical separation between remote screen-based trackers and head-mounted wearables, creating unified platform strategies that span automotive, research, and consumer VR deployments.
Event-based sensor technology is unifying low-light performance with microsecond latency through asynchronous pixel-level activation. Automotive Tier 1 suppliers are adopting these sensors for drowsiness detection at highway speeds. The convergence is unifying previously separate infrared and visible-light processing pipelines into single-chip solutions that compress bill-of-materials costs.
REACH restrictions on heavy metals in electronics are forcing redesigns of traditional infrared illuminator assemblies across European supply chains. Manufacturers are substituting gallium arsenide emitters for legacy arsenic-containing compounds. Medical device and automotive segments face the steepest reformulation timelines given their extended qualification protocols.
Academic procurement is fragmenting from centralized lab equipment budgets toward distributed departmental purchasing with cloud-based analytics subscriptions. University psychology and marketing departments are displacing capital-intensive hardware ownership with per-study licensing models. Germany and the United States exhibit the fastest migration toward usage-based service contracts.
Eye Tracking Market Segmentation
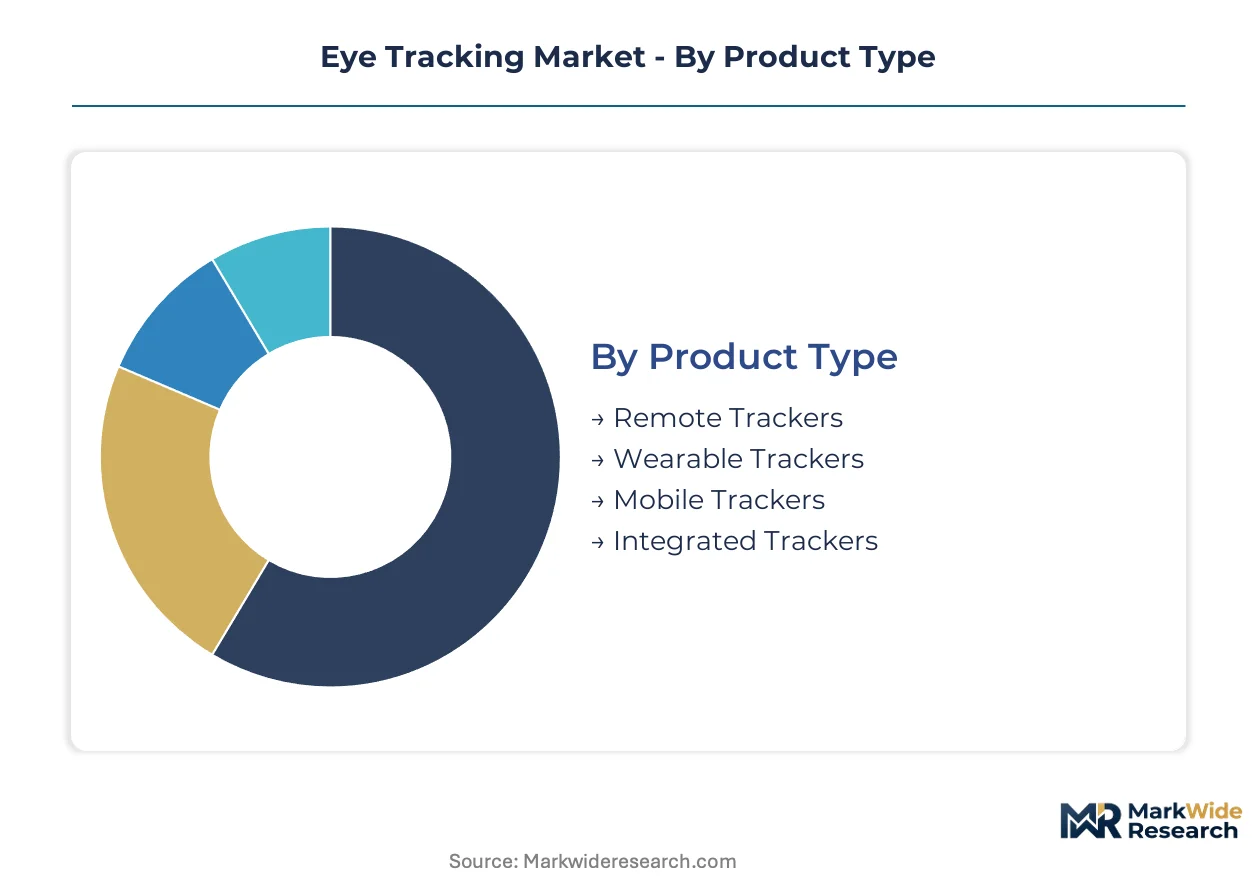
Eye tracking hardware and software configurations diverge sharply across use cases, with capital requirements, calibration complexity, and regulatory certification burdens determining supplier profitability. Understanding these segment boundaries reveals where technology platforms can scale versus where specialized engineering defends margin pools.
Product Type:
Capital intensity varies dramatically across form factors, with integrated automotive systems demanding the heaviest upfront validation investment while remote screen-based units minimize per-unit manufacturing costs.
- Remote Trackers:Screen-mounted or standalone cameras capture pupil-corneal reflection without headgear, typically operating at 60-120 Hz for marketing and academic applications. Germany and the United States concentrate replacement demand as university behavioral science departments upgrade legacy lab equipment.
- Wearable Trackers:Head-mounted assemblies embed gaze estimation directly into VR headsets or specialized glasses, requiring tight integration with display optics and rendering pipelines. VR developers in Sweden and the United States drive volume as foveated rendering becomes standard in immersive hardware.
- Mobile Trackers:Smartphone and tablet-embedded solutions leverage existing camera modules with software-based gaze estimation, sacrificing precision for ubiquity in consumer applications.
- Integrated Trackers:Automotive-grade systems merge infrared illuminators, image sensors, and processing units into dashboard-mounted driver monitoring assemblies, demanding ISO 26262 functional safety certification.
Remote trackers absorb the bulk of installed capacity in academic and marketing applications; wearable trackers are expanding most quickly through VR headset integration.
Technology:
Engineering talent concentration and component supply security differentiate technology tiers, with hybrid architectures commanding premium positioning by combining multiple sensing modalities.
- Infrared:Near-infrared illumination paired with high-sensitivity detectors enables sub-degree accuracy in low-light conditions, sustaining pricing power in research-grade deployments. Academic institutions in Germany and Sweden favor these systems for longitudinal behavioral studies requiring consistent calibration.
- Video-Based:Visible-light camera processing reduces hardware costs but struggles with variable illumination, finding traction in marketing and consumer applications where precision requirements relax.
- Electro-oculography:Skin electrode measurements of corneal-retinal potential differences serve niche medical diagnostics and sleep research, requiring specialized operator training.
- Optical:Emerging event-based sensors activate pixels asynchronously to achieve microsecond latency, attracting automotive Tier 1 suppliers for highway-speed drowsiness detection.
- Hybrid:Combined infrared and visible-light processing pipelines unify accuracy with environmental robustness, compressing bill-of-materials costs through single-chip integration.
Infrared systems dominate revenue concentration in research and premium automotive safety; hybrid architectures are gaining share fastest as suppliers consolidate multi-sensor designs.
Application:
Regulatory mandate timing and reimbursement pathways determine which applications can support premium pricing versus commodity hardware margins.
- Psychology Research:Controlled laboratory protocols demand sub-degree spatial accuracy and millisecond temporal resolution for fixation and saccade analysis. University departments in Germany and the United States sustain replacement cycles through grant-funded equipment upgrades.
- Automotive Safety:Euro NCAP distraction detection protocols and the EU General Safety Regulation mandate gaze-tracking integration for five-star safety ratings, compressing OEM procurement timelines.
- Marketing Analysis:Heat map generation and attention quantification for advertising effectiveness studies employ lower-precision remote trackers in commercial lab environments.
- Virtual Reality:Foveated rendering—displaying high resolution only at the gaze point—reduces GPU load and extends battery life in immersive headsets.
- Assistive Technology:Eye-controlled communication devices for motor-impaired users prioritize reliability and ease of calibration over research-grade precision.
Psychology research absorbs the bulk of legacy installed base; automotive safety is climbing the fastest as regulatory deadlines force OEM adoption.
End User:
Purchasing authority centralization versus departmental fragmentation shapes sales cycle length and service contract structure across customer types.
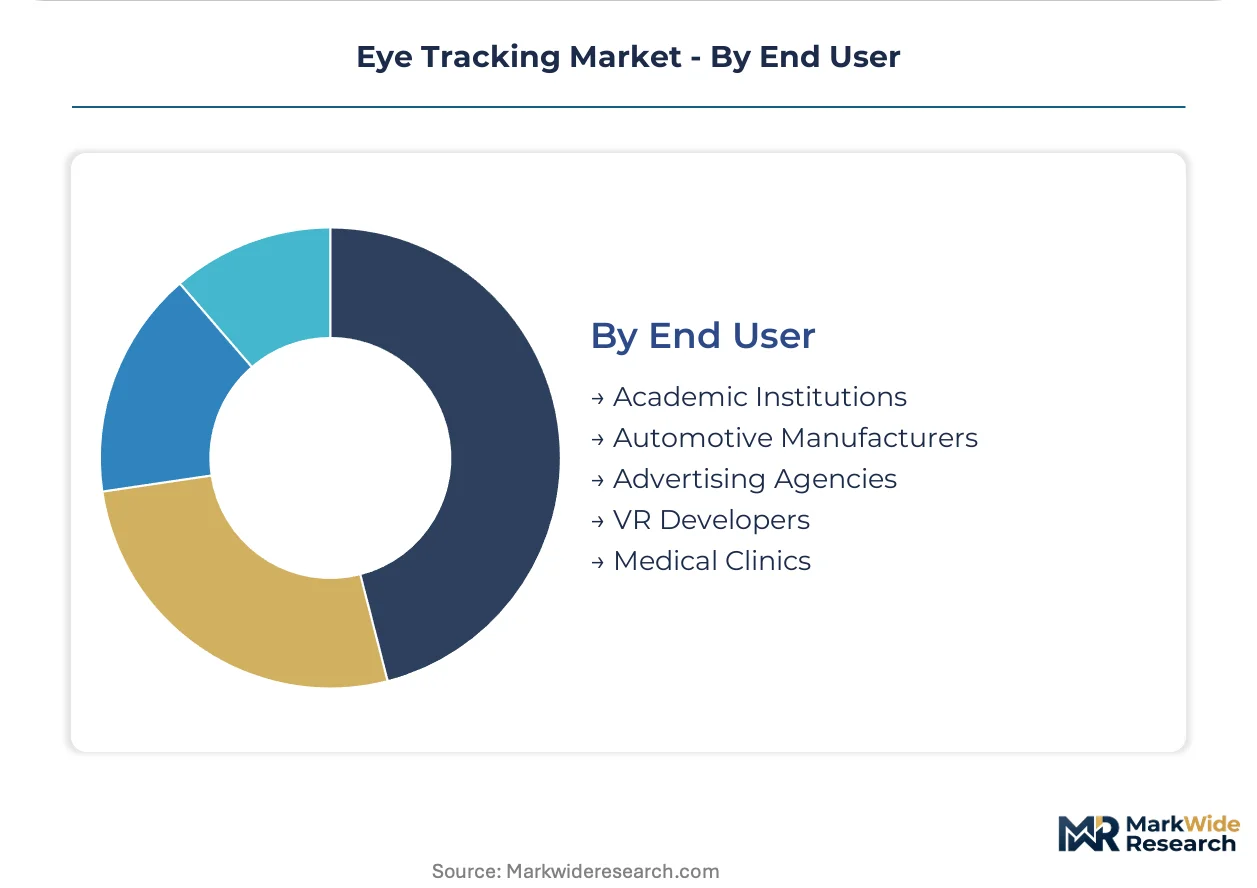
- Academic Institutions:University psychology, neuroscience, and marketing departments procure through centralized lab equipment budgets or distributed departmental purchasing, with Germany and the United States exhibiting fastest migration toward cloud-based analytics subscriptions.
- Automotive Manufacturers:OEM validation labs and Tier 1 suppliers demand certified systems meeting type-approval requirements across multiple regulatory regimes, with procurement concentrated in Germany and Sweden.
- Advertising Agencies:Consumer research divisions employ lower-cost remote trackers for copy testing and packaging optimization studies.
- VR Developers:Headset manufacturers integrate gaze estimation at the hardware design stage, creating captive demand for miniaturized optical assemblies.
- Medical Clinics:Neurological assessment protocols converge eye movement analytics with cognitive load measurement for early disease detection, facing extended qualification timelines.
Academic institutions retain the largest installed equipment base; automotive manufacturers are expanding procurement fastest as Euro NCAP deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European automotive validation activity where OEM labs stress-test driver monitoring systems against Euro NCAP protocols. University research clusters in Germany, Sweden, and the United States sustain replacement demand for sub-degree accuracy hardware. Regulatory mandate timing across these jurisdictions compresses procurement cycles unevenly.
United States
NHTSA guidance on advanced driver monitoring performance pushes Detroit-based OEM validation labs toward certified gaze-tracking partnerships. The FAA regulates pilot training simulation standards where crew resource management programs incorporate gaze-pattern analysis. Boston and San Francisco research corridors absorb federal grant funding for longitudinal behavioral studies requiring millisecond temporal resolution.
Germany
KBA type-approval requirements intersect with Euro NCAP five-star safety mandates to force Tier 1 supplier consolidation around ASIL-D certified systems. REACH restrictions on heavy metals in electronics are reformulating infrared illuminator assemblies across Bavarian and Baden-Württemberg supply chains. Munich and Stuttgart automotive clusters validate driver distraction detection algorithms at highway speeds.
Sweden
Stockholm's VR hardware developers integrate optical gaze estimation for foveated rendering in immersive headsets. The country's national pharmaceutical regulator oversees neurological assessment protocols converging eye movement analytics with cognitive load measurement. Linköping and Gothenburg university departments sustain replacement cycles through distributed departmental purchasing with cloud-based analytics subscriptions.
United Kingdom
GDPR Article 9 special category processing rules impose consent documentation burdens on London-based consumer-facing deployments. The Medicines and Healthcare products Regulatory Agency extends qualification timelines for medical device registrations involving biometric data collection. Cambridge and Oxford behavioral science departments upgrade legacy lab equipment through centralized research council budgets.
Japan
METI standards for human-machine interface safety guide Tokyo automotive suppliers toward hybrid infrared-visible processing architectures. PMDA oversight of neurological diagnostic devices shapes Yokohama medical clinic procurement for early disease detection protocols. Osaka and Nagoya electronics manufacturers compress bill-of-materials costs through single-chip sensor integration.
Eye Tracking Market Key Industry Players
Premium-margin players sit above commodity-margin players across calibration IP and regulatory certification dimensions. The supplier base organizes into three tiers: research-grade precision hardware specialists, automotive safety system integrators, and VR-embedded optical assembly providers. Consolidation pressure concentrates among automotive Tier 1 suppliers seeking ASIL-D ratings, while research equipment segments defend fragmentation through proprietary algorithms. Dominant competitive moves include technology licensing for foveated rendering pipelines and backward integration into infrared sensor fabrication.
Within the research-grade precision tier, Tobii AB and SR Research Ltd. exemplify proprietary calibration IP defenders. Seeing Machines occupies a position representing automotive safety certification breadth across multiple type-approval regimes. Smart Eye AB sits within the hybrid architecture segment combining infrared accuracy with visible-light environmental robustness. These three anchors illustrate how geographic clustering—Swedish, Canadian, and Swedish-Australian respectively—aligns with distinct regulatory validation pathways rather than manufacturing scale.
| Leading Market Players |
|---|
| Tobii AB |
| Seeing Machines |
| Smart Eye AB |
| SR Research Ltd. |
| EyeTech Digital Systems |
| EyeTracking, Inc. |
| Ergoneers GmbH |
| iMotions |
| Pupil Labs GmbH |
| Others |
Cost & Logistics Intelligence
ASIL-D certification tier divergence separates premium automotive driver monitoring systems from commodity research hardware, concentrating pricing power with validated Tier 1 suppliers while supply chains fragment across German automotive clusters and East Asian sensor foundries. Euro NCAP compliance deadlines compress procurement timelines for certified systems, forcing OEMs toward pre-qualified suppliers with locked-in illuminator and detector sourcing agreements.
Pricing Analysis
Value-based pricing anchored to regulatory certification outcomes dominates automotive deployments, with ASIL-D rated systems commanding substantial premiums over research-grade alternatives. Price differentiation rests on ISO 26262 functional safety tier and calibration IP exclusivity. Cost compression in the remote tracker segment intensifies as cloud-based subscription models displace capital-intensive hardware ownership. Academic institutions exhibit highest price sensitivity, while automotive OEMs prioritize certification breadth over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with indium gallium arsenide near-infrared detector fabrication concentrated in Taiwan, South Korea, and Japan. Raw material dependencies include gallium arsenide emitters, specialized optical glass, and high-speed image sensors. REACH restrictions on heavy metals in European electronics impose regulatory risk across illuminator component sourcing. Distribution runs through direct OEM partnerships for automotive systems and academic lab equipment distributors for research hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Event-based sensor technology is displacing legacy frame-based architectures, compressing latency benchmarks from milliseconds to microseconds and reshaping competitive positioning across automotive safety and VR rendering applications.
For Market Incumbents: Anticipate margin compression in the remote tracker segment as per-study licensing models displace hardware sales, and defend position through backward integration into infrared sensor fabrication and exclusive calibration algorithm IP. Prioritize ASIL-D certification investment to lock in automotive procurement cycles before Euro NCAP deadlines consolidate supplier relationships. For New Entrants and Emerging Players: Optical gaze estimation modules for foveated rendering represent the most penetrable wedge, targeting Swedish and United States VR headset manufacturers with miniaturized assemblies that integrate directly into display pipelines. Pursue aviation pilot training simulation contracts as an underpenetrated vertical with extended qualification timelines that favor agile engineering teams. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid architecture specialists given convergence of automotive safety mandates and VR hardware integration demand. Long-term viability favors suppliers with cross-domain certification capabilities spanning ISO 26262, medical device registration, and aviation safety assessment. Watch for Tier 1 automotive supplier consolidation announcements as inflection indicators for premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Event-Based Sensor Integration | Microsecond latency enables highway-speed drowsiness detection for Euro NCAP compliance. |
| ASIL-D Certification Investment | Functional safety rating unlocks premium automotive procurement and OEM validation partnerships. |
| Backward Integration into Infrared Emitters | Captive gallium arsenide supply secures margin against foundry capacity constraints. |
| Foveated Rendering Module Development | GPU load reduction extends battery life in Swedish and United States VR headsets. |
| Cloud-Based Analytics Platform Launch | Per-study licensing captures German and United States academic departmental purchasing migration. |
Research Approach
Multi-period observation of Euro NCAP protocol evolution, VR headset shipment volumes, and academic procurement patterns anchored the trend analysis, supplemented by interviews with automotive Tier 1 supplier procurement leads, OEM platform engineers, university lab equipment managers, and VR hardware integration specialists. Secondary validation drew from KBA type-approval databases, NHTSA guidance documents, REACH regulatory filings, and SEC disclosures of listed component suppliers. Bottom-up equipment unit estimates and top-down market sizing triangulated volume figures.
Input-output matrix modeling connected sensor component supply, certification timeline constraints, and end-use demand across product type, technology, application, and end-user dimensions. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs included Euro NCAP five-star rating adoption curves and foveated rendering penetration in immersive hardware.
Several conditions sit outside the modeled scope, including geopolitical disruptions to East Asian semiconductor foundry operations and unannounced regulatory amendments to GDPR biometric processing frameworks. Forecasts reflect documented assumptions about certification timeline adherence and component cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Global Tunnel Monitoring System Market
Sensors
Asia Pacific Container Monitoring Market
Sensors
GNSS-Enabled Consumer Device Market
Sensors
Yield Monitoring Systems Market
Sensors
Lidar in Mapping Market
Sensors
Robot Sensor Market
Sensors
Wireless Occupancy Sensors Market
Sensors
Bluetooth Photo Capture Device Market
Sensors
Global Weather Monitoring Solutions and Services Market
Sensors
Micro Location Technology Market
Sensors
Residential Water Leak Detection System Market
Sensors
Indoor Air Quality Monitor Market
Sensors
Personal Navigation Devices Market
Sensors
Weigh-In-Motion System Market
Sensors
Global Real-Time Locating Systems (RTLS) Market
Sensors
Temperature Data Loggers Market