
 Digital Direction Finder Market | 2026-2036
Digital Direction Finder Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Direction Finder Market Insights
The capital-intensity divergence between full-spectrum defense contractors and specialized RF component suppliers is unwinding competitive stability in the digital direction finder landscape. Rohde & Schwarz leverages its in-house semiconductor fabrication to sustain pricing power across European defense tenders. Thales Group anchors its position through deep integration with French military procurement channels. L3Harris Technologies competes aggressively in North American electronic warfare upgrades by controlling classified program access.
A digital direction finder is an electronic instrument that determines the azimuth or bearing of a radio-frequency emitter using amplitude comparison, phase interferometry, or time-difference-of-arrival techniques, typically operating across VHF through SHF bands for precision emitter location. Its primary purpose spans military electronic support measures, spectrum enforcement, and emergency services geolocation. Integrated Systems command the dominant share of defense budgets due to their multi-sensor fusion architectures and hardened packaging for platform deployment. Software Solutions represent the fastest-expanding category as algorithmic beamforming and machine-learning signal classification displace legacy hardware-defined processing. Embedded Units concentrate margin pools in automotive and drone navigation where SWaP constraints drive premium pricing for miniaturized RF front-ends.
The FCC enforces Part 15 and Part 90 equipment authorization standards that constrain civilian direction finder spurious emissions and measurement uncertainty. ETSI harmonizes European spectrum monitoring equipment specifications under EN 303 413, shaping cross-border procurement interoperability for national regulatory authorities. Military end users navigate ITAR and EU dual-use export controls that segment supplier access between allied defense programs. Stakeholders must monitor whether emerging autonomous vehicle mandates in Germany and Japan will extend direction-finding accuracy requirements from defense into commercial certification regimes.
Market Dynamics
Defense procurement agencies are consolidating supplier relationships around integrated electronic warfare platforms, compressing the addressable market for standalone digital direction finder modules while elevating systems-level contract values.
Growth Catalysts
- ITAR modernization:Streamlined export licensing for allied defense programs accelerates cross-border deployment of classified direction-finding architectures between NATO member states.
- Machine-learning signal classification:Algorithmic processing is displacing hardware-defined beamforming, reducing unit costs while improving emitter identification accuracy in contested spectrum environments.
- German automotive autonomy mandates:KBA certification requirements for vehicle-to-everything communication are extending precision direction-finding specifications into commercial transportation platforms.
Market Restraints
- GaN substrate supply concentration:RF front-end fabrication depends on captive gallium nitride wafer supply from a limited set of semiconductor foundries, exposing procurement timelines to single-source fragility.
- EU dual-use export controls:EN 303 413 harmonization creates compliance friction for non-European suppliers seeking access to national spectrum monitoring tenders across member states.
- SWaP constraints in unmanned platforms:Size, weight, and power limitations in tactical drones restrict antenna aperture dimensions, degrading angular resolution below military operational thresholds.
Strategic Opportunities
- Japan METI spectrum efficiency targets:National 5G spectrum repurposing mandates create demand for high-density emitter monitoring networks in dense urban deployments.
- Convergence of direction finding with software-defined radio:Unified RF processing architectures enable civilian test equipment vendors to enter defense-adjacent markets through dual-use certification pathways.
- Emergency services geolocation mandates:FCC Part 90 location accuracy requirements for public safety narrowband systems are expanding addressable volume in municipal procurement channels.
Industry Challenges
- Phase-coherent multi-channel calibration:Maintaining interferometric precision across temperature and vibration excursions demands specialized metrology expertise scarce in commercial RF engineering labor pools.
- Platform integration complexity:Hardened packaging for airborne and naval deployments requires concurrent thermal, electromagnetic, and mechanical design validation cycles that extend program timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Direction Finder Market |
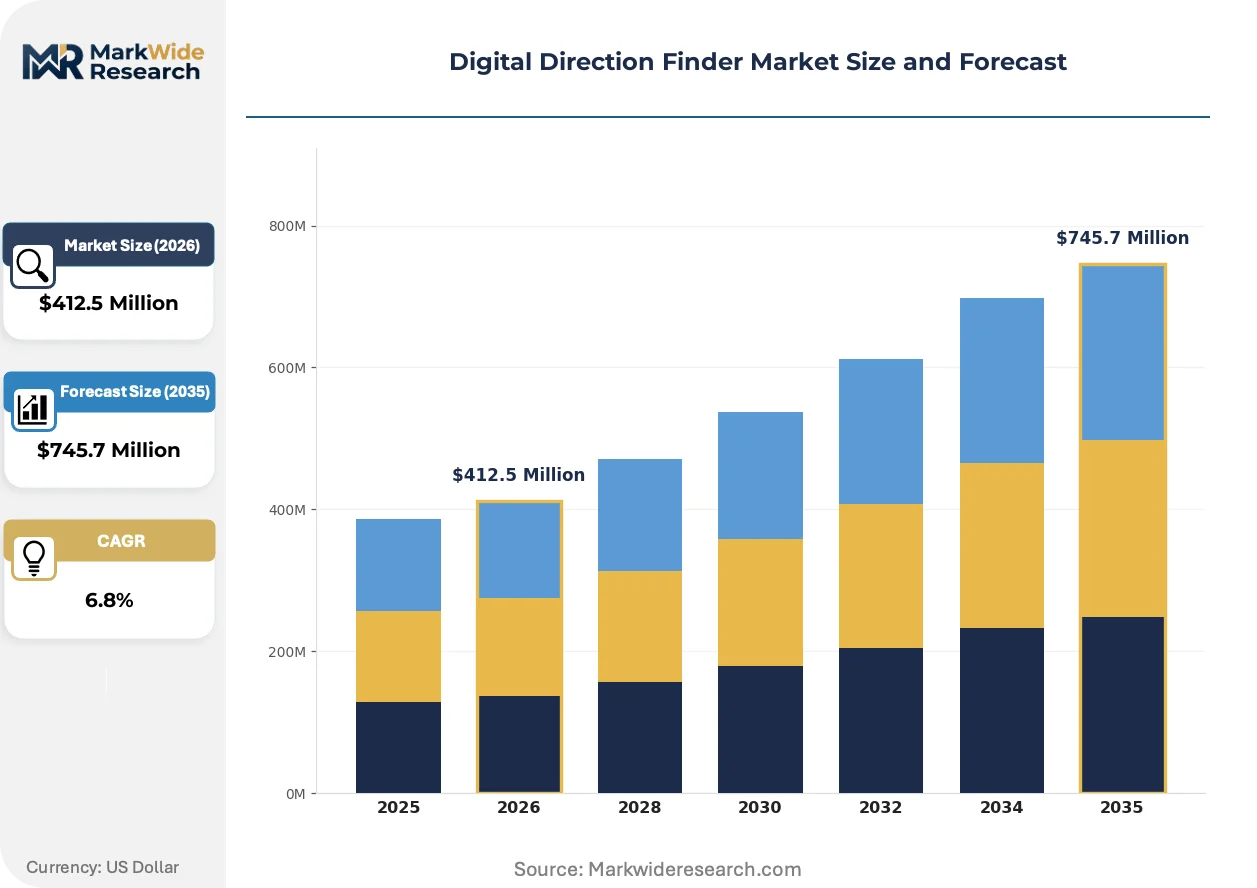
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Devices, Integrated Systems, Software Solutions, Embedded Units End User: Aerospace, Marine, Automotive, Consumer Electronics Technology: GPS, Inertial Navigation, Visual Recognition, Magnetic Field Application: Wayfinding, Fleet Management, Autonomous Vehicles, Drone Navigation |
| Companies Covered | Rohde & Schwarz, Thales Group, L3Harris Technologies, Honeywell International, Rockwell Collins, Northrop Grumman Corporation, BAE Systems, Raytheon Technologies Corporation, Navtech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Direction Finder Market Trends and Innovations
Algorithmic processing architectures are compressing the boundary between hardware-defined and software-defined direction finding, while regulatory mandates in transportation and public safety sectors extend military-derived specifications into civilian certification regimes.
Silicon-germanium BiCMOS front-end integration is miniaturizing. Automotive radar semiconductor suppliers are repurposing millimeter-wave transceiver dies for compact direction-finding modules in drone navigation systems. This convergence is compressing bill-of-material costs for sub-6 GHz arrays while degrading traditional defense contractor margin structures in volume segments.
ETSI EN 303 413 harmonization is tightening measurement uncertainty specifications for European spectrum monitoring equipment. National regulatory authorities in Germany, France, and Italy now require cross-border interoperability certification, forcing suppliers to standardize calibration protocols. Test equipment vendors are responding with modular architectures that separate RF acquisition from processing to satisfy multi-jurisdiction deployment requirements.
Defense procurement consolidation around prime contractors is displacing standalone subsystem purchases. Electronic warfare platform integrators now bundle direction finding with electronic attack and signals intelligence functions under single contract vehicles. This pattern concentrates supplier relationships in the US, UK, and French military procurement channels while marginalizing specialized component vendors without systems integration credentials.
Digital Direction Finder Market Segmentation
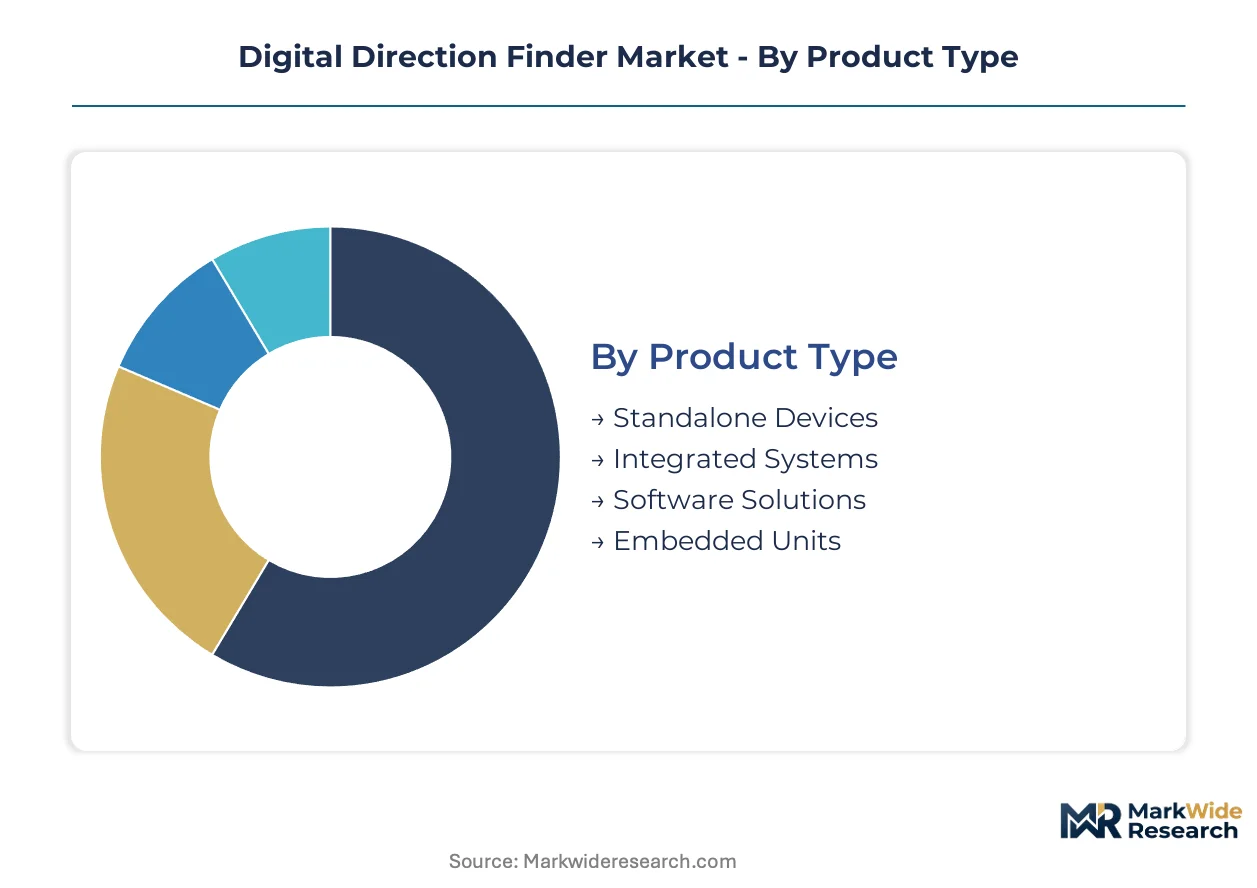
Direction-finding architectures fragment across hardware density, deployment platform, and processing location. Procurement patterns diverge sharply between defense systems requiring hardened packaging and commercial applications prioritizing algorithmic flexibility.
Product Type:
Integrated Systems and Embedded Units concentrate in domestic European defense manufacturing, while Standalone Devices and Software Solutions export to allied NATO procurement channels under streamlined ITAR licensing.
- Integrated Systems:Multi-sensor fusion architectures combine interferometric antennas with hardened signal processors in platform-deployable enclosures. German and French military procurement channels anchor demand, driven by electronic warfare platform modernization mandates.
- Software Solutions:Algorithmic beamforming and machine-learning signal classification modules displace legacy hardware-defined processing. North American spectrum enforcement agencies and Japanese 5G monitoring networks drive cross-border licensing volumes.
- Standalone Devices:Portable RF direction-finding equipment serves municipal emergency services and spectrum regulatory authorities.
- Embedded Units:Miniaturized front-ends integrate into automotive radar and drone navigation systems where SWaP constraints command premium positioning.
Integrated Systems command the established base. The steepest expansion runs through Software Solutions.
End User:
Aerospace and Marine applications stratify by certification tier, with Automotive and Consumer Electronics segments compressing procurement cycles through volume manufacturing economics.
- Aerospace:Airborne electronic support measures demand phase-coherent multi-channel arrays with thermal and vibration hardening. US and UK defense procurement channels concentrate platform integration contracts, constrained by ITAR export licensing requirements.
- Automotive:Vehicle-to-everything communication systems require compact direction-finding modules for collision avoidance. German KBA certification mandates and Japanese METI spectrum efficiency targets are extending precision specifications into commercial transportation platforms.
- Marine:Naval electronic warfare suites integrate direction finding with signals intelligence functions for emitter location at sea.
- Consumer Electronics:Smartphone and wearable navigation applications drive cost-down pressure on compact magnetic and inertial sensors.
Aerospace absorbs the dominant contract value. Automotive is climbing the fastest as autonomy mandates proliferate.
Technology:
GPS augmentation dominates civilian volume, while Inertial Navigation and Magnetic Field sensing concentrate in defense applications requiring jam-resistant positioning.
- GPS:Satellite-based positioning integrated with direction-finding algorithms for consumer and fleet applications. FCC Part 90 location accuracy mandates for public safety narrowband systems are expanding municipal procurement volumes.
- Inertial Navigation:Self-contained gyroscopic and accelerometric tracking independent of external signals. Military platforms in contested electromagnetic environments prioritize this technology for operational continuity.
- Visual Recognition:Camera-based orientation systems supplement RF direction finding in urban canyon environments.
- Magnetic Field:Compass-based azimuth determination serves low-cost consumer navigation and backup orientation functions.
GPS maintains the volume base. Inertial Navigation is gaining share fastest in defense procurement consolidation.
Application:
Wayfinding and Fleet Management concentrate in commercial logistics, while Autonomous Vehicles and Drone Navigation segments absorb premium pricing for safety-critical certification.
- Autonomous Vehicles:Precision emitter location enables vehicle-to-everything communication integrity in dense urban spectrum environments. German automotive regulatory mandates and Japanese 5G deployment timelines are synchronizing certification requirements across export markets.
- Drone Navigation:Miniaturized direction-finding modules support beyond-visual-line-of-sight operations. SWaP constraints in tactical unmanned platforms restrict antenna aperture dimensions, degrading angular resolution below operational thresholds in contested applications.
- Wayfinding:Indoor and outdoor pedestrian navigation systems integrate multi-technology positioning for consumer applications.
- Fleet Management:Commercial vehicle tracking and routing optimization drives high-volume, cost-sensitive module procurement.
Fleet Management commands the installed base. Autonomous Vehicles represents the fastest-growing trajectory as regulatory mandates extend military-derived specifications into commercial certification regimes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers command pricing premiums through captive semiconductor fabrication, while US defense contractors extract value through classified program access. This asymmetry shapes procurement patterns across NATO procurement channels and allied defense programs.
United States
Electronic warfare platform modernization drives procurement consolidation around prime contractors. FCC Part 15 and Part 90 equipment authorization standards constrain civilian direction finder spurious emissions. Greater Boston and Washington DC metropolitan clusters concentrate signals intelligence R&D facilities serving classified defense programs.
Germany
KBA certification requirements for vehicle-to-everything communication extend precision direction-finding specifications into commercial transportation. ETSI EN 303 413 harmonization shapes cross-border procurement interoperability for national regulatory authorities. Bavaria and Baden-Württemberg anchor substantial manufacturing footprints for integrated electronic warfare systems.
France
Deep integration with military procurement channels sustains domestic supplier relationships for hardened platform deployments. EU dual-use export controls segment supplier access between allied defense programs. The Île-de-France region concentrates prime contractor headquarters and systems integration capabilities.
Japan
METI spectrum efficiency targets create demand for high-density emitter monitoring networks in dense urban 5G deployments. National spectrum repurposing mandates synchronize certification requirements across export markets. The Kanto region around Tokyo hosts precision RF component manufacturing clusters.
United Kingdom
Airborne electronic support measures demand phase-coherent multi-channel arrays with thermal and vibration hardening. ITAR export licensing requirements constrain cross-border deployment of classified architectures. The Southeast and Midlands regions concentrate defense electronics manufacturing and platform integration facilities.
Digital Direction Finder Market Competitive Landscape
Concentration sits with full-spectrum defense contractors possessing systems integration credentials and captive semiconductor supply. The vendor base stratifies across three tiers: prime contractors bundling direction finding with electronic attack functions, specialized RF component suppliers with metrology expertise, and automotive semiconductor repurposers entering volume segments. Strategic moves center on M&A to acquire algorithmic beamforming capabilities and capacity expansion in gallium nitride wafer fabrication.
Within the prime contractor tier, Rohde & Schwarz and Thales Group exemplify divergent geographic anchoring strategies. Rohde & Schwarz represents the European defense electronics archetype with in-house semiconductor fabrication sustaining pricing power across continental tenders. Thales Group occupies a parallel position through deep French military procurement integration. L3Harris Technologies anchors the North American competitive vector, competing aggressively in electronic warfare upgrades through classified program access.
| Leading Market Players |
|---|
| Rohde & Schwarz |
| Thales Group |
| L3Harris Technologies |
| Honeywell International |
| Rockwell Collins |
| Northrop Grumman Corporation |
| BAE Systems |
| Raytheon Technologies Corporation |
| Navtech |
| Others |
Pricing and Supply Chain Analysis
Wafer-scale economies in gallium nitride substrate production concentrate pricing power among captive semiconductor foundries, compressing margin structures for non-integrated RF component vendors while elevating floor prices for precision direction-finding modules. This scale asymmetry feeds directly into procurement timelines, as defense contractors with in-house fabrication sustain configured-to-order premiums unavailable to fabless competitors.
Pricing Analysis
Configured-to-order pricing for hardened military-grade systems commands spreads exceeding standard commercial units by certification tier and thermal-hardening requirements. Project-based contracting dominates defense procurement, with price differentiation driven by ITAR compliance overhead and antenna aperture customization. Cost compression in automotive-derivative embedded units is intensifying because automotive radar semiconductor suppliers are repurposing millimeter-wave dies for drone navigation, degrading traditional defense contractor margins. Municipal emergency services exhibit highest price sensitivity due to constrained public safety budgets, while aerospace electronic warfare platforms demonstrate lowest sensitivity given operational-critical specifications.
Supply Chain Analysis
Germany and the United States anchor integrated systems manufacturing, while Taiwan and South Korea feed RF front-end wafer supply. Raw material dependencies center on gallium nitride substrates, high-frequency laminates, and precision-machined antenna elements. Single-source vulnerability in GaN wafer fabrication exposes procurement timelines to foundry capacity allocation decisions. Distribution runs through prime contractor channel partnerships for defense applications, with direct OEM supply agreements dominating automotive and drone navigation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine-learning signal classification is compressing hardware-defined processing margins, creating high-growth disruption as algorithmic beamforming displaces legacy architectures. FCC Part 90 and ETSI EN 303 413 harmonization are extending military-derived specifications into civilian certification regimes, amplifying addressable market expansion.
For Market Incumbents: Compound defensive positioning through captive gallium nitride wafer capacity expansion and deepened integration with NATO electronic warfare platform modernization programs. Acquire algorithmic beamforming specialists to offset margin erosion from software-defined radio convergence. Prioritize ITAR-compliant channel control against emerging automotive semiconductor repurposers.
For New Entrants and Emerging Players: Differentiate on modular RF acquisition architectures that separate hardware from processing to satisfy multi-jurisdiction ETSI certification requirements. Target Japanese METI spectrum efficiency mandates for high-density 5G emitter monitoring networks. Pursue dual-use certification pathways through software-defined radio convergence to access defense-adjacent procurement channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software solutions providers with algorithmic signal classification subscriptions. Long-term viability over the next decade favors vendors with metrology expertise in phase-coherent multi-channel calibration. Watch for GaN substrate supply consolidation signals as inflection indicators for procurement timeline risk and pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Algorithmic Beamforming Specialist | Machine-learning signal classification displaces legacy hardware-defined processing in contested spectrum environments. |
| GaN Wafer Fabrication Capacity Expansion | Captive substrate supply insulates procurement timelines from single-source foundry fragility. |
| Dual-Use Certification Pathway Development | ETSI EN 303 413 harmonization enables cross-border procurement interoperability for regulatory authorities. |
| Modular RF-Processing Architecture Launch | Separable acquisition and processing modules satisfy multi-jurisdiction deployment requirements. |
| Prime Contractor Channel Partnership | Electronic warfare platform bundling concentrates supplier relationships in US, UK, and French military procurement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense procurement officers, RF systems engineers, spectrum regulatory authorities, and automotive platform integration leads. Secondary validation drew from FCC equipment authorization databases, ETSI harmonization standards, NATO electronic warfare procurement disclosures, and semiconductor foundry capacity reports. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Across the analysis window, value and volume outputs were modeled through multi-dimensional segmentation spanning product architecture, deployment platform, processing location, and end-use certification tier. CAGRs were derived from trend extrapolation of procurement cycle data and technology substitution curves. Forecast inputs incorporated machine-learning adoption rates in signal classification and GaN substrate supply elasticity assumptions.
Material uncertainties — ITAR licensing delays, GaN wafer supply disruptions, and autonomous vehicle mandate timing — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization continuity and defense procurement consolidation patterns. Recalibration cycles align with material shifts in spectrum management policy and electronic warfare platform modernization schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Body Area Network Market
Sensors
Industrial Automation Sensors Market
Sensors
Underground Service Locator Market
Sensors
Yield Monitoring Systems Market
Sensors
Consumer 3D Sensing Products Market
Sensors
Lidar in Mapping Market
Sensors
Heat Stress Meter Market
Sensors
Surface Haptic Technology Market
Sensors
Wireless Synchronized Clocks Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Telemetric Devices Market
Sensors
Cloud Camera Market
Sensors
Beacon Market
Sensors
Robot Sensor Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Low Power Geolocation Market