
 APAC Wireless Sensors Market | 2026-2036
APAC Wireless Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Wireless Sensors Market Outlook
Smart manufacturing is expanding its share of total wireless sensor procurement across APAC, displacing traditional building automation as the dominant vertical. Honeywell International Inc leverages its distributed control heritage to anchor large-scale refinery sensor networks in Southeast Asia. Texas Instruments Incorporated competes on integrated radio-plus-sensor silicon that shrinks module footprint for original equipment manufacturers. Yokogawa Electric Corporation dominates process-industry wireless instrumentation through ISA100.11a-certified field devices.
Wireless sensors are self-contained measurement nodes that transmit digitized physical parameters—temperature, pressure, proximity, humidity—across unlicensed spectrum bands without hardwired power or data connections, typically operating on coin-cell batteries for multi-year lifespans and communicating via Bluetooth, Zigbee, Wi-Fi, or LoRaWAN protocols depending on range and latency requirements. Temperature sensors lead product-type revenue due to pervasive deployment in cold-chain logistics and semiconductor fabrication, while LoRaWAN technology captures the fastest expansion trajectory as utility-scale smart-metering rollouts in Australia and South Korea favor its sub-gigahertz penetration through dense urban infrastructure. Industrial automation remains the most mature application segment with established specification benchmarks, whereas healthcare monitoring holds concentrated margin pools where FDA-equivalent national regulators enforce clinical-grade wireless reliability standards.
Japan's METI enforces radio-law certification for 920 MHz band devices, China's MIIT governs SRRC type-approval for short-range wireless modules, and Australia's ACMA regulates spectrum allocation for unlicensed sensor networks—collectively shaping product design cycles and market access timelines across the region. India's WPC import licensing for radio-frequency equipment adds procedural friction that favors domestic assembly partnerships. Stakeholders must monitor evolving national cybersecurity mandates for IoT endpoints as these rules increasingly determine procurement eligibility in government-funded infrastructure programs.
Market Dynamics
Smart factory deployments across China are compressing sensor replacement cycles from five-year to two-year intervals as assembly-line digitization accelerates. METI's radio-law certification requirements for 920 MHz band devices in Japan are simultaneously lengthening product design cycles, creating a structural tension between rapid deployment demands and compliance timelines.
Growth Catalysts
- MIIT SRRC type-approval streamlining:China's Ministry of Industry and Information Technology has accelerated short-range wireless module certification, reducing market access timelines for industrial sensor vendors targeting smart manufacturing facilities.
- Soil-moisture monitoring nodes:India's precision agriculture sector is replacing manual field monitoring with LoRaWAN-enabled wireless sensors, driven by water conservation mandates and crop yield optimization programs.
- ISA100.11a field instrumentation:Process industries across Southeast Asia are standardizing on this wireless protocol for refinery and petrochemical sensor networks, ensuring interoperability between competing vendor equipment.
Market Restraints
- Coin-cell battery supply concentration:Lithium manganese dioxide cell production clusters in East Asia, exposing sensor manufacturers to raw material price volatility and single-source dependency risks.
- WPC import licensing friction:India's Wireless Planning and Coordination Wing imposes procedural delays on radio-frequency equipment imports, favoring domestic assembly partnerships over direct foreign supply.
- Sub-gigahertz spectrum congestion:Dense urban deployments in Australian and South Korean utility metering are encountering interference limits that constrain node density per square kilometer.
Strategic Opportunities
- Vietnam electronics manufacturing expansion:Sensor module assembly is migrating to northern Vietnamese industrial zones to bypass tariff exposure and access ASEAN trade preferences.
- Bluetooth-Zigbee protocol convergence:Silicon vendors are integrating dual-radio architectures that allow single-chip solutions to serve both consumer and industrial latency requirements.
- Australia ACMA spectrum allocation:Unlicensed sensor network bandwidth expansion in the 915 MHz band is enabling utility-scale smart metering rollouts with improved urban penetration characteristics.
Industry Challenges
- Embedded RF engineering talent scarcity:Multi-year battery lifespan requirements demand specialized antenna design and power-management expertise that concentrates in Japanese and Taiwanese engineering pools.
- Cybersecurity certification complexity:Evolving national IoT endpoint security mandates for government-funded infrastructure programs are fragmenting procurement eligibility criteria across APAC jurisdictions.
- Legacy wired system integration:Brownfield industrial facilities require protocol translation gateways that add cost and latency to wireless sensor deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Wireless Sensors Market |
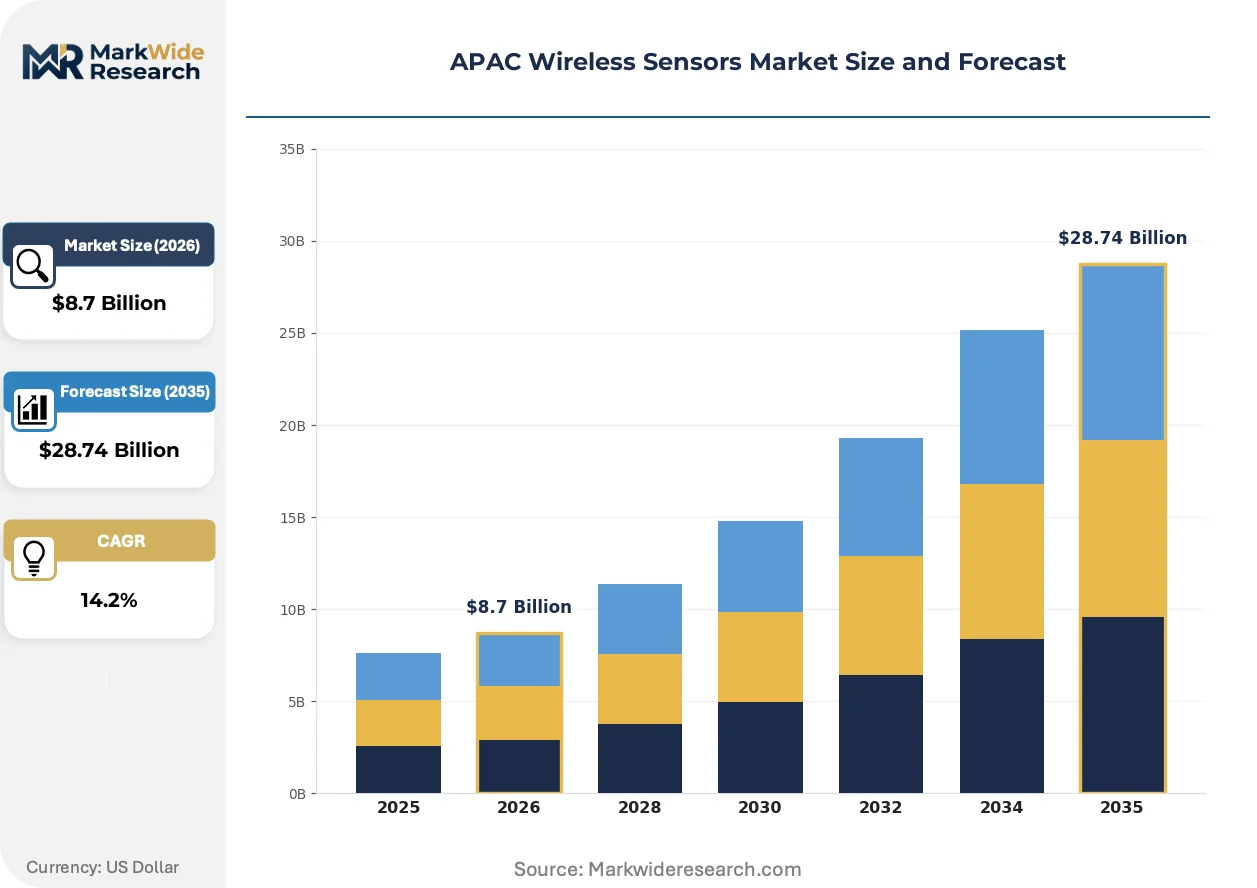
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
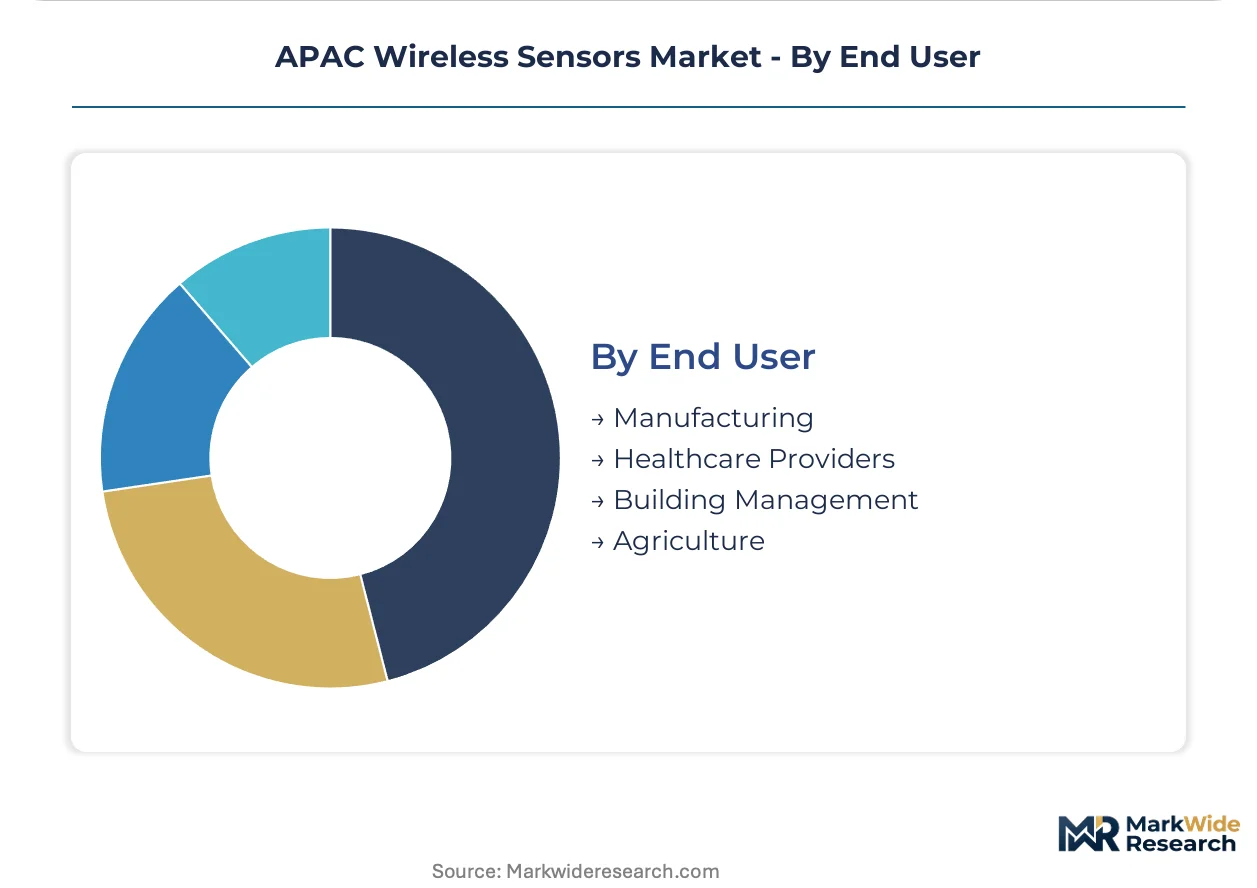
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Humidity Sensors Technology: Bluetooth, Zigbee, Wi-Fi, LoRaWAN Application: Industrial Automation, Smart Homes, Healthcare Monitoring, Environmental Monitoring End User: Manufacturing, Healthcare Providers, Building Management, Agriculture |
| Companies Covered | Emerson Electric Co, STMicroelectronics, Honeywell International Inc, Rockwell Automation Inc, Texas Instruments Incorporated, ABB Ltd, Siemens AG, Yokogawa Electric Corporation, Schneider Electric SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Wireless Sensors Market Strategic Shifts
Silicon integration and protocol standardization are compressing module footprints while expanding functional density. These shifts are reconfiguring competitive advantage away from discrete component sourcing toward firmware-defined sensor platforms.
Energy-harvesting micro-generators are absorbing ambient vibration and thermal differentials to supplement coin-cell power in industrial sensor nodes. Semiconductor fabs in South Korea are piloting piezoelectric harvesters for equipment-monitoring applications. This technology is absorbing maintenance-cycle compression by eliminating battery replacement labor from high-density deployments.
METI's Society 5.0 framework is mandating edge-device interoperability standards that harmonize previously fragmented Japanese IoT ecosystems. Industrial automation vendors must now certify against unified data-exchange protocols to qualify for public infrastructure tenders. Process-control sensor manufacturers are responding by pre-integrating ISA100.11a and WirelessHART stacks into single firmware images.
Hospital procurement committees are unbundling wireless sensor hardware from clinical software subscriptions, reversing decade-long bundled-service conventions. Medical device distributors in Australia and Japan are pivoting toward sensor-as-component sales models that separate FDA-equivalent regulatory liability from IT integration responsibility. This pattern is most visible in aged-care monitoring deployments where facility operators prefer direct hardware ownership with third-party platform integration.
APAC Wireless Sensors Market Segmentation

Wireless sensor procurement patterns across APAC diverge sharply by product specification, connectivity protocol, and deployment environment. Upgrade cycles and replacement timelines vary from two years in Chinese smart factories to five-plus years in Australian building automation, creating tiered demand profiles that vendors must navigate.
Product Type:
Replacement-cycle compression in industrial settings favors sensors with standardized form factors and backward-compatible interfaces, reducing facility downtime during swap-outs.
- Temperature Sensors:These units dominate cold-chain logistics networks across Australia and semiconductor cleanrooms in South Korea. Assembly lines in China's Yangtze River Delta are replacing thermocouple wired systems with wireless nodes that transmit per-second readings to distributed control systems, driven by food safety mandates and wafer yield optimization programs.
- Pressure Sensors:Deployed extensively across Southeast Asian refinery complexes and Japanese chemical processing plants. METI's process safety regulations mandate redundant pressure monitoring on high-risk vessels, creating dual-sensor procurement patterns where wireless units serve as primary or backup measurement channels depending on facility risk classification.
- Proximity Sensors:Compact inductive and capacitive variants enable collision-avoidance on automated guided vehicles in Vietnamese electronics assembly plants.
- Humidity Sensors:Critical for pharmaceutical storage compliance in India's cold-chain expansion and Singapore's precision manufacturing environments.
Volume placements concentrate in temperature sensors; the faster expansion belongs to pressure sensors as process-industry wireless instrumentation accelerates.
Technology:
Cost-tier differentiation separates high-bandwidth protocols for video-rich applications from ultra-low-power options for battery-constrained field deployments.
- Bluetooth:Short-range, low-latency connectivity dominates consumer wearables and clinical patient monitors in Japanese hospitals. South Korean smartphone ecosystem vendors are integrating Bluetooth sensor hubs into industrial tablets, creating hybrid consumer-industrial procurement channels that blur traditional vertical boundaries.
- LoRaWAN:Sub-gigahertz penetration enables utility-scale smart metering across Australian dense urban corridors and Indian agricultural moisture monitoring. Australia's ACMA spectrum allocation for 915 MHz unlicensed bands supports kilometer-range transmission through concrete infrastructure, favoring this protocol for basement-to-pentagon building automation.
- Zigbee:Mesh networking resilience serves Korean smart home ecosystems and Singapore's building management retrofits.
- Wi-Fi:High-throughput requirements concentrate in South Korean factory video analytics and Japanese healthcare imaging sensor backhaul.
Wi-Fi captures the highest unit volumes in manufacturing; LoRaWAN is climbing the fastest as utility infrastructure scales.
Application:
Customer-type segmentation separates specification-driven industrial procurement from price-sensitive consumer deployments, with margin pools concentrating where regulatory certification raises competitive barriers.
- Industrial Automation:Mature specification benchmarks from ISA100.11a and WirelessHART govern refinery, petrochemical, and automotive assembly applications. Yokogawa Electric and Honeywell anchor large-scale deployments across Southeast Asia with field-proven interoperability, while Chinese state-owned enterprises are accelerating domestic vendor qualification to reduce foreign technology dependency.
- Healthcare Monitoring:Concentrated margin pools attract specialized engineering investment where FDA-equivalent national regulators enforce clinical-grade wireless reliability. Australian aged-care facilities and Japanese hospital networks are unbundling sensor hardware from software subscriptions, shifting procurement toward component-level purchasing with third-party platform integration.
- Smart Homes:Price-competitive mass-market channel serving ASEAN middle-class housing developments and Korean apartment complexes.
- Environmental Monitoring:Government-funded air quality and water quality networks in Indian metropolitan regions and Chinese industrial zones.
Industrial automation holds the largest installed base; healthcare monitoring is gaining share fastest on regulatory-premium pricing.
End User:
Supply concentration in East Asian battery and silicon production shapes vendor accessibility across user segments with varying technical sophistication and procurement scale.
- Manufacturing:Smart factory deployments across China's Pearl River Delta and Yangtze River Delta are compressing sensor replacement cycles from five-year to two-year intervals. MIIT SRRC type-approval streamlining has reduced market access timelines for industrial sensor vendors, accelerating procurement velocity for assembly-line digitization programs.
- Agriculture:India's precision agriculture sector is replacing manual field monitoring with LoRaWAN-enabled wireless sensors, driven by water conservation mandates from state-level agricultural departments and crop yield optimization programs targeting export-market compliance. Soil-moisture nodes are penetrating Maharashtra and Punjab farming cooperatives fastest.
- Healthcare Providers:Hospital procurement committees in Tokyo, Osaka, Sydney, and Melbourne are rewriting vendor qualification criteria around cybersecurity certification for IoT endpoints.
- Building Management:Commercial real estate operators in Singapore and Hong Kong are retrofitting aging HVAC infrastructure with wireless environmental sensors to meet green building certification requirements.
Manufacturing commands the deepest volume commitments; agriculture is expanding most quickly on subsidy-driven digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate sensor module assembly, attracting foreign vendors seeking MIIT SRRC certification proximity. Japanese government procurement programs channel wireless instrumentation demand through METI-certified suppliers. India's state-level agricultural digitization subsidies are creating distributed demand nodes across farming cooperatives.
China
Smart factory deployments across Guangdong and Jiangsu provinces are compressing sensor replacement cycles to two-year intervals. MIIT's streamlined SRRC type-approval for short-range wireless modules has reduced market access timelines from twelve months to six. The Yangtze River Delta industrial corridor hosts the densest concentration of assembly-line digitization programs, with Suzhou and Hangzhou facilities leading wireless node procurement.
Japan
METI's Society 5.0 framework mandates edge-device interoperability standards for public infrastructure tenders. The 920 MHz radio-law certification requirement governs industrial sensor deployment across Kanto and Kansai manufacturing belts. Yokohama and Osaka process-control facilities are standardizing on ISA100.11a-certified instrumentation, creating specification-driven procurement patterns.
India
State agricultural departments in Maharashtra and Punjab are subsidizing LoRaWAN-enabled soil-moisture sensor networks. The Wireless Planning and Coordination Wing's import licensing for radio-frequency equipment favors domestic assembly partnerships over direct foreign supply. Farming cooperatives across the Indo-Gangetic Plain are replacing manual field monitoring with automated moisture detection nodes.
South Korea
Semiconductor fabrication cleanrooms in Gyeonggi Province are deploying wireless temperature sensors for wafer yield optimization. The Ministry of Science and ICT governs unlicensed spectrum allocation for industrial IoT deployments. Samsung and SK hynix supplier parks in Yongin and Icheon are piloting piezoelectric energy harvesters for equipment-monitoring applications.
Australia
Utility-scale smart metering rollouts in New South Wales and Victoria favor LoRaWAN's sub-gigahertz urban penetration. The Australian Communications and Media Authority's 915 MHz spectrum allocation enables basement-to-pentagon building automation coverage. Sydney and Melbourne commercial real estate operators are retrofitting aging HVAC infrastructure with wireless environmental sensors to meet green building certification requirements.
APAC Wireless Sensors Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with industrial automation favoring established instrumentation vendors while consumer applications attract electronics assemblers. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with process-control heritage, semiconductor firms integrating radio-plus-sensor silicon, and pure-play wireless instrumentation specialists. Competitive moves center on protocol certification pre-integration and geographic assembly relocation to bypass tariff exposure.
Within the diversified industrial tier, Honeywell International Inc and Emerson Electric Co occupy positions anchored by large-scale refinery sensor network deployments across Southeast Asia. Texas Instruments Incorporated exemplifies the silicon-integration archetype, competing on module footprint reduction for original equipment manufacturers. Yokogawa Electric Corporation sits within the pure-play instrumentation segment, dominating process-industry wireless instrumentation through certified field devices.
| Leading Market Players |
|---|
| Emerson Electric Co |
| STMicroelectronics |
| Honeywell International Inc |
| Rockwell Automation Inc |
| Texas Instruments Incorporated |
| ABB Ltd |
| Siemens AG |
| Yokogawa Electric Corporation |
| Schneider Electric SA |
| Others |
Value Chain & Pricing Dynamics
Captive integration into coin-cell battery and radio silicon production anchors pricing power for Japanese and South Korean sensor vendors, compressing module costs while extending procurement leverage across Southeast Asian assembly networks.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent replacement orders from scheduled procurement cycles. ISA100.11a-certified industrial sensors command premium positioning against uncertified alternatives, while price erosion runs through consumer-grade Bluetooth modules amid volume scale expansion in Chinese smart home channels. Healthcare monitoring applications exhibit lowest price sensitivity due to FDA-equivalent certification requirements, whereas agricultural soil-moisture nodes face acute cost pressure from subsidy-capped state procurement programs.
Supply Chain Analysis
Single-source vulnerability sits with lithium manganese dioxide cell production clustering in Japan and South Korea, exposing downstream assemblers to raw material volatility. Module fabrication draws from Taiwanese radio-frequency engineering talent and Chinese printed-circuit-board substrate capacity, creating tariff-exposed logistics chokepoints through regional shipping lanes. Distribution runs through Vietnamese electronics manufacturing zones that leverage ASEAN trade preferences for tariff-efficient re-export to Australian and Indian end markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from METI's harmonized interoperability standards is forcing sub-scale firmware vendors toward acquisition or exit, favoring integrated platform providers with pre-certified protocol stacks.
For Market Incumbents: Anchor market position through backward integration into energy-harvesting silicon design, eliminating battery replacement labor from high-density industrial deployments. Pre-integrate ISA100.11a and WirelessHART certification into unified firmware images to capture METI-mandated public infrastructure tenders ahead of smaller competitors lacking compliance resources. For New Entrants and Emerging Players: Energy-harvesting micro-generator technology offers a technology-first wedge into South Korean semiconductor fab equipment monitoring, where piezoelectric harvester pilots create specification gaps incumbent battery-dependent vendors cannot address. Target India's state-subsidized precision agriculture sector through domestic assembly partnerships that bypass WPC import licensing friction, selling LoRaWAN-enabled soil-moisture nodes direct to Maharashtra and Punjab farming cooperatives. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified industrial conglomerates seeking wireless instrumentation capabilities. Long-term viability favors pure-play vendors with certified field-device portfolios over module assemblers lacking protocol intellectual property. Watch Australia's ACMA spectrum allocation decisions for 915 MHz bandwidth expansion as the signal indicating utility-scale smart metering procurement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Protocol Certification Pre-Integration | ISA100.11a and WirelessHART unified firmware accelerates METI tender qualification timelines. |
| Energy Harvesting Technology Licensing | Piezoelectric micro-generators eliminate battery replacement labor from dense industrial sensor networks. |
| Vietnam Assembly Footprint Expansion | Northern industrial zones access ASEAN trade preferences for tariff-efficient Australian and Indian re-export. |
| Domestic India Partnership Structure | WPC-compliant local assembly bypasses import licensing friction for agricultural sensor deployment. |
| Dual-Radio Silicon Architecture Launch | Bluetooth-Zigbee convergence serves both consumer latency and industrial mesh requirements from single chip. |
Study Parameters
Independent corroboration across sensor vendor engineering directors, refinery automation procurement leads, and agricultural cooperative managers underwrites the qualitative findings. Primary fieldwork engaged distributed control system integrators in Southeast Asian petrochemical facilities, MIIT certification consultants in Suzhou and Hangzhou, and hospital biomedical engineers in Tokyo and Sydney. Secondary validation drew from MIIT SRRC type-approval filings, METI radio-law certification registries, and WPC import licensing records. Bottom-up module shipment estimates triangulated against top-down industrial automation capital expenditure patterns.
Comparable-period anchoring against historical smart factory deployment cycles in China's Yangtze River Delta established baseline replacement-rate assumptions across the projection horizon. The analytical framework modeled segmentation across product type, connectivity protocol, and end-use vertical, with additional dimensioning by national regulatory cluster given certification-driven procurement eligibility. CAGRs derived from trend-line extrapolation of assembly-line digitization programs, adjusted for MIIT streamlining effects and METI compliance timeline extensions. Forecast inputs incorporated soil-moisture subsidy allocation trajectories from Maharashtra and Punjab state agricultural departments.
Several conditions sit outside the modeled scope, including cybersecurity mandate evolution beyond current IoT endpoint frameworks and unlicensed spectrum congestion resolution mechanisms in Australian dense urban corridors. Forecasts reflect documented assumptions regarding MIIT certification velocity and WPC licensing procedural stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Traffic Sensor Market
Sensors
Bluetooth Beacons Market
Sensors
In-Counter Barcode Scanners Market
Sensors
Fixed RFID Readers Market
Sensors
Automated Weather Observation System Market
Sensors
Remote Sensing Technology Market
Sensors
Global Weather Monitoring Solutions and Services Market
Sensors
Wireless Occupancy Sensors Market
Sensors
Alcohol Sensor Market
Sensors
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market
Sensors
Residential Water Leak Detection System Market
Sensors
India Asset Tracking Market
Sensors
Body Area Network Market
Sensors
Europe Lidar Market
Sensors
Lidar Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market