
 Digital Compass (E-Compass) Market | 2026-2036
Digital Compass (E-Compass) Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Compass (E-Compass) Market Outlook
Sensor fusion integration is tilting e-compass design toward multi-axis IMU combinations with magnetometer calibration. Bosch Sensortec GmbH leverages its MEMS fabrication depth to anchor high-volume smartphone supply contracts. STMicroelectronics N.V. sustains R&D intensity across automotive-grade magnetic sensors with ASIL-compliant reliability. Honeywell International Inc. dominates aerospace and defense applications where ITAR-controlled precision heading references command premium positioning.
A digital compass (e-compass) is an electronic device that detects magnetic field direction using magnetoresistive, Hall-effect, or fluxgate sensing elements, typically outputting heading data with 0.5-degree to 2-degree accuracy for orientation and navigation functions. Its primary commercial purpose is to provide absolute heading reference in GPS-denied environments or augment satellite positioning with attitude awareness. MEMS technology leads volume production due to semiconductor-compatible batch fabrication, while hybrid architectures combining magnetic and inertial sensing capture the fastest expansion as drones and robotics demand tilt-compensated heading. Consumer electronics end users still occupy the largest shipment base, though automotive applications concentrate margin pools through AEC-Q100 qualification requirements and longer product lifecycles.
The US FAA mandates e-compass redundancy for certain commercial drone operations under Part 107 waivers, while EU REACH restrictions on rare-earth magnet materials shape component sourcing strategies for European manufacturers. Japan's METI promotes domestic MEMS supply chain resilience through JIS standardization and precision manufacturing subsidies. Stakeholders must monitor how IEC 60747 semiconductor reliability standards evolve for automotive magnetometers, as qualification scope expansions will determine which foundry partnerships secure tier-one OEM access.
Market Dynamics
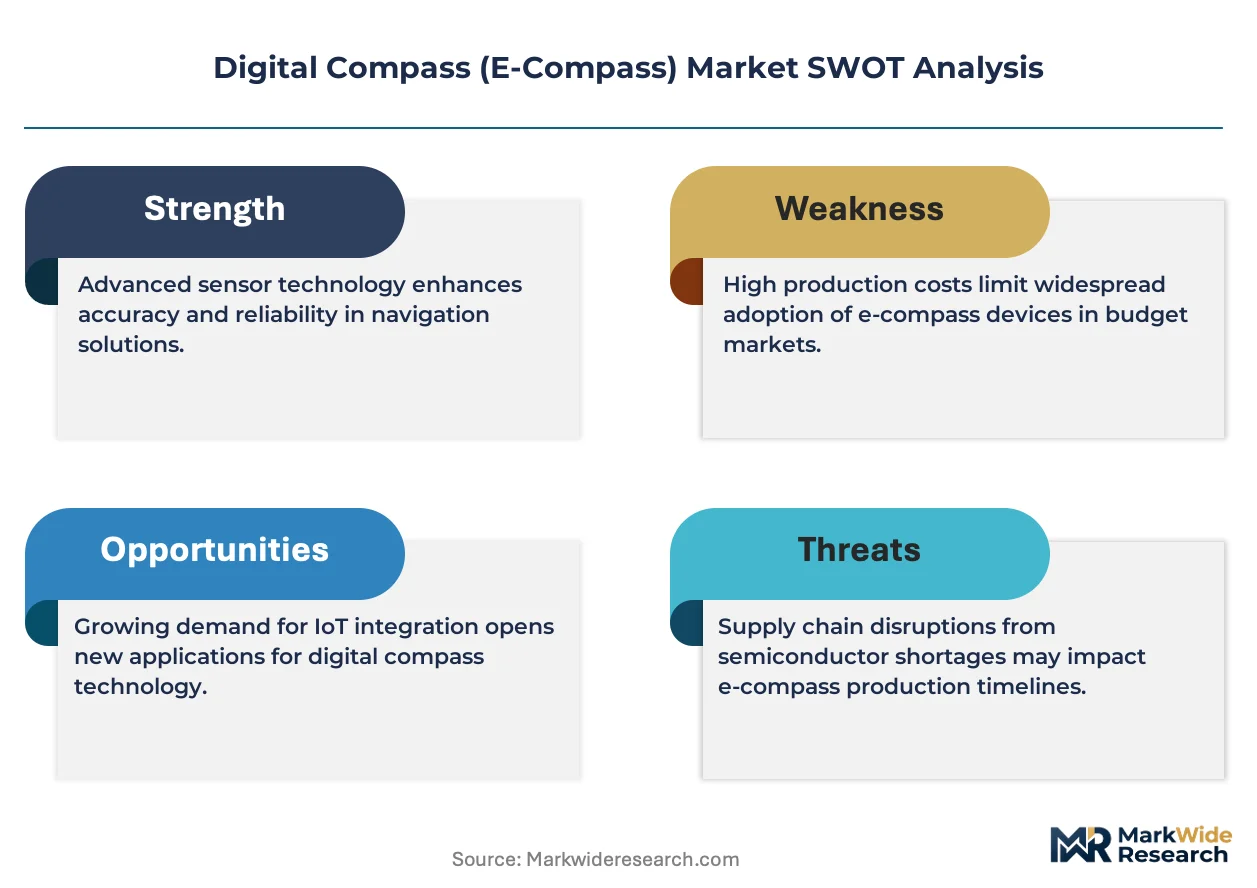
Sensor fusion architectures are compressing discrete e-compass shipments into multi-axis IMU modules, forcing pure-play magnetometer suppliers to recalibrate value capture around calibration algorithms and temperature compensation IP rather than hardware volume.
Growth Catalysts
- Automotive ADAS mandates:China's MIIT positioning accuracy standards for connected vehicles require redundant heading references, embedding e-compass modules into tier-one navigation platforms.
- Drone commercialization:The US FAA Part 107 waiver structure mandates magnetic heading redundancy for beyond-visual-line-of-sight operations, creating certified module demand.
- MEMS foundry clustering:East Asian manufacturing concentration around Japan, South Korea, and Taiwan reduces sensor packaging costs through precision electronics supply chain density.
Market Restraints
- Rare-earth magnet dependency:EU REACH restrictions on neodymium and samarium sourcing constrain European manufacturers' component procurement flexibility.
- Soft-iron interference:Ferromagnetic materials in vehicle chassis and consumer device housings degrade raw heading accuracy, requiring complex calibration routines.
- Foundry concentration risk:TSMC and GlobalFoundries capacity allocation for automotive-grade MEMS creates supply bottlenecks during semiconductor cycle upturns.
Strategic Opportunities
- Industrial robotics white space:Warehouse automation and AGV navigation in Germany and Japan lack standardized tilt-compensated heading modules.
- Subsea positioning:Offshore wind installation vessels require fluxgate-grade precision where GPS signals attenuate, opening premium sensor tiers.
- India PLI scheme:Production-linked incentives for electronics manufacturing attract MEMS packaging investments serving domestic smartphone and automotive OEMs.
Industry Challenges
- ASIL-D certification timelines:Automotive functional safety qualification for magnetometers extends 18-24 months, freezing design wins for emerging suppliers.
- Magnetic sensor fusion expertise:Shortage of engineers combining Kalman filter implementation with geomagnetic field modeling compresses R&D throughput at mid-tier vendors.
- IEC 60747 scope expansion:Evolving semiconductor reliability standards for automotive magnetometers require repeated qualification cycles, draining engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Compass (E-Compass) Market |
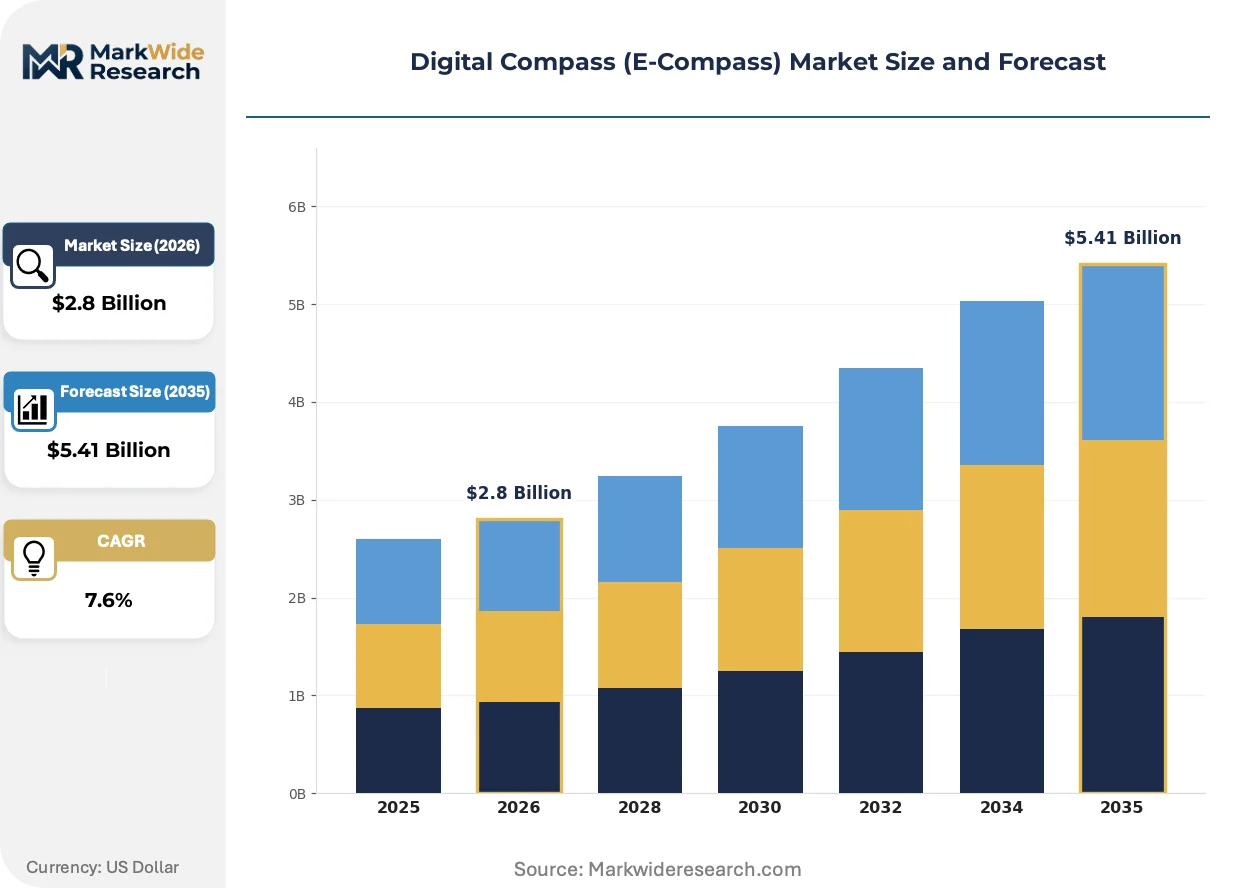
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automotive Navigation, Smartphone Integration, Wearable Devices, Drones Technology: MEMS, Optical, Magnetic, Hybrid End User: Consumer Electronics, Aerospace, Automotive, Robotics Distribution Channel: Online Retail, Direct Sales, Distributors, Others |
| Companies Covered | Honeywell International Inc., Bosch Sensortec GmbH, STMicroelectronics N.V., Asahi Kasei Microdevices Corporation, NXP Semiconductors N.V., Robert Bosch GmbH, TDK Corporation, Infineon Technologies AG, MEMSIC Semiconductor Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Compass (E-Compass) Market Strategic Shifts
Multi-sensor integration is eroding standalone e-compass boundaries as magnetometers merge with accelerometers and gyroscopes into unified attitude reference units. Calibration complexity and algorithmic differentiation now determine competitive position more than raw sensing element performance.
Fluxgate sensing is hybridizing with MEMS fabrication techniques to deliver military-grade precision at semiconductor-scale cost structures. Defense contractors and precision agriculture OEMs are adopting these hybrid modules for applications requiring sub-degree heading accuracy in high-vibration environments. The technology is hybridizing price-performance curves across industrial and commercial drone segments previously served by lower-accuracy Hall-effect alternatives.
Japan's METI precision manufacturing subsidies are accelerating domestic MEMS supply chain resilience investments following pandemic-era import disruptions. JIS standardization for automotive magnetic sensors now requires extended temperature cycling tests that exceed IEC baseline requirements. European sensor vendors are responding by partnering with Japanese tier-two automotive suppliers to secure qualification pathway access.
Smartphone OEMs are unbundling magnetic sensor procurement from IMU module contracts, creating direct relationships with discrete magnetometer specialists. This disintermediation of sensor fusion integrators concentrates in South Korean and Chinese handset manufacturers seeking cost transparency. The practice is most visible in flagship device programs where custom calibration profiles differentiate user experience across navigation and augmented reality applications.
Digital Compass (E-Compass) Market Segmentation
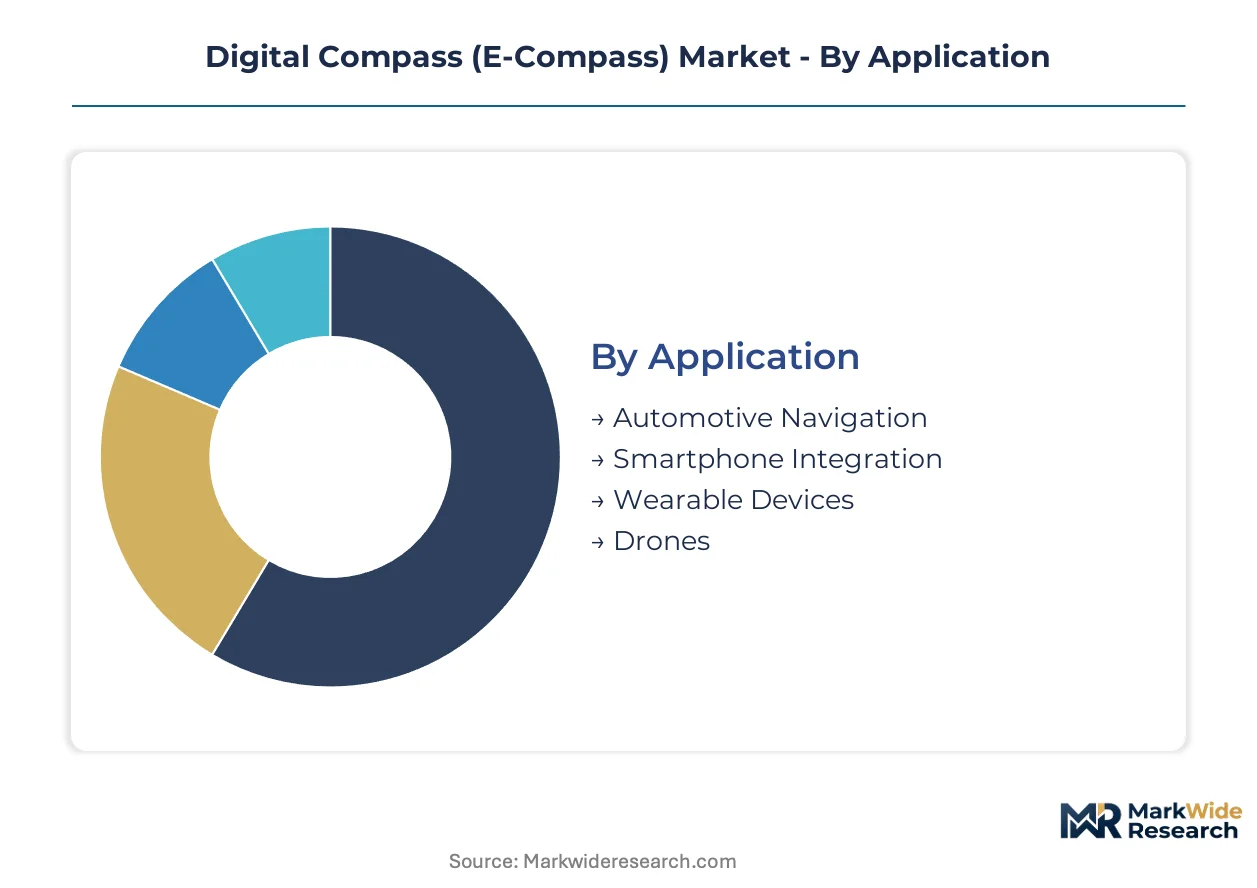
E-compass segmentation reflects divergent accuracy requirements and certification burdens across end-use environments. Application and technology categories capture the steepest margin differentiation, while distribution channels stratify by customer technical sophistication.
Application:
Mature navigation platforms coexist with emerging robotics deployments across this dimension.
- Automotive Navigation:AEC-Q100 qualified modules integrate into ADAS platforms with ASIL-D functional safety requirements. China's MIIT positioning mandates for connected vehicles concentrate OEM procurement through tier-one suppliers in Shanghai and Shenzhen.
- Smartphone Integration:9-axis IMU fusion demands sub-degree tilt compensation for augmented reality applications. Samsung and Xiaomi flagship programs drive discrete magnetometer procurement unbundling from legacy module contracts.
- Wearable Devices:Ultra-low power 1-2 degree accuracy modules serve fitness tracking and outdoor navigation wristbands.
- Drones:FAA Part 107 waiver compliance mandates magnetic heading redundancy for commercial beyond-visual-line-of-sight operations.
Automotive navigation handles the majority of throughput; drones are expanding most quickly on share.
Technology:
Cost tiers separate commodity MEMS from precision fluxgate alternatives serving defense and subsea applications.
- MEMS:Semiconductor batch fabrication enables smartphone and automotive volume economics. Bosch Sensortec and STMicroelectronics anchor high-volume supply through East Asian foundry partnerships.
- Hybrid:Magnetometer-accelerometer-gyroscope fusion delivers tilt-compensated heading for robotics and precision agriculture. Warehouse automation OEMs in Germany and Japan lack standardized modules, creating white-space capture opportunities.
- Magnetic:Discrete Hall-effect and magnetoresistive elements serve cost-constrained consumer applications.
- Optical:Fiber-optic gyroscope hybrids provide GPS-denied navigation for offshore wind installation vessels.
MEMS dominates absolute shipment volume; hybrid architectures climb the fastest as sensor fusion standardizes.
End User:
Customer type determines qualification burden and product lifecycle length.
- Consumer Electronics:Smartphone and wearable OEMs demand 12-18 month design cycles with aggressive cost-down trajectories.
- Automotive:Tier-one navigation platform suppliers enforce 18-24 month ASIL-D certification timelines freezing design wins.
- Aerospace:ITAR-controlled precision heading references command premium positioning for military and commercial aviation.
- Robotics:Industrial automation and AGV navigation lack calibration standardization, fragmenting procurement.
Consumer electronics captures the largest shipment base; robotics is gaining share fastest on automation investment cycles.
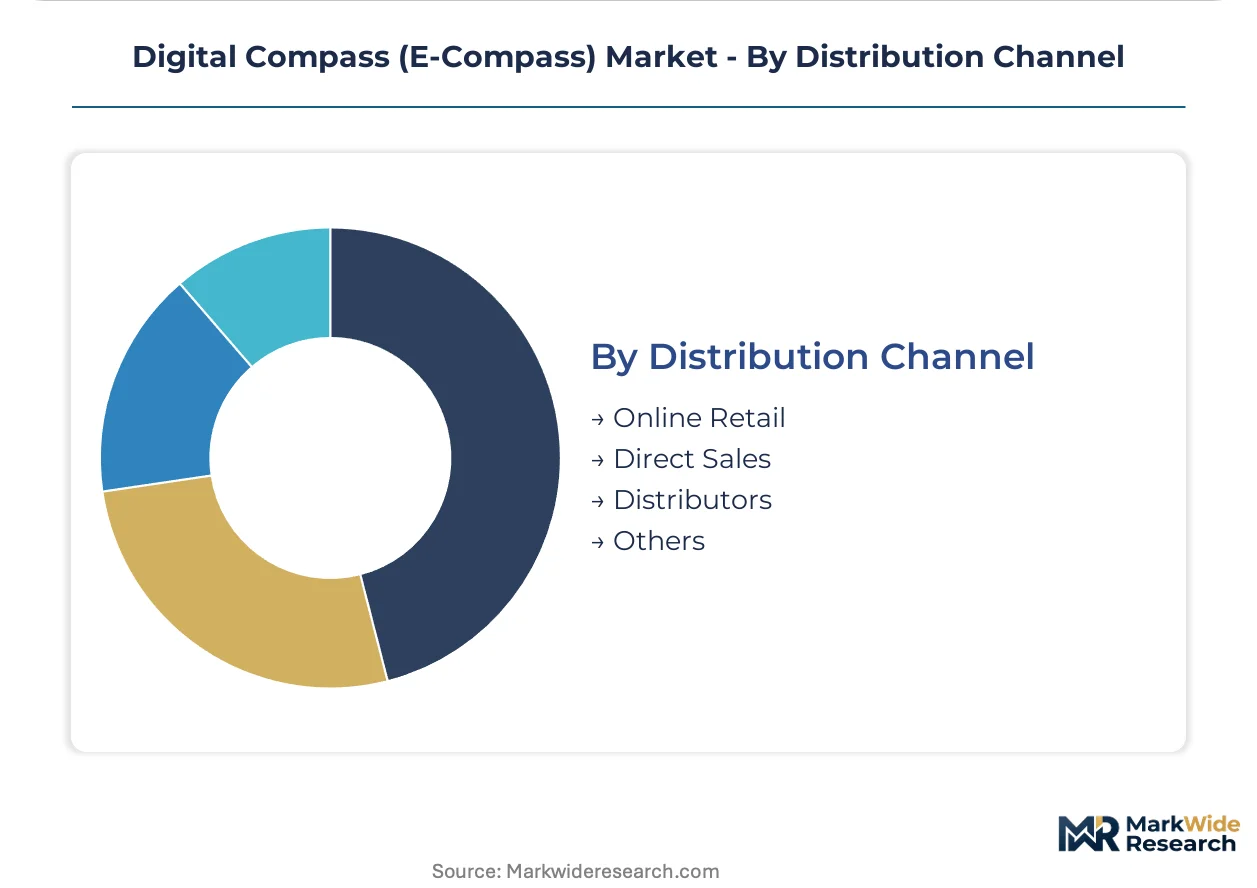
Distribution Channel:
Procurement patterns split between engineering-intensive direct relationships and volume-driven retail.
- Distributors:Arrow and Avnet aggregate mid-volume automotive and industrial demand with technical support services.
- Direct Sales:Tier-one smartphone and automotive OEMs negotiate direct magnetometer contracts bypassing IMU integrators.
- Online Retail:Developer kits and evaluation modules reach robotics startups and academic researchers.
- Others:Contract manufacturers and EMS providers handle consignment arrangements for consumer electronics brands.
Distributors handle the majority of throughput; direct sales is expanding most quickly on flagship OEM disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and smartphone manufacturers concentrate procurement in East Asian manufacturing clusters, with precision electronics supply chains anchoring sensor module assembly. Tier-one navigation platform suppliers enforce qualification requirements that favor established foundry partnerships.
China
Connected vehicle mandates from MIIT drive e-compass integration into ADAS platforms for domestic OEMs. Positioning accuracy standards require redundant heading references, tightening certification timelines. Shanghai and Shenzhen host tier-one navigation suppliers consolidating procurement through captive MEMS packaging facilities.
Japan
Domestic robotics OEMs and automotive suppliers source tilt-compensated heading modules for warehouse automation. METI precision manufacturing subsidies accelerate MEMS supply chain resilience investments following import disruptions. Nagoya and Osaka industrial corridors concentrate JIS-standard automotive sensor qualification laboratories.
South Korea
Samsung Electronics and smartphone OEMs unbundle discrete magnetometer procurement from legacy IMU module contracts. Flagship device programs demand custom calibration profiles for augmented reality navigation. Seoul metropolitan area hosts disintermediated supplier relationships bypassing traditional sensor fusion integrators.
Germany
Industrial automation OEMs lack standardized tilt-compensated heading modules for AGV navigation in warehouse environments. REACH restrictions on rare-earth magnet materials constrain component sourcing flexibility. Bavaria and Baden-Württemberg automotive clusters enforce extended temperature cycling tests exceeding IEC baseline requirements.
United States
Commercial drone operators pursue FAA Part 107 waivers mandating magnetic heading redundancy for beyond-visual-line-of-sight missions. Defense contractors source ITAR-controlled precision heading references for military applications. Greater Boston and Silicon Valley robotics startups evaluate developer kits through online retail channels.
Digital Compass (E-Compass) Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply relationships. The vendor base organizes around three strategic archetypes: MEMS foundry-integrated component suppliers, discrete magnetometer specialists, and aerospace-grade precision sensor providers. Consolidation pressure favors backward integration into calibration algorithm IP. Geographic expansion and strategic partnerships dominate competitive moves as qualification timelines freeze design wins.
Among MEMS fabrication-anchored suppliers, Bosch Sensortec GmbH, STMicroelectronics N.V., and Honeywell International Inc. exemplify distinct positioning archetypes. Bosch Sensortec represents foundry-integrated volume production serving consumer electronics procurement. STMicroelectronics occupies a position bridging automotive-grade reliability requirements with semiconductor-scale economics. Honeywell anchors the precision-tier segment where ITAR-controlled specifications command premium positioning for aerospace and defense applications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Bosch Sensortec GmbH |
| STMicroelectronics N.V. |
| Asahi Kasei Microdevices Corporation |
| NXP Semiconductors N.V. |
| Robert Bosch GmbH |
| TDK Corporation |
| Infineon Technologies AG |
| MEMSIC Semiconductor Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Foundry undercapacity at automotive-grade MEMS facilities in Taiwan and South Korea is compressing supplier margins while amplifying pricing power for qualified vendors. This utilization squeeze propagates through contract structures, input pass-through mechanisms, and buyer procurement flexibility across the e-compass value chain.
Pricing Analysis
Cost-plus contracts with rare-earth magnet price indexation dominate European procurement, insulating vendors from neodymium volatility while exposing buyers to material swings. Three-tier pricing structure across AEC-Q100 automotive, industrial-grade, and consumer MEMS separates qualification burden from performance tier. Cost compression in smartphone discrete magnetometers intensifies because Samsung and Xiaomi unbundle procurement from IMU integrators. Consumer electronics buyers exhibit highest price sensitivity; aerospace contractors under ITAR specifications show least.
Supply Chain Analysis
Contract manufacturing concentrates at TSMC automotive MEMS lines, GlobalFoundries specialty foundries, and Japanese tier-two packaging houses in Nagoya. Geographic supply concentration centers on Taiwan, South Korea, and Japan for wafer fabrication, with China hosting captive packaging for domestic OEMs. Raw material dependencies draw from rare-earth magnet processors, semiconductor-grade silicon substrates, and precision ceramic housings. Single-source vulnerability at fluxgate sensor coil suppliers creates qualification bottlenecks for defense contractors. Distribution runs through Arrow and Avnet for mid-volume automotive and industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The e-compass market is cycling through semiconductor inventory correction, with automotive ADAS procurement resuming as China's MIIT enforcement tightens. This cyclical recovery favors qualified vendors with existing foundry allocations and certification pathways.
For Market Incumbents: Entrench ASIL-D certification barriers by accelerating JIS standard alignment ahead of IEC 60747 scope expansion. Bosch Sensortec and STMicroelectronics should deepen backward integration into temperature compensation algorithm IP to offset hardware commoditization. Foundry capacity reservation agreements with TSMC automotive lines defend against emerging MEMSIC and domestic Chinese suppliers.
For New Entrants and Emerging Players: Build out calibration-as-a-service offerings for Germany's warehouse automation OEMs, where tilt-compensated heading modules lack standardization. India's PLI scheme for electronics manufacturing offers the most penetrable geography for MEMS packaging investments. Direct sales relationships with South Korean smartphone OEMs bypass entrenched IMU integrator channels.
For Investors and Strategic Acquirers: Long-term, this sits as a sensor fusion consolidation play because multi-axis IMU modules are compressing standalone magnetometer boundaries. Acquisition targets should display Kalman filter implementation expertise combined with geomagnetic field modeling capability. Monitor ASIL-D certification queue lengths at tier-one automotive suppliers as inflection signal for design win velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Acceleration | STMicroelectronics and Bosch Sensortec lock tier-one OEM access ahead of IEC scope expansion. |
| Foundry Partnership Expansion | GlobalFoundries automotive MEMS capacity allocation secures supply for drone FAA Part 107 compliance modules. |
| Algorithm IP Acquisition | Calibration software targets soft-iron interference compensation for vehicle chassis integration. |
| India PLI Manufacturing Entry | Domestic packaging investments serve Xiaomi and local automotive OEMs with reduced logistics exposure. |
| Fluxgate-MEMS Hybrid Development | Defense contractors adopt sub-degree precision modules for GPS-denied offshore wind installation. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs and secondary validation layers. Semiconductor procurement managers at tier-one automotive suppliers, MEMS foundry operations directors, drone platform engineers, and smartphone sensor fusion architects provided operational data. Secondary sources included MIIT regulatory filings, FAA Part 107 waiver databases, JIS standard documentation, and SEC 10-K disclosures from sensor vendors. Bottom-up shipment modeling and top-down market sizing were triangulated against foundry capacity utilization reports.
Calibration approaches anchored volume and value outputs across the analysis window. Segmentation dimensions spanned technology tier, application environment, end-user qualification burden, and regional regulatory cluster. CAGRs were derived from foundry capacity expansion schedules, automotive platform rollout timelines, and smartphone refresh cycle patterns. Specific forecast inputs incorporated China's connected vehicle mandate enforcement trajectory and EU REACH rare-earth sourcing restriction evolution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic MEMS suppliers or accelerated JIS standard adoption would shift outcomes. Forecasts assume stable rare-earth magnet pricing and unchanged IEC 60747 scope timelines. Quarterly review of tier-one automotive design win announcements and foundry automotive MEMS utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Global Tunnel Monitoring System Market
Sensors
Terrestrial Laser Scanning System Market
Sensors
Micro Location Technology Market
Sensors
Indoor Positioning and Navigation Market
Sensors
GNSS-Enabled Consumer Device Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Yield Monitoring Systems Market
Sensors
Mobile Laser Scanning Market
Sensors
Automatic Number Plate Recognition (ANPR) Market
Sensors
Europe Lidar Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Fixed RFID Readers Market
Sensors
Vibration Monitoring Market
Sensors
Barcode Scanner Market
Sensors
India Asset Tracking Market
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market