
 Self-Adhesive Films Market | 2026-2036
Self-Adhesive Films Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Adhesive Films Market Analytics
Southeast Asia is reshaping self-adhesive film supply chains through new extrusion and coating investments in Thailand and Vietnam. 3M leverages its acrylic adhesive patent portfolio to dominate high-temperature electronics applications. Avery Dennison Corporation anchors North American label stock capacity with integrated film manufacturing in Ohio and California. Nitto Denko Corporation specializes in optical-grade protective films for display panel makers across East Asia.
Self-adhesive films are multilayer laminates comprising a face stock, pressure-sensitive adhesive layer, and release liner, typically manufactured through solvent, solventless, or hot-melt coating processes with thickness ranging from 12 to 150 micrometers depending on end-use durability requirements. These films bond to substrates upon light pressure without heat activation, serving primary functions in temporary surface protection, permanent labeling, and functional insulation across industrial and consumer goods. Polymeric films command the largest value share due to their versatility in packaging and automotive applications, while biodegradable films represent the fastest-expanding category as brand owners face extended producer responsibility mandates. Acrylic adhesives lead volume consumption in electronics and medical segments where low outgassing and thermal stability determine specification compliance.
FDA regulations govern medical-grade adhesive films for wearable device and transdermal patch applications in the United States, while REACH and RoHS restrict hazardous substance content in films sold across the European Union. China's SAMR enforces GB standards for volatile organic compound emissions in adhesive formulations used in indoor environments and consumer products. Japan's METI promotes JIS-certified films for electronics export qualification, creating compliance cost tiers that filter market access. Stakeholders must monitor evolving bioplastic certification schemes and adhesive chemistry disclosure requirements to sustain specification credibility with multinational OEMs.
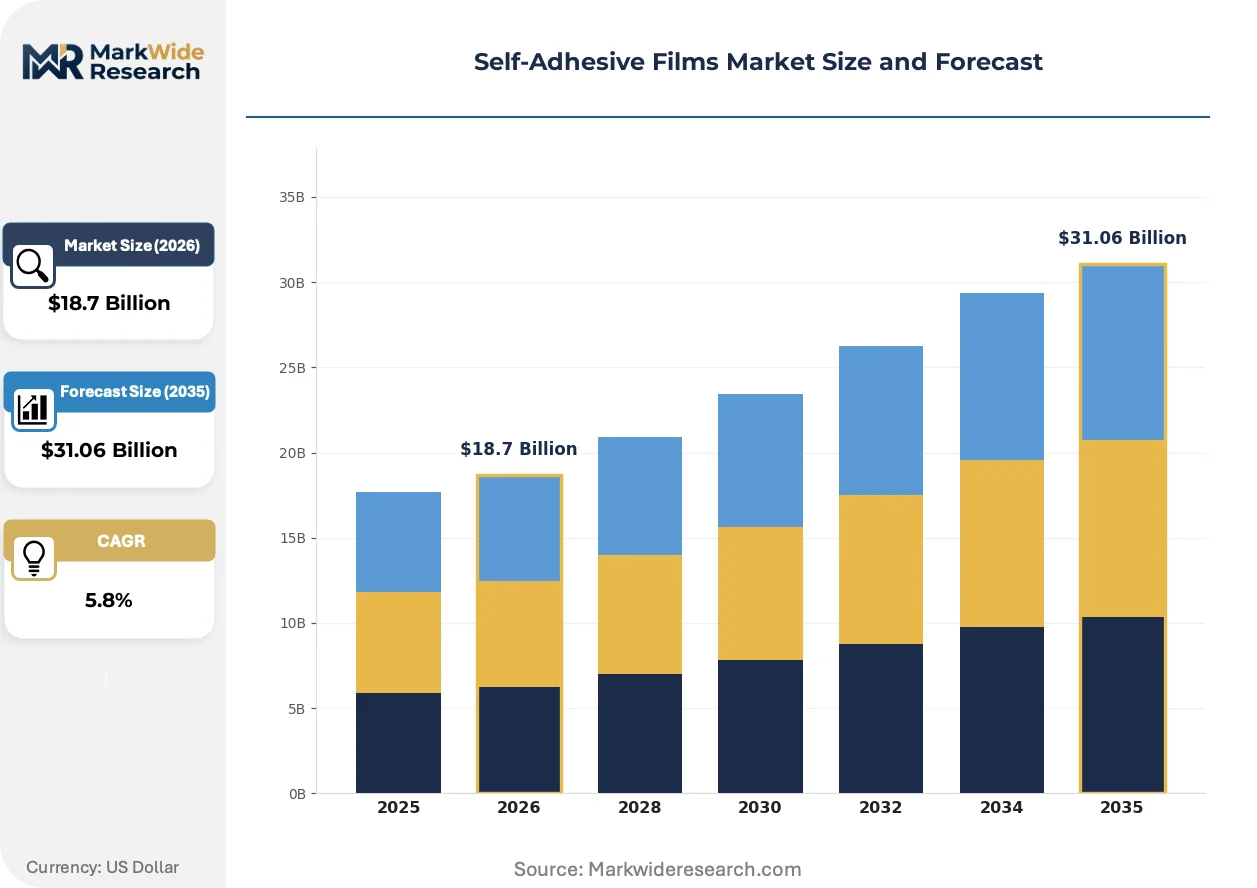
Market Dynamics
EV battery enclosure specifications from German and Japanese automotive OEMs are compressing qualification timelines for high-temperature acrylic adhesive films, forcing substrate suppliers to accelerate thermal cycling certification.
Growth Catalysts
- REACH compliance tiers:European Union hazardous substance restrictions filter out low-grade film suppliers, consolidating specification authority among certified manufacturers serving medical and electronics end-uses.
- Display panel clustering:Seoul and Suwon electronics corridors concentrate demand for ultra-clean surface protection films, pulling coating capacity investment into South Korea's Gyeonggi province.
- Biodegradable film chemistry:Extended producer responsibility mandates in packaging applications accelerate starch-based and PLA adhesive film development for consumer goods labeling.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and polypropylene resin prices swing with crude oil indices, compressing margin visibility for extrusion-dependent film manufacturers.
- Release liner supply concentration:Silicone-coated paper and PET liner production clusters in Scandinavian pulp mills and German specialty paper plants, creating single-source vulnerability for coating operations.
- Hot-melt coating technical ceiling:Solventless adhesive systems fail to match solvent-based formulations in optical clarity for display-grade protective films, limiting process conversion.
Strategic Opportunities
- Vietnam extrusion greenfield:New multilayer film lines near Ho Chi Minh City target ASEAN electronics assembly migration with lower labor cost structures than Chinese coastal provinces.
- Transdermal patch expansion:FDA wearable device approvals create specification demand for hypoallergenic medical-grade adhesive films with 7-day wear duration.
- Solvent recovery technology:Closed-loop distillation systems in coating plants convert regulatory emissions liability into circular chemistry credentials for EU Green Deal procurement.
Industry Challenges
- Adhesive formulation chemist scarcity:Pressure-sensitive polymer synthesis expertise concentrates among aging technical workforces in Japan and Germany, constraining R&D velocity for emerging film producers.
- Dual certification timelines:Simultaneous GB standard compliance for China SAMR and REACH registration for ECHA extends product launch cycles by 18-24 months for multinational film suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Adhesive Films Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Films, Paper Films, Metalized Films, Biodegradable Films End User: Packaging, Automotive, Electronics, Medical Adhesive Type: Acrylic, Rubber, Silicone, Water-Based Application: Labeling, Surface Protection, Decorative, Insulation |
| Companies Covered | Lintec Corporation, Toray Industries, 3M, Nitto Denko Corporation, H.B. Fuller Company, Avery Dennison Corporation, Henkel AG & Co. KGaA, UPM-Kymmene Oyj, LG Hausys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Adhesive Films Market Evolving Landscape
Coating process electrification and adhesive chemistry disclosure requirements are restructuring competitive position around environmental credentials rather than unit cost alone.
Solventless hot-melt coating systems with precision slot-die application are rendering obsolete conventional solvent-based lines in European packaging film plants. German label stock converters retrofit existing coating towers with nitrogen-inerted extrusion heads to eliminate volatile organic compound emissions. The technology compresses permitting timelines from 14 months to 90 days for facility expansions.
China's GB standards on volatile organic compound emissions in indoor-use adhesive formulations now mandate real-time emissions monitoring for film coating operations above 50,000 tons annual solvent consumption. SAMR enforcement actions in Guangdong and Jiangsu provinces have shuttered twelve uncertified coating plants since 2023. Medical and electronics-grade film suppliers respond by segregating solvent-based production lines from consumer goods capacity to isolate compliance risk.
Automotive OEMs now specify adhesive film performance through battery thermal runaway containment testing rather than legacy peel-strength metrics. Procurement contracts from Stuttgart and Toyota City engineering centers require 30-minute flame barrier documentation for enclosure protection films. Tier-1 suppliers in Bavaria and Aichi prefecture restructure quality departments around cell-level safety validation, displacing commodity specification buyers from material selection committees.
Self-Adhesive Films Market Segmentation
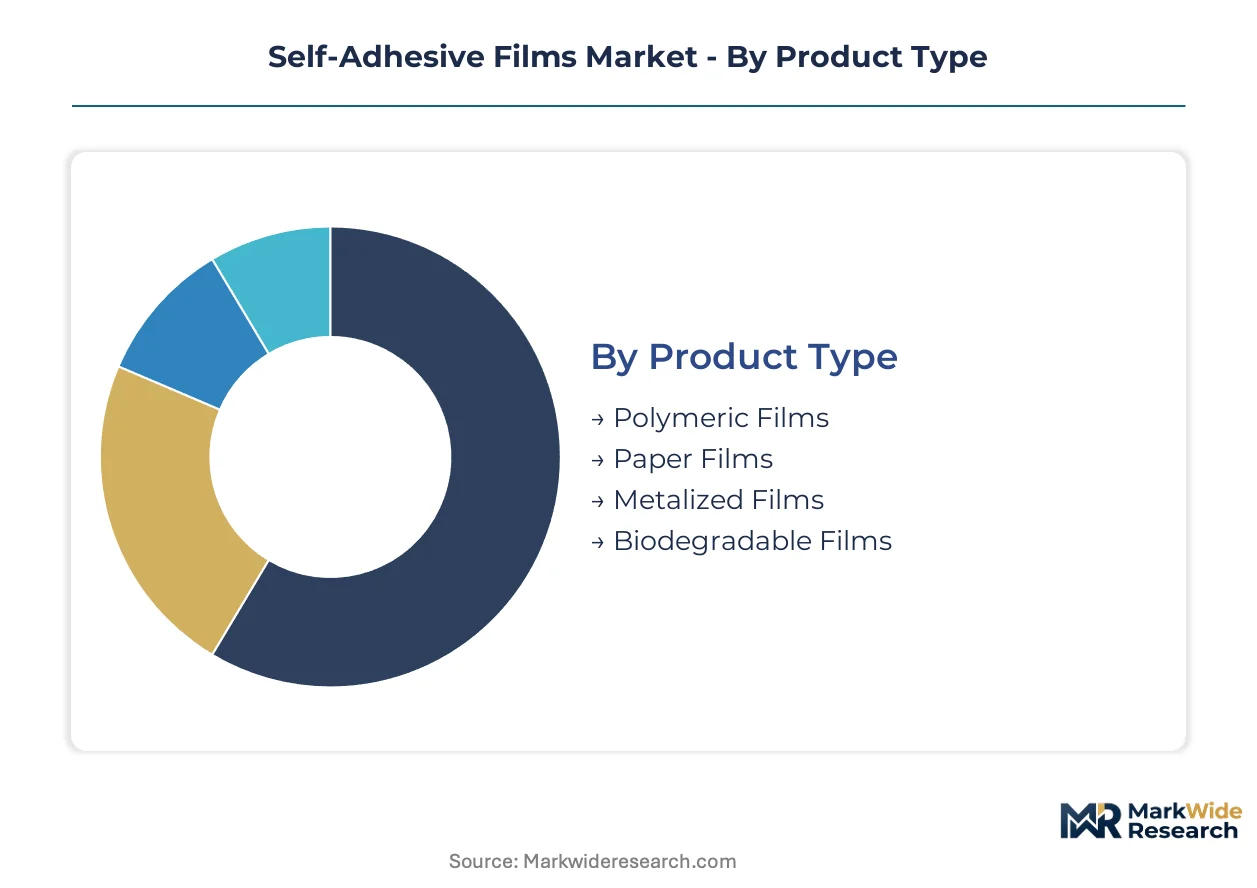
Self-adhesive film specifications diverge sharply across end-use requirements, with automotive battery enclosures demanding thermal runaway containment while electronics manufacturers prioritize optical clarity and low outgassing. Segmentation discipline separates commodity label stock from certified medical-grade films commanding qualification premiums.
Product Type:
Cost tier differentiation separates high-volume commodity extrusion from specialty film grades requiring precision coating and extended certification timelines.
- Polymeric Films:Multilayer laminates of polypropylene, polyester, and PVC dominate volume consumption through versatility in packaging durability and automotive conformability. German and Japanese automotive OEMs specify these films for EV battery enclosure protection where thermal cycling resistance determines qualification.
- Biodegradable Films:Starch-based and PLA formulations respond to extended producer responsibility mandates in European consumer goods labeling. Brand owners in France and Italy now require compostable adhesive films for premium food packaging applications.
- Paper Films:Uncoated and clay-coated facestocks serve cost-sensitive labeling in logistics and retail shelf applications.
- Metalized Films:Vacuum-deposited aluminum layers provide barrier properties and decorative reflectivity in luxury goods labeling.
Polymeric films hold installed capacity. Biodegradable films are rotating up the share rankings.
End User:
Application maturity varies dramatically, with electronics and medical segments imposing specification regimes that filter out uncertified suppliers.
- Electronics:Display panel manufacturers in Seoul and Suwon corridors demand ultra-clean surface protection films with sub-micron particle contamination controls. South Korea's METI export certification requirements compress qualification timelines for foreign film suppliers.
- Automotive:EV battery enclosure specifications from Stuttgart and Toyota City engineering centers now mandate 30-minute flame barrier documentation rather than legacy peel-strength metrics. Tier-1 suppliers restructure quality departments around cell-level safety validation.
- Packaging:Label stock converters serve food, beverage, and logistics end-uses with shorter specification cycles and price-sensitive procurement.
- Medical:FDA wearable device approvals create demand for hypoallergenic adhesive films with 7-day wear duration in transdermal patch applications.
Packaging holds installed capacity. Electronics is rotating up the share rankings.
Adhesive Type:
Customer type determines chemistry selection, with multinational OEMs restricting procurement to low-outgassing formulations while commodity buyers prioritize unit cost.
- Acrylic:Pressure-sensitive polymers synthesized from acrylic monomers deliver thermal stability and UV resistance for electronics and medical segments. 3M leverages patent portfolios to dominate high-temperature applications where outgassing specifications filter commodity competitors.
- Silicone:Platinum-catalyzed systems provide extreme temperature tolerance and chemical resistance for industrial masking and aerospace applications.
- Rubber:Natural and synthetic rubber adhesives offer aggressive tack and lower cost for temporary surface protection and construction applications.
- Water-Based:Emulsion acrylics and polyurethane dispersions reduce volatile organic compound emissions for indoor-use consumer products under China's GB standards.
Acrylic holds installed capacity. Water-based formulations are rotating up the share rankings.
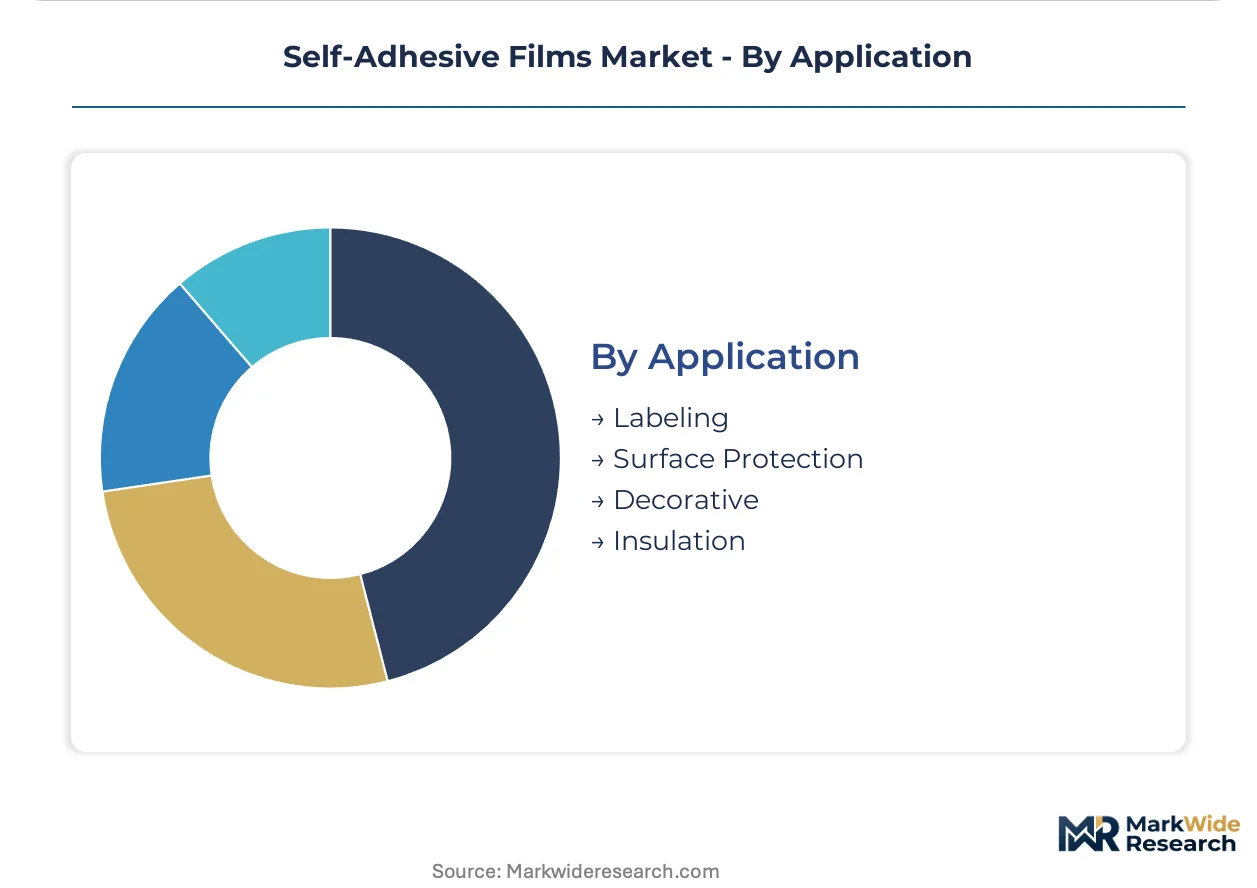
Application:
Volume concentration in labeling contrasts with margin concentration in functional protection films where specification authority commands pricing power.
- Surface Protection:Temporary films shield automotive paint, display panels, and architectural glass from abrasion and contamination during manufacturing and transit. South Korean electronics clusters specify ultra-clean grades with static-dissipative properties.
- Labeling:Permanent and removable adhesive films serve logistics, retail, and consumer goods with pressure-sensitive application requiring no heat activation.
- Decorative:Metallized and holographic films provide aesthetic differentiation in premium cosmetics and spirits packaging.
- Insulation:Multi-layer laminates deliver thermal and electrical barrier properties in battery packs and electronic assemblies.
Labeling holds installed capacity. Surface protection is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR enforcement actions in Guangdong and Jiangsu provinces anchor the regulatory geography for self-adhesive film supply chains. China's GB standards on volatile organic compound emissions now mandate real-time emissions monitoring for coating operations above 50,000 tons annual solvent consumption.
China
Display panel manufacturers in the Yangtze River Delta and Pearl River Delta drive demand for ultra-clean surface protection films. SAMR enforcement actions in Guangdong and Jiangsu provinces have shuttered twelve uncertified coating plants since 2023. Medical and electronics-grade film suppliers segregate solvent-based production lines from consumer goods capacity in Suzhou and Shenzhen to isolate compliance risk.
Germany
Automotive OEMs in Stuttgart specify adhesive film performance through battery thermal runaway containment testing rather than legacy peel-strength metrics. REACH compliance tiers filter out low-grade film suppliers, consolidating specification authority among certified manufacturers. Bavarian Tier-1 suppliers restructure quality departments around cell-level safety validation for EV battery enclosure films.
Japan
Engineering centers in Toyota City require 30-minute flame barrier documentation for enclosure protection films from procurement contracts. METI promotes JIS-certified films for electronics export qualification, creating compliance cost tiers that filter market access. Aichi prefecture coating operations specialize in optical-grade protective films for display panel makers.
South Korea
Seoul and Suwon electronics corridors concentrate demand for ultra-clean surface protection films with sub-micron particle contamination controls. METI export certification requirements compress qualification timelines for foreign film suppliers. Gyeonggi province pulls coating capacity investment from display manufacturers specifying static-dissipative properties.
United States
FDA wearable device approvals create specification demand for hypoallergenic medical-grade adhesive films with 7-day wear duration in transdermal patch applications. Ohio and California anchor North American label stock capacity with integrated film manufacturing. Midwest coating plants convert regulatory emissions liability into circular chemistry credentials through closed-loop distillation systems.
Self-Adhesive Films Market Competitive Landscape
Capability concentration sits with patent-rich specialty chemical houses; scale advantage sits with integrated film manufacturers serving commodity label stock. The market structures around three tiers: multinational adhesive formulators with polymer synthesis expertise, integrated film converters with captive coating capacity, and regional label stock specialists. Consolidation pressure runs through qualification-heavy segments where dual certification timelines extend product launch cycles. Competitive moves center on solvent recovery technology deployment and ASEAN greenfield extrusion investments.
Within the multinational specialty tier, 3M and Nitto Denko Corporation exemplify patent-anchored positioning in high-temperature electronics applications. Avery Dennison Corporation occupies a position among integrated North American label stock manufacturers with Ohio and California production assets. H.B. Fuller Company represents the adhesive formulator archetype supplying coating operations across multiple film substrates. These three anchors illustrate how competitive position stratifies between chemistry ownership, manufacturing integration, and specification authority rather than unit cost alone.
| Leading Market Players |
|---|
| Lintec Corporation |
| Toray Industries |
| 3M |
| Nitto Denko Corporation |
| H.B. Fuller Company |
| Avery Dennison Corporation |
| Henkel AG & Co. KGaA |
| UPM-Kymmene Oyj |
| LG Hausys |
| Others |
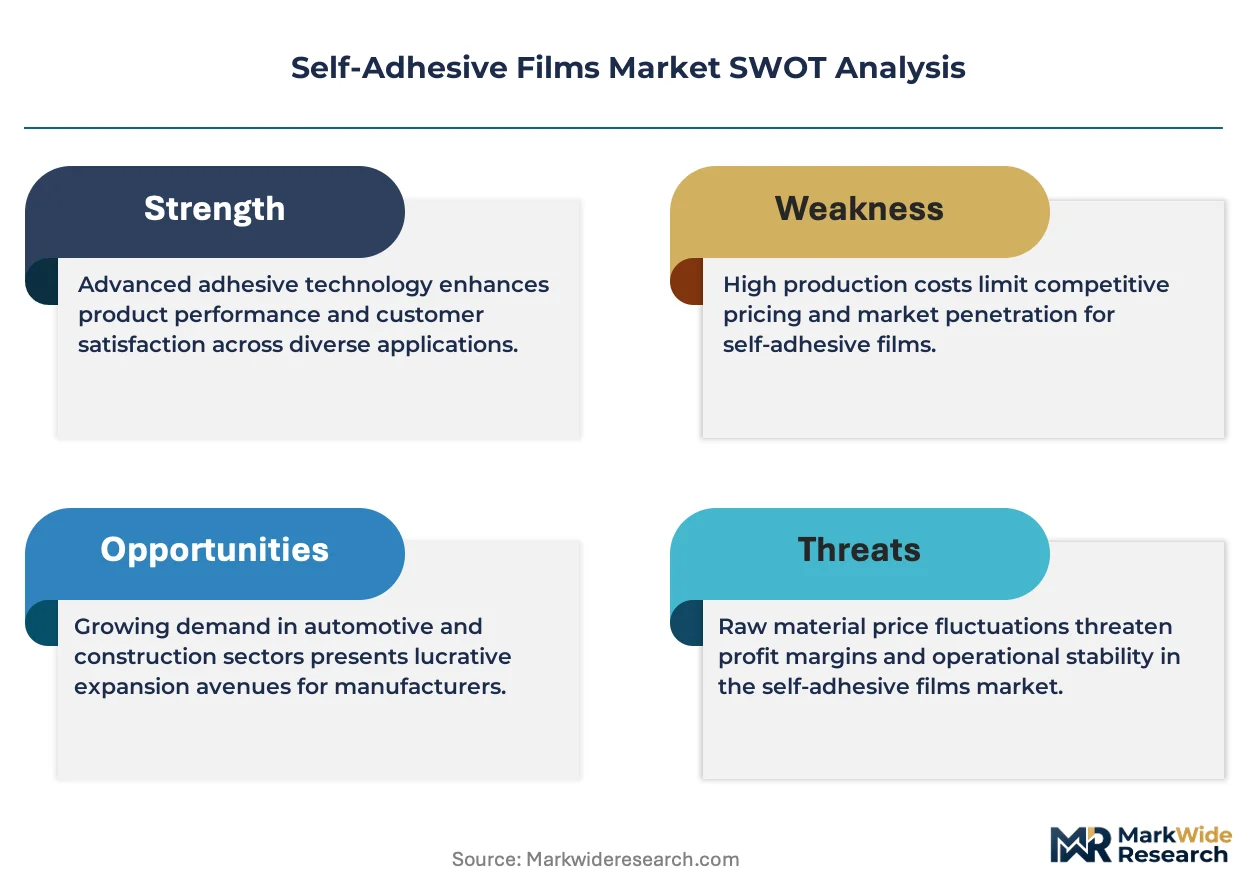
Value Network & Pricing Analysis
Scandinavian pulp mills and German specialty paper plants concentrate release liner production, anchoring margin pools in silicone-coated substrates that filter downstream to coating operations across three continents. Acrylic monomer pricing swings with crude oil indices, compressing visibility for extrusion-dependent manufacturers while certification-heavy segments capture qualification premiums.
Pricing Analysis
Price spreads between German automotive-grade films and Southeast Asian commodity label stock exceed threefold, reflecting divergence in thermal cycling certification investment. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade hypoallergenic formulations from logistics labeling. Cost compression in commodity polypropylene extrusion is intensifying because of petrochemical feedstock volatility. Packaging converters exhibit highest price sensitivity; EV battery enclosure procurement teams prioritize flame barrier documentation over unit cost.
Supply Chain Analysis
Export-control regimes on silicone-catalyst technology limit liner coating equipment flows from German engineering centers to emerging Asian producers. Supply concentrates in China, Japan, and South Korea for optical-grade protective films; acrylic monomer and polypropylene resin dependencies feed from petrochemical complexes in the Middle East and US Gulf Coast. Single-source vulnerability runs through Scandinavian pulp mills for release liner substrate. Distribution runs through integrated film converters with captive coating capacity serving multinational OEM direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV battery thermal runaway containment specifications are compressing qualification timelines, creating a high-growth disruption window for adhesive film suppliers with certified high-temperature acrylic portfolios. This technological inflection favors chemistry ownership over commodity scale.
For Market Incumbents: Build certification moats around dual REACH-GB standard compliance to extend product launch cycle advantages over emerging competitors. Accelerate solvent recovery technology deployment in European coating plants to convert emissions liability into circular chemistry credentials. Consolidate specification authority by acquiring regional label stock specialists with established automotive OEM relationships. For New Entrants and Emerging Players: Establish a beachhead in Vietnam extrusion serving ASEAN electronics assembly migration with lower labor cost structures than Chinese coastal provinces. Target biodegradable film development for European extended producer responsibility mandates in premium food packaging. Pursue white-label coating partnerships with established liner suppliers to bypass capital-intensive multiline investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solventless hot-melt coating retrofit programs as nitrogen-inerted extrusion heads displace legacy solvent-based lines. Target acquisition candidates with integrated film manufacturing and captive adhesive synthesis capabilities. Monitor SAMR enforcement action frequency in Guangdong and Jiangsu provinces as inflection indicator for Chinese supply consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Synthesis | Captive supply of pressure-sensitive polymer feedstock insulates margin from petrochemical volatility. |
| Solvent Recovery Technology Deployment | Closed-loop distillation systems convert EU emissions liability into Green Deal procurement credentials. |
| Dual Certification Investment | Simultaneous REACH and GB standard compliance extends product launch cycle barriers against competitors. |
| Vietnam Extrusion Greenfield | Multilayer film capacity near Ho Chi Minh City captures ASEAN electronics assembly migration. |
| Medical-Grade Hypoallergenic Formulation Development | FDA wearable device approvals create specification demand for seven-day wear duration films. |
Research Methodology
Initial hypotheses were tested against primary input from coating plant managers, automotive OEM procurement leads, adhesive formulation chemists, and medical device regulatory affairs directors and refined through secondary validation. Trade data from customs authorities, SEC filings of integrated film manufacturers, REACH registration databases, and SAMR enforcement records anchored supply-side characterization. Bottom-up capacity modeling and top-down demand aggregation triangulated volume estimates across the analysis window.
Demand-supply balance dynamics shaped the analytical framework across adhesive chemistry, film substrate, and end-use application dimensions. CAGRs were derived from segment-level growth rate synthesis calibrated to macroeconomic drivers and regulatory inflection points. Modeled inputs included EV battery enclosure specification velocity, display panel manufacturing capacity expansion in Gyeonggi province, and biodegradable film certification scheme adoption curves.
Stress conditions across acrylic monomer price volatility, SAMR enforcement intensity, and automotive OEM qualification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding petrochemical feedstock stability and dual certification timeline standardization. Material shifts in EU battery safety regulation stringency or China emissions enforcement posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Microwavable Barrier Films Market
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
Flow Pack Films Market
Packaging Barrier Films
Perforated Packaging Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Global Heat Sealable Packaging Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Cryogenic Insulation Films Market
Packaging Barrier Films
Barrier Coated Papers Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Barrier Tube Packaging Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market