
 Retail E Commerce Packaging Market | 2026-2036
Retail E Commerce Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Retail E Commerce Packaging Market Intelligence
The divergence between custom-branded, sustainable packaging and standardized, low-cost mailers is restructuring competitive dynamics. Premium solutions focus on unboxing experience and material circularity. Smurfit Kappa Group specializes in paper-based solutions, while Sealed Air Corporation leads in protective packaging innovations. Amcor plc leverages its scale to serve large B2C platforms with a diverse material portfolio.
Retail e-commerce packaging refers to primary and secondary containers engineered for the direct-to-consumer shipment of goods. These materials must meet specific performance criteria, such as edge crush test (ECT) ratings for corrugated boxes, to ensure product integrity during transit. Corrugated boxes made from cardboard represent the largest material segment due to their structural integrity and recyclability. The B2C customer type, particularly within the fashion vertical, drives demand for custom-sized mailers and envelopes that enhance brand presentation.
Regulatory frameworks increasingly shape material selection and design choices for e-commerce packaging. In the United States, EPA guidelines on recycling influence material composition, while the EU Green Deal promotes circular economy principles. China’s GB standards for packaging materials also set strict performance and safety requirements. Navigating the trade-offs between material cost, protective performance, and regulatory compliance remains the central challenge for shippers and converters.
Market Dynamics
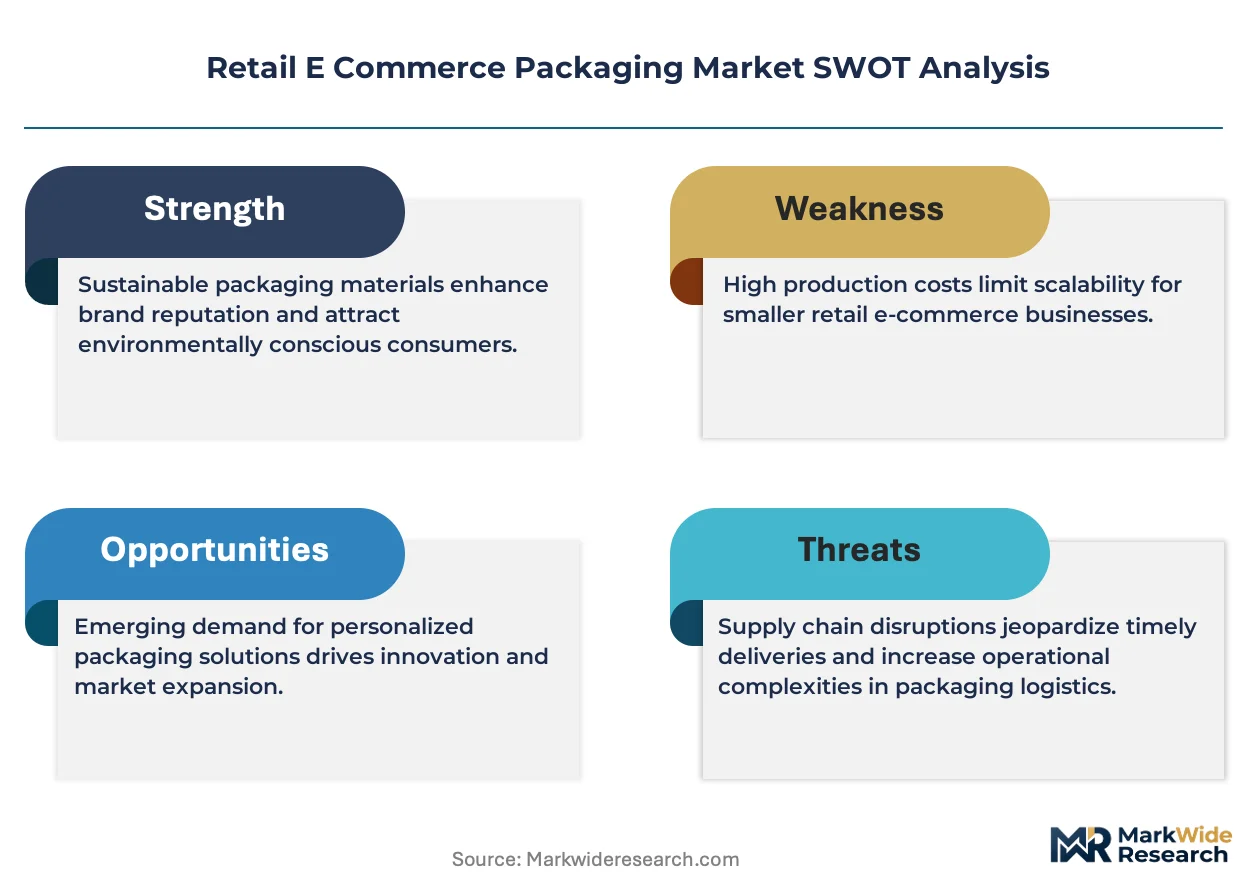
The central tension in the retail e-commerce packaging market is the trade-off between sustainability mandates and cost pressures. This dynamic forces shippers and converters to balance the demand for circular, brand-enhancing materials against the operational realities of high-volume, low-cost fulfillment.
Growth Catalysts
- Fashion Vertical Expansion:The direct-to-consumer fashion segment's emphasis on unboxing experiences stimulates demand for custom-printed boxes and mailers that reinforce brand identity and perceived value.
- Circular Economy Frameworks:Regulations like the EU Green Deal are accelerating the transition to mono-material, easily recyclable packaging, creating a strong pull for innovative paper and bio-plastic solutions.
- Digital Retail Infrastructure:China's mature e-commerce ecosystem and vast logistics networks support high-volume demand for standardized yet protective packaging solutions like corrugated boxes and poly mailers.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of raw materials, particularly recycled paper pulp and kraftliner, create margin pressure for corrugated box converters and shippers.
- Regulatory Fragmentation:Navigating disparate standards, such as EU packaging waste directives, US EPA guidelines, and China's GB standards, complicates global product design and supply chain management.
- Substitution from Reusables:The emergence of reusable packaging-as-a-service models presents a structural threat to the dominant single-use packaging business model, especially in closed-loop systems.
Strategic Opportunities
- Smart Packaging Integration:Incorporating QR codes or NFC tags into packaging offers a channel for brand storytelling, authentication, and providing consumers with detailed recycling instructions.
- Fiber-Based Protective Solutions:Developing high-performance, molded pulp or paper-based alternatives to plastic air pillows and foam inserts addresses a key sustainability gap in protective packaging.
- Subscription Box Specialization:Designing modular and curated packaging systems for the subscription box industry caters to a niche requiring consistent branding and a premium unboxing experience.
Industry Challenges
- Scale vs. Customization:Shippers face the operational challenge of balancing the cost efficiencies of standardized box sizes with the marketing benefits and waste reduction of on-demand, right-sized packaging.
- Recycling Infrastructure Gaps:The effectiveness of recyclable packaging designs is often undermined by the lack of adequate sorting and processing facilities at the municipal level in many regions.
- Performance Testing for New Materials:Ensuring that emerging sustainable materials meet established performance benchmarks, such as edge crush test (ECT) ratings, requires extensive and costly validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail E Commerce Packaging Market |
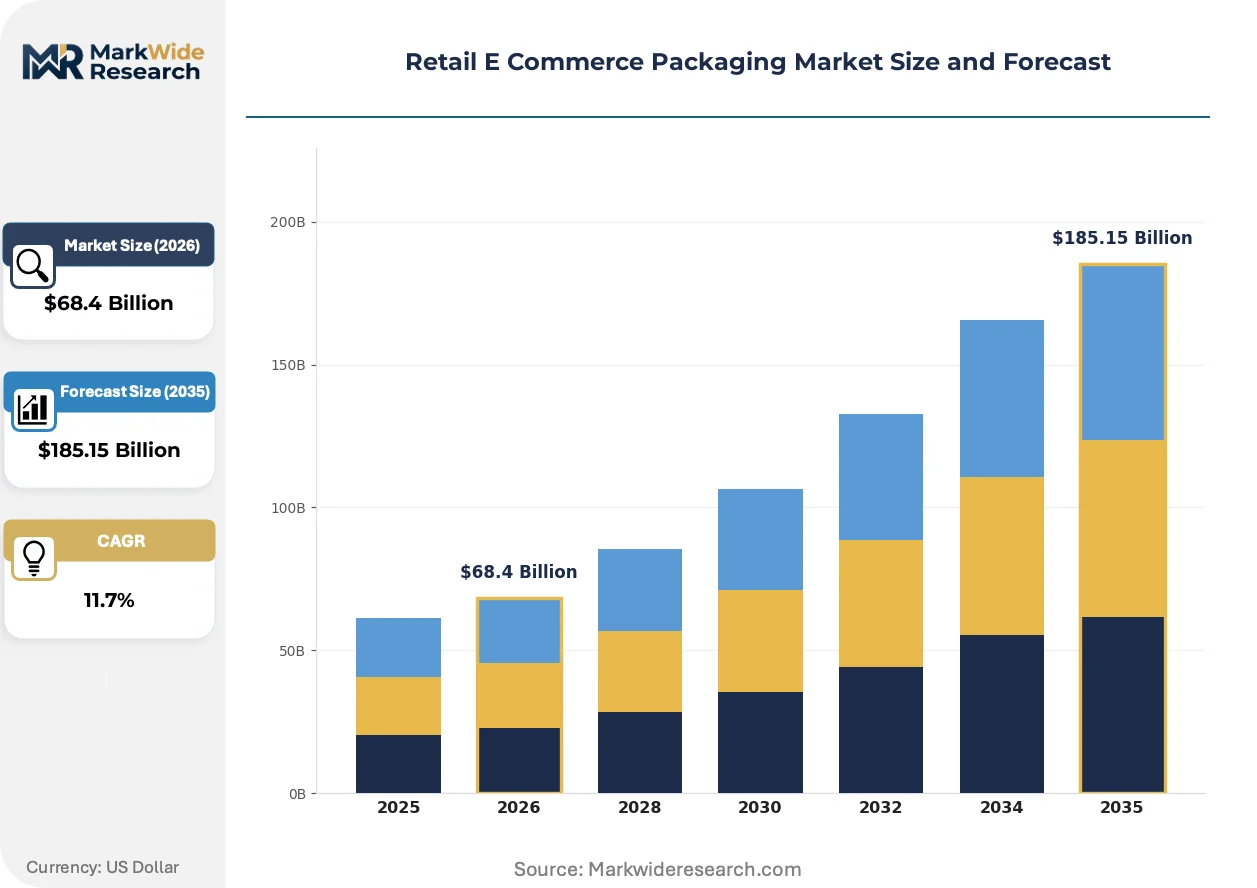
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Box, Mailer, Polybag, Envelope Material: Cardboard, Kraft Paper, Bubble Wrap, Plastic Customer Type: B2C, B2B, Consumer Electronics, Fashion Size: Small, Medium, Large, Custom |
| Companies Covered | International Paper Company, DS Smith plc, Mondi plc, Sealed Air Corporation, WestRock Company, Smurfit Kappa Group, Packaging Corporation of America, Amcor plc, Berry Global Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail E Commerce Packaging Market Strategic Shifts & Innovations
Material science and digital automation are converging to address the market's core demands for sustainability and personalization. Innovations focus on reducing material waste through intelligent design while enhancing brand engagement through the package itself, moving it beyond a simple container.
On-demand, right-sizing technology utilizes automated systems to create a custom-fit box for each order. Major B2C fulfillment centers are adopting this to cut down on void fill materials and reduce dimensional weight shipping charges. This automation is unifying the previously separate objectives of cost efficiency and material sustainability by minimizing both corrugated board consumption and plastic filler waste.
Extended Producer Responsibility (EPR) schemes, particularly those advanced under the EU Green Deal, are gaining global traction. These policies make brands financially responsible for the end-of-life management of their packaging, directly impacting cost structures. The electronics and consumer goods verticals are most affected, prompting a design shift toward mono-materials and packaging with established, low-cost recycling pathways.
A behavioral shift toward circularity is driving interest in reusable packaging through service-based models. This disrupts the conventional single-use mailer channel by introducing a closed-loop system of delivery, customer return, and centralized cleaning for reuse. This trend is most prominent in dense urban centers in Europe, especially for apparel brands and beauty subscription services.
Retail E Commerce Packaging Market Segmentation
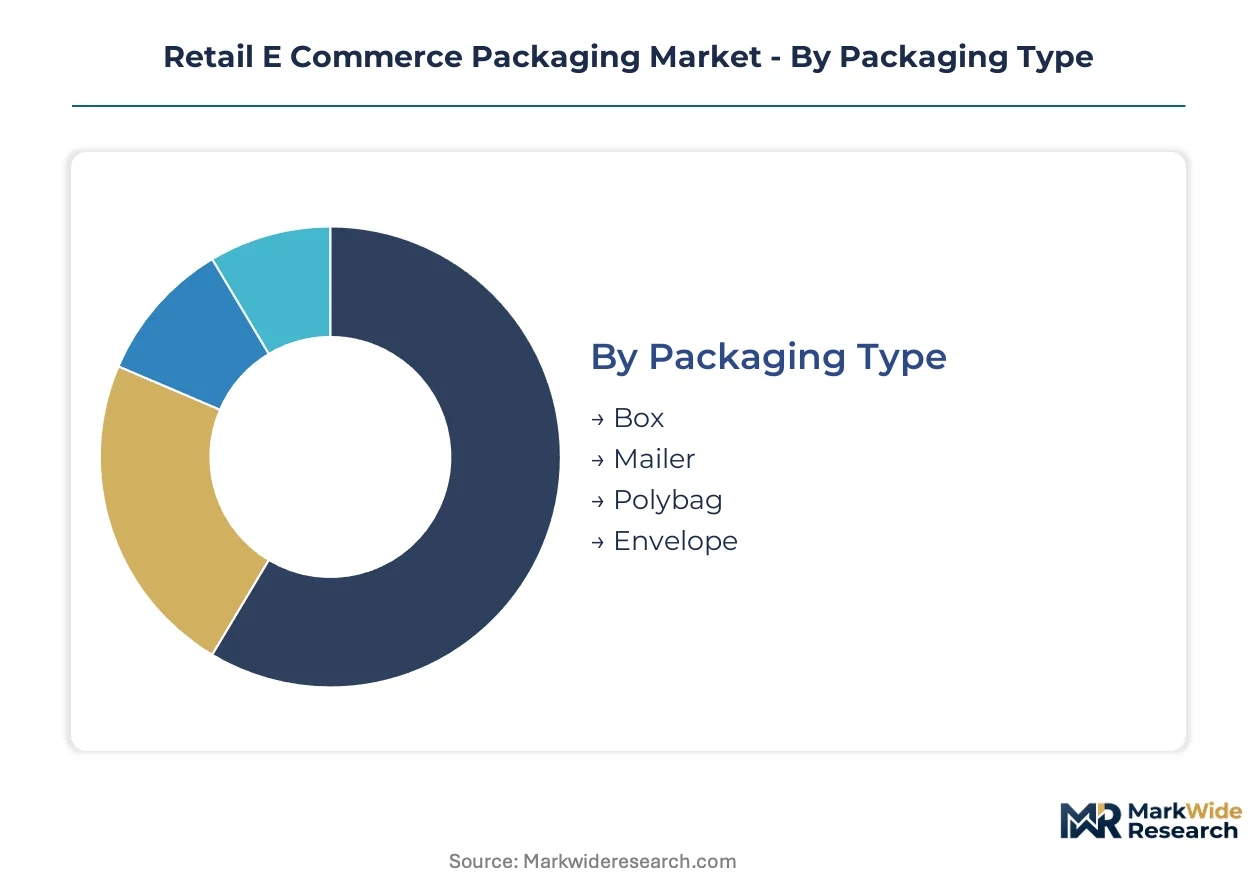
Market segmentation clarifies the diverse requirements for retail e-commerce packaging, revealing where specific material science and design innovations deliver the most impact. Understanding these distinct segments allows stakeholders to align product development with evolving consumer expectations and regulatory mandates. This granular view informs strategic resource allocation across the value chain.
Packaging Type:
The supply of packaging types is concentrating around solutions that balance protective performance with material efficiency for direct-to-consumer shipments.
- Box:These primary or secondary containers, often corrugated, provide structural integrity and product protection during transit. Demand concentrates in general merchandise and electronics, where edge crush test (ECT) ratings ensure goods arrive undamaged.
- Mailer:Flexible or semi-rigid envelopes, frequently custom-printed, enhance brand presentation and reduce dimensional weight. The fashion vertical drives significant demand for mailers that reinforce brand identity through unboxing experiences.
- Polybag:Lightweight, flexible plastic bags offer basic protection against moisture and dust for non-fragile items.
- Envelope:Typically paper-based, envelopes are used for documents, small flat items, and apparel, prioritizing low cost and ease of shipping.
Box absorbs the bulk of installed capacity; Mailer is expanding most quickly.
Material:
Material selection for e-commerce packaging is increasingly driven by a combination of protective performance, cost, and circular economy principles.
- Cardboard:Corrugated cardboard, derived from paper pulp, provides robust structural support and high recyclability. Demand is concentrated across all e-commerce categories due to its versatility and established recycling infrastructure in markets like China.
- Kraft Paper:This strong, durable paper is used for mailers, void fill, and as a component in corrugated board, offering a sustainable, mono-material solution. Its use is expanding in Europe due to EU Green Deal initiatives promoting easily recyclable materials.
- Bubble Wrap:Lightweight plastic sheeting with trapped air bubbles offers cushioning and impact resistance for fragile goods.
- Plastic:Various polymers are used for polybags, protective films, and some mailers, valued for moisture resistance and durability.
The material segment is differentiated by functional properties, with Cardboard consistently holding significant volume.
Customer Type:
Customer type segmentation highlights the varied demands for packaging functionality and brand engagement across different e-commerce models.
- B2C:Business-to-consumer packaging focuses on brand experience, ease of opening, and returns functionality for individual shoppers. This type drives demand for custom-sized mailers and premium unboxing solutions within the fashion vertical.
- Fashion:This specialized B2C segment prioritizes aesthetic appeal, custom branding, and sustainable material choices to align with brand values. Demand for custom-printed boxes and mailers is particularly strong here, emphasizing the unboxing experience.
- B2B:Business-to-business e-commerce packaging emphasizes bulk protection, logistical efficiency, and cost-effectiveness for larger shipments between companies.
- Consumer Electronics:Packaging for electronics requires high protective performance against shock and static, often incorporating specialized inserts.
B2C dominates volume requirements, while Fashion dictates specific design innovation.
Size:
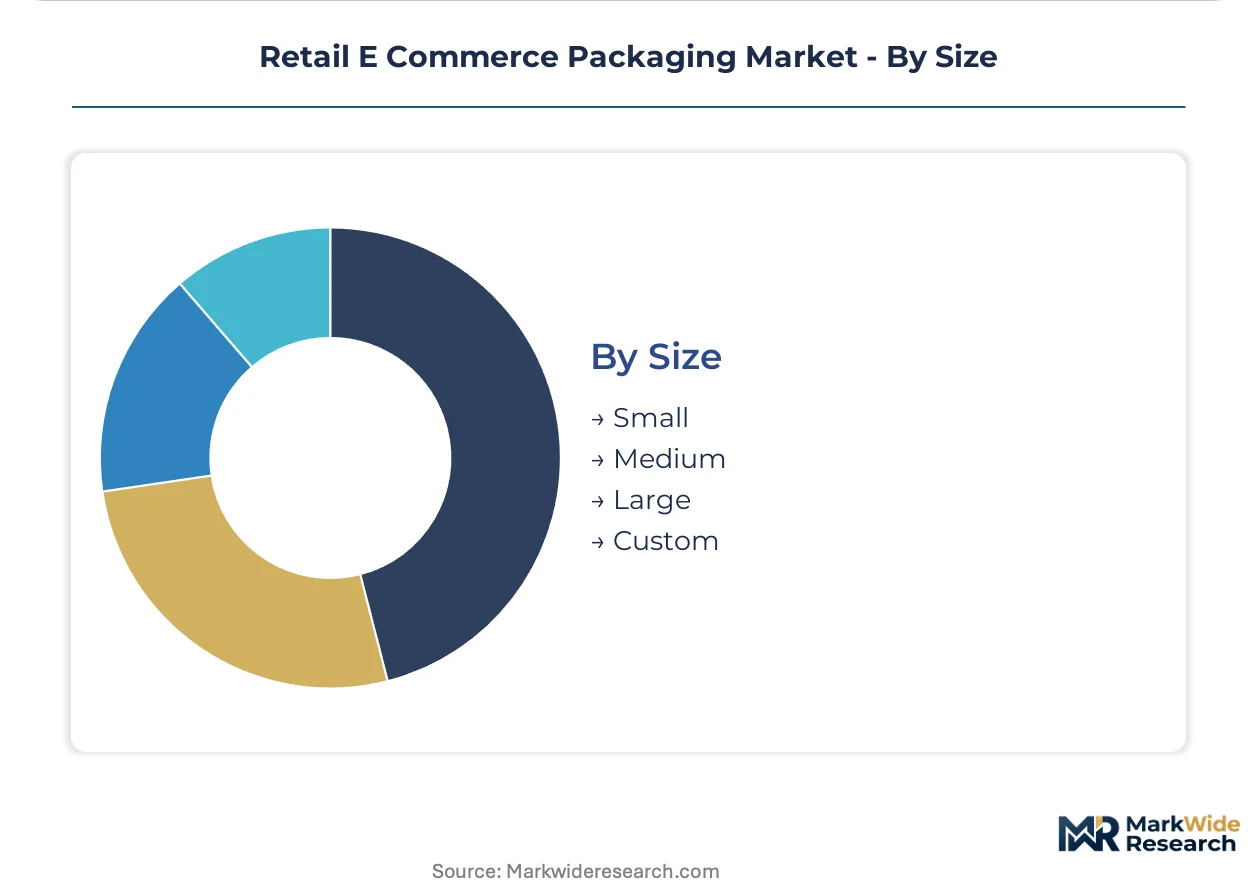
Packaging size considerations address both product fit and shipping cost optimization, especially regarding dimensional weight calculations.
- Custom:Packaging designed specifically for product dimensions minimizes void fill and enhances brand presentation, reducing shipping costs. The subscription box industry and fashion brands show high demand for custom-sized solutions that improve the unboxing experience.
- Large:These packages accommodate bulky or multiple items, requiring robust construction and efficient handling. Demand for large packaging is significant in furniture e-commerce and bulk goods shipments, where protective performance is paramount.
- Small:Compact packaging is ideal for small, lightweight items, optimizing shipping costs and material usage.
- Medium:Standardized medium-sized options serve a broad range of products, balancing cost-effectiveness and protective qualities.
Standardized sizes enable operational efficiencies, but Custom solutions offer a distinct market advantage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen, a prominent digital retail hub, drives significant e-commerce packaging innovations. This city's robust logistics infrastructure supports the rapid growth of online commerce. Regional dynamics reflect varied consumer preferences and regulatory landscapes.
United States
The United States' B2C market, particularly the fashion and subscription box segments, fuels demand for custom-sized mailers. EPA guidelines on recycling influence material composition and design choices. California's tech and e-commerce sector in Silicon Valley continuously seeks innovative, sustainable packaging solutions.
China
China's vast digital retail infrastructure supports high-volume demand for protective packaging solutions. The nation's GB standards for packaging materials set strict performance and safety requirements. The Yangtze River Delta region, including Shanghai, serves as a critical hub for e-commerce fulfillment and packaging production.
Germany
German consumers and regulations emphasize circular economy principles, accelerating demand for mono-material and easily recyclable packaging. The EU Green Deal directly promotes sustainable material innovation across the supply chain. Logistics hubs around Frankfurt and Leipzig are central to distributing eco-friendly packaging solutions.
United Kingdom
The United Kingdom's fashion e-commerce segment prioritizes unboxing experiences and sustainable material choices. Extended Producer Responsibility (EPR) schemes are gaining traction, making brands financially accountable for packaging waste. London's vibrant e-commerce and fashion brands frequently drive demand for premium, custom-branded solutions.
India
India's expanding e-commerce penetration, driven by a growing middle class, creates substantial demand for cost-effective and protective packaging. The country's national packaging waste management rules are gradually shaping material selection. Bengaluru's burgeoning tech and e-commerce logistics sector is a focal point for packaging innovation.
Retail E Commerce Packaging Market Key Industry Players
Premium-margin players sit above commodity-margin players across material innovation and customization services. The market exhibits a tiered structure, with global conglomerates competing against specialized regional providers. Strategic archetypes include integrated paperboard producers, protective packaging innovators, and diversified material suppliers. Dominant competitive moves involve strategic partnerships for sustainable solutions and capacity expansion in fiber-based materials.
Within the integrated paperboard production tier, Smurfit Kappa Group and WestRock Company exemplify extensive fiber-based packaging portfolios. Sealed Air Corporation occupies a position as a leading protective packaging innovator, focusing on cushioning solutions. Amcor plc represents a diversified material supplier, leveraging its scale to serve large B2C platforms globally.
| Leading Market Players |
|---|
| International Paper Company |
| DS Smith plc |
| Mondi plc |
| Sealed Air Corporation |
| WestRock Company |
| Smurfit Kappa Group |
| Packaging Corporation of America |
| Amcor plc |
| Berry Global Group, Inc. |
| Others |
Cost & Logistics Intelligence
Kraftliner futures, a key benchmark for paper-based packaging, significantly influence retail e-commerce packaging pricing. These commodity fluctuations cascade into pricing tiers for both premium custom solutions and standardized mailers.
Pricing Analysis
Value-based pricing for custom e-commerce packaging anchors on brand presentation and unboxing experience. Pricing stratifies across premium, standard, and economy tiers, driven by customization levels and material circularity certifications. Input cost volatility, particularly for recycled paper pulp, creates margin pressure for converters. B2B customers exhibit higher price sensitivity compared to the fashion vertical, which prioritizes brand alignment.
Supply Chain Analysis
Domestic content mandates, especially those driven by the EU Green Deal, reshape sourcing for sustainable packaging materials. Supply concentrations exist in China for high-volume corrugated boxes and in Europe for innovative mono-materials like kraft paper. The market relies on paper pulp and various plastic polymers as primary inputs. Commodity price volatility for these raw materials presents a structural supply chain risk. Downstream distribution primarily runs through large B2C platforms and specialized logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market faces supply constraints, particularly in specialized sustainable material production, which props up pricing for eco-friendly packaging solutions.
For Market Incumbents: Deploy capacity addition in fiber-based materials to meet sustainability mandates. Incumbents should invest in advanced material science for molded pulp solutions to counter substitution from reusables. Strategic partnerships with recycling infrastructure developers can also mitigate future regulatory risks. Consolidating smaller, specialized sustainable packaging innovators strengthens market position.
For New Entrants and Emerging Players: Begin with specializing in subscription box packaging systems, offering consistent branding and curated unboxing experiences. Target the fashion vertical by providing custom-printed mailers that reinforce brand identity. A strong go-to-market angle involves integrating smart packaging features like QR codes for enhanced consumer engagement and recycling instructions. Focus on regions with strong circular economy principles.
For Investors and Strategic Acquirers: The window for entry favors specialized material science firms and automation providers with proven sustainable solutions. Long-term viability hinges on the global transition towards circular economy frameworks. Target acquisition profiles include innovators in fiber-based protective solutions and on-demand right-sizing technology. The signal to watch is the broader adoption and enforcement of Extended Producer Responsibility (EPR) schemes.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Fiber-Based Materials | This move addresses the growing demand for sustainable packaging options, particularly in Europe. |
| Investment in Smart Packaging Technologies | Integrating QR codes enhances brand storytelling and provides critical consumer information for recycling. |
| Acquisition of Sustainable Packaging Innovators | This strategy secures specialized expertise and intellectual property in eco-friendly material development. |
| Partnerships with Recycling Infrastructure Developers | Collaborations improve end-of-life management for packaging, supporting circular economy goals. |
| Specialization in Subscription Box Packaging | Tailoring solutions for this niche segment captures consistent demand for premium unboxing experiences. |
Research Approach
Document review covered regulatory guidelines from EPA and the EU Green Deal, industry reports on packaging materials, and e-commerce market analyses, complemented by interviews. Primary research engaged e-commerce platform executives, packaging converters, brand managers in the fashion vertical, and logistics providers. This approach ensured bottom-up market sizing and top-down validation.
The analytical model generated volume and value outputs across the analysis window, integrating various macro and microeconomic variables. Segmentation dimensions modeled included packaging type, material, customer type, size, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical trends and projected market dynamics, factoring in e-commerce penetration rates and raw material price forecasts.
Underlying measurement precision varies by segment; cardboard packaging and the B2C customer type carry tighter precision than others. Forecasts reflect assumptions regarding technological adoption and consumer behavior. Global economic slowdowns or significant shifts in regulatory enforcement could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Packaging
Retail Ready Trays Market
Retail Packaging
Retail Ready Packaging (RRP) Market
Retail Packaging
Global Shoe Packaging Market
Retail Packaging
Table Tent Market
Retail Packaging
Club Store Packaging Market
Retail Packaging
Black Friday Packaging Market
Retail Packaging
Free Standing Display Units Market
Retail Packaging
Retail Bags Market
Retail Packaging
Floor POP Display Market