
 Perforated Packaging Market | 2026-2036
Perforated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Perforated Packaging Market Analytics
Asset-light leasing models for converting equipment is tilting competitive dynamics toward mid-tier converters that previously faced capital barriers. Mondi Group leverages its integrated paper and film operations to sustain margin control across perforated bread bag lines in European retail. Sealed Air Corporation anchors its position through proprietary micro-perforation technologies that extend produce shelf life for North American grocery chains. Uflex Ltd. competes on scale, operating one of Asia's largest flexo printing and perforation facilities for export-oriented food packaging.
Perforated packaging refers to materials containing precisely engineered holes, slots, or pores—typically ranging from 50 microns to 5 millimeters in diameter—manufactured through mechanical needle punching, laser ablation, or hot-needle perforation to enable controlled gas exchange, moisture regulation, or easy-open functionality. Films dominate value generation due to their versatility in modified atmosphere packaging for respiring produce, while biodegradable materials represent the fastest-expanding material category as brand owners face retailer mandates to eliminate petroleum-based plastics. Food Packaging anchors application demand through bread, fresh-cut salad, and berry segments where oxygen transmission rates directly correlate with shelf-life extension and waste reduction targets.
The EU F-Gas Regulation and REACH framework restrict certain polymer additives used in conventional perforated films, redirecting formulation investment toward compliant mono-material structures. FDA food contact substance notifications govern perforation lubricants and anti-fog coatings in US-bound exports, creating compliance cost differentiation between regional suppliers. Stakeholders must monitor evolving extended producer responsibility schemes across multiple geographies, as fee structures for hard-to-recycle perforated multi-layers will reshape material selection decisions and supplier qualification criteria.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing converters to abandon multi-layer perforated structures in favor of mono-material and paper-based formats, compressing established supply chains while opening substitution pathways for integrated producers.
Growth Catalysts
- Fresh Produce Retail Expansion:Supermarket chains in Germany and the Netherlands are deploying perforated films for respiring vegetables and berries, directly linking oxygen transmission control to spoilage reduction targets.
- REACH Compliance Investment:ECHA restrictions on polymer additives are redirecting R&D budgets toward compliant mono-material formulations that simplify end-of-life sorting.
- Closed-Loop Recycling Pilots:Food retailers and converters in Berlin and Hamburg are testing take-back schemes for perforated bread bags, establishing material recovery precedents.
Market Restraints
- Petrochemical Input Volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil markets, squeezing converter margins on standard perforated film grades.
- Equipment Concentration Risk:Precision laser perforation systems rely on German and Swiss machinery suppliers, creating capex bottlenecks for mid-tier converters seeking capacity expansion.
- Multi-Layer Technical Lock-In:Existing high-barrier perforated structures cannot meet EU recyclability targets without complete reformulation, stranding prior capital investment.
Strategic Opportunities
- Biodegradable Material White Space:PLA and PHA-based perforated formats command premium positioning as French and Italian retailers enforce plastic elimination timelines.
- Micro-Perforation Technology Convergence:Integration of laser ablation with inline vision inspection enables real-time pore-size adjustment for variable produce respiration rates.
- Extended Producer Responsibility Tailwinds:Germany's Verpackungsgesetz fee structures favor easily recyclable mono-material perforated bags over complex multi-layer alternatives.
Industry Challenges
- Specialized Technician Scarcity:Laser perforation equipment requires operators trained in beam calibration and thermal management, a skill set concentrated among German and Austrian engineering graduates.
- Certification Timeline Compression:FDA food contact substance notifications for new anti-fog coatings on perforated films extend qualification cycles by 12-18 months, delaying US market entry.
- Legacy System Integration Friction:Converters running mechanical needle-punch lines face retrofit complexity when adding digital process control for smart perforation patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perforated Packaging Market |
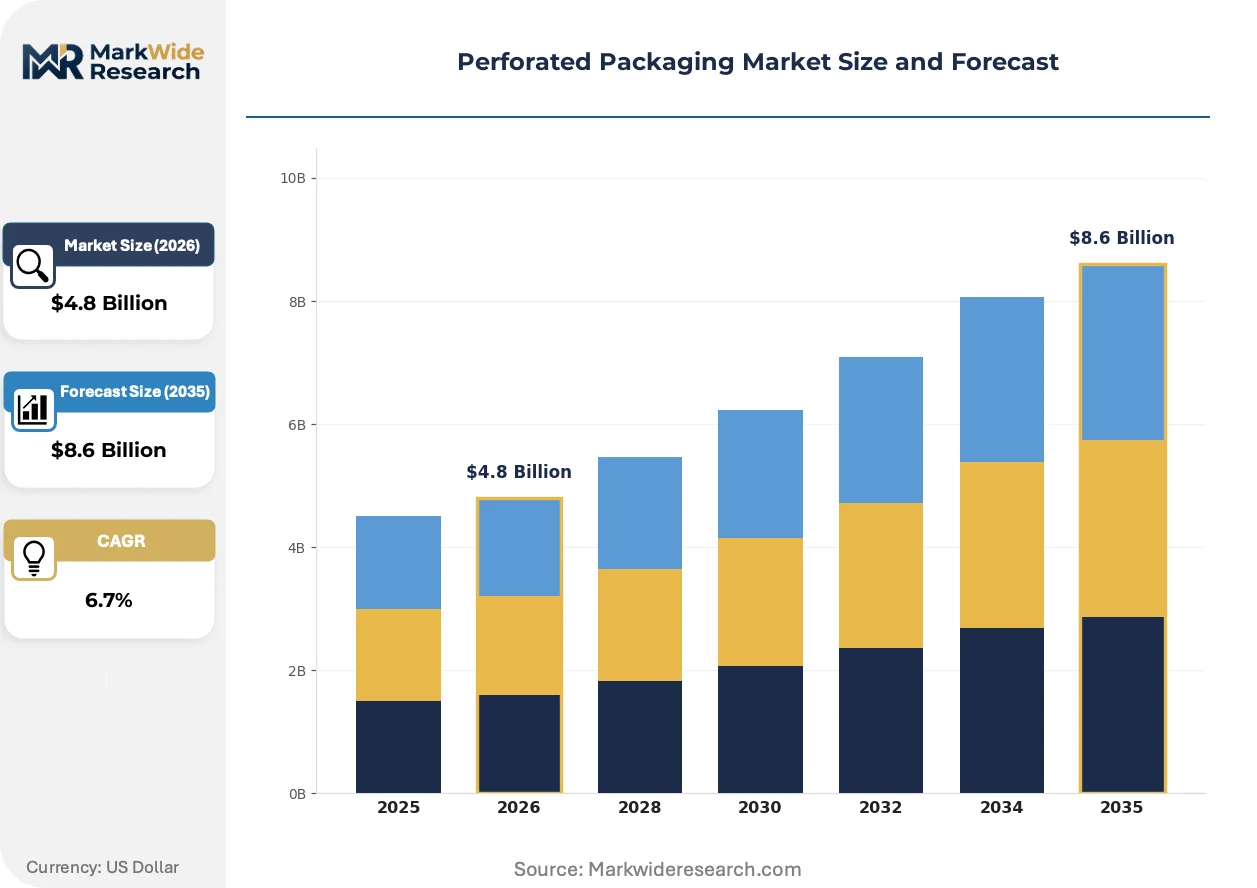
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Bags, Wraps, Sheets Material: Plastic, Paper, Aluminum, Biodegradable Application: Food Packaging, Medical Supplies, Consumer Goods, Industrial Parts End User: Manufacturers, Retailers, Healthcare Providers, Food Service |
| Companies Covered | Amcor plc, Mondi Group, Sealed Air Corporation, Berry Global Inc., Coveris Holdings, Sonoco Products Company, Uflex Ltd., TCL Packaging, Aera International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perforated Packaging Market Evolving Landscape
Perforated packaging technology is bifurcating between precision-engineered micro-perforation for premium produce and simplified mono-material structures for mass-market compliance, with regulatory pressure acting as the primary accelerant.
Hot-needle perforation with servo-controlled temperature modulation is rendering obsolete mechanical punching systems that produce inconsistent pore geometry and elevated micro-fracture rates. Berry packers in California and Spain are adopting these systems to achieve sub-50-micron tolerance bands. The technology is compressing quality differentiation between tier-one and tier-two converters by democratizing precision formerly captive to laser systems.
REACH Annex XVII restrictions on perfluorinated compounds are eliminating legacy anti-fog coatings from perforated film formulations, forcing converters to qualify bio-based surfactant alternatives. The industrial consequence is a 24-month reformulation cycle for bread bag producers supplying EU retailers. German packaging converters are responding by consolidating coating supply relationships to secure compliant material streams ahead of enforcement deadlines.
Retail procurement teams are consolidating perforated film suppliers from 8-10 regional vendors to 3-4 integrated partners capable of certifying full material provenance. This concentration is displacing spot-market purchasing for standardized produce bags in French and Benelux supermarket chains. The shift is most visible in the fresh-cut salad segment, where Carrefour and Albert Heijn now mandate blockchain-tracked mono-material sourcing.
Perforated Packaging Market Segmentation
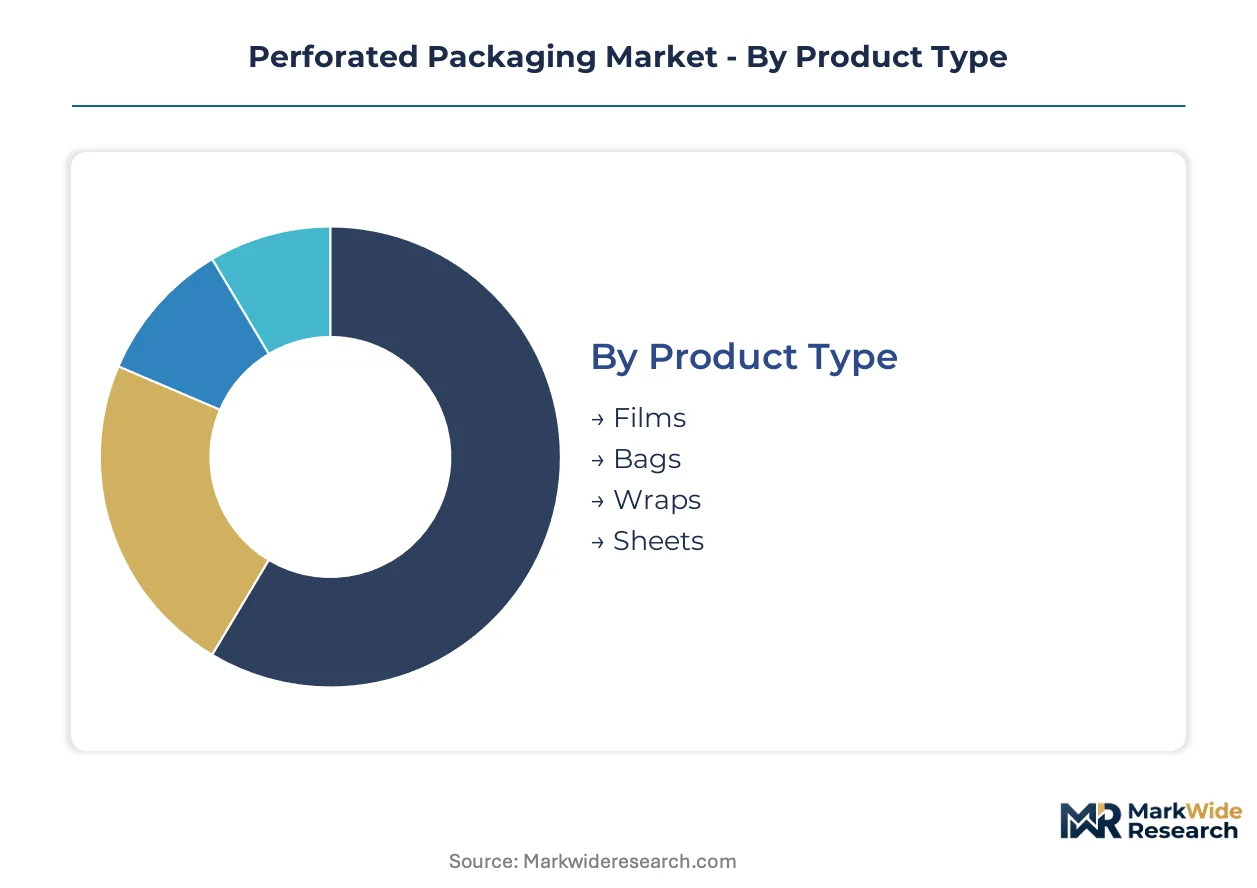
Perforated packaging segmentation reveals how technical specifications, material compliance, and end-use requirements fragment supply capabilities across converter tiers. Equipment retrofit costs and regulatory qualification timelines create divergent margin structures within each category.
Product Type:
After-sales service intensity varies sharply across product types, with precision perforation systems demanding specialized maintenance contracts that favor suppliers with regional technician networks.
- Films:Multi-layer and mono-material films with laser or hot-needle perforation dominate modified atmosphere packaging for respiring produce. German retailers specify oxygen transmission rate tolerances within 5% variance for berry and fresh-cut salad applications, compressing supplier qualification pools.
- Bags:Pre-formed perforated bags for bread and vegetables require heat-seal integrity alongside pore precision. Closed-loop recycling pilots in Berlin and Hamburg focus on mono-material bag formats, establishing collection infrastructure precedents.
- Wraps:Stretch wraps with directional perforation patterns serve palletized produce ventilation. California berry packers specify micro-perforation density by SKU.
- Sheets:Flat perforated sheets interleave industrial components or medical devices. Swiss machinery suppliers dominate laser perforation equipment for sub-50-micron tolerance bands.
By volume, Films leads. By growth pace, Bags is ahead.
Material:
Material selection now hinges on end-of-life fee structures under extended producer responsibility schemes rather than unit cost alone.
- Plastic:Polypropylene and polyethylene films with mechanical or laser perforation anchor current volume. ECHA REACH restrictions on polymer additives are forcing 24-month reformulation cycles for EU-bound production.
- Paper:Kraft and glassine papers with needle perforation gain share in bread bag applications. French retailers enforce plastic elimination timelines that accelerate paper substitution.
- Aluminum:Laminated foil structures with micro-perforation serve high-barrier medical and industrial segments. Complex multi-layer constructions face recyclability compliance pressure.
- Biodegradable:PLA and PHA-based perforated formats command premium positioning. Italian supermarket chains mandate biodegradable alternatives for produce packaging.
Plastic holds the volume base. Biodegradable formats are expanding most quickly.
Application:
Application segmentation tracks divergent regulatory exposure, with food contact compliance timelines stretching 12-18 months for new coating formulations.
- Food Packaging:Modified atmosphere packaging for bread, berries, and fresh-cut salads where oxygen transmission correlates directly with shelf-life extension. Dutch supermarket chains link spoilage reduction targets to perforated film procurement specifications.
- Medical Supplies:Sterile barrier systems with controlled gas exchange for device packaging. FDA food contact substance notifications govern perforation lubricants and anti-fog coatings.
- Consumer Goods:Easy-open perforated features for personal care and household products. Brand owners specify tear-initiation force tolerances.
- Industrial Parts:Corrosion-inhibiting perforated wraps for automotive and aerospace components. VCI additive compatibility constrains material selection.
Food Packaging dominates volume. Medical Supplies shows the steepest expansion trajectory.
End User:
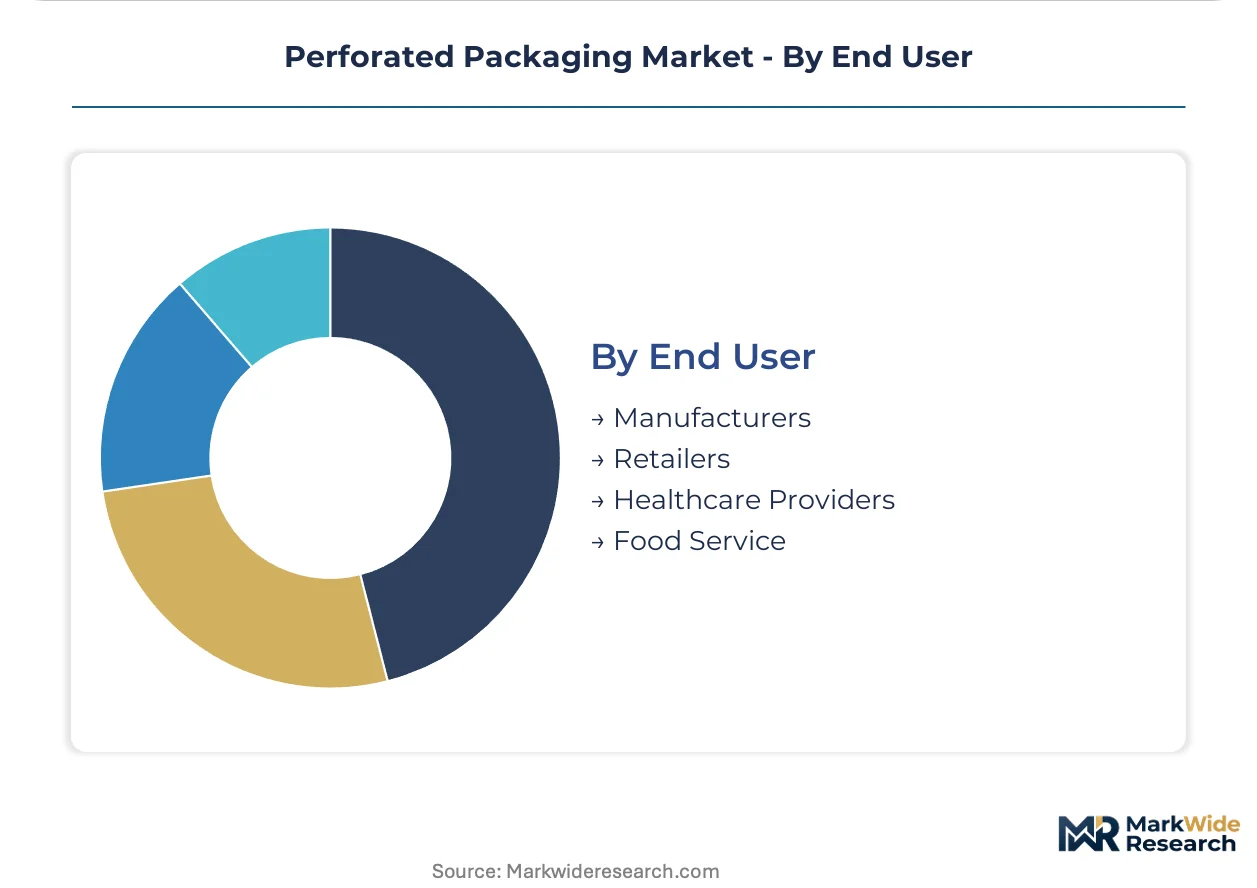
End-user concentration patterns determine converter salesforce deployment, with retail procurement consolidation favoring integrated suppliers over regional specialists.
- Manufacturers:Industrial converters and food processors specifying perforated materials for downstream packaging operations. Automotive tier suppliers in Germany demand VCI-compatible perforated films with documented batch traceability.
- Retailers:Supermarket chains consolidating supplier bases from 8-10 regional vendors to 3-4 integrated partners. Carrefour and Albert Heijn mandate blockchain-tracked mono-material sourcing for fresh-cut salad segments.
- Healthcare Providers:Hospital systems and medical device sterilization facilities specifying sterile barrier perforated packaging. FDA notification requirements extend qualification cycles.
- Food Service:Restaurant chains and catering operations using perforated bags for prepared food ventilation. Quick-service operators specify cost-optimized mechanical perforation.
Retailers command the largest volume pull. Healthcare Providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in perforated packaging track divergent regulatory timelines, with European converters importing precision equipment while Asian manufacturers export standardized film grades to price-sensitive markets.
Germany
Fresh produce retail chains in Berlin and Hamburg specify oxygen transmission tolerances within 5% variance for berry applications. The Verpackungsgesetz fee structures favor easily recyclable mono-material formats over multi-layer alternatives. Converters in the Hamburg metropolitan area operate closed-loop recycling pilots for perforated bread bags with retail partners.
United States
California berry packers demand micro-perforation density calibrated by SKU for palletized produce ventilation. FDA food contact substance notifications govern perforation lubricants and anti-fog coatings, extending qualification cycles by 12-18 months. Precision laser perforation equipment concentrates in Midwestern converting clusters serving North American grocery chains.
China
Domestic food processors specify cost-optimized mechanical perforation for quick-service restaurant supply chains. The country's national packaging standards authority tightens material recovery targets, redirecting investment toward mono-material structures. Converting capacity clusters in the Yangtze River Delta serve export-oriented fresh produce packaging demand.
France
Supermarket procurement teams consolidate perforated film suppliers from 8-10 regional vendors to 3-4 integrated partners capable of certifying full material provenance. Retailers enforce plastic elimination timelines that accelerate paper substitution in bread bag applications. The Île-de-France region anchors converter technical service networks for precision perforation systems.
India
Export-oriented food packaging demand drives flexo printing and perforation facility investment in Gujarat and Maharashtra. The country's central food safety regulator mandates compliance timelines for food contact materials that compress supplier qualification windows. Converters in the Ahmedabad industrial corridor supply perforated formats to Middle Eastern retail chains.
Perforated Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around integrated material producers and precision technology specialists, with mid-tier converters facing equipment financing barriers. Three strategic archetypes dominate: diversified packaging conglomerates with captive polymer supply, regional specialists leveraging asset-light leasing models for laser perforation capacity, and biodegradable material pioneers capturing premium positioning. Competitive moves center on backward integration into resin formulation and strategic partnerships with retail chains for closed-loop collection infrastructure.
Within the diversified conglomerate tier, Amcor plc and Mondi Group exemplify integrated producers controlling margin structures across European retail supply chains. Sealed Air Corporation anchors the precision technology vector through proprietary micro-perforation capabilities. Uflex Ltd. occupies a scale-driven position among Asia-based converters serving export markets. Berry Global Inc. and Coveris Holdings represent mid-cap specialists consolidating regional supplier bases. Sonoco Products Company and TCL Packaging sit within the industrial and consumer goods application segments respectively.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi Group |
| Sealed Air Corporation |
| Berry Global Inc. |
| Coveris Holdings |
| Sonoco Products Company |
| Uflex Ltd. |
| TCL Packaging |
| Aera International |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese mechanical perforation lines is compressing spot-market margins for standard film grades while concentrating pricing power among German and Swiss precision equipment operators serving EU retail compliance mandates.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels differentiated by perforation precision tolerance and REACH compliance certification. Price differentiation hinges on oxygen transmission rate variance guarantees and after-sales service bundling for laser system maintenance. Cost compression in standard-grade mechanical perforation is intensifying because resin price volatility and Asian import competition squeeze converter margins. Quick-service restaurant supply chains exhibit highest price sensitivity, while German supermarket procurement teams prioritize certified mono-material provenance over unit cost.
Supply Chain Analysis
Contract manufacturing for precision laser perforation systems concentrates in German and Swiss machinery suppliers, with secondary capacity in Austrian engineering clusters. Raw material dependencies draw from Saudi and Qatari polyethylene feedstock, German optical components, and Chinese servo motor assemblies. Single-source vulnerability in precision laser optics creates supply chain risk given limited qualified secondary sources. Distribution runs through converter-direct relationships for large retail accounts and regional distributors for mid-tier food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The perforated packaging market is entering a cyclical recovery phase as EU regulatory enforcement tightens and retail procurement consolidation accelerates replacement demand for compliant formats.
For Market Incumbents: Entrench positioning through backward integration into mono-material resin formulation and captive coating supply chains. Add precision laser capacity in Hamburg and Berlin corridors to serve closed-loop recycling pilot demand. Defend against biodegradable substitute threats by accelerating PLA/PHA certification timelines ahead of French and Italian retailer mandates.
For New Entrants and Emerging Players: Pursue white-space opportunities in biodegradable perforated formats for Italian supermarket chains and asset-light leasing models for mid-tier converters in India. The most penetrable segment is export-oriented food packaging serving Middle Eastern retail chains from Gujarat and Maharashtra facilities. Lead with blockchain-tracked material provenance as the go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision perforation equipment lessors with regional technician networks. Long-term viability centers on converters with integrated paper and film operations capable of margin control across regulatory cycles. Target acquisition archetypes include German mid-tier specialists with Verpackungsgesetz-compliant mono-material qualifications. Watch laser perforation equipment order backlogs as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive supply of REACH-compliant mono-materials secures margin control against ECHA additive restrictions. |
| Precision Laser Capacity Expansion | Hot-needle and laser systems in Hamburg corridor serve Berlin retail closed-loop pilots with sub-50-micron tolerance. |
| Biodegradable Material Certification | PLA and PHA qualification ahead of French retailer plastic elimination timelines commands premium positioning. |
| Blockchain-Tracked Provenance Systems | Carrefour and Albert Heijn mandates for fresh-cut salad sourcing require transparent material documentation. |
| Regional Technician Network Buildout | German and Austrian engineering graduate scarcity creates defensive moat for equipment lessors with trained service teams. |
Research Methodology
Operator-level perspectives from laser perforation equipment operators, converter plant managers, retail procurement leads, and coating formulation chemists anchored the qualitative base. Primary interview findings triangulated against ECHA REACH restriction filings, EU Packaging and Packaging Waste Regulation impact assessments, German Verpackungsgesetz fee structure documentation, and customs trade data for polyethylene and polypropylene resin flows. Bottom-up volume estimates from equipment installation records and top-down demand modeling from retail packaging specifications were cross-validated.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling demand trajectories by material type, product format, application segment, and regional regulatory cluster. CAGRs derived from segmented growth rate analysis incorporating equipment capacity expansion timelines, retailer mandate enforcement dates, and resin price elasticity assumptions. Industry-specific forecast inputs included oxygen transmission rate specification tightening by German retail chains and biodegradable material substitution curves driven by French and Italian plastic elimination timelines.
Macroeconomic conditions sit as an overlay; deviation in crude oil price volatility, euro-dollar exchange rates, or EU regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding equipment adoption curves and retailer compliance timelines. Quarterly review of laser perforation equipment order backlogs, ECHA restriction enforcement announcements, and German retail closed-loop pilot expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Barrier Materials Market
Packaging Barrier Films
Global Adhesive Films Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Global Silicone Release Liner Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Cryogenic Insulation Films Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
Hydrocolloid Coating Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Sealant Web Films Market
Packaging Barrier Films
Packaging Barrier Films Market
Packaging Barrier Films
Disposable Barrier Sleeves Market