
 South America Solar Control Window Films Market | 2026-2036
South America Solar Control Window Films Market Size, Share, and Industry Trends Forecast 2026-2036
South America Solar Control Window Films Market Analytics
The gap between premium ceramic-nanotechnology films and commodity dyed products is expanding across South America. 3M leverages its multi-layer optical film expertise to command positions in high-specification commercial projects. Eastman Chemical Company sustains supply continuity through captive polyester substrate production. Garware Suncontrol competes on cost-adjusted performance for mid-market residential rollouts in Brazilian state capitals.
Solar control window films are thin polymer laminates, typically polyethylene terephthalate-based with vapor-deposited metal or ceramic oxide layers, engineered to reject infrared radiation while maintaining visible light transmission for glazing systems. Dyed films retain volume leadership across price-sensitive residential retrofits, though margin pools concentrate in ceramic films where thermal rejection specifications command premium positioning. Advanced nanotechnology segments capture accelerated specification rates among architects targeting LEED-equivalent certification for commercial towers in Santiago and Buenos Aires.
Brazil's INMETRO certification requirements and Argentina's IRAM building efficiency standards shape product compliance thresholds for imported films. ANVISA oversight of adhesive formulations influences material selection for automotive OEM supply contracts. Chile's Ministry of Energy efficiency labeling program drives specification shifts toward measured solar heat gain coefficient performance rather than nominal tint ratings. Stakeholders must monitor evolving Mercosur technical barriers to trade negotiations, as harmonized testing protocols would reshape competitive access across the customs union.
Market Dynamics
Brazilian municipal mandates for commercial envelope performance are compressing specification timelines while ceramic-nanotechnology films capture margin pools from commodity alternatives across the Southern Cone.
Growth Catalysts
- INMETRO certification expansion:Brazil's national quality institute tightened testing protocols for solar heat gain coefficient claims, forcing specification upgrades in new São Paulo commercial towers.
- Santiago municipal energy codes:Chile's capital now mandates solar control glazing for structures exceeding specified floor plates, directly pulling ceramic film volumes.
- Automotive OEM thermal management:Argentine assembly plants serving Mercosur markets now specify infrared-rejecting films for cabin climate load reduction.
Market Restraints
- Polyester substrate concentration:Captive supply chains at Eastman Chemical and select Asian producers limit independent converter margin flexibility.
- Import duty volatility:Mercosur's external tariff negotiations on polymer laminates create landed cost uncertainty for distributors in Montevideo and Asunción.
- Performance verification gaps:Infrared rejection claims lack harmonized third-party testing across Brazilian state capitals, slowing specification decisions.
Strategic Opportunities
- Colombian high-altitude construction:Bogotá's elevation intensifies ultraviolet exposure, creating unmet demand for spectrally-selective films in residential retrofits.
- ANVISA automotive adhesive pathway:Simplified regulatory routes for cabin-interior materials open OEM supply contracts to qualified importers.
- Photovoltaic-integrated glazing:Building-integrated solar projects in Atacama require compatible solar control layers, converging two film applications.
Industry Challenges
- Nanoparticle dispersion expertise:Ceramic oxide coating uniformity demands specialized vapor deposition technicians scarce in regional converter facilities.
- IRAM-INMETRO dual certification:Argentine and Brazilian testing divergence forces duplicate sample submissions, extending product launch timelines.
- Legacy dyed film inventory:Distributor stockpiles of commodity tint products resist write-downs, blocking shelf space for premium alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Solar Control Window Films Market |
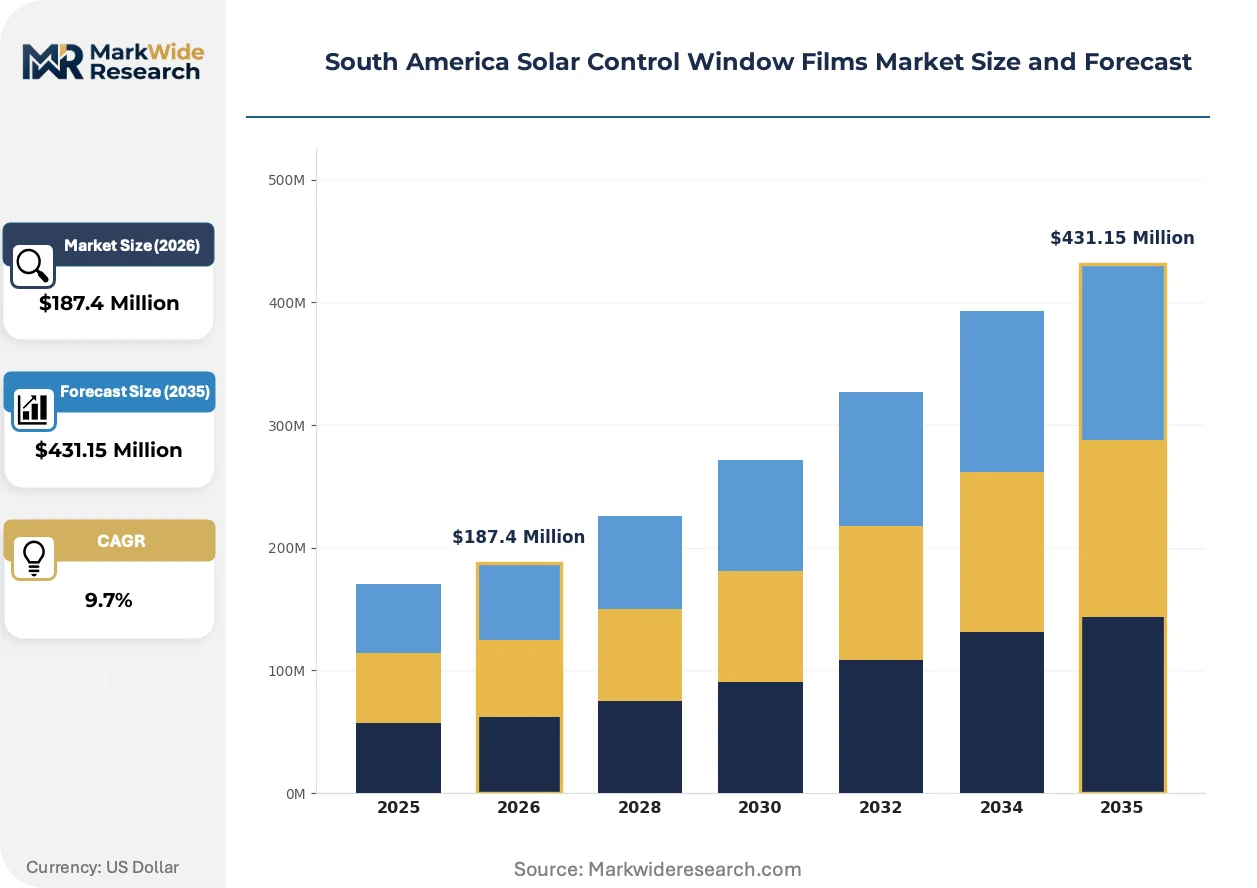
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dyed Films, Reflective Films, Ceramic Films, Clear Films Application: Residential, Commercial, Automotive, Marine Technology: Analog Coating, Digital Print, Advanced Nanotechnology, Hybrid Solutions End User: Builders, Architects, Contractors, Automotive Manufacturers |
| Companies Covered | Polytronix Inc, Garware Suncontrol, 3M, Johnson Window Films Inc., Madico, Saint-Gobain Performance Plastics Corporation, Purlfrost Ltd, Avery Dennison Israel Ltd, Eastman Chemical Company, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Solar Control Window Films Market Evolving Landscape
Material science advances and regulatory precision are collapsing the traditional performance-price tradeoff, while procurement patterns shift toward verified thermal metrics rather than visual tint preferences.
Multi-layer sputtered ceramic stacks are automating specification decisions for architects targeting LEED-equivalent certifications in Buenos Aires commercial developments. These films reject infrared wavelengths through precisely deposited metal oxide interference layers rather than absorption. Large-scale glazing contractors now default to ceramic specifications where municipal codes mandate measurable solar heat gain coefficients.
Chile's Ministry of Energy efficiency labeling program now requires published solar heat gain coefficient values on all distributed window film products. This policy eliminates nominal tint ratings as a basis for procurement across Santiago, Valparaíso, and Concepción construction markets. Distributors have responded by discontinuing unlabeled inventory and retraining sales staff on thermal performance metrics.
Building managers in São Paulo's commercial corridor now contract directly with certified installers rather than sourcing through general construction suppliers. This disintermediation compresses project timelines and shifts margin capture toward application specialists with INMETRO-accredited measurement capabilities. The pattern is replicating in Rio de Janeiro and Belo Horizonte as municipal inspection regimes tighten.
South America Solar Control Window Films Market Segmentation
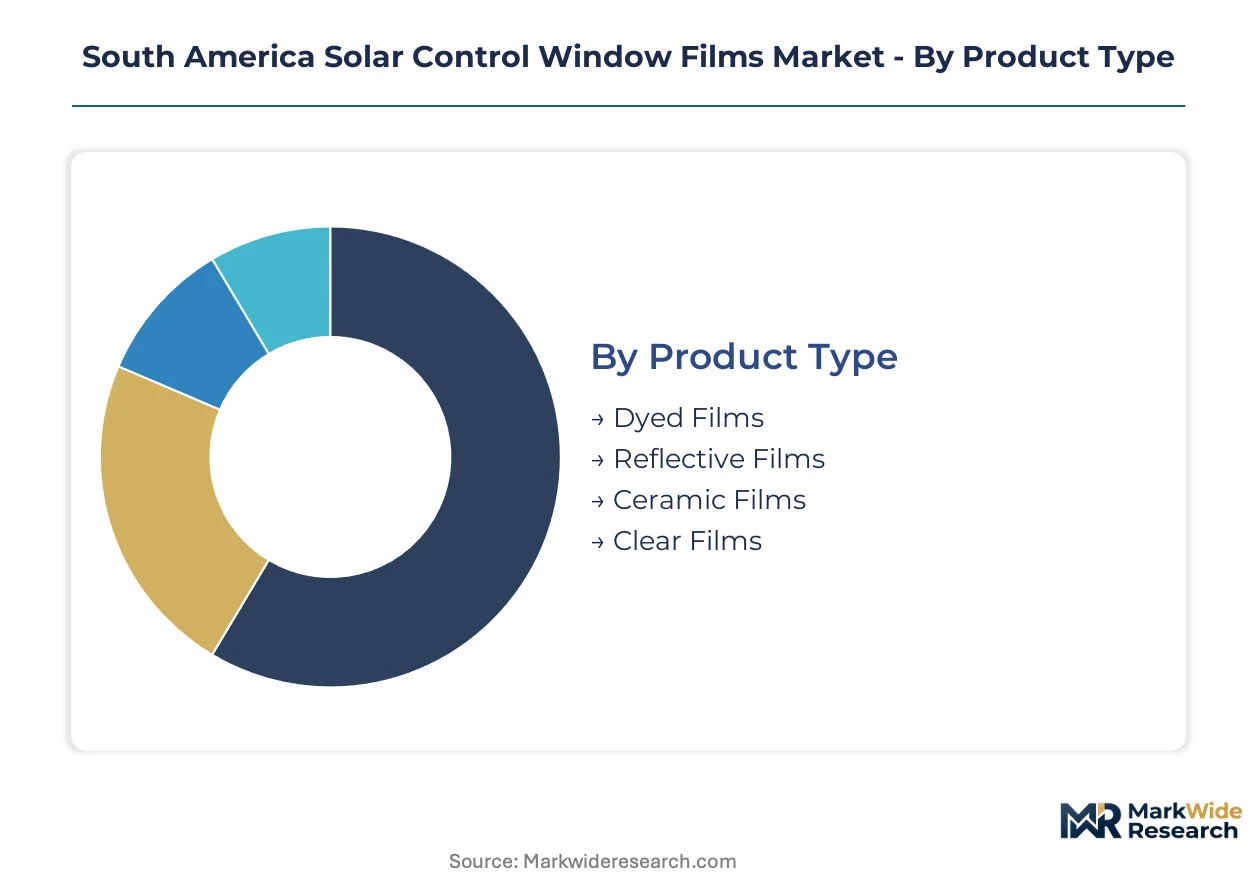
Segmentation in South America solar control window films reveals how ceramic-nanotechnology specifications are displacing commodity alternatives across Brazilian commercial construction corridors. The market stratifies along performance tiers that map directly to municipal energy code compliance requirements in São Paulo, Santiago, and Buenos Aires.
Product Type:
Ceramic oxide deposition and spectral selectivity define the performance hierarchy across the Southern Cone glazing supply chain.
- Ceramic Films:Multi-layer sputtered metal oxide stacks reject infrared through interference rather than absorption. São Paulo municipal codes mandating measurable solar heat gain coefficients now specify these films for commercial towers exceeding threshold floor areas.
- Dyed Films:Conventional polymer substrates loaded with light-absorbing dyes retain volume leadership in Brazilian residential retrofits where price sensitivity dominates procurement decisions and INMETRO certification remains optional.
- Reflective Films:Vapor-deposited aluminum or silver layers create mirror-like exterior surfaces. Argentine coastal commercial properties deploy these for maximum solar rejection despite aesthetic tradeoffs.
- Clear Films:Spectrally selective near-infrared blockers maintain high visible transmission. Chilean Ministry of Energy labeling requirements favor these where daylight harvesting priorities conflict with thermal control.
Mature deployment sits with dyed films. Newer deployment is concentrated in ceramic films.
Application:
Building envelope regulations and automotive OEM thermal management specifications split demand across end-use categories with diverging certification requirements.
- Commercial:LEED-equivalent certification targets in Buenos Aires and Santiago drive specification of measured solar heat gain coefficient performance rather than nominal tint ratings. Large-scale glazing contractors now default to ceramic specifications.
- Automotive:ANVISA oversight of adhesive formulations shapes cabin-interior material selection for Mercosur assembly plants specifying infrared-rejecting films for climate load reduction.
- Residential:Brazilian state capital retrofits concentrate in cost-adjusted dyed films, though Bogotá's high-elevation ultraviolet exposure creates unmet demand for spectrally-selective alternatives.
- Marine:Salt-air corrosion resistance requirements favor ceramic over metallized constructions in Argentine and Chilean coastal vessel applications.
Volume concentrates in commercial construction. Steepest expansion trajectory is emerging in automotive OEM supply contracts.
Technology:
Deposition precision and coating uniformity capabilities separate regional converter competitiveness from import-dependent supply.
- Advanced Nanotechnology:Ceramic oxide nanoparticle dispersion demands specialized vapor deposition technicians scarce in regional facilities. These solutions capture accelerated specification rates among architects targeting certified commercial towers.
- Hybrid Solutions:Combinations of sputtered ceramics with selective dye loading bridge performance-price gaps for mid-market Brazilian rollouts.
- Analog Coating:Roll-to-roll dye saturation and basic metallization dominate legacy converter capacity serving commodity residential demand.
- Digital Print:Patterned deposition enables custom aesthetic applications with minimal thermal performance compromise for Santiago design-focused commercial projects.
Converter investment concentrates in analog coating capacity. Technology migration is accelerating toward advanced nanotechnology.
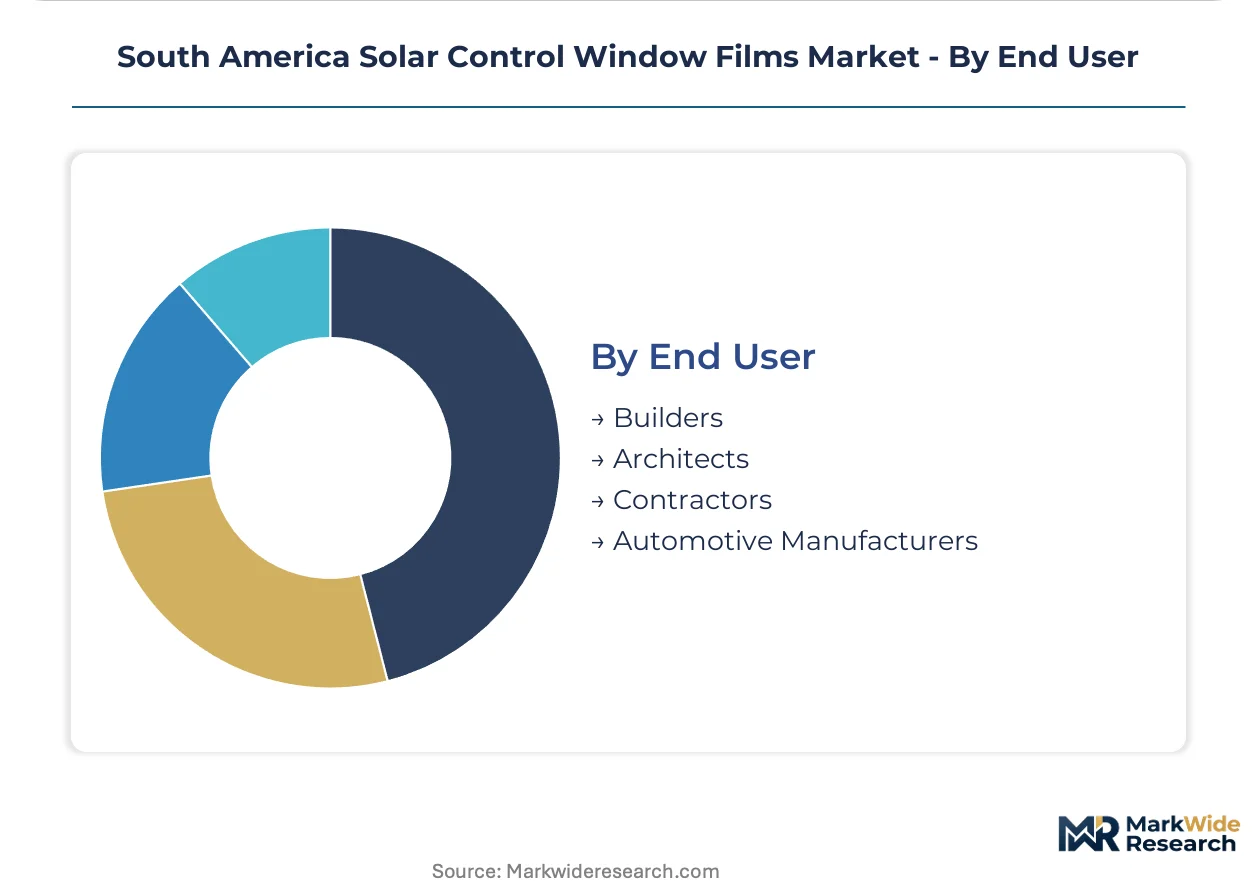
End User:
Procurement disintermediation is reshaping margin capture toward application specialists with accredited measurement capabilities.
- Architects:Specification authority for Buenos Aires and Santiago commercial towers now defaults to ceramic-nanotechnology films where municipal codes mandate verified thermal metrics.
- Builders:São Paulo commercial corridor managers increasingly contract directly with certified installers rather than sourcing through general construction suppliers.
- Contractors:INMETRO-accredited measurement capabilities determine competitive positioning for glazing installation specialists across Brazilian state capitals.
- Automotive Manufacturers:ANVISA regulatory pathway access distinguishes qualified importers for Mercosur cabin-interior supply contracts.
Traditional channel concentration sits with contractors. Specification influence is migrating fastest toward architects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors South American solar control film demand through its southeastern construction corridor, where municipal energy codes now mandate thermal performance verification for commercial towers exceeding specified floor plates.
Brazil
INMETRO certification requirements tightened testing protocols for solar heat gain coefficient claims across Brazilian state capitals. São Paulo and Rio de Janeiro municipal regulations now mandate solar control measures for new commercial towers exceeding threshold floor areas, forcing specification upgrades. The southeastern construction corridor concentrates ceramic-nanotechnology film volumes as building managers contract directly with certified installers.
Argentina
IRAM building efficiency standards shape product compliance thresholds for imported films entering Buenos Aires commercial developments. Argentine assembly plants serving Mercosur markets specify infrared-rejecting films for cabin climate load reduction. Coastal commercial properties in Mar del Plata deploy reflective metallized constructions for maximum solar rejection despite aesthetic tradeoffs.
Chile
Santiago municipal energy codes mandate solar control glazing for structures exceeding specified floor plates, directly pulling ceramic film volumes into the capital. The Ministry of Energy efficiency labeling program requires published solar heat gain coefficient values on all distributed window film products, eliminating nominal tint ratings as a procurement basis. Valparaíso and Concepción construction markets have replicated this specification shift.
Colombia
Bogotá's high-elevation position intensifies ultraviolet exposure, creating unmet demand for spectrally-selective films in residential retrofits. Colombian construction activity lags Brazilian and Chilean code stringency, though altitude-driven degradation concerns accelerate specification of ceramic alternatives over dyed films. Medellín's commercial corridor shows early adoption patterns mirroring Santiago's regulatory trajectory.
South America Solar Control Window Films Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South America's solar control film supply chain. The market structure concentrates around vertically integrated polyester substrate manufacturers and independent converter networks serving regional distribution channels. Three archetypes dominate: captive substrate producers with backward integration into resin supply, multi-layer optical specialists leveraging proprietary sputtering expertise, and cost-optimized converters competing on volume throughput. Strategic moves center on INMETRO accreditation investments and direct installer channel development bypassing general construction suppliers.
Among substrate-integrated manufacturers, Eastman Chemical Company and 3M occupy positions defined by captive supply chain control and multi-layer optical film expertise respectively. Garware Suncontrol sits within the cost-adjusted performance tier, competing for mid-market residential rollouts across Brazilian state capitals where price sensitivity dominates procurement decisions.
| Leading Market Players |
|---|
| Polytronix Inc |
| Garware Suncontrol |
| 3M |
| Johnson Window Films Inc. |
| Madico |
| Saint-Gobain Performance Plastics Corporation |
| Purlfrost Ltd |
| Avery Dennison Israel Ltd |
| Eastman Chemical Company |
| Others |
Value Network & Pricing Analysis
Multi-layer sputtered ceramic deposition is compressing production costs for high-performance films while simultaneously concentrating supply among converters with captive vapor deposition expertise. This technology migration simultaneously erodes dyed-film margins and rewards backward-integrated producers with in-house polyester substrate control across Brazil and Chile.
Pricing Analysis
Solar heat gain coefficient performance anchors value-based pricing across São Paulo and Santiago commercial specifications. Three-tier pricing structure separates INMETRO-certified ceramic films from uncertified mid-grade alternatives and commodity dyed residential products. Cost compression in dyed films is intensifying because Brazilian distributors resist inventory write-downs on legacy stock. Residential retrofit buyers in Brazilian state capitals exhibit highest price sensitivity, while Buenos Aires LEED-equivalent commercial developers show lowest.
Supply Chain Analysis
Refurbishment flows for removed metallized films remain underdeveloped across South America, creating latent circularity gaps. Polyester substrate supply concentrates in the United States, South Korea, and China, with Eastman Chemical maintaining captive resin-to-film integration. Regional converters draw from vapor-deposited metal oxides, specialized adhesives, and release liners. Single-source vulnerability sits with Asian ceramic nanoparticle suppliers. Distribution runs through certified installer networks disintermediating general construction suppliers in Brazilian state capitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward control over polyester substrate supply to escape margin compression from concentrated raw material sources.
For Market Incumbents: Cement INMETRO accreditation moats by acquiring certified measurement laboratories in São Paulo and Rio de Janeiro. Deepen captive supply of sputtering-grade ceramic oxides to offset nanoparticle dispersion bottlenecks threatening quality consistency. Defend against emerging Asian converter entrants by locking exclusive distribution through direct installer channel partnerships. For New Entrants and Emerging Players: Spectrally-selective clear films offer the most penetrable wedge into Bogotá's high-altitude residential retrofit segment, where altitude-driven ultraviolet degradation exceeds Brazilian price sensitivity. Target Colombian state capitals with simplified IRAM-equivalent certification pathways before Chilean labeling requirements replicate. Lead with daylight-harvesting value propositions rather than thermal rejection metrics. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to substrate-integrated chemical conglomerates seeking South American glazing market access. Five-to-ten-year viability hinges on regulatory harmonization across Mercosur. Acquisition targets should demonstrate ANVISA automotive adhesive pathway clearance and INMETRO dual-certification capability. Monitor Mercosur external tariff negotiation announcements as inflection signals for import-dependent distributor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| INMETRO Certification Investment | Accredited measurement capabilities unlock São Paulo commercial tower specifications and direct installer channel access. |
| Ceramic Oxide Backward Integration | In-house sputtering material production reduces nanoparticle dispersion quality risks and supplier concentration exposure. |
| Automotive OEM Supply Contract | ANVISA adhesive pathway clearance opens Mercosur assembly plant specifications for climate load reduction films. |
| Direct Installer Channel Development | Disintermediation of general construction suppliers captures margin compression from procurement pattern shifts in Brazilian state capitals. |
| Colombian Market Entry | Bogotá altitude-driven ultraviolet exposure creates unmet demand for spectrally-selective residential retrofit solutions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs across this study. Primary interviews with glazing contractors, INMETRO certification officers, architectural specification leads, and automotive OEM material buyers combined with bottom-up installation volume tracking and top-down construction spend analysis. Secondary sources included ANVISA adhesive formulation databases, Chile Ministry of Energy labeling registries, Brazilian customs polymer laminate import records, and IRAM building efficiency standard documentation.
Data-stream reconciliation across installation volume tracking, construction permit analysis, and distributor shipment records produced consistent growth trajectories across the projection horizon. Segmentation modeling incorporated product type performance tier, application end-use, deposition technology maturity, and end-user procurement authority. CAGRs derived from fitted adoption curves against municipal code implementation timelines, with ceramic film specification rates calibrated to LEED-equivalent certification penetration in Buenos Aires and Santiago commercial developments.
Several conditions sit outside the modeled scope, including Mercosur tariff harmonization outcomes, ANVISA regulatory simplification timelines, and automotive OEM platform standardization shifts. Forecasts reflect documented assumptions regarding municipal code enforcement intensity and certification cost pass-through elasticity. Practitioners should monitor INMETRO testing protocol amendments and Chilean Ministry of Energy labeling expansion announcements for early signals of specification acceleration or compliance cost spikes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Barrier Tube Packaging Market
Packaging Barrier Films
Release Liners Market
Packaging Barrier Films
Barrier Films Market
Packaging Barrier Films
Microwavable Barrier Films Market
Packaging Barrier Films
Cryogenic Insulation Films Market
Packaging Barrier Films
Packaging Barrier Films Market
Packaging Barrier Films
Cap Liner Films Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
Non Heat Sealable Film Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Global Peelable Lidding Films Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market