
 Moisture-Resistant Packaging Market | 2026-2036
Moisture-Resistant Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Moisture-Resistant Packaging Market Foresight
Pharmaceutical-grade barrier specifications is redrawing competitive boundaries in moisture-resistant packaging. Amcor leverages its integrated film manufacturing network to supply validated cold-chain formats. Sealed Air anchors North American demand through controlled-atmosphere packaging systems. Mondi specializes in recyclable barrier papers that target sustainability-driven pharmaceutical buyers.
Moisture-resistant packaging encompasses engineered enclosures designed to maintain specified humidity thresholds through multi-layer constructions incorporating metallized films, extruded polyolefins, or bio-based sealants, typically achieving water vapor transmission rates below one gram per square meter per day for sensitive payloads. Flexible packaging leads volume deployment due to material efficiency and form-factor adaptability across pharmaceutical and food applications, while biodegradable materials represent the fastest-expanding material class as ECHA REACH restrictions on conventional polymers intensify reformulation cycles. Barrier films command premium positioning where electronics manufacturers require electrostatic discharge protection alongside moisture control.
FDA stability testing protocols and EMA Annex 1 manufacturing guidelines mandate documented moisture protection for sterile pharmaceutical products, directly shaping material selection and validation requirements for packaging suppliers. EPA regulations on per- and polyfluoroalkyl substances are accelerating transitions to fluorine-free barrier chemistries across North American and European supply chains. Stakeholders must monitor evolving substance restrictions and pre-qualify alternative barrier technologies before existing formulations face regulatory sunset dates.
Market Dynamics
Pharmaceutical cold-chain validation requirements are compressing supplier qualification timelines while forcing material specification upgrades across multi-layer barrier film production networks.
Growth Catalysts
- EMA Annex 1 sterile manufacturing guidelines:Mandatory moisture documentation for parenteral drugs is expanding validated packaging procurement across European pharmaceutical corridors.
- Biologics cold-chain expansion:Temperature-sensitive monoclonal antibodies and cell therapies require vapor transmission rates below 0.5 g/m²/day, pulling high-barrier formats into oncology logistics.
- Germany's pharmaceutical manufacturing corridor:Concentrated sterile injectable production in Hesse and Baden-Württemberg generates sustained demand for pre-qualified barrier systems.
Market Restraints
- Aluminum metallized film supply concentration:Vacuum deposition capacity clusters in South Korea and Japan, creating input bottlenecks during semiconductor packaging demand surges.
- Fluoropolymer chemistry phase-outs:EPA restrictions on perfluorinated barrier coatings are forcing premature equipment write-downs at North American extrusion facilities.
- Bio-based sealant performance gaps:Polylactic acid and starch-derived alternatives fail to match polyolefin moisture resistance in accelerated aging protocols.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO harmonization with ICH stability guidelines creates demand for FDA-pre-validated barrier formats in Hyderabad and Ahmedabad clusters.
- Electronics dry-packaging convergence:Electrostatic discharge protection combined with sub-10% RH control opens semiconductor and lithium battery cell segments.
- EU Green Deal packaging waste targets:Recyclable mono-material barrier structures gain procurement preference in sustainability-mandated tenders.
Industry Challenges
- Accelerated stability testing protocols:ICH Q1A(R2) compressed timelines demand packaging validation completion within 12-18 months versus traditional 24-36 month cycles.
- Multi-layer coextrusion equipment retrofitting:Fluorine-free barrier chemistry transitions require $2-4 million line modifications with uncertain return periods.
- Cross-border qualification document harmonization:Divergent FDA, EMA, and NMPA submission requirements duplicate analytical testing expenditure for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moisture-Resistant Packaging Market |
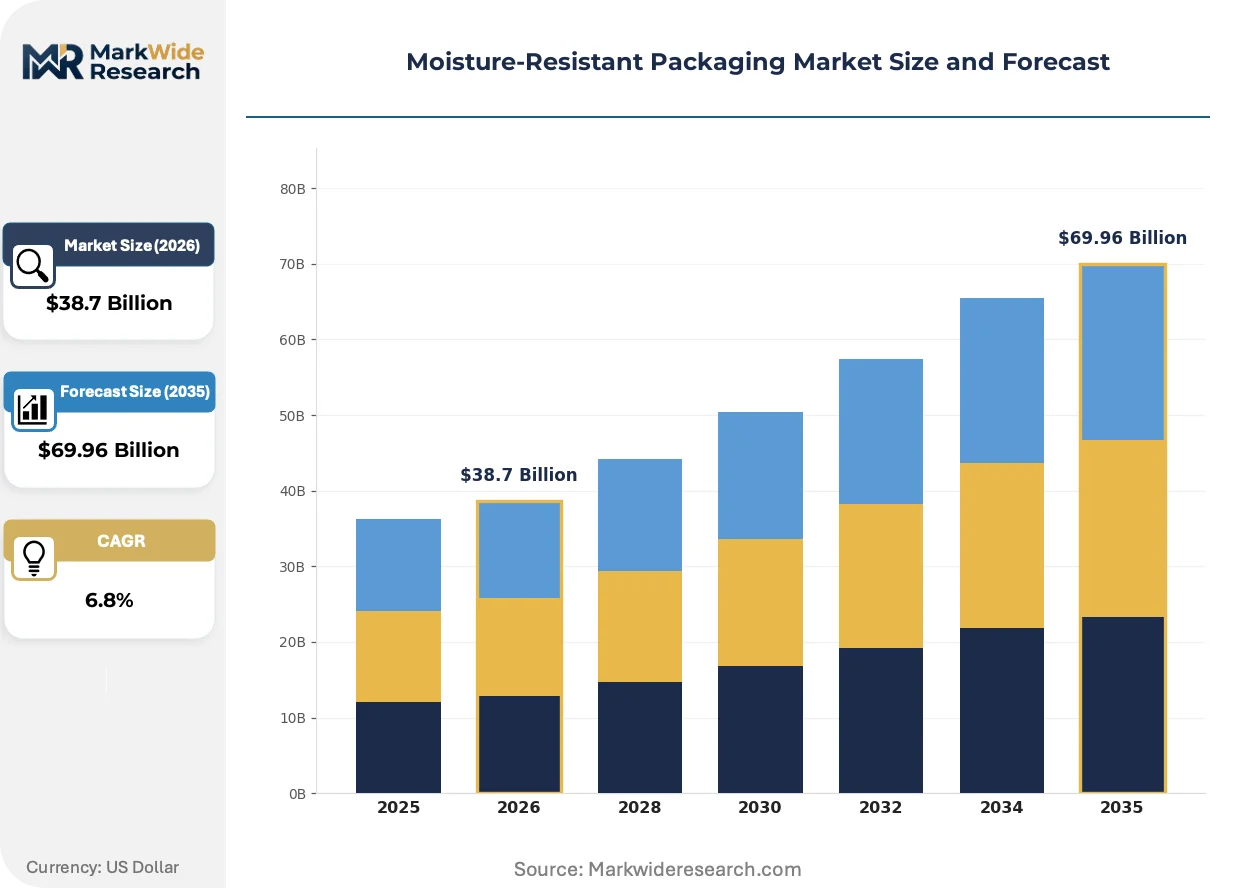
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Containers, Pouches, Barrier Films Material: Polyethylene, Polypropylene, Aluminum Foil, Biodegradable Materials End User: Food & Beverage, Pharmaceuticals, Electronics, Personal Care Application: Preservation, Transportation, Storage, Display |
| Companies Covered | Smurfit Kappa, Sonoco Products Company, Amcor, DS Smith, Westrock Company, Berry Global, Mondi, ProAmpac, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moisture-Resistant Packaging Market Shifts & Advancements
Barrier chemistry reformulation and validation protocol digitization are compressing development cycles while opening new end-use segments previously served by conventional desiccant systems.
Water-based acrylic barrier coatings with nanoclay reinforcement are achieving metallized-film vapor transmission performance at 40% lower embodied carbon. Pharmaceutical contract packagers in Switzerland and the Netherlands are qualifying these formats for oral solid dose applications. Fluoropolymer-dependent structures are supplanting legacy high-barrier formats in European sustainability-driven procurement.
EPA regulations on per- and polyfluoroalkyl substances are prohibiting fluorinated barrier chemistries in food-contact and pharmaceutical packaging by 2027. North American converters are accelerating qualification of silicon oxide and aluminum oxide plasma-deposited alternatives. Medical device sterile barrier systems face the steepest compliance timeline, with PMA supplement submissions required 18 months ahead of enforcement dates.
Direct supplier relationships with pharmaceutical quality assurance departments are displacing distributor-mediated procurement for validated cold-chain formats. Large molecule biologics manufacturers in Massachusetts and California are mandating packaging supplier access to batch release documentation. This transparency requirement concentrates purchasing power among integrated film manufacturers with captive analytical laboratories.
Moisture-Resistant Packaging Market Segmentation
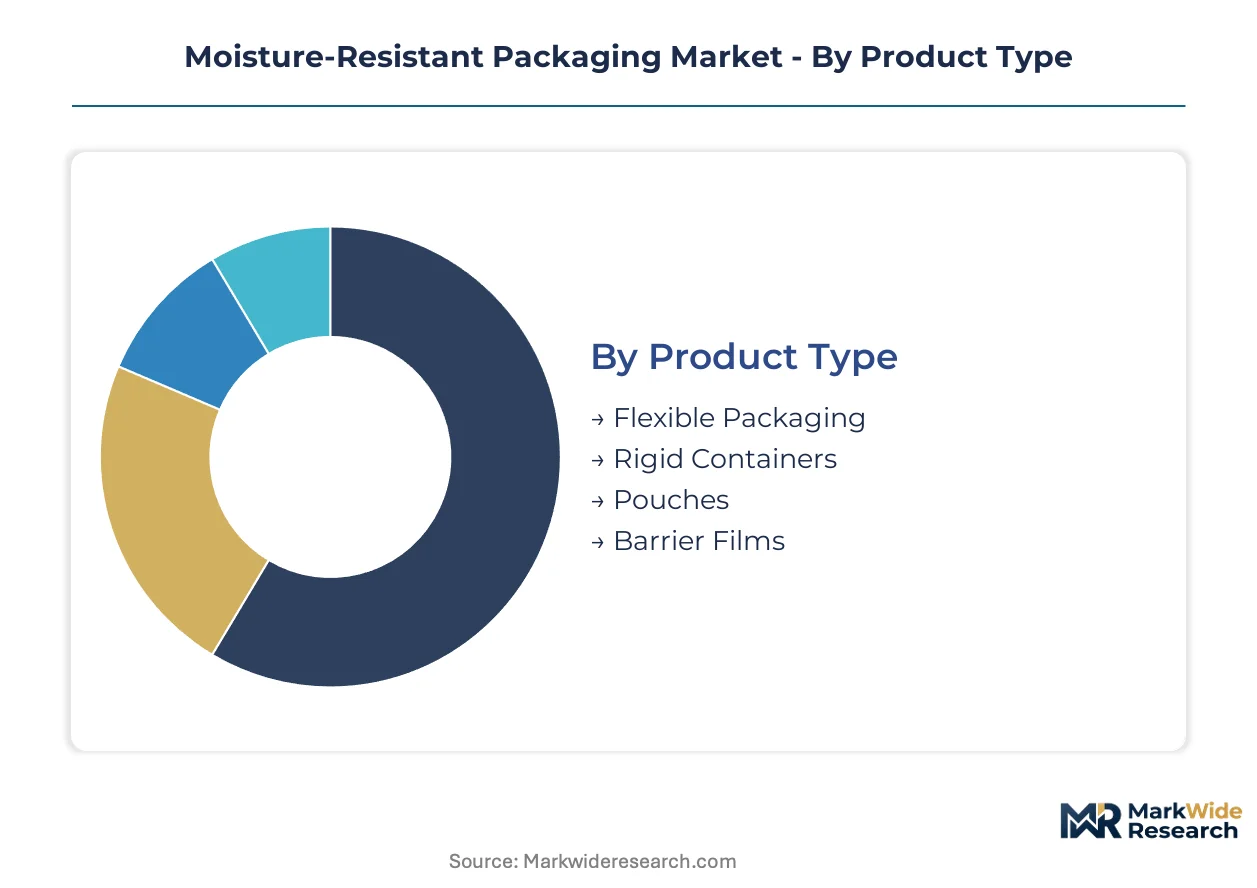
Segmentation in moisture-resistant packaging reveals how material specifications, regulatory compliance tiers, and end-use criticality determine channel access and margin capture. Understanding these divides helps suppliers align production assets with validated demand pools rather than commoditized volume segments.
Product Type:
Channel differentiation runs deepest here — pharmaceutical cold-chain formats flow through qualified supplier networks with batch documentation, while food-grade volumes move through distributor channels with minimal technical validation.
- Flexible Packaging:Multi-layer laminates incorporating metallized films or coextruded polyolefins achieve sub-1 g/m²/day vapor transmission rates. Pharmaceutical contract packagers in Switzerland and the Netherlands are qualifying these formats for oral solid dose applications where FDA stability protocols mandate documented barrier performance.
- Barrier Films:High-clarity biaxially oriented structures with silicon oxide or aluminum oxide plasma deposition serve electronics manufacturers requiring electrostatic discharge protection alongside sub-10% RH control. Semiconductor packaging demand in South Korea and Japan is pulling premium-grade capacity away from pharmaceutical allocations during supply crunches.
- Pouches:Stand-up and flat formats with resealable zipper closures dominate food retail shelf presence. European supermarket private-label programs are specifying recyclable mono-material constructions to meet EU Green Deal packaging waste targets.
- Rigid Containers:Injection-molded polypropylene jars and aluminum cans provide structural protection for moisture-sensitive powders. Personal care applications in Germany's Hesse corridor utilize these formats for hygroscopic active ingredients.
Flexible packaging dominates installed base. Barrier films are where expansion concentrates.
Material:
Cost tiers separate validated pharmaceutical grades from commodity food-contact specifications, with sustainability premiums creating a third pricing stratum.
- Polyethylene:Linear low-density and high-density grades provide the foundation for coextruded barrier structures. North American converters are accelerating fluorine-free reformulations as EPA restrictions on perfluorinated coatings approach enforcement.
- Aluminum Foil:Dead-soft annealed foils at 6-9 micron thickness deliver near-zero vapor transmission for biologics cold-chain. Vacuum deposition capacity constraints in East Asia are creating input bottlenecks during semiconductor packaging demand surges.
- Polypropylene:Cast and oriented films offer moisture resistance with optical clarity for display applications. Food & beverage preservation formats in Germany's Baden-Württemberg region specify biaxially oriented grades for extended shelf-life dairy.
- Biodegradable Materials:Polylactic acid and starch-derived alternatives are gaining procurement preference in sustainability-mandated tenders. Performance gaps in accelerated aging protocols limit penetration beyond non-critical food applications.
Polyethylene anchors volume production. Biodegradable materials are climbing the fastest.
End User:
Application criticality determines validation burden — sterile pharmaceutical barriers require 12-18 month qualification cycles versus 3-6 months for food formats.
- Pharmaceuticals:Parenteral drug packaging must document moisture protection under EMA Annex 1 and FDA stability testing protocols. CDSCO harmonization with ICH guidelines in India is creating demand for pre-validated barrier formats in Hyderabad and Ahmedabad clusters.
- Electronics:Lithium battery cells and semiconductor components require electrostatic discharge protection combined with rigorous humidity control. Dry-packaging specifications here are converging with pharmaceutical barrier standards.
- Food & Beverage:Extended shelf-life applications for snack foods and dehydrated ingredients utilize metallized film laminates. ECHA REACH restrictions on conventional polymers are intensifying reformulation cycles toward bio-based sealants.
- Personal Care:Hygroscopic active ingredients in skincare formulations demand moisture protection with premium aesthetic presentation. German manufacturing corridors concentrate demand for validated barrier systems in this segment.
Food & beverage holds volume leadership. Pharmaceuticals command the steepest expansion trajectory.
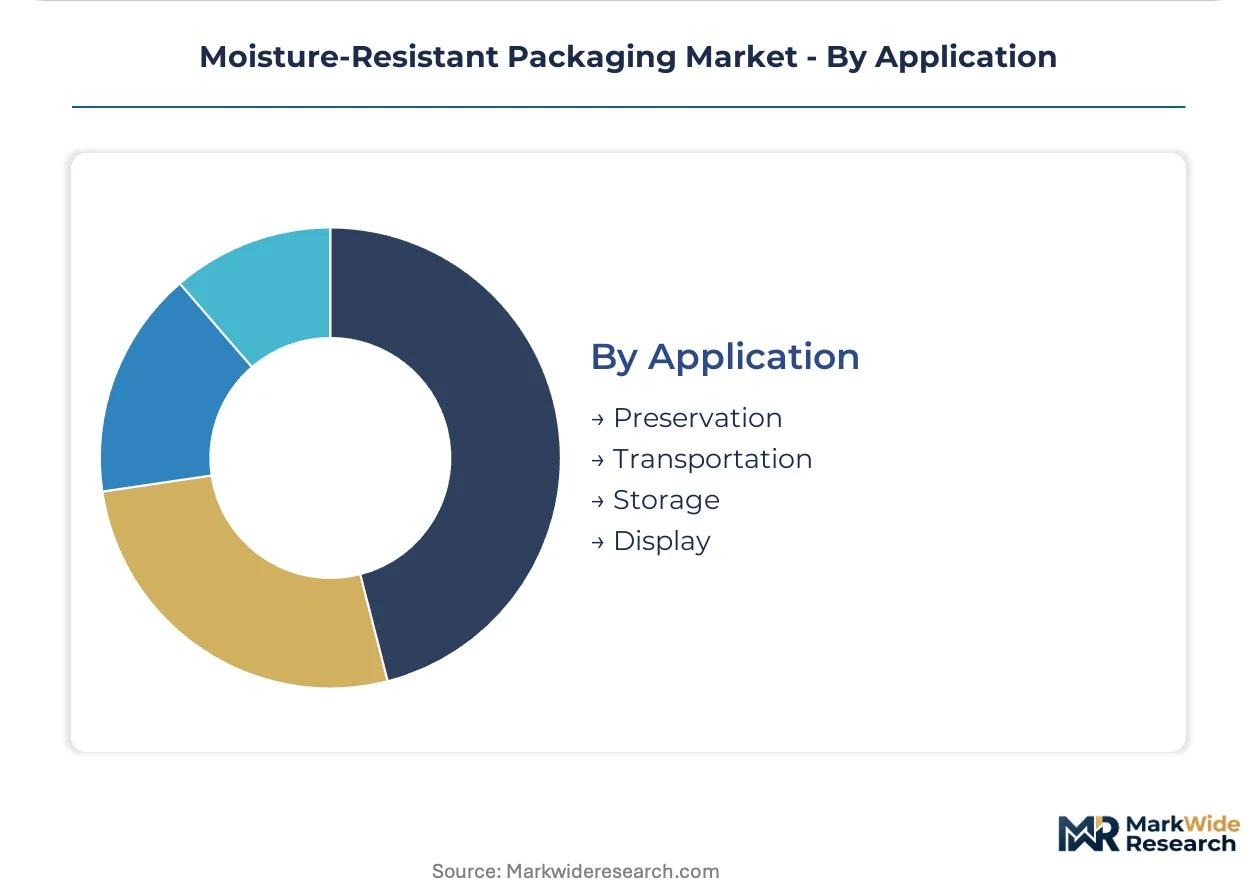
Application:
Maturity gradients separate established preservation formats from emerging transportation solutions serving cold-chain validation requirements.
- Preservation:Static barrier systems for shelf-stable products represent the most penetrated application. Oral solid dose pharmaceuticals and dehydrated foods constitute the core demand base here.
- Transportation:Active and passive temperature-controlled packaging for biologics cold-chain is forcing material specification upgrades. ICH Q1A(R2) compressed timelines demand packaging validation completion within shortened cycles.
- Storage:Warehouse humidity control systems and desiccant-enhanced containers serve intermediate holding requirements. Electronics manufacturers in Massachusetts and California are mandating supplier access to batch release documentation.
- Display:Retail-ready formats balance moisture protection with optical clarity and printability. European sustainability-driven procurement is gaining preference for recyclable barrier papers in this application.
Preservation dominates installed base. Transportation is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports validated barrier systems to pharmaceutical manufacturers across Switzerland and the Netherlands, forming the dominant trade corridor in European moisture-resistant packaging.
United States
Biologics manufacturers in Massachusetts and California mandate supplier access to batch release documentation. EPA restrictions on per- and polyfluoroalkyl substances accelerate transitions to fluorine-free barrier chemistries. North American converters face $2-4 million equipment retrofit costs.
Germany
Sterile injectable production in Hesse and Baden-Württemberg generates sustained demand for pre-qualified barrier systems. EMA Annex 1 manufacturing guidelines mandate documented moisture protection for parenteral drugs. The pharmaceutical manufacturing corridor concentrates procurement power among integrated film suppliers.
India
CDSCO harmonization with ICH stability guidelines creates demand for FDA-pre-validated barrier formats. The central pharmaceutical regulator tightens documentation requirements for export-oriented packaging. Hyderabad and Ahmedabad clusters drive qualification timelines for cold-chain formats.
Switzerland
Pharmaceutical contract packagers qualify water-based acrylic barrier coatings with nanoclay reinforcement for oral solid dose applications. Swissmedic oversight ensures alignment with EMA standards. Basel and Zurich house validation laboratories serving European sterile manufacturing networks.
South Korea
Vacuum deposition capacity for aluminum metallized films clusters here, creating input bottlenecks during semiconductor packaging demand surges. The national industrial policy prioritizes advanced materials for electronics dry-packaging. Seoul and Suwon anchor production for barrier film exports.
Moisture-Resistant Packaging Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and validation capability dimensions. The supplier base concentrates among integrated film manufacturers with captive analytical laboratories, while regional converters occupy commoditized food-grade segments. Three archetypes dominate: multinational packaging conglomerates with pharmaceutical validation networks, specialty paper and board producers with recyclable barrier portfolios, and regional flexible packaging converters serving distributor channels. Competitive moves center on fluorine-free chemistry qualification and direct quality assurance relationships with biologics manufacturers.
Within the integrated multinational tier, Amcor and Sealed Air occupy positions defined by cold-chain validation infrastructure and controlled-atmosphere system expertise. Mondi exemplifies the specialty paper archetype through its focus on recyclable barrier formats targeting sustainability-driven procurement. Sonoco Products Company sits within the diversified industrial packaging segment with broad format capabilities. These three represent distinct competitive positions rather than comparable strategic approaches.
| Leading Market Players |
|---|
| Smurfit Kappa |
| Sonoco Products Company |
| Amcor |
| DS Smith |
| Westrock Company |
| Berry Global |
| Mondi |
| ProAmpac |
| Sealed Air |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German pharmaceutical manufacturers and integrated film suppliers lock in multi-year aluminum foil allocations while freezing unit pricing for validated barrier formats. These arrangements insulate qualified suppliers from spot-market volatility in metallized film inputs while constraining buyer flexibility during supply crunches.
Pricing Analysis
Fluoropolymer-dependent barrier coatings command 25-40% premiums over silicon oxide alternatives, though EPA-mandated phase-outs are collapsing that technology-generation pricing gap. Three-tier pricing structure across pharmaceutical-validated, food-grade certified, and unconverted commodity tiers reflects documentation burden and batch-release overhead. Cost compression in standard-grade pouches is intensifying because South Korean vacuum deposition capacity diverts to semiconductor dry-packaging during demand surges. Contract packagers in Switzerland exhibit lowest price sensitivity, while European supermarket private-label programs drive hardest bargain on recyclable mono-material specifications.
Supply Chain Analysis
Just-in-time inventory strategies dominate pharmaceutical cold-chain procurement, though aluminum foil buyers maintain 60-90 day strategic stockpiles against East Asian deposition bottlenecks. Supply concentrates in Germany, South Korea, and Japan, with vacuum deposition capacity and coextrusion line density determining regional leverage. The chain draws from biaxially oriented polypropylene feedstock, 6-9 micron annealed aluminum foil, and plasma-deposited oxide coatings. Single-source vulnerability in East Asian metallized film output exposes converters to allocation rationing during electronics demand peaks. Distribution runs through qualified supplier networks with batch documentation for pharmaceutical grades, distributor channels for food volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated biologics manufacturers in Massachusetts and California, fragmenting procurement influence away from distributor intermediaries and toward direct quality assurance relationships with film suppliers.
For Market Incumbents: Fortify captive analytical laboratory capabilities to meet batch-release documentation demands from large-molecule manufacturers. Deepen backward integration into metallized film deposition to offset South Korean supply bottlenecks during semiconductor demand surges. Prioritize fluorine-free barrier chemistry qualification ahead of EPA enforcement timelines to avoid stranded equipment assets. For New Entrants and Emerging Players: Differentiate on sustainability credentials by qualifying water-based acrylic nanoclay coatings for oral solid dose applications in Swiss and Dutch contract packaging networks. Target Indian pharmaceutical export corridors in Hyderabad and Ahmedabad where CDSCO harmonization with ICH guidelines creates demand for pre-validated formats. Lead with recyclable mono-material barrier papers to capture EU Green Deal procurement preferences. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated film manufacturers with captive validation laboratories serving pharmaceutical cold-chain networks. Five-to-ten year viability hinges on fluorine-free chemistry transition completion and direct quality assurance relationship density. Acquisition candidates with plasma-deposited oxide coating capabilities and existing FDA master file submissions warrant closest scrutiny. Signal to monitor: semiconductor packaging demand spikes triggering allocation rationing that permanently displaces pharmaceutical customers.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Barrier Chemistry Qualification | EPA restrictions on perfluorinated coatings mandate reformulation ahead of enforcement dates. |
| Direct Quality Assurance Relationships | Biologics manufacturers in Massachusetts and California now require supplier batch-release access. |
| Recyclable Mono-Material Structure Development | EU Green Deal packaging waste targets drive procurement preference for barrier papers. |
| Plasma-Deposited Oxide Coating Capacity Addition | Silicon oxide and aluminum oxide alternatives replace fluoropolymer-dependent formats. |
| Indian Pharmaceutical Export Packaging Certification | CDSCO harmonization with ICH guidelines creates demand in Hyderabad and Ahmedabad clusters. |
Research Methodology
Desk research of FDA stability testing protocols, EMA Annex 1 manufacturing guidelines, and EPA substance restriction filings preceded structured interviews with pharmaceutical quality assurance directors, flexible packaging plant managers, metallized film procurement leads, and contract packager operations heads. Primary fieldwork combined with secondary validation against customs trade data, SEC 10-K disclosures from listed packaging conglomerates, and CDSCO regulatory harmonization documents. Bottom-up demand modeling across end-use segments triangulated against top-down supply-side capacity assessments.
Variance decomposition across material type, end-use criticality, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product format, barrier technology generation, validation tier, and geographic manufacturing corridor. CAGRs were derived from installed base growth rates and replacement demand elasticity. Forecast inputs incorporated ICH Q1A(R2) compressed validation timelines and ECHA REACH polymer restriction phase-in schedules.
Material uncertainties — regulatory enforcement delays, aluminum deposition capacity expansion, bio-based sealant performance breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions regarding fluoropolymer phase-out adherence and pharmaceutical cold-chain growth continuity. Revision becomes warranted when semiconductor packaging demand crosses thresholds that trigger sustained metallized film allocation rationing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Heat Transfer Films Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
Perforated Packaging Film Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Transport Protection Film Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Nano Sealers Market