
 Stretch Films Packaging Market | 2026-2036
Stretch Films Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Stretch Films Packaging Market Analytics
A capital-intensity divergence between integrated resin producers and film converters is reorganizing competitive tiers in stretch films packaging. Dow Inc. leverages captive polyethylene supply chains to control raw material costs across North American manufacturing. Sealed Air Corporation differentiates through engineered pre-stretch technologies that reduce film consumption per pallet wrapped. Berry Global Group sustains broad geographic coverage across hand and machine stretch formats.
Stretch films packaging comprises thin, flexible polymeric membranes manufactured through cast or blown extrusion processes, typically ranging from 8 to 35 microns in thickness, designed to cling tightly around palletized goods for unitization and protection during handling and transit. Machine stretch films dominate volume throughput in automated warehouse environments where throughput speed and load containment force are critical operational parameters. Polyethylene-based formulations anchor material demand due to cost efficiency and recyclability alignment, while pre-stretched variants capture margin pools by reducing material intensity per wrapped unit.
The US EPA and OSHA frameworks govern workplace exposure limits and film dust particulate standards in converting facilities, while the EU REACH regulation restricts phthalate plasticizer content in films contacting consumer goods. These standards compel reformulation investments and filter market access toward compliant suppliers. Stakeholders must monitor evolving extended producer responsibility schemes that will reshape cost allocation between resin suppliers, film manufacturers, and end-user recyclers.
Market Dynamics
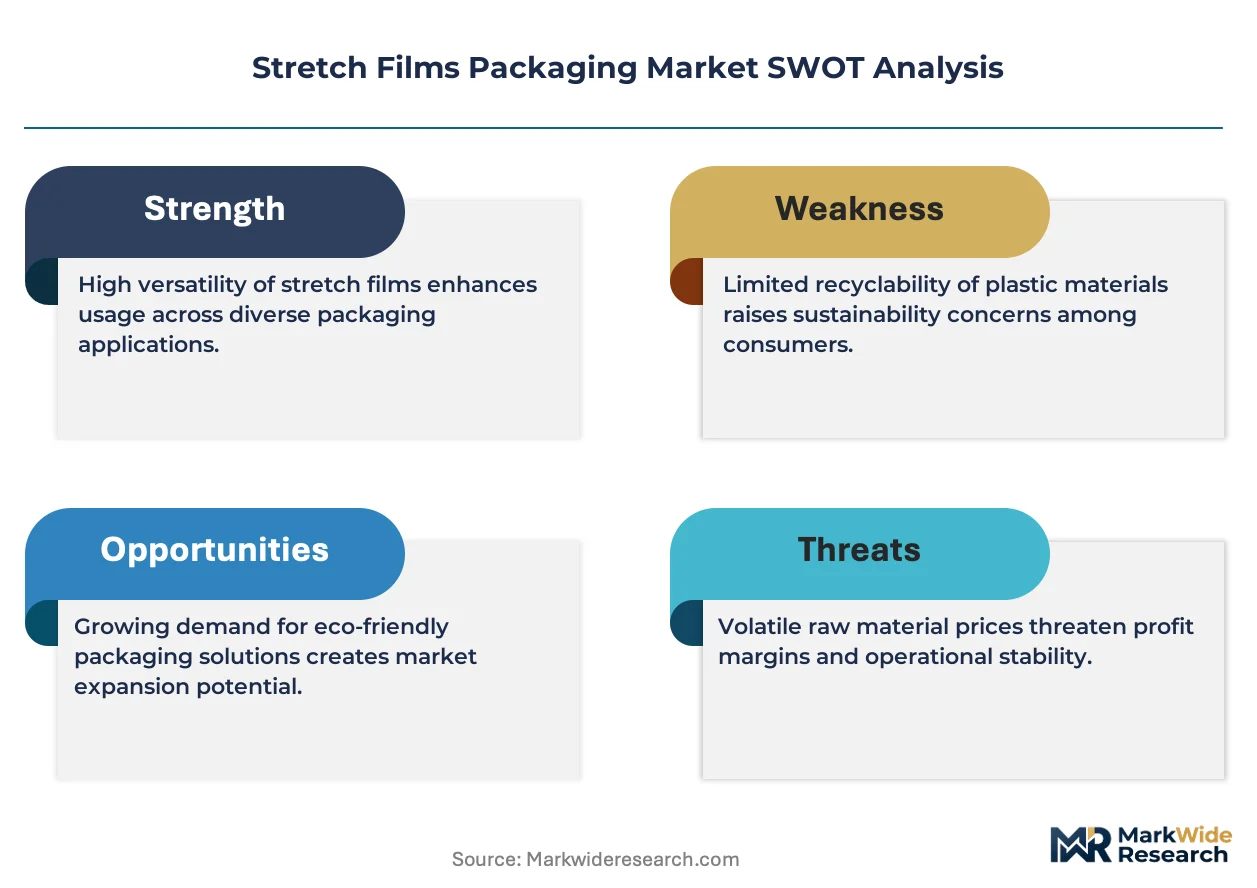
Machine-grade film adoption in automated warehousing is compressing demand for hand-wrap formats while EU recyclability mandates force resin reformulation investments across the value chain.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates for recyclability and recycled content thresholds are pulling converters toward mono-material polyethylene designs that simplify end-of-life processing.
- Food & Beverage logistics expansion:Cold-chain networks and e-commerce fulfillment centers are scaling machine-wrap capacity to secure palletized loads at higher throughput speeds.
- Germany's industrial corridor concentration:Automotive and chemical exporters in Baden-Württemberg and North Rhine-Westphalia are specifying high-performance films with elevated puncture resistance and load containment force.
Market Restraints
- Ethylene feedstock volatility:Naphtha and ethane price swings transmit directly to film converter margins, squeezing smaller extruders without captive resin supply.
- Blown film capacity concentration:Production of high-performance agricultural and industrial grades clusters in specific manufacturing zones, creating geographic supply risk during logistics disruptions.
- Mechanical recycling contamination limits:Multi-layer barrier films and UV-stabilized agricultural variants face technical barriers to closed-loop recovery, limiting circular economy participation.
Strategic Opportunities
- India's organized retail modernization:Cold-chain infrastructure buildout and FMCG distribution centralization are creating first-mover advantages for pre-stretch film suppliers.
- Downgauging technology convergence:Nano-layer coextrusion combined with metallocene polyethylene resins enables thinner films without performance sacrifice, reducing material intensity per pallet.
- Extended producer responsibility schemes:France's Citeo and Germany's Der Grüne Punkt systems are creating financial incentives for design-for-recycling investments that capture compliance premiums.
Industry Challenges
- Extrusion technician scarcity:Blown film line operation and die gap optimization require specialized skills that aging workforces and limited vocational pipelines struggle to replenish.
- Legacy warehouse management integration:Automated stretch wrapper deployment demands API connectivity with existing WMS platforms, creating implementation friction for mid-sized 3PL operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretch Films Packaging Market |
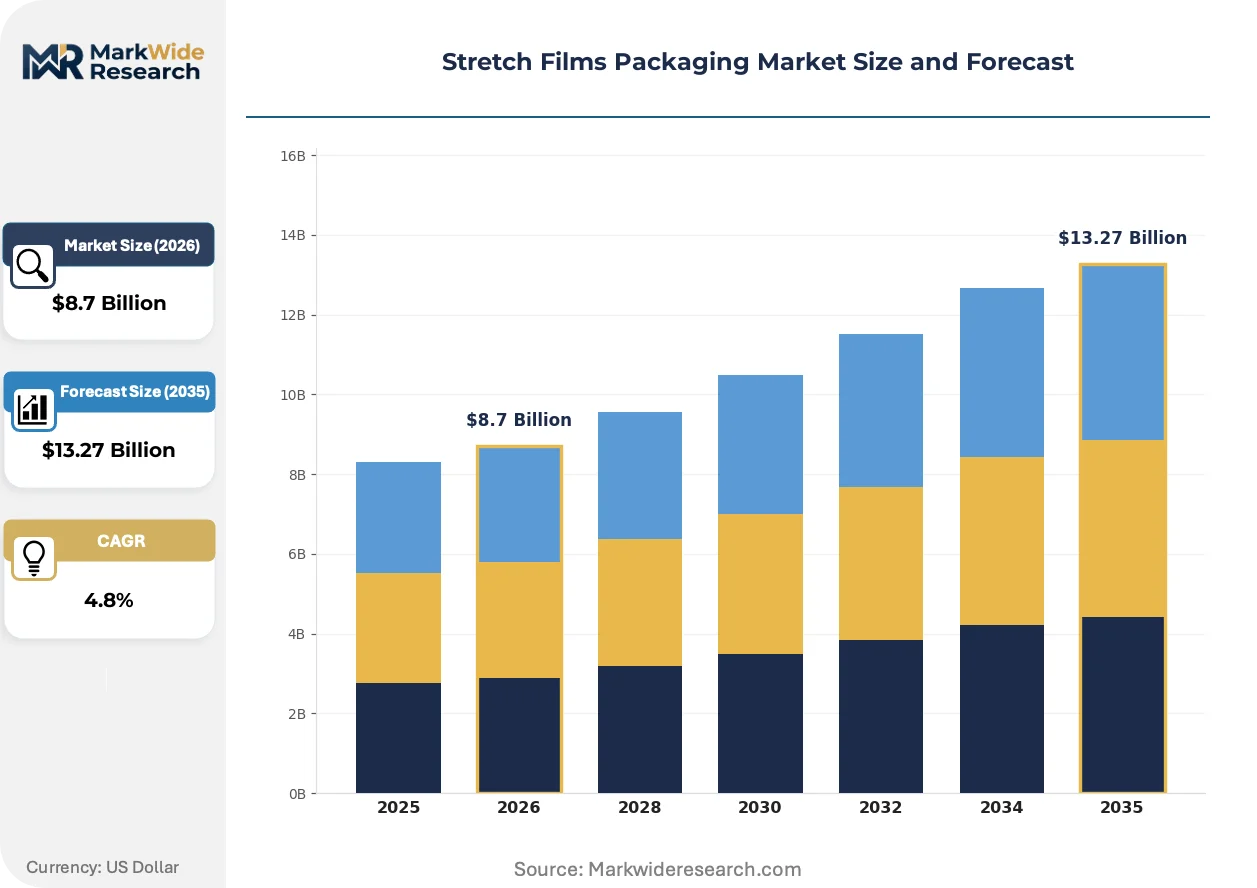
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Stretch, Machine Stretch, Pre-Stretched, Mini Stretch Material: Polyethylene, PVC, Polypropylene, Others Application: Food & Beverage, Healthcare, Consumer Goods, Industrial End User: Manufacturers, Retailers, Logistics, Distributors |
| Companies Covered | Berry Global Group, Amcor plc, Sealed Air Corporation, Dow Inc., Sigma Plastics Group, Paragon Films, Inteplast Group, Intertape Polymer Group, Coveris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretch Films Packaging Market Evolving Landscape
Pre-stretch film technology and bio-based resin formulations are reconfiguring material economics, while regulatory pressure on plastic waste accelerates investment in circular design capabilities.
Metallocene polyethylene (mPE) formulations with enhanced puncture resistance and cling properties are displacing conventional linear low-density polyethylene in high-value load containment applications. Major retail distribution centers and automotive tier-one suppliers are specifying these grades for irregular pallet geometries. The shift is compressing margins for commodity resin producers while rewarding compounders with proprietary catalyst technology.
REACH restrictions on phthalate plasticizers and the EU's evolving microplastic definition are compelling film converters to validate non-migratory additive packages. Industrial consequence includes accelerated substitution of traditional cling agents with plant-derived alternatives in food-contact applications. German and French converters are responding fastest, leveraging proximity to ECHA guidance and national chemical agency technical support.
Consolidated buying by multinational 3PL operators and retail chains is compressing supplier bases and extending payment terms beyond ninety days. Regional film distributors and smaller converters are losing shelf position to integrated producers with direct account management capabilities. The pattern is most visible in Benelux and northern Italy, where logistics outsourcing concentration has advanced furthest.
Stretch Films Packaging Market Segmentation
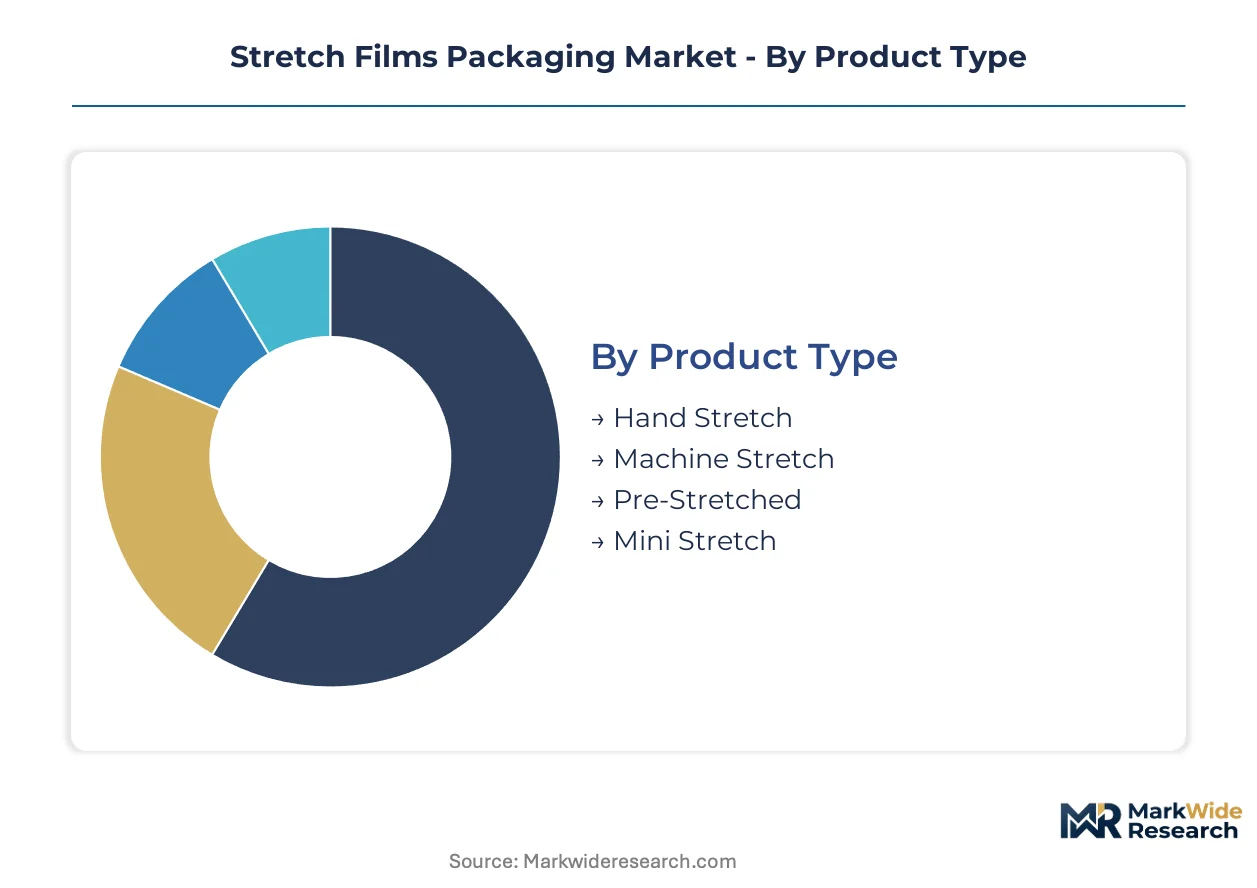
Stretch films packaging segments diverge sharply in automation compatibility and material intensity, with substitution pressure from alternative unitization methods reshaping investment priorities across each category. Understanding where pre-stretch films displace conventional grades, or where bio-based resins challenge petroleum formulations, determines capital allocation for converters and procurement strategy for end-users.
Product Type:
Substitution pressure runs strongest against hand-wrap formats as warehouse automation accelerates, while pre-stretched variants threaten both conventional machine and hand grades through material efficiency advantages.
- Machine Stretch:Blown or cast extruded films engineered for automated wrapper compatibility, typically 15-35 microns thick with high puncture resistance and cling force. Demand concentrates in German automotive tier-one supplier networks and US e-commerce fulfillment centers where throughput speed dictates operational economics. ECHA REACH compliance for cling additives shapes converter formulation decisions.
- Pre-Stretched:Films pre-oriented during manufacture to reduce gauge thickness while maintaining load containment force, cutting material consumption per pallet. Cold-chain operators in France and pharmaceutical distributors in Switzerland specify these grades for sustainability metrics and freight cost reduction.
- Hand Stretch:Lower-tack formulations for manual application in small-batch operations and remote logistics nodes without wrapper infrastructure.
- Mini Stretch:Narrow-width rolls for bundling individual items or small parcel unitization in retail backrooms and light manufacturing.
Machine stretch retains volume leadership; pre-stretched holds the steepest expansion curve.
Material:
Cost tier stratification separates commodity polyethylene from specialty resins, with regulatory recyclability mandates forcing reformulation investments that compress margins for non-compliant suppliers.
- Polyethylene:Linear low-density and metallocene-catalyzed grades dominate through cost efficiency, mechanical recyclability, and established collection infrastructure. German chemical exporters and Benelux food distributors specify mono-material PE designs to satisfy EU Packaging and Packaging Waste Regulation thresholds.
- Polypropylene:Higher clarity and temperature resistance than PE, capturing pharmaceutical cold-chain applications where sterilization compatibility matters. Demand clusters in Swiss and Austrian healthcare logistics corridors.
- PVC:Declining share due to chlorine content complicating mechanical recycling and ECHA scrutiny of plasticizer migration in food-contact scenarios.
- Others:Bio-based PLA and PHA formulations, plus nylon barrier layers for extreme puncture resistance in metal coil and construction materials shipping.
Polyethylene commands the volume base; polypropylene climbs fastest on healthcare specification.
Application:
Application segmentation tracks directly to pallet geometry complexity and load stability requirements, with food logistics demanding the tightest cling specifications and industrial applications tolerating heavier gauges.
- Food & Beverage:Films must balance oxygen transmission rates with moisture barrier properties for fresh produce and chilled dairy. French retail chains and German discount grocers drive specification toward ultra-thin metallocene grades.
- Industrial:Heavy-gauge blown films for irregular metal fabrications, chemicals, and construction materials where puncture resistance outweighs clarity. Baden-Württemberg automotive suppliers and Ruhr basin chemical exporters anchor demand.
- Consumer Goods:Medium-duty wraps for electronics, appliances, and household products requiring retail-presentable pallet appearance.
- Healthcare:Sterile-grade films with validated non-migratory additives for pharmaceutical distribution, governed by FDA and EMA material safety requirements.
Food & Beverage leads pallet volume; healthcare posts the steepest specification premium growth.
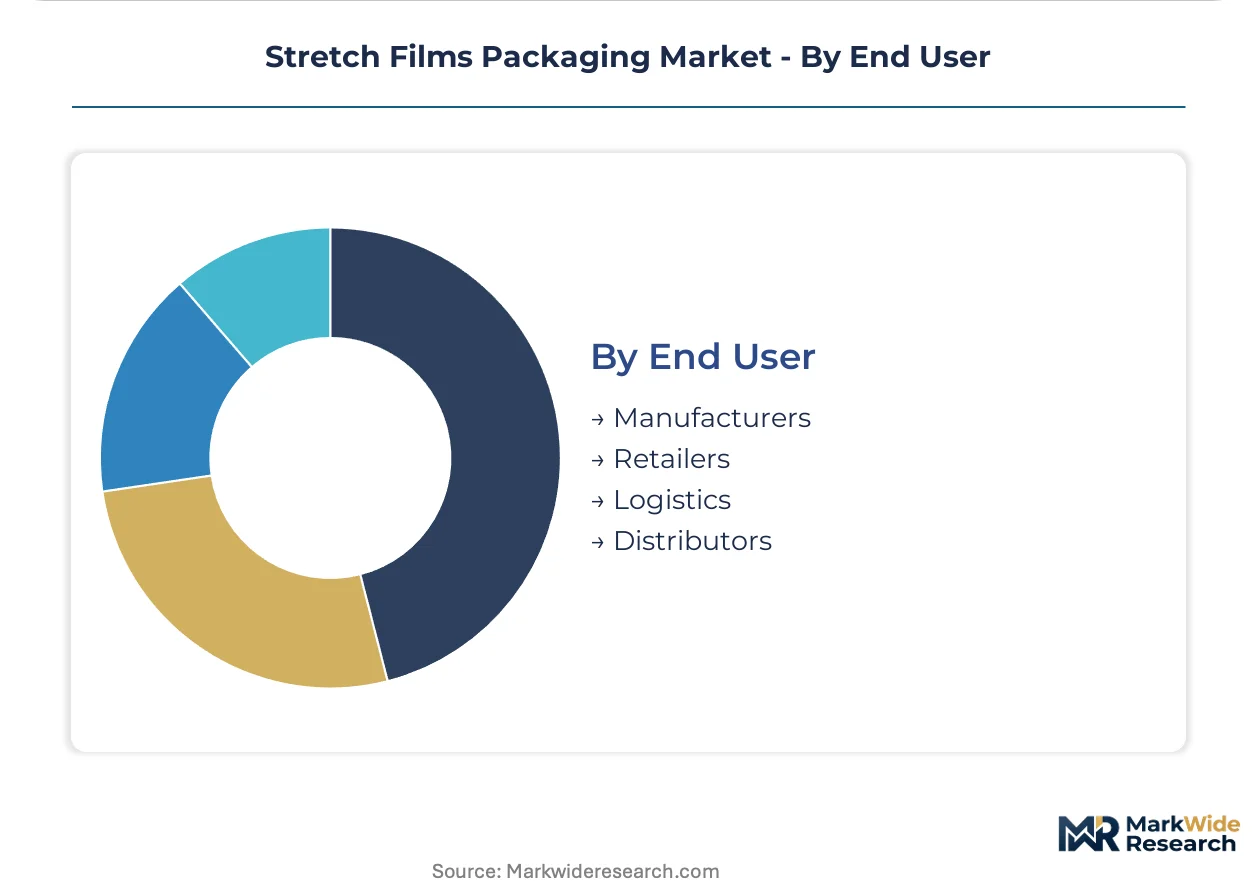
End User:
Customer type determines contract structure and technical service intensity, with consolidated logistics operators extracting the most demanding performance guarantees and payment terms.
- Logistics:Third-party operators and dedicated contract logistics firms specify films through total-cost-of-ownership metrics including wrapper speed compatibility and load failure rates. DHL Supply Chain and Kuehne+Nagel procurement desks in Rotterdam and Hamburg drive standardization.
- Manufacturers:Original producers of food, chemicals, and automotive components who internalize palletization before handoff to transport. German Mittelstand exporters value supplier technical support for wrapper line integration.
- Retailers:Grocery and mass-merchandise chains with private distribution networks, increasingly specifying recycled-content thresholds.
- Distributors:Wholesale and trading intermediaries with fragmented, lower-volume requirements and price-sensitive procurement.
Logistics commands the largest contract value; manufacturers show the fastest specification upgrading.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies: German automotive exporters absorb premium-grade premiums while Indian FMCG distributors prioritize cost-per-meter metrics above performance specifications.
United States
E-commerce fulfillment networks and third-party logistics operators drive machine-grade film consumption. EPA workplace exposure standards govern converting facility compliance. The Chicago-Milwaukee industrial corridor hosts dense clusters of stretch wrapper deployment in retail distribution centers.
Germany
Automotive tier-one suppliers and chemical exporters demand high-performance load containment solutions. ECHA REACH restrictions on phthalate plasticizers compel additive reformulation. Baden-Württemberg and North Rhine-Westphalia concentrate specification-driven procurement for puncture-resistant blown films.
France
Cold-chain operators and pharmaceutical distributors specify pre-stretched grades for sustainability metrics. Citeo extended producer responsibility schemes create financial incentives for mono-material designs. The Île-de-France logistics basin anchors demand from retail chain distribution hubs.
China
Organized retail modernization and express delivery networks expand machine-wrap capacity. MIIT industrial standards govern packaging material quality specifications. The Yangtze River Delta manufacturing belt concentrates cast film production for domestic FMCG distribution.
India
Cold-chain infrastructure buildout and centralizing FMCG distribution create first-mover opportunities for pre-stretch suppliers. FSSAI food-contact material regulations shape converter compliance investments. Maharashtra and Gujarat industrial corridors concentrate warehousing automation adoption.
Stretch Films Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in stretch films packaging. Resin producers with captive polyethylene supply chains command cost advantages over film converters dependent on spot market feedstock. Strategic archetypes separate integrated resin-to-film operators, engineered pre-stretch technology specialists, and geographic coverage generalists. Competitive moves concentrate on backward integration into resin production and metallocene catalyst licensing partnerships.
Among North American integrated producers, Dow Inc. and Berry Global Group exemplify the resin-captive archetype with upstream cost control. Sealed Air Corporation occupies a position within the engineered technology tier, representing pre-stretch innovation specialization. These three anchors illustrate how competitive advantage separates feedstock-integrated, technology-differentiated, and scale-geographic positioning strategies.
| Leading Market Players |
|---|
| Berry Global Group |
| Amcor plc |
| Sealed Air Corporation |
| Dow Inc. |
| Sigma Plastics Group |
| Paragon Films |
| Inteplast Group |
| Intertape Polymer Group |
| Coveris |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between polyethylene resin producers and German automotive exporters lock in feedstock access while anchoring price visibility through ethylene cost pass-through mechanisms. These arrangements insulate high-volume buyers from naphtha volatility while compressing spot-market margins for smaller converters in Benelux and northern Italy.
Pricing Analysis
After-sales service contracts for stretch wrapper maintenance and film supply bundling drive lifetime value for integrated suppliers like Sealed Air and Berry Global. Three-tier pricing structure across premium metallocene grades, standard LLDPE formulations, and economy recycled-content tiers separates specification-driven automotive buyers from price-sensitive Indian FMCG distributors. Cost compression in commodity hand-wrap segments is intensifying because of consolidated 3PL procurement desks extending payment terms beyond ninety days. German chemical exporters show least price sensitivity, absorbing puncture-resistance premiums, while Indian cold-chain operators prioritize cost-per-meter metrics.
Supply Chain Analysis
Inbound logistics costs from Rotterdam-Antwerp port congestion and container availability constraints on Asia-Europe trade lanes elevate landed costs for Asian resin imports into European converting facilities. Supply concentrates in Germany, the United States, and China, with blown film capacity clustering in Baden-Württemberg, the Chicago-Milwaukee corridor, and the Yangtze River Delta. Raw material flows draw from naphtha crackers in the US Gulf Coast, ethane-fed facilities in the Middle East, and coal-to-olefins complexes in northwest China. Single-source vulnerability runs through metallocene catalyst licensing controlled by Dow and ExxonMobil Chemical. Distribution runs through direct account management for multinational 3PL operators and regional distributor networks for mid-sized manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation's recyclability mandates constitute a technological-regulatory inflection that will separate compliant mono-material suppliers from stranded multi-layer inventory.
For Market Incumbents: Secure captive resin supply through backward integration or long-term offtake agreements with Gulf Coast ethane crackers to defend against feedstock volatility squeezing non-integrated converters. Invest in metallocene catalyst licensing partnerships to maintain specification premiums against emerging bio-based resin competitors. Prioritize ECHA REACH compliance for non-migratory additive packages before enforcement tightens. For New Entrants and Emerging Players: Lead with pre-stretched film technology targeting India's cold-chain infrastructure buildout in Maharashtra and Gujarat, where warehousing automation adoption lags Western benchmarks. Penetrate through technical service partnerships with FMCG distributors upgrading from hand-wrap to machine-grade formats. Bundle wrapper line integration support to overcome legacy warehouse management system friction. For Investors and Strategic Acquirers: Capital is best deployed toward engineered technology specialists with proprietary pre-stretch processes and established ECHA compliance dossiers rather than commodity converters exposed to resin margin compression. The five-to-ten year viability window favors compounders with catalyst partnerships over pure-play extruders. Monitor France's Citeo and Germany's Der Grüne Punkt extended producer responsibility scheme expansions as inflection indicators for design-for-recycling premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Dow Inc.'s captive polyethylene supply chains neutralize ethane price volatility for North American film operations. |
| Metallocene Catalyst Licensing Partnership | Proprietary mPE formulations displace conventional LLDPE in German automotive tier-one supplier networks. |
| Pre-Stretch Technology Scale-Up | Sealed Air's engineered films reduce material intensity per pallet for French cold-chain operators. |
| Design-for-Recycling Investment | Mono-material PE designs satisfy EU Packaging and Packaging Waste Regulation thresholds for Benelux food distributors. |
| Direct Account Management Buildout | Integrated producers displace regional distributors in Rotterdam and Hamburg 3PL procurement desks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade association filings, customs data, and regulatory agency guidance to validate market sizing. Conversations with blown film plant managers, automotive tier-one procurement leads, 3PL category buyers, and ECHA regulatory affairs specialists informed operational assumptions. Secondary sources include Cefic plastics industry reports, USITC trade databases, and EU Packaging and Packaging Waste Regulation impact assessments. Bottom-up capacity modeling triangulated against top-down demand aggregation from end-use industry consumption patterns.
Segmentation dimensions modeled include product type (machine stretch, pre-stretched, hand stretch, mini stretch), material formulation (polyethylene, polypropylene, PVC, bio-based alternatives), application vertical (food and beverage, industrial, consumer goods, healthcare), and end-user category (logistics operators, manufacturers, retailers, distributors). CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends across the projection horizon. Industry-specific inputs incorporated ethylene feedstock cost curves, wrapper automation penetration rates, and ECHA REACH compliance cost burdens.
Forecasts assume regulatory continuity in EU REACH and Packaging and Packaging Waste Regulation regimes; material policy shifts would require re-modeling. Forecasts reflect assumptions about metallocene catalyst licensing availability, ethane-naphtha price spreads, and mechanical recycling infrastructure buildout rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Transparent Barrier Films Market
Packaging Barrier Films
Moisture Barrier Bags Market
Packaging Barrier Films
Dual Ovenable Lidding Films Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Transport Protection Film Market
Packaging Barrier Films
Barrier Coated Papers Market
Packaging Barrier Films
Nano Sealers Market
Packaging Barrier Films
Global High Barrier Packaging Films Market
Packaging Barrier Films
Release Liners Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Global Heat Sealable Packaging Market
Packaging Barrier Films
Pipe Insulation Film Market
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Sealant Web Films Market