
 Wash Off Labels Market | 2026-2036
Wash Off Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Wash Off Labels Market Analytics
Asset-light leasing arrangements for coating and converting equipment is reconfiguring competitive entry in wash-off label production. Avery Dennison Corporation leverages its global adhesive R&D network to sustain formulation leadership in removable acrylic systems. CCL Industries Inc. anchors North American supply through captive film extrusion and precision coating assets. HERMA GmbH differentiates via specialized die-cutting capabilities serving European beverage returnable bottle programs.
Wash off labels employ water-dispersible adhesives that separate cleanly from glass, PET, and metal substrates during standard caustic wash or warm-water rinse cycles at temperatures between sixty and eighty degrees Celsius. Their primary purpose is to enable container reuse and streamline recycling streams without contaminating recovered materials. Pressure sensitive formats dominate volume given compatibility with high-speed rotary labelers, while shrink sleeve applications are expanding fastest in craft beverage segments where full-wrap decoration meets returnable bottle requirements. Paper substrates retain cost advantage in standard beverage applications, though polyethylene films command margin pools in personal care and pharmaceutical containers requiring moisture resistance and premium aesthetics.
The European Union's Packaging and Packaging Waste Regulation and REACH chemical compliance frameworks are reshaping adhesive formulation requirements and recyclability certification protocols. FDA food contact substance notifications govern wash-off adhesive migration limits for beverage applications in the United States, while China's GB standards for packaging recyclability are tightening import specifications for labeled containers. Stakeholders must monitor evolving extended producer responsibility schemes and adhesive substance restrictions to align product development with compliance timelines and customer sustainability scorecards.
Market Dynamics
Returnable packaging mandates from the EU Packaging and Packaging Waste Regulation are forcing beverage bottlers to retrofit label specifications, compressing adhesive formulation cycles and rewiring procurement relationships across the value chain.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets for returnable glass and PET containers are accelerating wash-off label adoption across German, French, and Italian beverage bottling facilities.
- Caustic wash infrastructure:Existing industrial bottle-washing systems at sixty to eighty degrees Celsius operate without modification, eliminating capital barriers for label format conversion.
- Polyethylene film substrates:Personal care and pharmaceutical brands are migrating from paper to moisture-resistant films, opening margin pools in premium container segments.
Market Restraints
- Acrylic adhesive raw material volatility:Petroleum-derived monomer feedstocks expose formulators to price swings that compress margin predictability in removable adhesive production.
- European labelstock concentration:Germany, France, and Italy control the majority of regional procurement decisions, creating geographic dependency risk for converters outside these markets.
- Water-dispersible performance ceiling:Current adhesive chemistry struggles to maintain tack stability across extended temperature ranges in warm-climate distribution.
Strategic Opportunities
- China GB standards alignment:Tightening import specifications for packaging recyclability create first-mover advantage for adhesive suppliers certifying wash-off compatibility under national standards.
- Craft beverage shrink sleeve convergence:Small-batch brewers combining full-wrap decoration with returnable bottle programs represent an underpenetrated application segment for pressure-sensitive alternatives.
- Asset-light coating partnerships:Leasing arrangements for precision converting equipment lower entry barriers for regional players seeking captive film extrusion capabilities.
Industry Challenges
- REACH substance restriction timelines:ECHA evaluations of adhesive components compress product reformulation windows, forcing R&D teams to parallel-track compliance and performance validation.
- Rotary labeler integration complexity:High-speed beverage lines require precise die-cutting tolerances and tension control, demanding specialized engineering support that strains technical service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wash Off Labels Market |
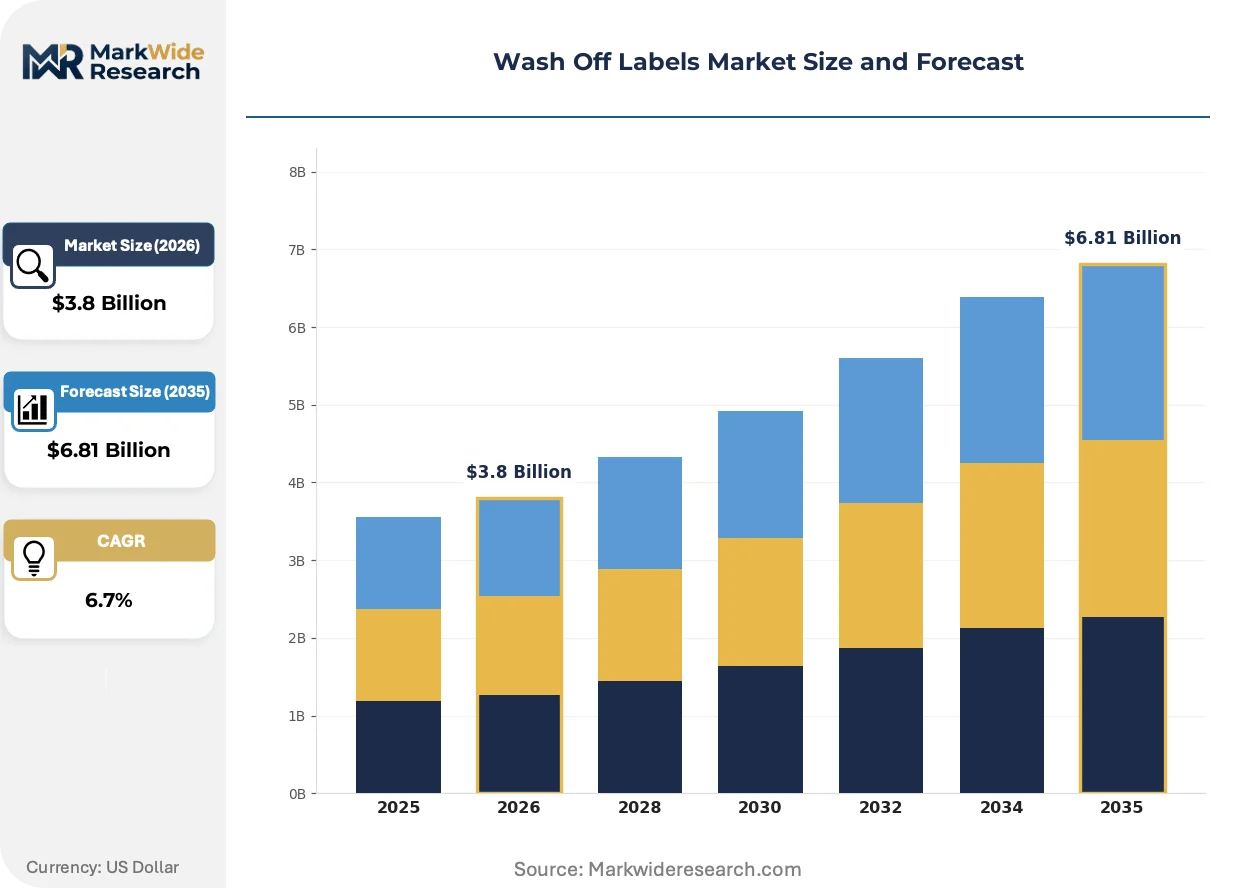
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensitive, Heat Transfer, Wet Glue, Shrink Sleeve Material: Paper, Plastic, Polyethylene, Polypropylene End User: Food & Beverage, Personal Care, Chemical, Pharmaceuticals Application: Bottles, Jars, Containers, Cans |
| Companies Covered | Avery Dennison Corporation, CCL Industries Inc., Multi-Color Corporation, UPM Raflatac, HERMA GmbH, LINTEC Corporation, Fuji Seal International, Inc., Mondi Group, Adcraft Labels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wash Off Labels Market Evolving Landscape
Active hybridization between adhesive chemistry and substrate engineering is collapsing traditional format boundaries, enabling single-label solutions to serve multiple container reuse cycles without performance degradation.
Water-dispersible acrylic systems are hybridizing with bio-based polymer backbones to maintain caustic-wash separability while reducing petroleum dependency. European beverage cooperatives are piloting these formulations at commercial scale. The convergence is compressing the innovation cycle for sustainable adhesive alternatives.
REACH chemical compliance frameworks are tightening substance restriction lists for adhesive monomers used in food-contact applications. ECHA prioritization of specific acrylates is forcing reformulation investments ahead of sunset dates. German bottlers are accelerating supplier audits to lock in compliant labelstock ahead of enforcement windows.
Leasing models for coating and converting assets are displacing outright equipment purchases among mid-tier label converters. Regional players in Italy and France are accessing precision die-cutting capabilities without capital commitment. The shift is visible most acutely in European beverage returnable bottle programs where volume volatility demands operational flexibility.
Wash Off Labels Market Segmentation
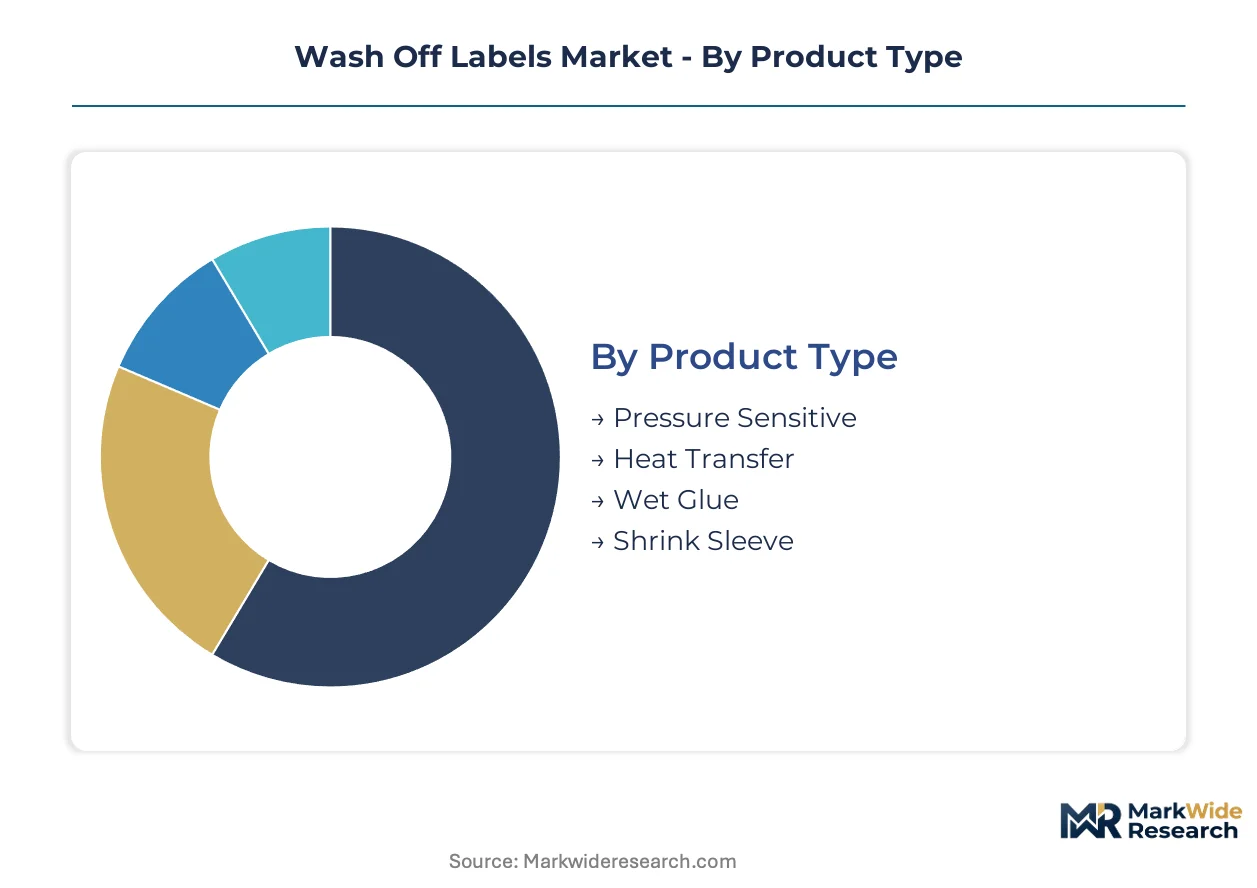
Wash-off label specifications diverge sharply across container formats, thermal processing requirements, and end-use compliance standards. Adhesive chemistry and substrate selection must align precisely with caustic wash infrastructure and regulatory migration limits for each target application.
Product Type:
The use-case spectrum spans permanent bonding for single-use containers to fully removable systems engineered for multi-cycle returnable bottle programs.
- Pressure Sensitive:Acrylic-based adhesives coated onto release liners enable high-speed rotary application at beverage bottling lines. German and French returnable bottle cooperatives concentrate procurement here, driven by compatibility with existing sixty-to-eighty-degree Celsius caustic wash systems.
- Shrink Sleeve:Full-wrap polyethylene or PETG films deliver three-hundred-sixty-degree decoration for craft beverage brands. Demand is accelerating among small-batch brewers seeking premium aesthetics combined with returnable container compliance.
- Heat Transfer:Dry-offset inks sublimated onto containers via thermal transfer ribbons suit short-run pharmaceutical labeling with variable data requirements.
- Wet Glue:Starch or casein adhesives applied via cold-glue labelers retain cost advantage in emerging market beverage operations with lower line speeds.
The dominant share belongs to Pressure Sensitive, while Shrink Sleeve is closing the gap fastest.
Material:
Cost tier differentiation separates commodity substrates from performance films commanding premium positioning in moisture-critical applications.
- Paper:Uncoated or semi-gloss paper facestocks with water-dispersible adhesives dominate standard beverage applications where cost minimization outweighs moisture exposure risks.
- Polyethylene:Low-density and linear low-density films provide moisture resistance and conformability for personal care containers subject to shower or humidity exposure. Italian converters are expanding extrusion capacity to capture this margin pool.
- Plastic:Generic plastic substrates encompass PVC and OPS alternatives now facing regulatory pressure under REACH substance restrictions.
- Polypropylene:Biaxially oriented polypropylene delivers stiffness and print clarity for pharmaceutical labels requiring extended shelf-life stability.
Paper retains volume leadership, though Polyethylene is expanding most quickly in premium personal care segments.
End User:
Customer type determines adhesive migration limits, wash-cycle durability requirements, and sustainability certification priorities.
- Food & Beverage:Returnable glass and PET bottle programs under EU Packaging and Packaging Waste Regulation mandates represent the core demand anchor. German bottlers are retrofitting procurement specifications fastest.
- Pharmaceuticals:FDA food contact substance notifications and EMA guidelines govern adhesive composition for primary container labeling. Compliance documentation requirements compress supplier qualification timelines.
- Personal Care:Moisture-resistant film labels for shampoo, conditioner, and body wash containers prioritize aesthetic premiumization over wash-off performance.
- Chemical:Industrial solvent and cleaning product containers require adhesive stability against aggressive contents, often superseding wash-off separability.
Food & Beverage commands the dominant position, while Pharmaceuticals is climbing the fastest on regulatory compliance investments.
Application:
Container geometry and closure type dictate die-cutting tolerances, adhesive coverage patterns, and labeler integration complexity.
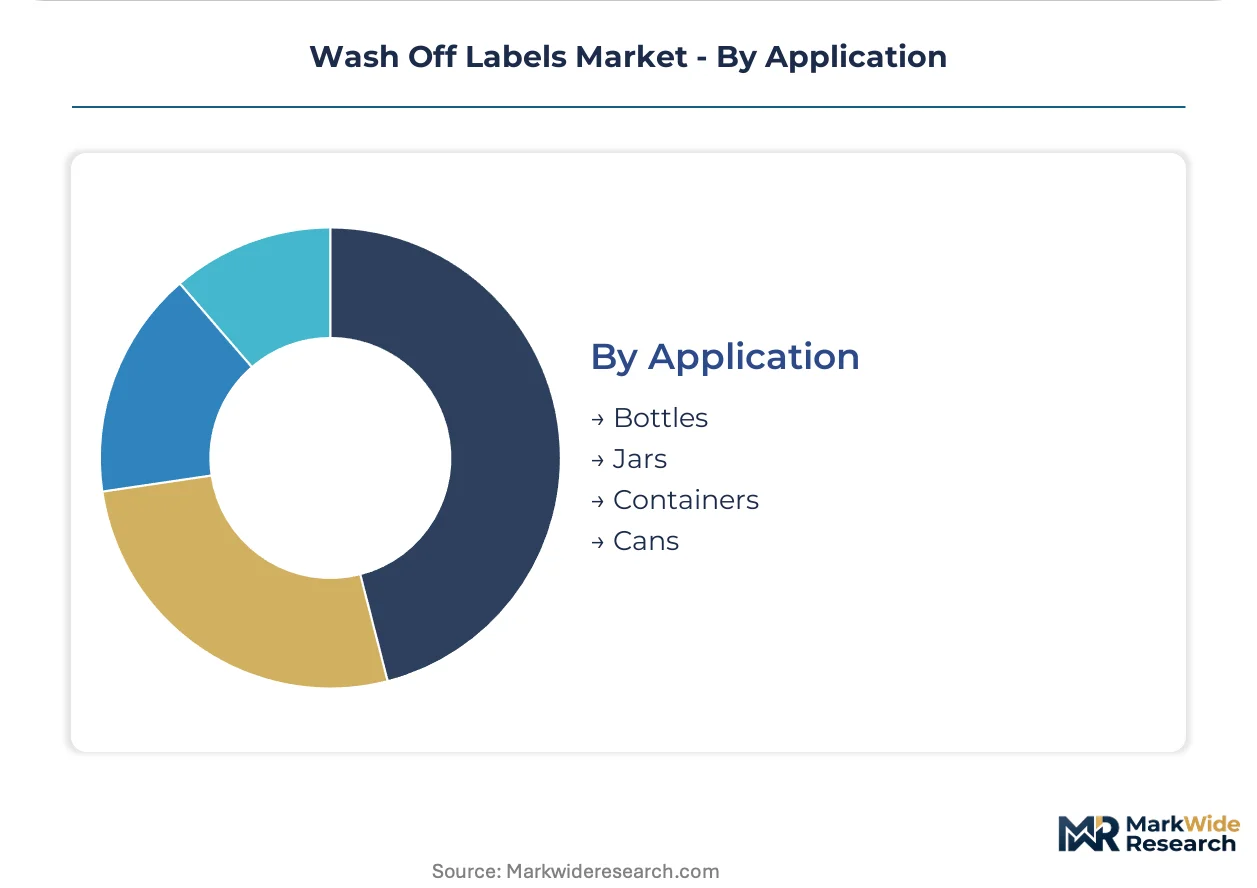
- Bottles:Cylindrical glass and PET containers for beverages, pharmaceuticals, and personal care represent the standardized application format. Pressure-sensitive labels with specialized die-cut patterns accommodate neck, body, and full-wrap placements.
- Jars:Wide-mouth glass and plastic containers for food preserves and cosmetics require larger label formats with enhanced adhesive anchoring at curved shoulder transitions.
- Containers:Rectangular or irregular industrial packaging for chemicals and bulk goods demands flexible adhesive systems accommodating surface texture variation.
- Cans:Aluminum beverage cans present unique challenges for wash-off adhesion due to surface treatment chemistry and high-speed filling line dynamics.
Bottles hold the dominant share, though Jars are gaining share fastest in premium food and cosmetic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers and personal care manufacturers concentrate procurement decisions in industrial clusters with established caustic wash infrastructure and stringent recyclability mandates. Regulatory pressure from the EU Packaging and Packaging Waste Regulation and diverging national standards reshape geographic demand patterns.
Germany
Returnable glass bottle cooperatives in Bavaria and North Rhine-Westphalia drive specification changes for water-dispersible adhesives. The country's national packaging regulator enforces strict recyclability certification under extended producer responsibility schemes. Frankfurt-Rhine-Main chemical clusters host adhesive formulators accelerating compliant labelstock development ahead of enforcement windows.
France
Champagne and mineral water bottlers retrofit procurement for multi-cycle container programs. ANSM and environmental agencies coordinate adhesive migration limit enforcement for food-contact applications. The Grand Est region concentrates precision die-cutting converters serving cross-border beverage supply chains into Belgium and Luxembourg.
Italy
Personal care brands in Lombardy and Emilia-Romagna migrate from paper to moisture-resistant polyethylene films. The national standardization body aligns domestic packaging regulations with evolving EU chemical restrictions. Milan-based converters expand captive film extrusion capacity to capture premium segment margin pools.
United States
Craft beverage producers in the Pacific Northwest and Colorado combine shrink sleeve decoration with returnable bottle pilot programs. FDA food contact substance notifications govern adhesive formulation for domestic beverage applications. California's extended producer responsibility framework pressures importers to certify wash-off compatibility under state-level packaging regulations.
China
Export-oriented beverage bottlers in Guangdong and Zhejiang provinces adapt label specifications for EU-bound container shipments. GB standards for packaging recyclability tighten import specifications for labeled containers entering domestic circular economy streams. Yangtze River Delta converters invest in coating equipment to meet dual certification requirements for European and North American customers.
Wash Off Labels Market Competitive Landscape
Channel-controlling players compete with product-specialist players across adhesive formulation, substrate engineering, and precision converting capabilities. The vendor base spans multinational material science conglomerates with captive R&D networks and regional specialists leveraging leased coating assets. Three archetypes dominate: integrated adhesive-substrate developers, precision die-cutting converters, and asset-light regional formulators. Capacity expansion in European film extrusion and strategic partnerships for caustic-wash certification represent the primary competitive vectors.
Within the integrated material science tier, Avery Dennison Corporation and CCL Industries Inc. exemplify archetypes combining global adhesive R&D with captive manufacturing infrastructure. HERMA GmbH occupies a specialist position anchored in European beverage returnable bottle programs. These three entities represent distinct strategic postures: multinational network leverage, North American supply chain anchoring, and regional application engineering depth.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries Inc. |
| Multi-Color Corporation |
| UPM Raflatac |
| HERMA GmbH |
| LINTEC Corporation |
| Fuji Seal International, Inc. |
| Mondi Group |
| Adcraft Labels |
| Others |
Value Network & Pricing Analysis
Overcapacity in European film extrusion capacity is pressuring converters to absorb adhesive raw material volatility rather than pass through costs, compressing margins while locking in long-term supply contracts with German and Italian beverage bottlers.
Pricing Analysis
Certification level under REACH and FDA food contact substance notifications creates the primary spread between premium and standard labelstock tiers. Three-tier pricing structure across premium, standard, and economy levels reflects compliance documentation depth and caustic-wash performance validation. Price differentiation stems from adhesive migration testing and volume scale commitments. Cost compression in economy-grade paper labels is intensifying because petroleum-derived acrylic monomer feedstocks expose formulators to margin unpredictability. Beverage cooperatives in Germany exhibit highest price sensitivity due to procurement consolidation, while pharmaceutical brands in North America show least sensitivity given compliance documentation requirements.
Supply Chain Analysis
Contract manufacturing concentration among Italian and French precision die-cutting specialists holds converting capacity for European beverage returnable bottle programs. Geographic supply concentration centers on Germany, France, and Italy for adhesive formulation and labelstock converting, with China expanding coating capacity for export-oriented production. Raw material dependencies draw from petroleum-derived acrylic monomers, polyethylene resin for film substrates, and release liner papers. Single-source vulnerability in caustic-wash adhesive chemistry creates formulation lock-in risk for converters. Distribution runs through direct procurement relationships between bottlers and integrated adhesive-substrate developers, with regional converters accessing leased coating assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation mandates are accelerating wash-off label adoption faster than adhesive R&D cycles can adapt, creating a high-growth disruption window for suppliers certifying compliant formulations ahead of enforcement timelines.
For Market Incumbents: Insulate formulation leadership by accelerating bio-based polymer backbone R&D ahead of REACH substance restriction sunset dates. Backward integration into captive film extrusion in Lombardy and Emilia-Romagna captures polyethylene margin pools threatened by regional converter expansion. Lock in multi-year procurement contracts with German returnable bottle cooperatives before competitor certification cycles complete. For New Entrants and Emerging Players: China's Yangtze River Delta converters represent underpenetrated capacity for dual-certification labelstock serving EU-bound export bottlers. Target craft beverage shrink sleeve applications in the US Pacific Northwest and Colorado where small-batch brewers combine premium decoration with returnable pilot programs. Pursue asset-light coating partnerships to access precision die-cutting capabilities without capital commitment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated adhesive-substrate developers with captive R&D networks and long-term beverage bottler contracts. Five-to-ten year viability favors specialists with REACH compliance documentation and caustic-wash certification depth. Watch for ECHA prioritization announcements on specific acrylates as signal for reformulation investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captures polyethylene margin pools in Italian personal care segments. |
| REACH Compliance Certification | Locks in German beverage cooperative procurement ahead of enforcement windows. |
| Asset-Light Coating Partnerships | Enables French and Italian regional converters to access precision capabilities. |
| Bio-Based Adhesive Formulation | Reduces petroleum dependency while maintaining caustic-wash separability. |
| Dual-Certification for China Export | Aligns Yangtze River Delta capacity with EU and North American import specifications. |
Research Methodology
Desk research of ECHA substance restriction databases, FDA food contact substance notifications, and EU Packaging and Packaging Waste Regulation compliance filings preceded structured interviews with adhesive R&D directors, beverage bottler procurement leads, precision die-cutting plant managers, and labelstock distribution channel partners. Secondary validation drew from customs trade data, SEC 10-K filings of listed converters, and industry association reports from European and North American packaging federations. Bottom-up volume modeling triangulated against top-down market sizing across adhesive chemistry, substrate format, and end-use application dimensions.
Assumptions held fixed include REACH substance restriction enforcement timelines and caustic-wash infrastructure temperature parameters at sixty to eighty degrees Celsius, while variables included bio-based polymer adoption rates and craft beverage shrink sleeve penetration. Segmentation dimensions modeled encompass adhesive chemistry type, substrate material grade, end-use compliance tier, container application format, and regional regulatory cluster. CAGRs were derived from growth driver elasticity analysis and substitution rate modeling. Forecast inputs incorporated EU extended producer responsibility scheme implementation pace and China GB standards alignment progress.
Practitioners should monitor ECHA prioritization announcements, FDA migration limit revisions, and German bottler procurement specification changes for early signals of forecast deviation. Forecasts reflect assumptions about regulatory enforcement consistency and adhesive performance validation timelines. Quarterly review of REACH substance restriction updates and beverage bottler cooperative audit schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Future-Proof Pharma Labels Market
Labels
Global Industrial Labels Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
Self-Adhesive Labels Market
Labels
Tags Market
Labels
Self-Laminating Labels Market
Labels
Inspection and Inventory Labels Market
Labels
United States Print Label Market
Labels
Direct Thermal Labels Market
Labels
Wet Glue Labeling Machines Market
Labels
Shrink Sleeve Labels Market
Labels
GCC Labeling Market
Labels
Global Cryogenic Label Market
Labels
Pre-Gummed Labels Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Global Security Labels Market