
 Flow Pack Films Market | 2026-2036
Flow Pack Films Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Pack Films Market Foresight
European flexible packaging capacity is rebalancing as energy-intensive resin processing migrates toward lower-cost polymer feedstock regions. SÜDPACK leverages vertical integration across blown film extrusion and printing to sustain margin control in high-barrier applications. KOROZO Ambalaj anchors Turkish export supply into Middle Eastern and North African markets, while Flexopack competes on specialty nylon coextrusions for fresh protein packaging.
Flow pack films are multilayer flexible laminates, typically 20-150 microns thick, manufactured through blown or cast coextrusion with optional metallization or coating to achieve oxygen transmission rates below 1 cc/m²/day. These structures seal under heat and pressure to form continuous pillow, gusseted, or quad-seal packages that protect moisture-sensitive and oxygen-critical contents during distribution. Polyethylene formulations dominate volume due to cost efficiency and sealability, though biodegradable films represent the fastest-growing material class as brand owners face extended producer responsibility obligations. Food and beverage end-use applications command the largest share of value, with snack foods and confectionery requiring the highest barrier specifications and driving premium pricing tiers.
The EU's PPWR and REACH frameworks mandate recyclability-by-design and restrict certain phthalate plasticizers, compelling reformulation of legacy multilayer structures. FDA compliance requirements for indirect food contact additives shape export eligibility for non-European producers seeking access to US distribution channels. Stakeholders must monitor evolving mono-material recyclability standards and decide between retrofitting existing coextrusion assets or investing in entirely new polymer platforms before compliance deadlines crystallize into procurement requirements.
Market Dynamics
Material transitions under the EU's Packaging and Packaging Waste Regulation are forcing coextrusion asset reconfiguration across European flexible packaging supply chains. Producers face compressed timelines to validate mono-material recyclability while maintaining barrier performance specifications for oxygen-sensitive food applications.
Growth Catalysts
- PPWR Recyclability Mandates:The EU's Packaging and Packaging Waste Regulation creates immediate demand for redesign services as brand owners retrofit multilayer structures toward mono-material compatibility without sacrificing shelf-life extension properties.
- Snack Food Portion Control:Single-serve and on-the-go consumption patterns in convenience foods drive specification for thin-gauge, high-seal-strength films that reduce material intensity per unit while preserving product integrity.
- Biodegradable Polymer R&D:PLA and PHA formulation advances are narrowing the performance gap with conventional polyethylene, enabling pilot deployments in fresh produce packaging where oxygen barrier requirements sit below 10 cc/m²/day.
Market Restraints
- Ethylene Feedstock Volatility:European crackers dependent on naphtha cracking face margin compression when Brent crude spreads widen, forcing selective production curtailments at Ludwigshaven and Rotterdam polymer complexes.
- Barrier Coating Concentration:Metallization and aluminum oxide coating capacity clusters in southern Germany and northern Italy, creating geographic single-source risk for high-barrier specifications above 0.5 cc/m²/day oxygen transmission.
- Mechanical Recycling Limitations:Current sorting infrastructure cannot separate multilayer films at commercial scale, rendering most legacy flow pack structures technically recyclable but practically excluded from circular economy loops.
Strategic Opportunities
- Central European Coextrusion Modernization:Czech and Polish processors lag German barrier film capabilities by approximately two equipment generations, creating acquisition and technology licensing prospects for mid-cap specialists.
- Pharmaceutical Blister Alternative Conversion:Unit-dose pharmaceutical packaging represents a white-space application where flow pack formats can displace rigid PVC blisters if EMA extractables testing protocols validate polymer compliance.
- Digital Printing Integration:Combination of HP Indigo and Xeikon narrow-web presses with coextrusion lines enables short-run customization for regional brand variants, collapsing minimum order quantities from 10-tonne to 500-kilogram runs.
Industry Challenges
- Multilayer Extrusion Technician Scarcity:Die gap adjustment and layer ratio optimization for seven-plus layer structures require skills concentrated among operators aged 50-plus, with vocational pipeline replacement rates below retirement velocity.
- REACH Pre-registration Burden:Novel biodegradable additives face eighteen-month ECHA dossier preparation timelines, delaying commercialization of reformulated structures targeting 2027 compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Pack Films Market |
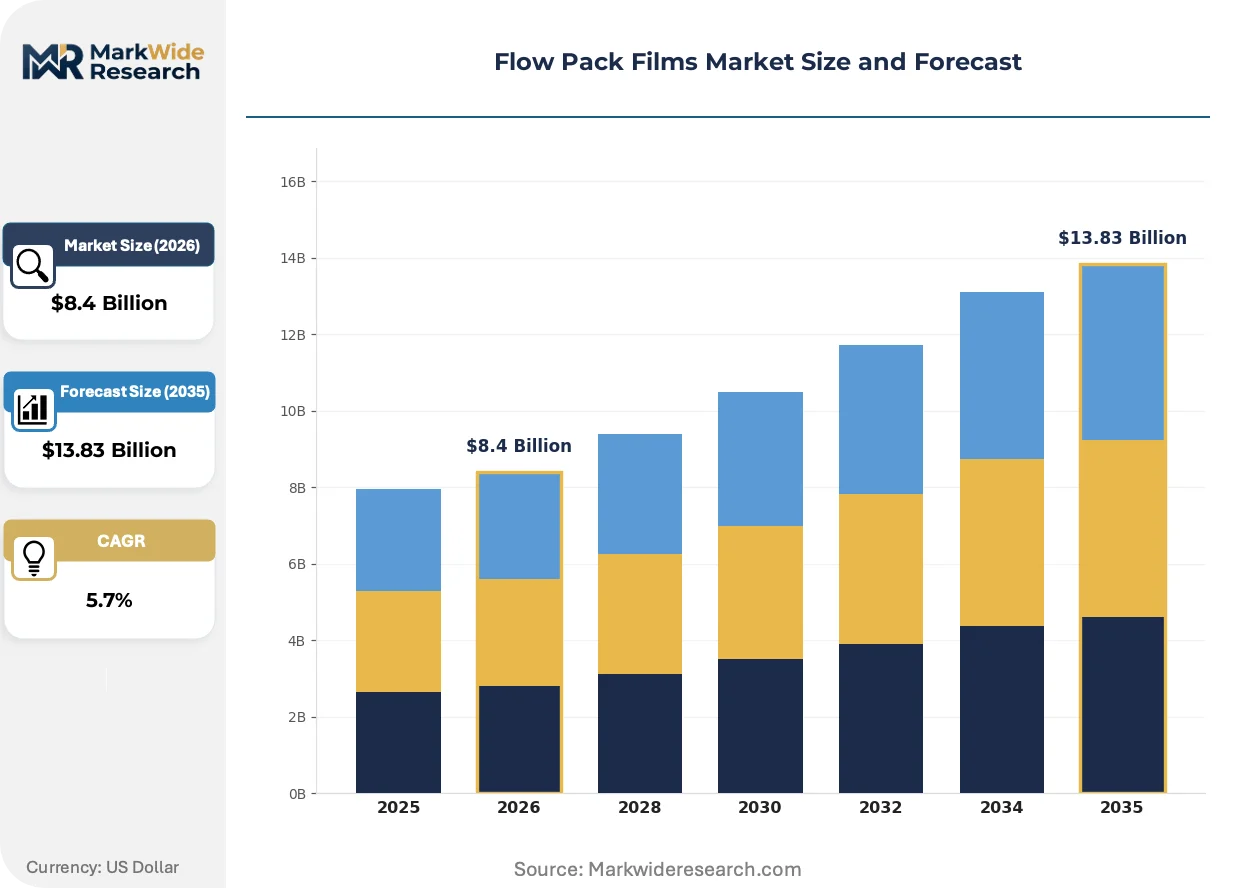
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Material: Polyethylene, Polypropylene, Polyester, Nylon, Cellophane, Biodegradable Films End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Electronics, Household Products, Stationery Packaging Type: Pillow Packs, Gusseted Bags, Wrap-around Packs, Quad Seal, Stick Packs, Flow Wraps Application: Snack Foods, Confectionery, Medical Devices, Detergents, Pet Food, Consumer Goods |
| Companies Covered | SÜDPACK, Accolade Packaging, Linpac, Multifilm Packaging, Lietpak Sweden, Flexopack, NNZ Group, KOROZO Ambalaj, Plastopil Flexible Packaging Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Pack Films Market Shifts & Advancements
Digital workflow integration and polymer platform diversification are compressing product development cycles while fragmenting specification authority away from central procurement functions toward regional brand management teams.
Mono-material polyethylene barrier films incorporating ethylene vinyl alcohol copolymer tie layers are decentralizing specification authority from multinational food conglomerates toward regional co-packers. Mid-sized meat processors in Spain and Portugal now source directly from extruders rather than through distributor intermediaries, collapsing traditional three-tier supply hierarchies into direct technical partnerships.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated coatings from grease-resistant snack food applications by 2026. Paperboard and molded fiber substitutes capture premium confectionery segments, while film producers accelerate silicon oxide deposition R&D to recover barrier performance without regulatory exposure.
Brand owners now embed sustainability scorecards into supplier qualification protocols, displacing pure unit-cost procurement optimization. French retail chains Carrefour and Intermarché have implemented packaging carbon footprint thresholds as hard eligibility gates, filtering film vendors on lifecycle assessment metrics before price negotiation begins.
Flow Pack Films Market Segmentation
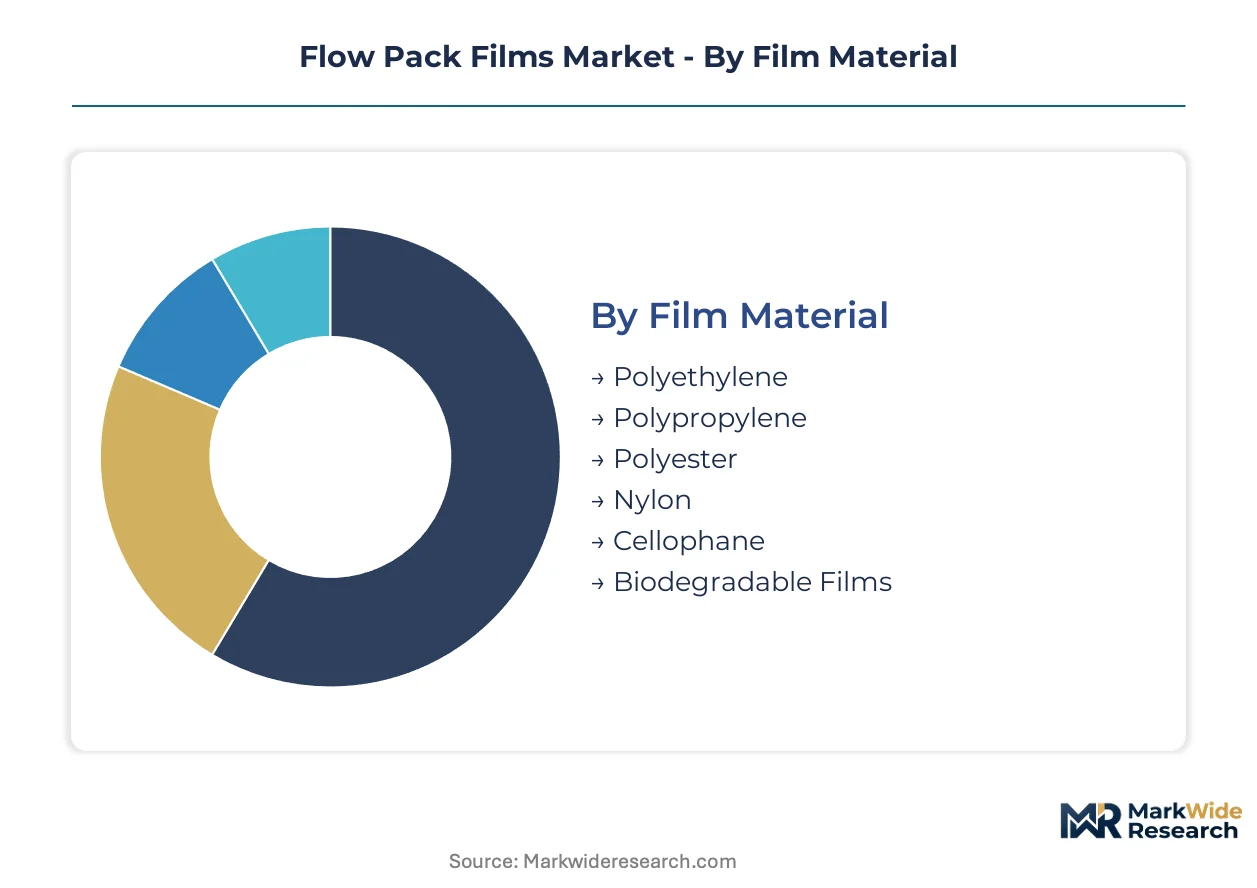
Flow pack film specifications fragment across material platforms, barrier requirements, and sealing technologies. Procurement teams balance shelf-life performance against recyclability mandates and equipment compatibility. Each segmentation axis reveals distinct margin structures and supplier capability requirements.
Film Material:
Customization intensity spans from commodity polyethylene formulations to engineered biodegradable structures requiring specialized extrusion assets.
- Polyethylene:Linear low-density and metallocene grades dominate volume through superior heat-seal response and dart impact resistance. German snack food processors specify PE for high-speed form-fill-seal lines running above 200 packages per minute.
- Biodegradable Films:PLA and PHA platforms narrow the performance gap with conventional polymers through improved thermal stability and oxygen barrier. French retail chains now mandate biodegradable specifications for fresh produce categories, accelerating pilot deployments across Iberian co-packers.
- Polypropylene:Cast PP delivers optical clarity and stiffness for premium confectionery presentation.
- Polyester:PET provides dimensional stability and print registration accuracy for high-graphic applications.
- Nylon:PA6 and PA6/66 coextrusions anchor puncture resistance for bone-in meat and frozen protein.
- Cellophane:Regenerated cellulose serves niche premium segments requiring dead-fold properties and grease resistance.
Leading the category by volume: Polyethylene. Growing fastest: Biodegradable Films.
End Use Industry:
Margin concentration tracks regulatory burden and barrier specification intensity across customer verticals.
- Food & Beverage:Oxygen transmission specifications below 1 cc/m²/day drive seven-layer coextrusion with EVOH core barriers. Italian pasta and cured meat processors maintain the highest specification density, sourcing directly from SÜDPACK and regional extruders rather than distributor channels.
- Pharmaceuticals:Unit-dose packaging demands extractables validation per EMA guidelines and moisture barrier performance exceeding food-grade requirements. Compliance timelines stretch 18-24 months for polymer qualification, concentrating procurement among pre-validated supply bases.
- Personal Care:Cosmetic wipes and single-use sachets prioritize seal integrity and aesthetic surface finish.
- Electronics:Anti-static formulations protect sensitive components during distribution.
- Household Products:Detergent pods and cleaning wipes require chemical resistance and child-resistant closure compatibility.
- Stationery:Low-barrier specifications favor cost-optimized monolayer structures.
Food & Beverage commands the largest revenue pool. Pharmaceuticals posts the steepest expansion trajectory on compliance-driven specification upgrades.
Packaging Type:
Equipment investment and line speed requirements stratify procurement authority between multinational converters and regional co-packers.
- Pillow Packs:Continuous horizontal form-fill-seal formats seal three sides around product, accommodating irregular shapes at speeds exceeding 300 units per minute. German confectionery producers specify pillow configurations for count-line candy and chocolate tablets.
- Gusseted Bags:Side folds expand cubic capacity for bulk dry goods while maintaining vertical stability. French pet food specialists favor gusseted formats for 2-5kg dry kibble presentations.
- Wrap-around Packs:Sleeve configurations group multi-unit presentations for club store channels.
- Quad Seal:Four-side sealing delivers maximum graphic billboard area and shelf stability for premium positioning.
- Stick Packs:Narrow vertical formats suit single-serve powder and liquid portions.
- Flow Wraps:Overwrap configurations protect trays and rigid containers.
Pillow Packs dominate unit volume. Quad Seal configurations gain share fastest on premium positioning requirements.
Application:
Product shelf-life sensitivity and distribution temperature requirements determine barrier investment levels.
- Snack Foods:Nitrogen flush compatibility and oil resistance specifications demand metallized or ceramic-coated structures. Spanish potato chip and nut processors specify oxygen barriers below 0.5 cc/m²/day to maintain six-month shelf life under Mediterranean distribution temperatures.
- Medical Devices:Sterile barrier systems require validated seal strength and particulate control exceeding food-grade protocols. EMA and FDA dual compliance concentrates supply among audited film converters with cleanroom coating capabilities.
- Confectionery:Moisture and fat barrier requirements preserve texture and prevent bloom.
- Detergents:Chemical resistance and fragrance retention drive coextruded structures.
- Pet Food:Fat oxidation control and odor barrier specifications match human food requirements.
- Consumer Goods:General merchandise applications tolerate lower barrier investments.
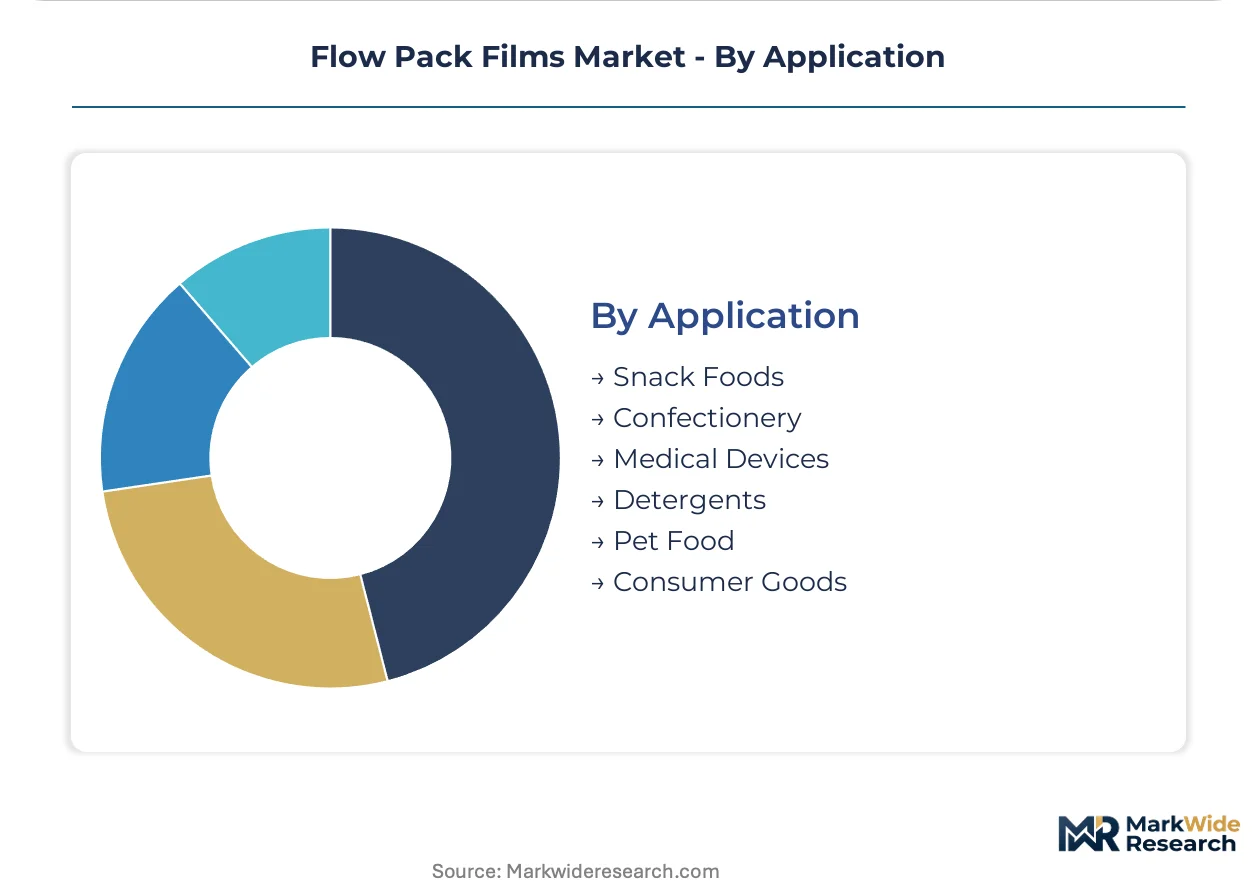
Snack Foods anchor category volume. Medical Devices expand most quickly on healthcare supply chain reshoring initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene feedstock availability from Rotterdam and Antwerp polymer complexes anchors European flow pack film supply chains. Naphtha crackers in the ARA hub supply resin to extrusion assets across the Rhine-Ruhr industrial corridor. Regional demand concentrates in Germany, France, Italy, Spain, and Poland.
Germany
Snack food manufacturers in Bavaria and Baden-Württemberg specify high-barrier coextrusions for nitrogen-flushed packaging. The Packaging and Packaging Waste Regulation forces material transitions toward mono-material recyclability by 2030. SÜDPACK operates vertically integrated blown film extrusion in Ochsenhausen, supplying German meat processors directly.
France
Carrefour and Intermarché impose carbon footprint thresholds that filter film vendors before price negotiation. The national regulator enforces extended producer responsibility schemes that accelerate biodegradable film pilots. Fresh produce co-packers in the Île-de-France region now source PLA-based structures for leafy green categories.
Italy
Pasta and cured meat processors in Emilia-Romagna maintain the highest barrier specification density in Southern Europe. ECHA REACH restrictions on phthalate plasticizers compel reformulation of legacy multilayer structures. Metallization capacity clusters around Milan and Turin, serving premium confectionery exporters.
Spain
Potato chip and nut processors specify oxygen barriers below 0.5 cc/m²/day for Mediterranean distribution temperatures. Spanish regulators align with EU PPWR timelines while allowing transitional multilayer structures through 2027. Barcelona-area extruders supply Iberian co-packers shifting toward direct technical partnerships.
Poland
Central European meat processors seek cost-optimized barrier films for export to German retail chains. Polish environmental inspectors enforce EU packaging waste directives with phased compliance windows. Łódź and Warsaw extrusion assets lag German equipment generations, creating technology licensing demand.
Flow Pack Films Market Competitive Landscape
Global majors compete with regional champions across barrier technology and vertical integration depth. The vendor base stratifies into three tiers: integrated resin-to-film operators, specialized coextrusion houses, and regional converter-distributors. Strategic archetypes include backward-integrated polymer compounders, high-barrier coating specialists, and digital-print-enabled short-run providers. Capacity expansion and technology licensing dominate competitive moves as producers retrofit assets for mono-material compliance.
Among German integrated operators, SÜDPACK exemplifies the resin-through-printing archetype with captive extrusion and metallization capabilities. KOROZO Ambalaj represents Turkish export-oriented supply into Middle Eastern and North African markets. Flexopack occupies a position within specialty nylon coextrusion for fresh protein applications. These three anchors illustrate the geographic and technological fragmentation across European flexible packaging supply chains.
| Leading Market Players |
|---|
| SÜDPACK |
| Accolade Packaging |
| Linpac |
| Multifilm Packaging |
| Lietpak Sweden |
| Flexopack |
| NNZ Group |
| KOROZO Ambalaj |
| Plastopil Flexible Packaging Solutions |
| Others |
Supply & Pricing Matrix
Mono-material coextrusion line retrofits simultaneously compress conversion costs and concentrate supply authority among German and Italian processors with capital reserves for EVOH tie-layer validation. This technology transition fragments procurement hierarchies as mid-sized meat processors in Spain and Portugal negotiate directly with extruders, collapsing distributor markups that historically buffered price transparency.
Pricing Analysis
Technical service bundling separates premium-tier suppliers from commodity extruders, with SÜDPACK and Flexopack including die-gap optimization and seal-strength validation within contract terms while economy-tier vendors unbundle these support functions. Three-tier pricing structure across premium, standard, and economy levels tracks barrier specification intensity, with oxygen transmission below 0.5 cc/m²/day commanding substantial premiums. Cost compression in standard-tier polyethylene formulations is intensifying because Czech and Polish processors are importing German equipment generations to close capability gaps. Private-label snack food manufacturers exhibit highest price sensitivity, while pharmaceutical unit-dose specifications tolerate premium positioning due to eighteen-month EMA validation timelines.
Supply Chain Analysis
EMA and FDA dual-compliance certification gates concentrate pharmaceutical-grade film supply among audited converters with cleanroom metallization capabilities. Raw material flows draw from Rotterdam and Antwerp naphtha crackers, with resin supply tethered to Ludwigshaven and Rotterdam polymer complexes for high-barrier coextrusion feedstock. EVOH copolymer and metallization coating dependencies create single-source vulnerability for specifications exceeding 0.5 cc/m²/day oxygen transmission. Distribution runs through direct technical partnerships displacing three-tier hierarchies, with Spanish and Portuguese co-packers sourcing straight from Ochsenhausen and Milan extrusion assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with backward integration into blown film extrusion and metallization coating emerging as the decisive lever for margin control against feedstock volatility.
For Market Incumbents: Cement barrier technology leadership by acquiring Czech and Polish extrusion assets two equipment generations behind German capabilities, converting these lines for mono-material EVOH structures before PPWR compliance deadlines crystallize. Deepen captive supply of metallization capacity in southern Germany and northern Italy to offset geographic single-source risk for high-barrier specifications. Prioritize R&D investment in silicon oxide deposition to recover grease-resistance performance lost to REACH fluorinated coating restrictions. For New Entrants and Emerging Players: The price-point gap between validated pharmaceutical-grade films and commodity food-grade polyethylene creates entry space for mid-cap specialists. Target Iberian fresh produce co-packers mandated by French retail chains to source biodegradable PLA structures, where oxygen barrier requirements sit below 10 cc/m²/day and technical validation demands remain manageable. Pursue digital printing integration with HP Indigo or Xeikon narrow-web presses to capture short-run regional brand variant demand, collapsing minimum order quantities from traditional 10-tonne runs. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to resin compounders seeking downstream film conversion capabilities or private-equity roll-ups of fragmented Central European extrusion assets. Five-to-ten-year viability hinges on successful mono-material platform transitions before mechanical recycling infrastructure matures. Target acquisition archetype: mid-cap coextrusion houses with validated EVOH tie-layer expertise and direct relationships with meat processors in Spain, Portugal, or Poland. Watch for inflection when ECHA REACH pre-registration timelines for novel biodegradable additives compress below twelve months, signaling commercialization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Retrofit | PPWR compliance mandates EVOH tie-layer validation without sacrificing oxygen barrier performance specifications. |
| Backward Integration into Metallization | Captive coating capacity insulates margin control against geographic single-source risk in southern Germany. |
| Digital Printing Integration | HP Indigo and Xeikon narrow-web presses enable 500-kilogram minimum runs for regional brand variants. |
| Biodegradable Polymer R&D Partnership | PLA and PHA formulation advances target French retail chain mandates for fresh produce categories. |
| Central European Acquisition | Czech and Polish extrusion assets lag German capabilities, creating technology licensing and upgrade demand. |
Research Methodology
Document review covered ECHA REACH registration databases, EU PPWR implementation guidelines, and flexible packaging trade association technical specifications, complemented by interviews with blown film extrusion plant managers, procurement leads at German meat processors, distribution channel partners in Iberia, and technical R&D directors at coextrusion equipment manufacturers. Secondary validation drew from customs and resin trade data, SEC filings of listed packaging converters, and European Plastics Association capacity surveys. Bottom-up volume estimates triangulated against top-down spending patterns across food, pharmaceutical, and personal care end-use segments.
Segmented outputs across the projection horizon reflect material platform, barrier specification tier, end-use industry, and regional production cluster dimensions, with CAGRs derived from elasticity modeling against ethylene feedstock price scenarios and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated EMA extractables testing protocol timelines and French retail chain carbon footprint threshold implementations.
Inputs from ECHA dossier filings and EU member state PPWR transposition documents were available through the study window; gaps in real-time biodegradable additive commercialization timelines introduce uncertainty bands around PLA and PHA penetration assumptions. Forecasts reflect documented assumptions on mechanical recycling infrastructure development and resin feedstock sourcing patterns. A model refresh is warranted upon material change in EVOH copolymer supply availability or REACH substance restriction expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Moisture Barrier Bags Market
Packaging Barrier Films
Non Heat Sealable Film Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Barrier Coated Papers Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Meat Packaging Films Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Barrier Coatings for Packaging Market
Packaging Barrier Films
72 Inch Paint Protection Film Market