
 Relaxor Ferroelectric Ceramics Market | 2026-2036
Relaxor Ferroelectric Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Relaxor Ferroelectric Ceramics Market Analysis
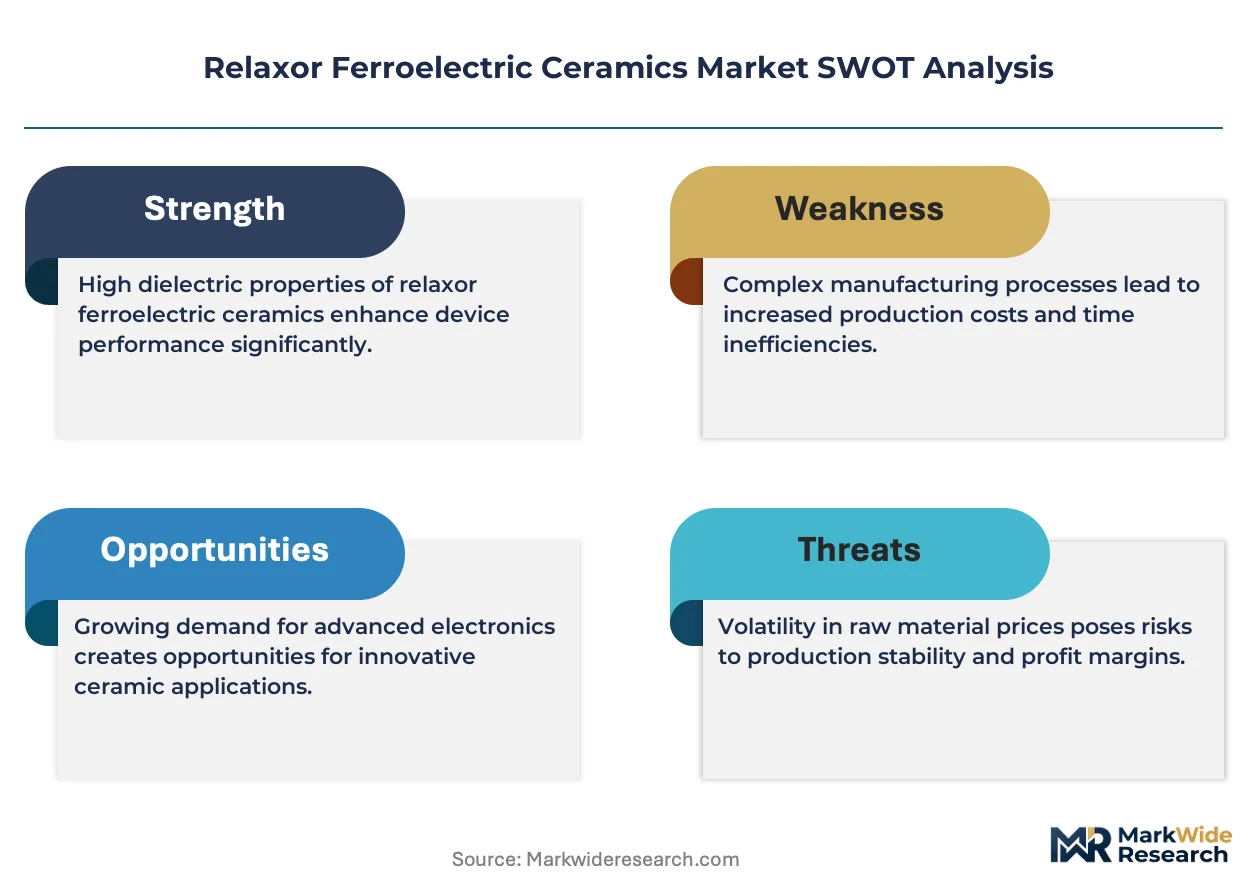
Aftermarket service revenue for piezoelectric calibration and sensor refurbishment is fragmenting across regional service networks. PI Ceramic leverages its vertically integrated wafer-to-package workflow to sustain premium positioning in medical ultrasound transducers. Samsung Electro-Mechanics anchors high-volume supply for smartphone haptic feedback modules through captive powder synthesis operations. Murata Manufacturing competes on dielectric reliability in automotive-grade multilayer capacitors.
Relaxor ferroelectric ceramics exhibit strong electrostriction with compositionally tuned lead magnesium niobate-lead titanate solid solutions, delivering strain responses above conventional piezoelectrics for precision positioning systems. Barium Titanate formulations dominate consumer electronics capacitor applications where cost sensitivity outweighs peak performance requirements. Strontium Barium Niobate thin films represent the fastest-growing delivery mode segment, driven by MEMS integration in aerospace pressure sensors.
EMA's updated Medical Device Regulation imposes biocompatibility documentation on implantable ferroelectric transducers, while REACH restricts lead-bearing compositions in European electronics supply chains. Japan's METI enforces JIS standards for piezoelectric material characterization that shape export qualification protocols. Stakeholders must monitor evolving material substitution timelines as regulators tighten hazardous substance limits without compromising electromechanical performance thresholds.
Market Dynamics
REACH compliance thresholds for lead-bearing compositions are forcing material reformulation across European electronics supply chains, compressing substitution timelines while performance benchmarks remain fixed.
Growth Catalysts
- MEMS integration in aerospace pressure sensors:Strontium Barium Niobate thin films enable miniaturized transducer architectures for altitude and cabin pressure monitoring systems.
- South Korean multilayer ceramic capacitor manufacturing:Domestic powder synthesis operations drive captive material uptake for smartphone haptic feedback modules and automotive-grade dielectric components.
- Japan's METI JIS standards:Export qualification protocols for piezoelectric material characterization shape procurement specifications across precision component clusters in Kyoto and Osaka.
Market Restraints
- Lead-content regulatory friction:ECHA's tightened REACH thresholds restrict lead magnesium niobate-lead titanate formulations in European consumer electronics without mature non-lead alternatives matching electrostrictive performance.
- Raw material supply concentration:Niobium oxide feedstock depends on Brazilian mining operations and Chinese refining capacity, exposing processors to geopolitical disruption and price volatility.
- Barium Titanate substitution ceiling:Cost-optimized formulations dominate consumer electronics where electrostrictive strain response remains secondary to unit economics, capping premium material penetration.
Strategic Opportunities
- Biocompatibility-compliant implantable transducers:EMA's updated Medical Device Regulation creates documentation requirements that favor suppliers with established biocompatibility testing infrastructure for cardiac and neuromodulation devices.
- Medical ultrasound transducer refurbishment networks:Aftermarket service revenue for piezoelectric calibration fragments across regional service networks, opening channel consolidation plays for certified repair operations.
- Wafer-to-package workflow convergence:Vertically integrated manufacturing architectures that combine thin-film deposition with precision dicing and electrode patterning capture margin from medical device OEMs requiring lot traceability.
Industry Challenges
- Material characterization expertise scarcity:Electromechanical coupling coefficient measurement and hysteresis loop analysis require specialized technicians that ceramic engineering programs produce insufficiently.
- Dual regulatory timeline compression:Simultaneous REACH substance restrictions and EMA biocompatibility documentation create overlapping compliance windows that strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Relaxor Ferroelectric Ceramics Market |
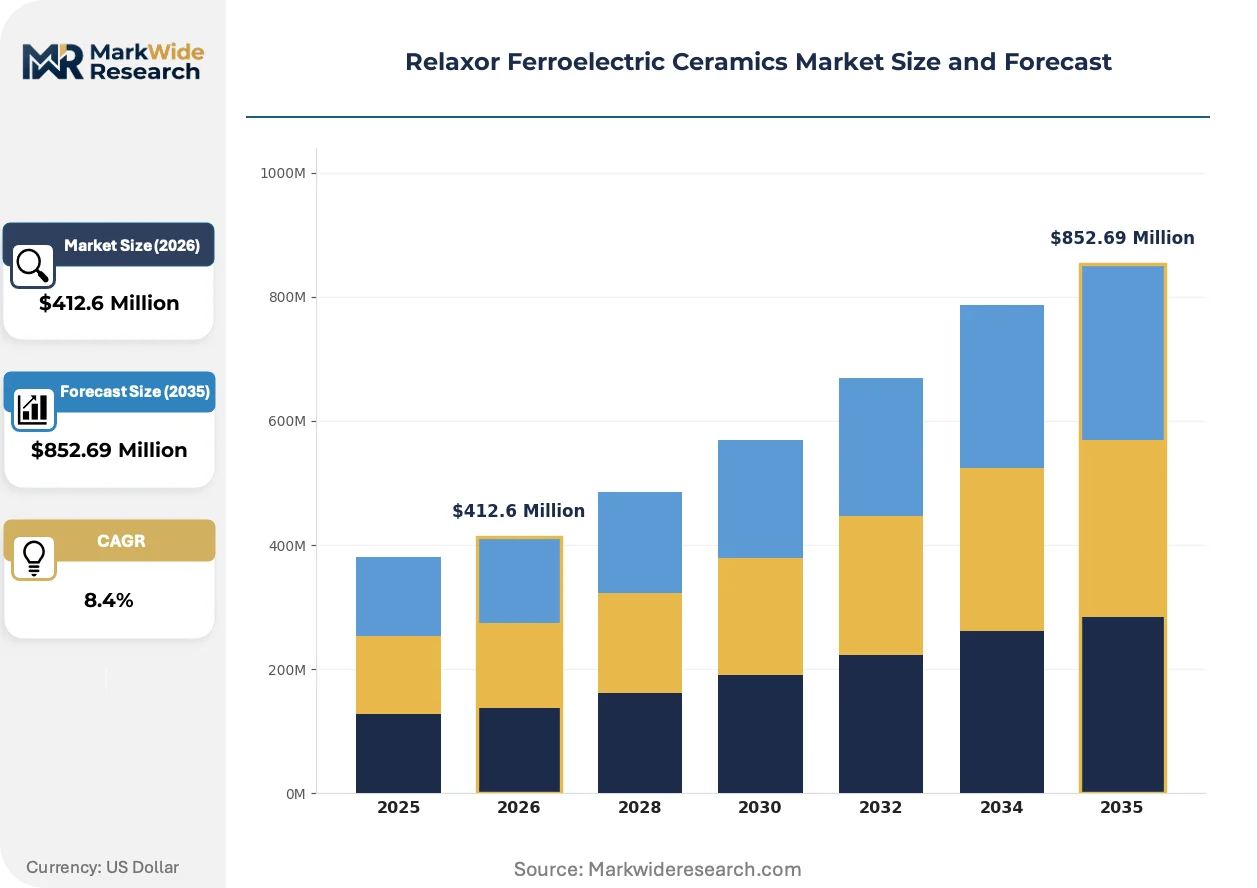
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $852.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barium Titanate, Lead Titanate, Strontium Barium Niobate, Others Industry Vertical: Telecommunications, Electronics, Aerospace, Medical Application: Sensors, Actuators, Capacitors, Transducers Delivery Mode: Bulk, Powder, Thin Film, Others |
| Companies Covered | PI Ceramic, Kojundo Chemical, Samsung Electro-Mechanics, Techno Alpha, Sparkler Ceramics, Kyocera Corporation, Citizen, Murata Manufacturing, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Relaxor Ferroelectric Ceramics Market Emerging Trajectories
Computational materials science and thin-film processing advances are compressing development cycles for compositionally tuned relaxor formulations, enabling faster iteration between electrostrictive performance and regulatory compliance.
Lead-free piezoelectric ceramics is virtualizing competitive positioning in medical implant applications. Cardiac pacemaker and neuromodulation device manufacturers are accelerating qualification timelines for potassium sodium niobate-based compositions. This substitution is virtualizing the traditional lead-based supply chain lock-in that protected incumbent material suppliers.
EMA's updated Medical Device Regulation imposes biocompatibility documentation requirements on implantable ferroelectric transducers. The regulation forces ceramic processors to establish ISO 10993 testing partnerships or in-house biocompatibility laboratories. Implantable neuromodulation devices face the steepest compliance burden, with OEMs now requiring lot-level cytotoxicity data that extends procurement qualification periods.
Service unbundling from hardware sales reshapes aftermarket economics for precision positioning systems. Japanese machine tool OEMs now separate piezoelectric actuator calibration from original equipment contracts, driving demand for third-party metrology laboratories with JIS-traceable standards. This shift concentrates in Germany's automotive press tool sector, where downtime costs accelerate outsourcing decisions for sensor refurbishment.
Relaxor Ferroelectric Ceramics Market Segmentation
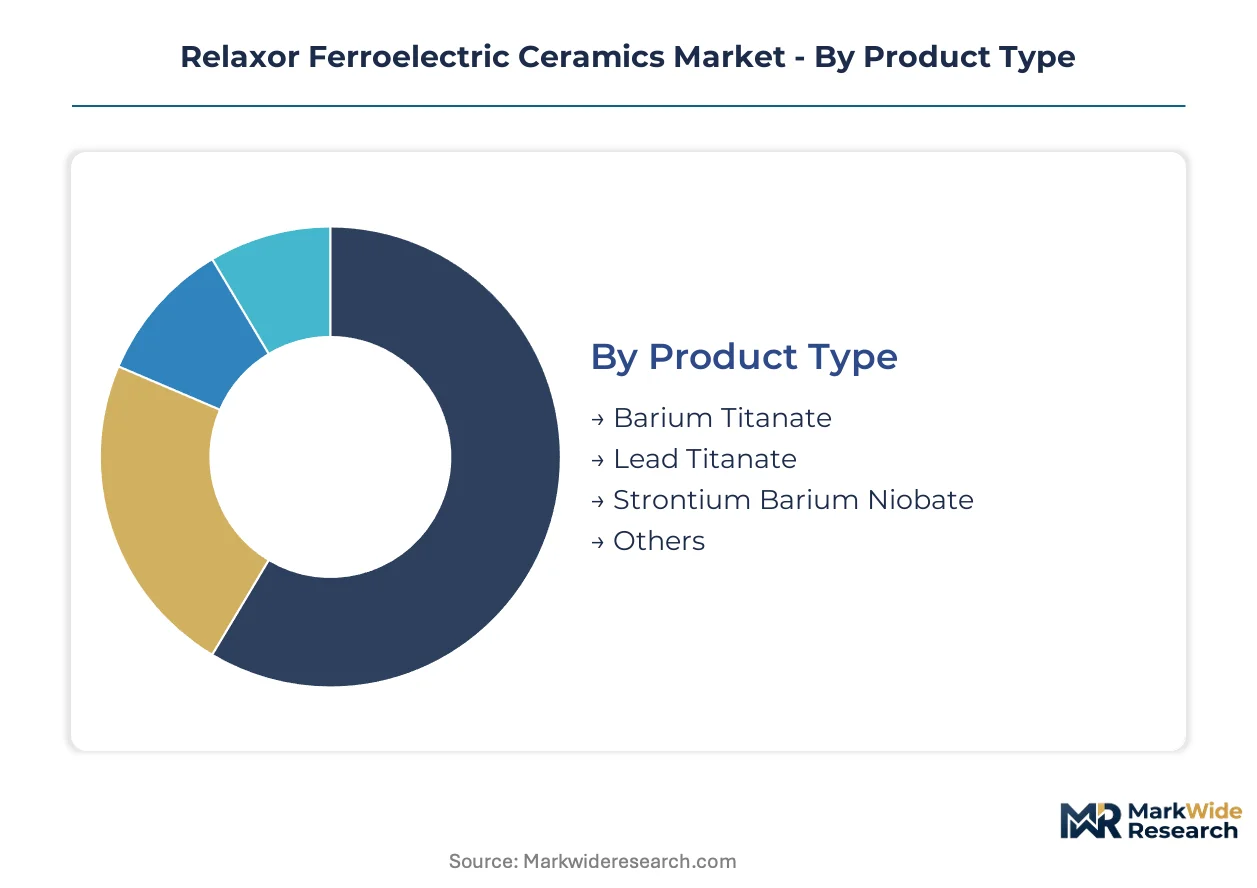
Relaxor ferroelectric ceramics serve divergent performance requirements across precision positioning, energy storage, and signal conversion applications. Material selection hinges on electrostrictive strain response, dielectric constant, and regulatory compliance thresholds that vary by end-use jurisdiction.
Product Type:
The use-case spectrum spans cost-optimized consumer electronics to mission-critical aerospace systems where composition determines electromechanical coupling efficiency.
- Lead Titanate:Lead magnesium niobate-lead titanate solid solutions deliver strain responses above conventional piezoelectrics for precision positioning systems. Demand concentrates in Japan's precision component clusters around Kyoto and Osaka, where METI JIS standards enforce rigorous material characterization protocols that shape export qualification.
- Strontium Barium Niobate:Compositionally tuned thin-film formulations enable miniaturized transducer architectures with strong electrostriction. MEMS integration in aerospace pressure sensors for altitude and cabin pressure monitoring systems is climbing the fastest among product categories.
- Barium Titanate:Cost-optimized formulations dominate consumer electronics capacitor applications where unit economics outweigh peak performance requirements.
- Others:Potassium sodium niobate-based compositions are accelerating qualification timelines for cardiac pacemaker and neuromodulation device applications under EMA biocompatibility documentation requirements.
The dominant share belongs to Lead Titanate, while Strontium Barium Niobate is closing the gap fastest.
Industry Vertical:
Margin profiles diverge sharply between regulated medical implant markets and high-volume consumer electronics procurement.
- Electronics:Multilayer ceramic capacitor manufacturers in South Korea drive captive material uptake through domestic powder synthesis operations for smartphone haptic feedback modules. REACH compliance thresholds in the European Union compress substitution timelines for lead-bearing compositions without mature non-lead alternatives matching electrostrictive performance.
- Medical:Implantable ferroelectric transducers face EMA's updated Medical Device Regulation imposing biocompatibility documentation requirements. Cardiac and neuromodulation device OEMs now require lot-level cytotoxicity data that extends procurement qualification periods.
- Aerospace:Strontium Barium Niobate thin films enable miniaturized pressure sensing architectures where reliability requirements override cost sensitivity.
- Telecommunications:Base station and optical network hardware demand dielectric components with temperature-stable resonant frequencies.
Electronics commands the largest volume position, though Medical exhibits the steepest margin expansion trajectory.
Application:
Functional requirements dictate material architecture choices across sensing, actuation, energy storage, and signal conversion roles.
- Actuators:Precision positioning systems in semiconductor lithography equipment demand sub-nanometer resolution from electrostrictive ceramics. Japanese machine tool OEMs now unbundle piezoelectric actuator calibration from original equipment contracts, driving third-party metrology demand.
- Transducers:Medical ultrasound applications require vertically integrated wafer-to-package workflows that combine thin-film deposition with precision dicing and electrode patterning. Aftermarket service revenue for piezoelectric calibration fragments across regional service networks.
- Sensors:MEMS-integrated pressure transducers for aerospace altitude monitoring utilize Strontium Barium Niobate thin-film architectures.
- Capacitors:Automotive-grade multilayer dielectric components compete on reliability metrics under tightened thermal cycling specifications.
Actuators retain the dominant application share, with Transducers gaining ground fastest on medical device OEM procurement expansion.
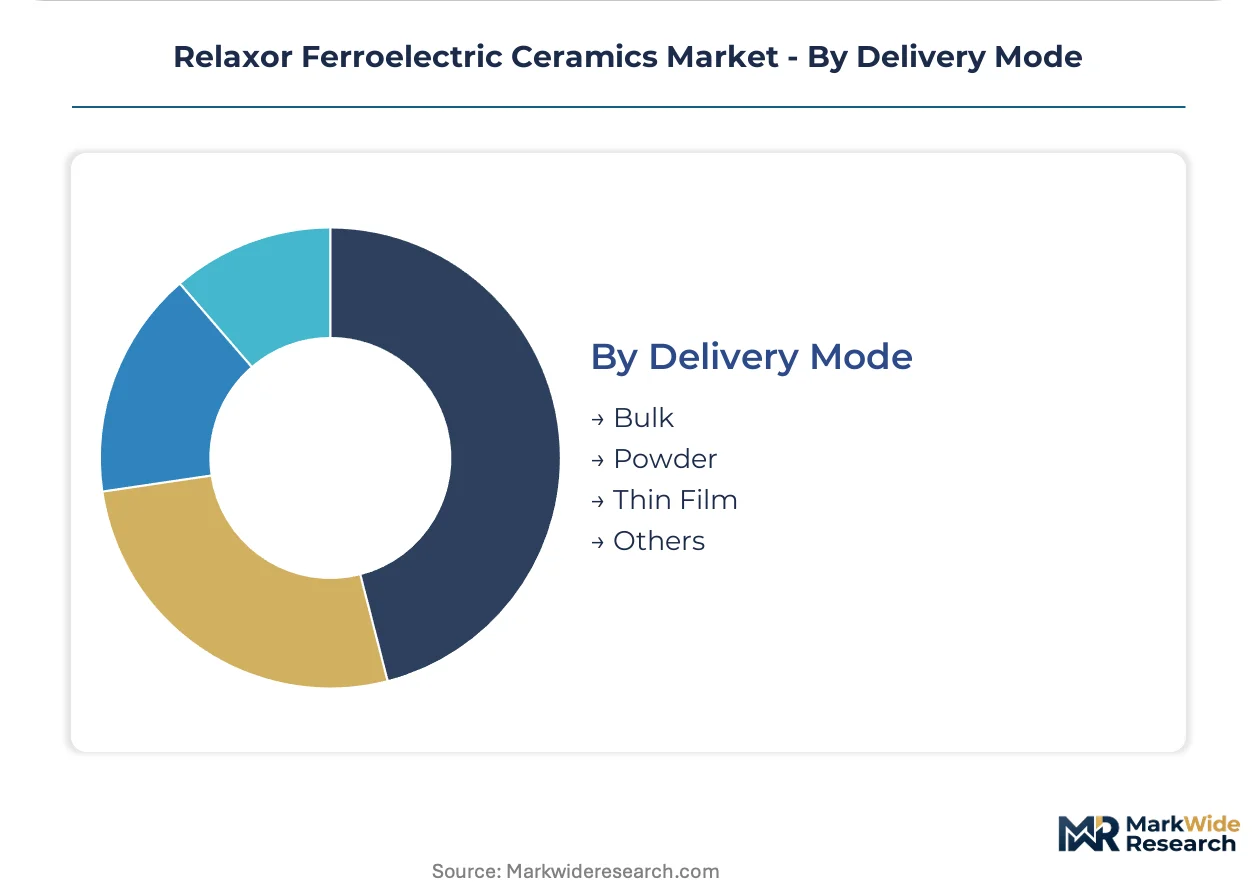
Delivery Mode:
Supply chain configuration reflects customer scale, lot traceability requirements, and in-house processing capabilities.
- Thin Film:Strontium Barium Niobate deposition on silicon substrates enables MEMS integration for aerospace pressure sensors. Sputtering and sol-gel processes require specialized equipment that concentrates supply among vertically integrated processors.
- Powder:Captive synthesis operations at South Korean multilayer ceramic capacitor manufacturers anchor high-volume supply for smartphone haptic feedback modules. Niobium oxide feedstock dependence on Brazilian mining and Chinese refining exposes processors to geopolitical disruption.
- Bulk:Machined ceramic blocks serve precision positioning systems requiring custom geometries and electrode patterning.
- Others:Tape-cast green sheets and pre-sintered blanks address intermediate processing stages for specialized component fabricators.
Powder maintains the largest volume position, though Thin Film is expanding most quickly on MEMS integration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan deploys relaxor ferroelectric ceramics predominantly for precision positioning actuators, whereas South Korea channels material output toward smartphone haptic modules and automotive capacitors. Germany's industrial base emphasizes medical ultrasound transducers and aerospace pressure sensors. The United States concentrates demand in implantable neuromodulation devices and semiconductor lithography equipment.
Japan
Precision component clusters around Kyoto and Osaka anchor domestic consumption for semiconductor lithography actuators. METI enforces JIS standards for piezoelectric material characterization that shape export qualification protocols for ceramic processors. Kansai-based fabricators supply sub-nanometer resolution positioning systems to domestic machine tool OEMs.
South Korea
Multilayer ceramic capacitor manufacturers drive captive material uptake through domestic powder synthesis operations for smartphone haptic feedback modules. The country's national industrial regulator mandates hazardous substance documentation that compresses lead-content substitution timelines. Seoul Capital Area facilities anchor high-volume supply chains for automotive-grade dielectric components.
Germany
Automotive press tool OEMs outsource piezoelectric actuator calibration to third-party metrology laboratories with traceable standards. ECHA's tightened REACH thresholds restrict lead-bearing formulations in consumer electronics supply chains. Bavaria-based precision engineering clusters concentrate demand for medical device component qualification.
United States
Implantable neuromodulation device manufacturers accelerate qualification timelines for lead-free ceramic compositions under FDA biocompatibility pathways. EPA and state-level environmental regulations pressure material reformulation for electronics applications. Greater Boston and Pacific Northwest medical device clusters drive procurement for cardiac pacemaker transducers.
China
Niobium oxide refining capacity concentrates domestic control over critical feedstock for relaxor ceramic synthesis. SAMR enforces GB standards for electronic ceramics that shape import substitution strategies. Yangtze River Delta processing facilities supply MEMS-integrated pressure sensors for domestic aerospace programs.
Relaxor Ferroelectric Ceramics Market Vendor Landscape
Capability concentration sits with vertically integrated specialists; scale advantage sits with captive powder synthesis operations at electronics conglomerates. The market structures around three tiers: wafer-to-package workflow owners, high-volume multilayer capacitor suppliers, and regional component fabricators. Dominant competitive moves include backward integration into niobium oxide feedstock and strategic partnerships with medical device OEMs for biocompatibility documentation.
Among Japanese fabricators, PI Ceramic exemplifies the vertically integrated specialist archetype through its medical ultrasound positioning, while Murata Manufacturing and Kyocera Corporation occupy scale-driven roles in dielectric component supply. Samsung Electro-Mechanics represents the captive synthesis model through South Korean electronics conglomerate integration. These three anchors illustrate how geographic clustering around Kyoto-Osaka and Seoul Capital Area shapes competitive differentiation between precision-tier and volume-tier supply.
| Leading Market Players |
|---|
| PI Ceramic |
| Kojundo Chemical |
| Samsung Electro-Mechanics |
| Techno Alpha |
| Sparkler Ceramics |
| Kyocera Corporation |
| Citizen |
| Murata Manufacturing |
| ABB |
| Others |
Supply Flow & Price Mechanics
Brazilian niobium oxide mining concentration and Chinese refining dominance upstream tether margin capture to processors with captive powder synthesis operations in South Korea and Japan. Long-term offtake contracts for aerospace-grade Strontium Barium Niobate thin films command premium positioning against spot-market Barium Titanate powder transactions in consumer electronics procurement.
Pricing Analysis
Long-term offtake agreements dominate aerospace and medical implant procurement, while spot-market transactions govern high-volume consumer electronics capacitor sourcing. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified precision actuators from automotive-grade dielectric components and commodity Barium Titanate formulations. Pricing pressure stems from REACH-driven lead-content reformulation costs without performance-matched non-lead alternatives. Medical device OEMs exhibit lowest price sensitivity due to biocompatibility documentation requirements, whereas smartphone haptic module manufacturers face acute cost compression.
Supply Chain Analysis
Export-control regimes on advanced thin-film deposition equipment limit Strontium Barium Niobate MEMS integration capacity outside Japan and Germany. Niobium oxide feedstock draws from Brazilian mining operations and Chinese refining infrastructure, with ceramic powder synthesis concentrating in South Korea and Japan. Single-source vulnerability sits with niobium oxide supply given geographic concentration of extractive operations. Distribution runs through vertically integrated wafer-to-package processors serving medical ultrasound transducer OEMs and captive powder operations at multilayer capacitor manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized electromechanical characterization expertise scarcity constrains quality assurance bandwidth as dual regulatory timelines compress substitution and biocompatibility compliance windows simultaneously.
For Market Incumbents: Build backward integration moats into niobium oxide feedstock to defend against raw material supply concentration risks from Brazilian mining disruption. Invest in ISO 10993 biocompatibility testing infrastructure to capture EMA Medical Device Regulation documentation requirements for implantable neuromodulation transducers. Anchor capacity expansion in Seoul Capital Area clusters to maintain scale advantage in smartphone haptic feedback module supply. For New Entrants and Emerging Players: Mid-market medical ultrasound transducer refurbishment networks in Germany and the United States represent the most penetrable entry point given fragmented regional service coverage and unbundled calibration contracts from Japanese machine tool OEMs. Target potassium sodium niobate-based composition qualification for cardiac pacemaker applications where lead-free substitution timelines accelerate. Pursue JIS-traceable metrology laboratory partnerships as the go-to-market angle for third-party piezoelectric calibration services. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional component fabricators lacking wafer-to-package workflow integration. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than pure scale positioning. Acquisition target archetype: vertically integrated thin-film processors with established biocompatibility testing partnerships. Watch ECHA REACH threshold enforcement intensity as the inflection signal for lead-bearing composition substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Niobium Oxide Feedstock | Captive supply of critical raw material insulates processors from Brazilian mining geopolitical disruption and price volatility. |
| ISO 10993 Biocompatibility Laboratory Investment | In-house testing infrastructure accelerates EMA Medical Device Regulation documentation for implantable neuromodulation device procurement. |
| Wafer-to-Package Workflow Convergence | Combined thin-film deposition with precision dicing captures margin from medical device OEMs requiring lot traceability. |
| Long-term Aerospace Offtake Contracting | Structured agreements with altitude pressure sensor manufacturers stabilize revenue against consumer electronics spot-market volatility. |
| Regional Metrology Laboratory Certification | JIS-traceable third-party calibration services capture unbundled piezoelectric actuator maintenance from German automotive press tool OEMs. |
Methodological Framework
The analysis maps relaxor ferroelectric ceramic product types, delivery modes, and industry verticals, each validated through ceramic engineering directors, medical device OEM procurement managers, and multilayer capacitor manufacturing executives. Primary interview findings triangulate against METI JIS standard documentation, ECHA REACH substance restriction filings, EMA Medical Device Regulation guidance, and customs trade data for niobium oxide feedstock flows. Bottom-up segment sizing and top-down market reconciliation ensure cross-validation across precision positioning, energy storage, and signal conversion application clusters.
Assumptions held fixed include current REACH lead-content thresholds and JIS piezoelectric characterization protocols, while niobium oxide supply disruption scenarios and potassium sodium niobate qualification timelines varied across sensitivity runs. Segmentation modeling spans composition chemistry, delivery mode architecture, end-use vertical, and geographic production cluster. CAGRs derive from installed base growth in semiconductor lithography equipment, MEMS-integrated aerospace sensor deployment, and implantable neuromodulation device volumes. Forecast inputs incorporate powder synthesis capacity expansion announcements and thin-film deposition equipment order backlogs.
Practitioners should monitor ECHA substance restriction proposals and FDA biocompatibility pathway updates for early signals of regulatory timeline compression. Forecasts reflect these documented assumptions regarding substitution technology maturity and regional supply chain configuration. Material shifts in niobium oxide export policy or breakthrough lead-free electrostrictive performance matching would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Setter Plate Market
Ceramics
Europe Aluminum Oxide Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
Solid-Ion Conductors Market
Ceramics
Ceramics Packaging Market
Ceramics
Global Industrial Clay Market
Ceramics
ME K-Feldspar Market
Ceramics
Medical Ceramics Market
Ceramics
Calcined Bauxite Market
Ceramics
Ball Clay Market
Ceramics
Nano Ceramic Coatings Market
Ceramics
North America Ceramic Coatings Market
Ceramics
Aluminium Nitride Market
Ceramics
Fly Ash and Ceramic Microsphere Market
Ceramics
Malaysia Ceramic Tiles Market
Ceramics
Global Zirconia Oxygen Sensors Market