
 Europe Ceramic Coatings Market | 2026-2036
Europe Ceramic Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ceramic Coatings Market Foresight
Spanish thermal spray capacity is rebalancing toward aerospace-qualified production lines after years of automotive-dominant utilization. Bodycote plc leverages its pan-European network of service centers to sustain proximity-based relationships with tier-one suppliers across France and Italy. Hauzer Techno Coating B.V. anchors the Benelux region through its PVD and CVD equipment ecosystem, while Morgan Advanced Materials plc competes on ceramic formulation intellectual property developed at its UK technical center.
Ceramic coatings constitute inorganic, non-metallic layers deposited onto metallic or composite substrates to impart thermal insulation, wear resistance, or chemical protection, typically formulated from oxides, carbides, nitrides, or silicates and applied through processes reaching 15,000°C in plasma spray torches. Thermal spray coatings occupy the largest installed base across European maintenance-repair-operations infrastructure, while sol-gel coatings represent the fastest-expanding technology platform for electronics and biomedical precision finishing. Plasma spray deposition commands premium pricing in aerospace blade applications where porosity below 2% determines airworthiness certification.
REACH restrictions on chromium VI compounds and the EU Green Deal industrial emissions framework compel coating users to validate alternative surface treatments through ECHA-registered substitution assessments. EASA airworthiness directives and CE marking under the EU Machinery Directive shape product qualification protocols for coating applicators serving regulated industries. Stakeholders must monitor revision timelines for the F-Gas Regulation, as fluorinated precursor chemistries face phase-down schedules that could disrupt certain CVD process chemistries.
Market Dynamics
REACH-driven substitution of hexavalent chromium plating with ceramic alternatives is restructuring procurement specifications across European precision manufacturing, forcing coating applicators to revalidate entire process portfolios through ECHA-registered assessment protocols.
Growth Catalysts
- EU Green Deal decarbonization mandates:Industrial emissions frameworks compel automotive OEMs to abandon electroplating lines in favor of thermal barrier ceramic coatings for powertrain thermal management.
- Aerospace blade refurbishment cycles:Plasma spray deposition with sub-2% porosity specifications commands premium positioning as MRO infrastructure expands across European maintenance hubs.
- Precision engineering clusters:Procurement concentrates in Bavaria and Baden-Württemberg, where specification-grade coating volumes track German automotive and industrial equipment production schedules.
Market Restraints
- Fluorinated precursor supply uncertainty:F-Gas Regulation phase-down schedules threaten disruption to CVD process chemistries reliant on fluorinated feedstocks.
- Capital intensity of aerospace qualification:EASA airworthiness certification timelines extend 18-36 months for new coating formulations, freezing out mid-scale applicators without balance sheet depth.
- Technical limitation in electronics miniaturization:Sol-gel coating thickness control below 5 micrometers remains inconsistent for biomedical implant applications requiring sub-micron precision.
Strategic Opportunities
- Spanish aerospace thermal spray pivot:Underutilized automotive-dominant capacity in Spanish service centers rebalances toward aerospace-qualified production lines with lower qualification backlogs than German counterparts.
- Benelux equipment ecosystem leverage:PVD and CVD equipment infrastructure anchored in the Netherlands supports technology convergence with additive manufacturing repair workflows for turbine components.
- UK ceramic formulation IP commercialization:Technical center-developed oxide and carbide formulations face limited European competition for high-temperature silicate coatings in industrial furnace applications.
Industry Challenges
- Plasma spray operator skill scarcity:Torch parameter optimization for porosity control requires 5-7 year apprenticeship pipelines that European technical training institutions have deprioritized.
- Legacy chromium plating workforce transition:Electroplating technicians require 12-18 month reskilling programs to operate thermal spray robotics, creating labor friction during facility conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ceramic Coatings Market |
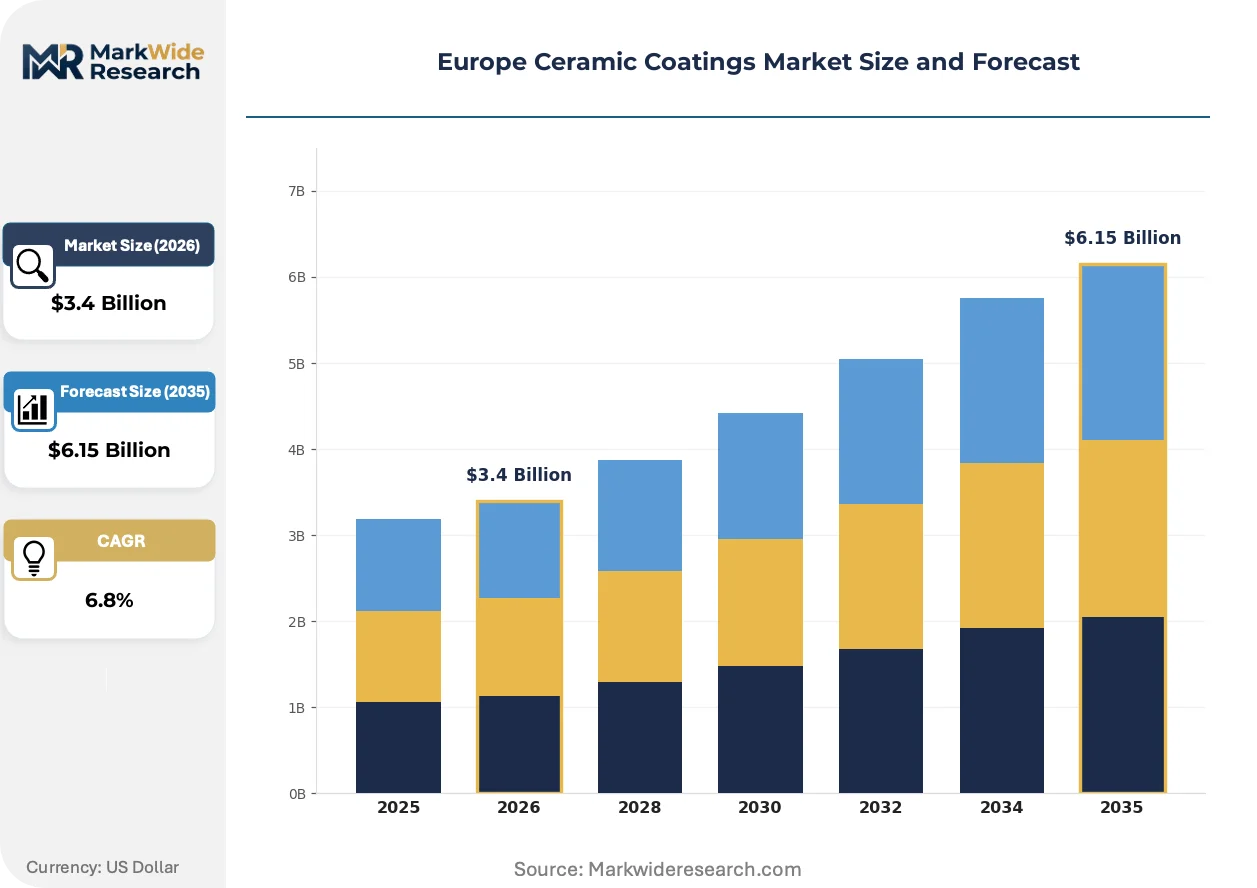
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Spray Coatings, Plasma Spray Coatings, Sol-Gel Coatings, Chemical Vapor Deposition Application: Aerospace, Automotive, Electronics, Biomedical End User: Manufacturing, Defense, Healthcare, Oil & Gas Technology: Airless Spray, Electrostatic Spray, Ultrasonic Spray, Dip Coating |
| Companies Covered | Zircotec Ltd., CemeCon AG, Bodycote plc, Aalberts Surface Technologies, Hauzer Techno Coating B.V., Morgan Advanced Materials plc, Hardide Coatings Ltd., Surface Technology International Ltd., Keronite Group Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ceramic Coatings Market Shifts & Advancements
Process automation and digital coating monitoring systems are compressing qualification timelines while regulatory chemistry restrictions force reformulation of established product lines.
Hybrid thermal spray-cold spray deposition is unifying wear resistance and dimensional restoration in single-pass operations. Aerospace MRO providers in France and Italy adopt these systems to eliminate multi-step stripping and re-coating sequences. The technology is unifying previously separate repair and protective coating workflows into consolidated service offerings.
REACH Annex XIV authorization requirements for chromium VI compounds now cover all automotive and aerospace surface treatment applications. Coating users must complete substitution assessments documenting technical and economic viability of ceramic alternatives. German tier-one suppliers face 2026 deadlines for chromium elimination in powertrain components, compressing validation schedules for qualified applicators.
Specification-driven procurement now favors coating service providers with EASA Part 145 certification and CE marking documentation under the EU Machinery Directive. French and Italian automotive OEMs consolidate vendor lists to three approved applicators per coating technology category. Benelux industrial equipment manufacturers lead this concentration, requiring integrated quality management systems as table stakes for contract eligibility.
Europe Ceramic Coatings Market Segmentation
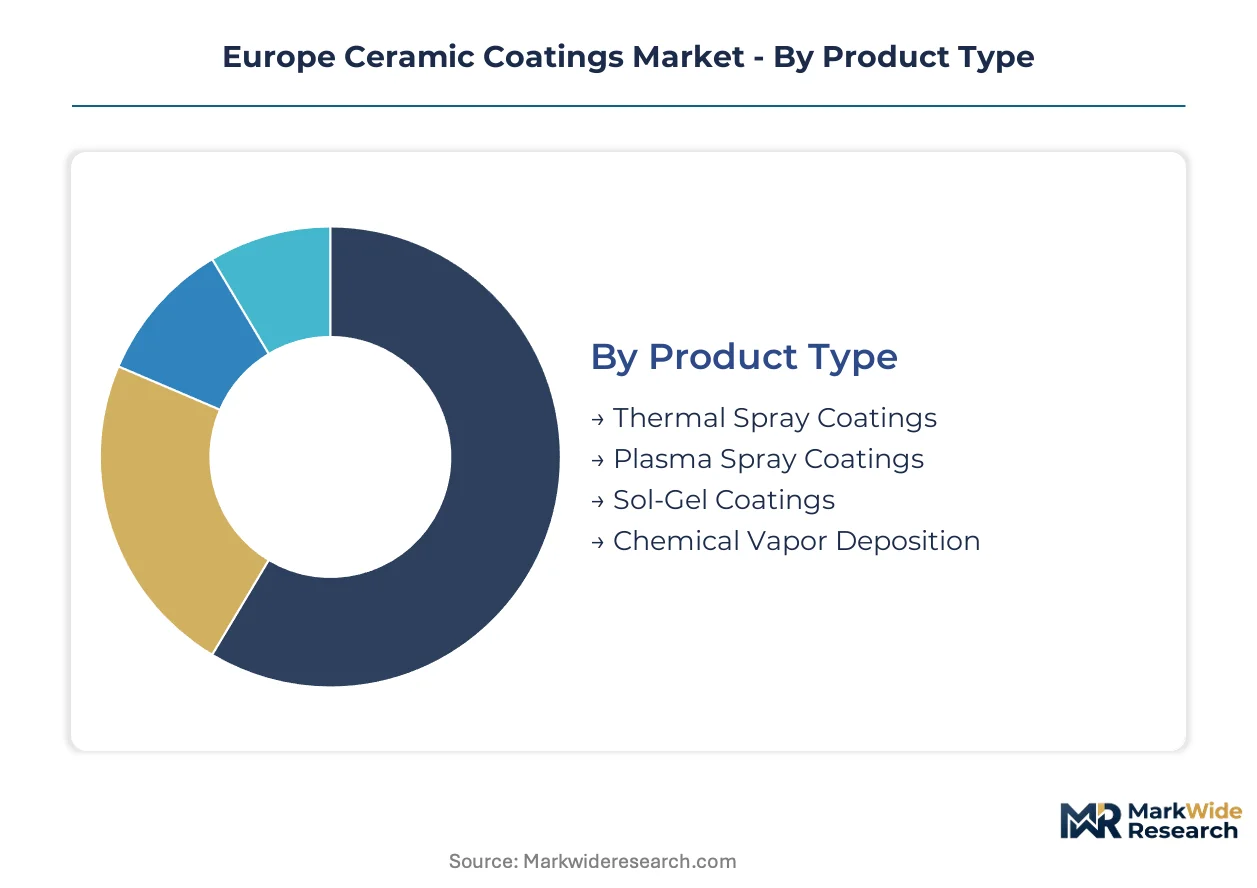
Procurement specifications for ceramic coatings diverge sharply across European regulated industries, with REACH compliance timelines and EASA airworthiness protocols forcing buyers to prioritize certified applicators over cost optimization. Specification-grade volumes concentrate where automotive and aerospace production clusters overlap with qualified thermal spray infrastructure.
Product Type:
Application temperature thresholds and porosity specifications drive buyer selection between deposition technologies.
- Thermal Spray Coatings:Oxide and carbide layers deposited at 3,000-15,000°C dominate European MRO infrastructure for industrial turbine refurbishment. German precision engineering clusters in Bavaria specify these coatings for wear-resistant machine tool components facing REACH-mandated chromium substitution.
- Plasma Spray Coatings:Sub-2% porosity specifications command premium positioning in aerospace blade applications where EASA airworthiness certification requires documented torch parameter traceability. French and Italian MRO providers consolidate procurement to Part 145-certified applicators with automated deposition cells.
- Sol-Gel Coatings:Low-temperature oxide formation suits electronics miniaturization and biomedical implant finishing where substrate thermal damage must be avoided.
- Chemical Vapor Deposition:Fluorinated precursor chemistries face F-Gas Regulation phase-down uncertainty that threatens process continuity for semiconductor equipment manufacturers.
Thermal spray coatings lead on scale across European maintenance infrastructure; sol-gel coatings lead on momentum in precision electronics and biomedical segments.
Application:
End-use certification requirements fragment procurement into specification tiers with divergent qualification timelines.
- Aerospace:EASA Part 145 certification and CE marking under the EU Machinery Directive restrict contract eligibility to applicators with 18-36 month qualification backlogs. Plasma spray deposition for turbine blade thermal barriers commands the highest specification premiums in the European market.
- Automotive:German OEM powertrain thermal management specifications are accelerating ceramic coating adoption as REACH Annex XIV deadlines eliminate hexavalent chromium plating alternatives by 2026.
- Electronics:Sol-gel thickness control below 5 micrometers remains inconsistent for sub-micron precision requirements in advanced semiconductor packaging.
- Biomedical:Implant surface finishing requires biocompatibility documentation under the EU Medical Device Regulation that extends validation cycles for coating applicators.
Aerospace leads on specification premium capture; automotive leads on volume acceleration from regulatory substitution mandates.
End User:
Capital intensity and regulatory exposure determine contract tenure and vendor consolidation patterns.
- Manufacturing:Industrial equipment producers in Benelux require integrated quality management systems as baseline eligibility for specification-grade coating procurement.
- Defense:National security classification protocols restrict coating technology transfer and limit qualified supplier pools for military turbine applications.
- Healthcare:EU MDR compliance documentation demands extend coating validation timelines for implant manufacturers beyond standard industrial schedules.
- Oil & Gas:Corrosion-resistant coating specifications for subsea infrastructure concentrate procurement with North Sea service providers holding offshore certification credentials.
Manufacturing leads on contract volume; healthcare leads on qualification barrier height and vendor consolidation.
Technology:
Automation compatibility and coating uniformity specifications separate production-scale from specialty applicators.
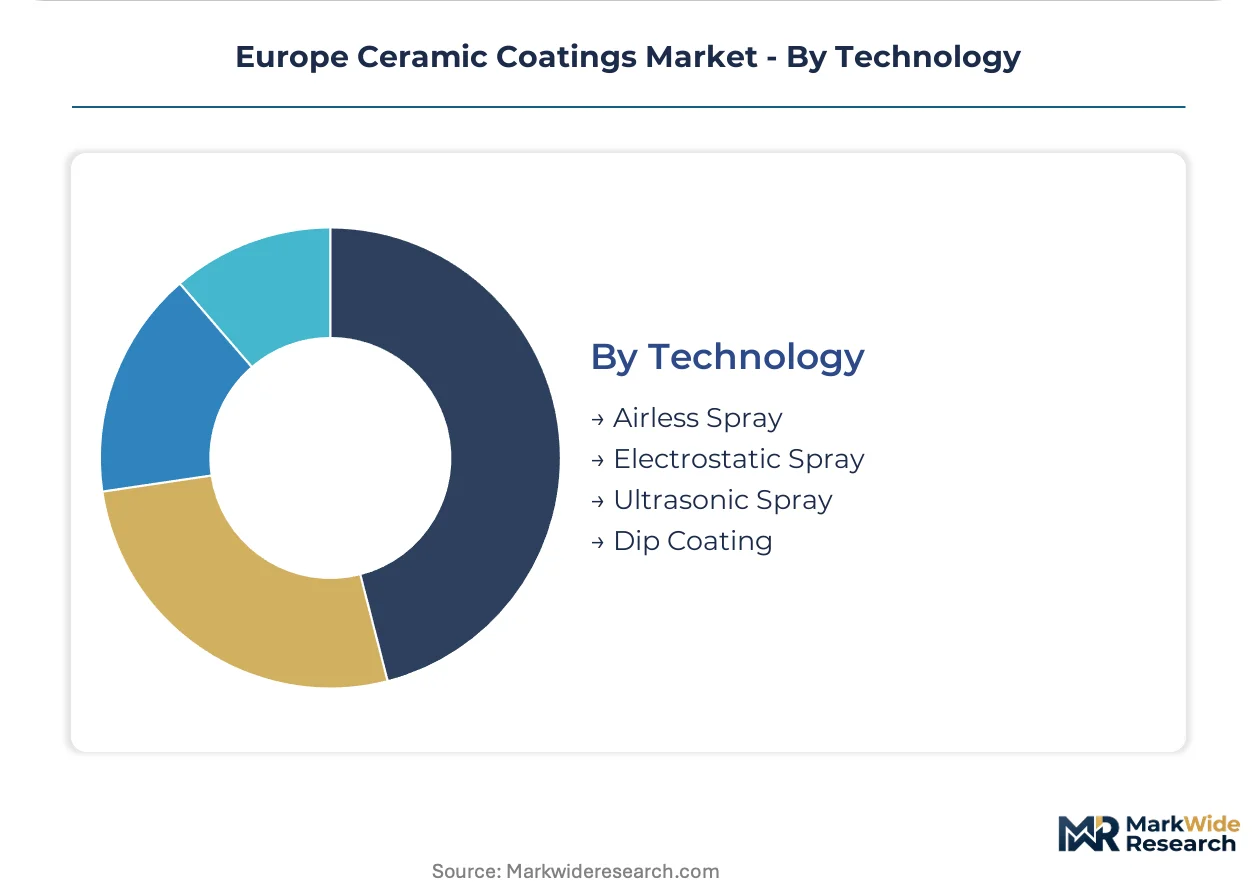
- Airless Spray:High-pressure hydraulic atomization delivers thick ceramic layers for heavy industrial wear protection where surface finish tolerance permits higher roughness.
- Electrostatic Spray:Charged particle deposition improves transfer efficiency and reduces overspray waste for automotive OEMs facing EU Green Deal emissions accounting requirements.
- Ultrasonic Spray:Low-velocity atomization enables sub-10 micrometer thickness control for electronics and biomedical precision finishing applications.
- Dip Coating:Submersion processes suit high-volume uniform coverage of complex geometries in industrial furnace component manufacturing.
Electrostatic spray leads on automotive OEM adoption; ultrasonic spray leads on precision miniaturization applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity migrates toward jurisdictions with streamlined ECHA registration pathways and established aerospace qualification infrastructure. REACH compliance cost differentials between member states reshape where coating applicators locate thermal spray facilities.
Germany
Bavaria and Baden-Württemberg host precision engineering clusters driving specification-grade procurement for automotive powertrain thermal barriers. KBA enforcement of REACH Annex XIV chromium elimination deadlines compresses validation schedules for tier-one suppliers. Stuttgart industrial corridor facilities convert electroplating lines to plasma spray cells under EU Green Deal emissions mandates.
United Kingdom
Morgan Advanced Materials plc anchors ceramic formulation development at its UK technical center, supplying oxide and carbide coatings for industrial furnace applications. CE marking under the EU Machinery Directive shapes export qualification protocols despite post-Brexit regulatory divergence. Midlands manufacturing belt concentrates aerospace MRO providers seeking EASA Part 145 certification for turbine blade refurbishment.
France
Aerospace blade thermal barrier coatings command premium positioning at Toulouse and Bordeaux maintenance hubs. ANSM oversight of biomedical implant surface finishing extends validation cycles beyond standard industrial schedules. Île-de-France industrial equipment manufacturers consolidate vendor lists to three approved applicators per technology category.
Spain
Thermal spray capacity rebalances from automotive-dominant utilization toward aerospace-qualified production lines. Spanish service centers exploit lower qualification backlogs than German counterparts to capture blade refurbishment contracts. Barcelona and Madrid industrial zones attract coating applicators seeking alternative to saturated Central European markets.
Netherlands
Hauzer Techno Coating B.V. anchors Benelux PVD and CVD equipment ecosystem supporting technology convergence with additive manufacturing repair workflows. Randstad manufacturing corridor requires integrated quality management systems as baseline procurement eligibility. Dutch technical universities feed operator apprenticeship pipelines scarce across neighboring jurisdictions.
Europe Ceramic Coatings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue aerospace qualification and REACH-compliant chromium substitution niches. The vendor base stratifies across pan-European service networks, regional equipment specialists, and formulation-focused material science firms. Three archetypes dominate: thermal spray facility operators, PVD/CVD equipment manufacturers, and ceramic powder formulators. Competitive moves concentrate on EASA certification acquisition and automated deposition cell deployment.
Within the pan-European service network tier, Bodycote plc and Aalberts Surface Technologies represent proximity-based relationship models with tier-one automotive and aerospace suppliers. Hauzer Techno Coating B.V. anchors equipment-centric positioning in the Benelux region. Morgan Advanced Materials plc exemplifies formulation intellectual property commercialization through technical center-developed oxide and carbide specifications.
| Leading Market Players |
|---|
| Zircotec Ltd. |
| CemeCon AG |
| Bodycote plc |
| Aalberts Surface Technologies |
| Hauzer Techno Coating B.V. |
| Morgan Advanced Materials plc |
| Hardide Coatings Ltd. |
| Surface Technology International Ltd. |
| Keronite Group Limited |
| Others |
Supply & Pricing Matrix
Plasma spray automation compressing qualification timelines simultaneously concentrates production economics among capital-intensive operators and eliminates price competition from manual deposition shops. REACH-driven chromium substitution accelerates volume migration toward certified applicators with EASA Part 145 documentation, amplifying their procurement leverage over tier-one automotive and aerospace buyers.
Pricing Analysis
Direct-to-OEM contract structures dominate specification-grade procurement, bypassing distributor markups that characterize commodity coating trade. Three-tier pricing structure across EASA-certified premium, CE-marked standard, and uncertified economy levels tracks certification investment amortization and torch parameter traceability documentation. Pricing pressure stems from Spanish service centers undercutting German qualification backlogs on aerospace blade refurbishment contracts. Automotive OEM procurement teams exhibit highest price sensitivity, while aerospace MRO buyers prioritize airworthiness documentation over unit cost optimization.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Toulouse, and Barcelona coordinate hub-and-spoke patterns for ceramic powder feedstock and qualified applicator capacity. Supply concentration rests on Germany, France, and Spain for thermal spray infrastructure, with Benelux anchoring PVD and CVD equipment manufacturing. Yttria-stabilized zirconia powders, aluminum oxide precursors, and tungsten carbide feedstocks draw from specialized European chemical suppliers with limited alternative sourcing. Single-source vulnerability concentrates in fluorinated precursor chemistries facing F-Gas Regulation phase-down schedules. Distribution runs through pan-European service networks with proximity-based tier-one relationships rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on REACH compliance cost pass-through to automotive buyers and premium-tier positioning in aerospace blade refurbishment where EASA certification scarcity sustains pricing power.
For Market Incumbents: Anticipate consolidation pressure from pan-European service networks acquiring regional thermal spray operators to capture chromium substitution volumes. Defensive positioning demands EASA Part 145 certification investment and automated deposition cell deployment in Bavaria and Baden-Württemberg industrial corridors. Vertical integration into ceramic powder formulation secures supply security against fluorinated precursor disruption. For New Entrants and Emerging Players: REACH Annex XIV in Germany opens a window for mid-scale applicators with streamlined ECHA registration pathways to capture tier-two automotive powertrain contracts abandoned by electroplating shops. Spanish aerospace thermal spray capacity rebalancing presents the most penetrable geography given lower qualification backlogs than Central European counterparts. Sol-gel coating specialization for biomedical implant surface finishing offers differentiation through EU MDR compliance documentation capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among equipment-centric PVD and CVD manufacturers in Benelux lacking service revenue streams. Long-term viability over the next decade favors formulation-focused material science firms with technical center-developed intellectual property and captive aerospace qualification pipelines. Monitor EASA airworthiness directive revision timelines as inflection indicators for premium-tier coating demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Part 145 Certification Acquisition | Airworthiness documentation unlocks aerospace blade refurbishment contracts at Toulouse and Bordeaux maintenance hubs. |
| Automated Deposition Cell Deployment | Robotic plasma spray systems compress torch parameter optimization cycles and reduce operator skill dependency. |
| Backward Integration into Ceramic Powder Formulation | In-house oxide and carbide development secures supply continuity against fluorinated precursor regulatory phase-down. |
| Spanish Aerospace Capacity Rebalancing | Underutilized automotive-dominant thermal spray infrastructure pivots toward lower-backlog aerospace qualification pipelines. |
| Sol-Gel Biomedical Specialization | EU MDR compliance documentation capabilities capture implant surface finishing contracts with extended validation barriers. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with thermal spray facility operators, EASA certification auditors, automotive OEM procurement directors, and ceramic powder formulators cross-validated secondary sources including ECHA registration databases, EASA airworthiness directives, EU Green Deal implementation reports, and customs trade data for yttria-stabilized zirconia and aluminum oxide feedstocks.
Historical trendline analysis of specification-grade coating volumes across German automotive production schedules and European aerospace MRO activity established baseline growth patterns. Segmentation modeling incorporated deposition technology, application certification tier, end-use industry, and regional production cluster dimensions. CAGRs derived from installed base expansion rates, REACH compliance deadline impacts, and aerospace fleet refurbishment cycle projections without explicit year anchoring.
Revisions become necessary when F-Gas Regulation phase-down schedules accelerate, EASA airworthiness protocols extend qualification timelines, or automotive OEM chromium elimination deadlines shift. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and certification backlog accumulation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Nano Ceramic Coatings Market
Ceramics
Thailand Ceramic Tiles Market
Ceramics
Global Alumina Trihydrate Market
Ceramics
Calcined Bauxite Market
Ceramics
Brazil Ceramic Tiles Market
Ceramics
North America Ceramic Coatings Market
Ceramics
Relaxor Ferroelectric Ceramics Market
Ceramics
Fly Ash and Ceramic Microsphere Market
Ceramics
Medical Ceramics Market
Ceramics
Technical Ceramics Market
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
Diatomite Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Ceramic Setter Plate Market
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
Carbon-Ceramic Discs Market