
 Calcined Bauxite Market | 2026-2036
Calcined Bauxite Market Size, Share, and Industry Trends Forecast 2026-2036
Calcined Bauxite Market Intelligence
Refractory service contracts and technical support revenue is rewriting profit allocation across the calcined bauxite value chain. Bosai Minerals Group leverages captive bauxite mining in Guizhou to control feedstock quality and cost. LKAB Minerals sustains Nordic supply reliability through vertically integrated logistics. Great Lakes Minerals anchors North American availability with Great Lakes port access and regional blending operations.
Calcined bauxite consists of bauxite ore thermally treated at 1,600–1,800°C to drive off combined water, yielding a dense, high-alumina aggregate with Mohs hardness above 8.5 and primary use in shaped and monolithic refractories for blast furnaces, ladles, and cement kilns. High alumina product types command premium positioning where thermal shock resistance and corrosion endurance justify unit cost. Refractory applications dominate volume absorption, while specialty calcined bauxite for proppants and precision abrasives captures faster expansion. Steelmaking end-use pulls disproportionate tonnage as electric arc furnace and direct reduced iron capacity expands.
China's MEE enforces GB standards on particulate emissions from rotary kiln calcination, forcing facility upgrades or closures. REACH in Europe and OSHA silica exposure limits in the US constrain product qualification and workplace handling protocols. Stakeholders must monitor regulatory divergence between emission-control jurisdictions and refractory performance standards to align capital deployment with compliant supply sources.
Market Dynamics
China's dual carbon goals and GB standards on industrial emissions are compressing calcination capacity while tightening furnace lining specifications in steelmaking pull premium-grade material. Procurement criteria now weight carbon intensity alongside alumina content, restructuring supplier qualification hierarchies.
Growth Catalysts
- Steelmaking furnace upgrades:Electric arc furnace and direct reduced iron capacity expansion drives disproportionate tonnage absorption for high-alumina refractory linings.
- REACH compliance in Europe:Product qualification protocols favor certified low-silica calcined bauxite, creating preference premiums for compliant supply sources.
- Rotary kiln emission controls:China's MEE enforcement of GB particulate standards accelerates facility consolidation, concentrating viable output among upgraded producers.
Market Restraints
- Natural gas price volatility:Thermal treatment at 1,600–1,800°C ties production economics to energy input costs, compressing margins during price spikes.
- Feedstock concentration in Shanxi:Bauxite ore procurement depends on a single province cluster, exposing supply chains to localized disruption or quality variance.
- Fused alumina substitution:Synthetic alternatives compete in precision abrasive applications where thermal shock resistance requirements moderate.
Strategic Opportunities
- Proppant specialty grades:Oilfield service demand for high-strength hydraulic fracturing media opens faster-expansion segments outside refractory saturation.
- Nordic logistics integration:Vertically controlled port-to-plant networks in Scandinavia enable premium positioning for European buyers seeking supply reliability.
- Precision abrasive convergence:Bonded grinding wheel manufacturers combine calcined bauxite with engineered ceramic grains for next-generation cutting tools.
Industry Challenges
- Rotary kiln technician scarcity:Specialized furnace operation and temperature control expertise limits facility restart and upgrade execution timelines.
- Multi-jurisdiction certification lag:Simultaneous OSHA silica exposure documentation and REACH dossier preparation extends product qualification cycles.
- Legacy refractory integration:Monolithic lining formulations require extensive compatibility testing before calcined bauxite grade substitution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcined Bauxite Market |
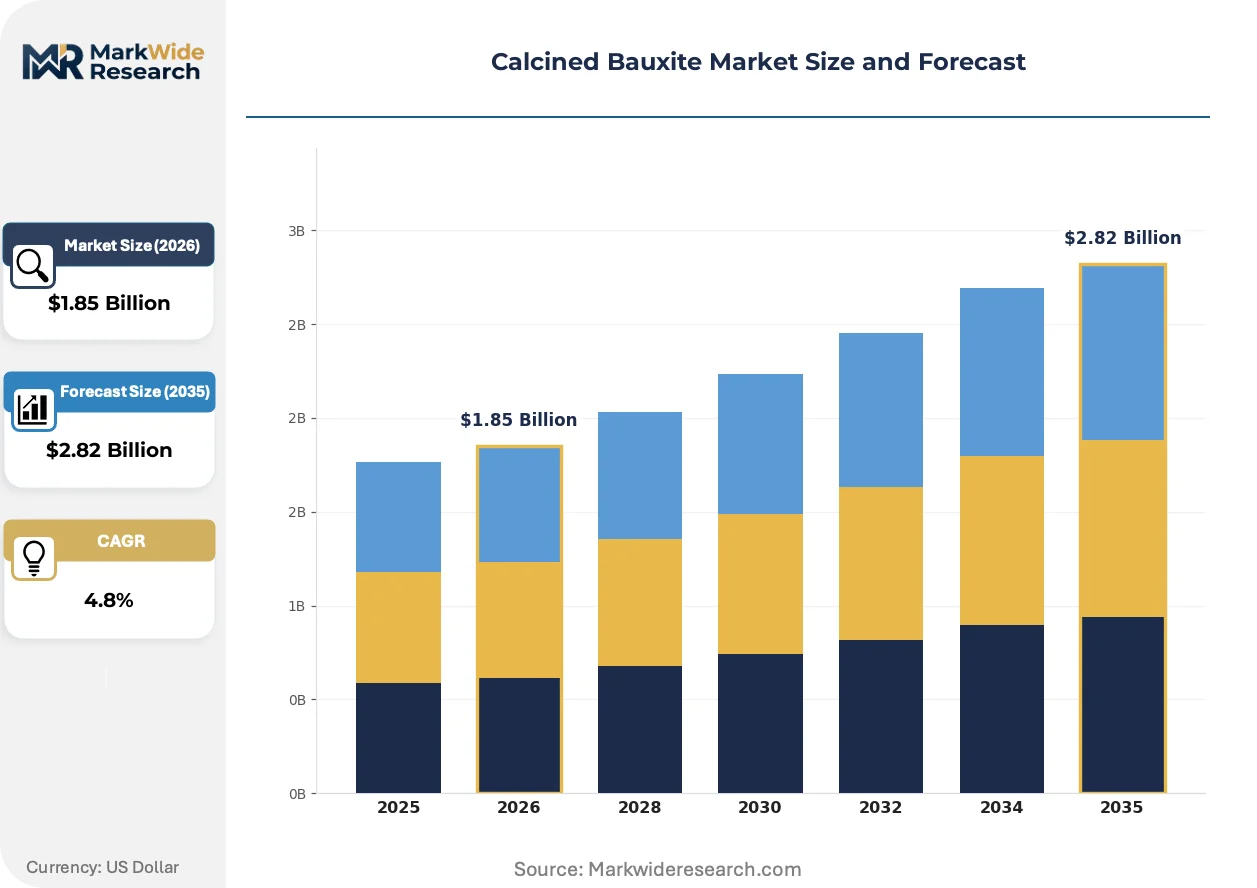
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Alumina, High Alumina, Medium Alumina, Specialty Calcined Bauxite Application: Refractory, Abrasives, Cement, Steelmaking Grade: Industrial Grade, Chemical Grade, Metallurgical Grade, Other Grades Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Alchemy Mineral LLC, EK-COMPANY AG, Bosai Minerals Group, Great Lakes Minerals LLC, Boud Minerals Limited, First Bauxite LLC, LKAB Minerals, Artha Mineral Resources, Sinocean Industrial Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcined Bauxite Market Strategic Shifts & Innovations
Kiln control systems and supply chain traceability platforms are digitizing production economics and procurement verification. Material science advances in synthetic aggregate blending reshape performance benchmarks.
Sensor-integrated rotary kiln monitoring is digitizing temperature profiling and fuel efficiency optimization. Steelmakers and refractory installers adopt these systems to document thermal consistency for furnace lining warranties. Real-time data streams compress quality variance and enable predictive maintenance scheduling.
REACH authorization requirements for crystalline silica content are tightening workplace exposure documentation across European refractory fabrication. Downstream processors must demonstrate compliant handling protocols to maintain market access. High-alumina low-silica calcined bauxite grades command sourcing priority as substitution hedges.
Service unbundling separates technical support contracts from material supply agreements in steelmaker procurement. Refractory installers now bid performance-based lining life guarantees independently of aggregate sourcing. This pattern concentrates most visibly in German and Japanese blast furnace maintenance markets where operational uptime penalties structure contract terms.
Calcined Bauxite Market Segmentation
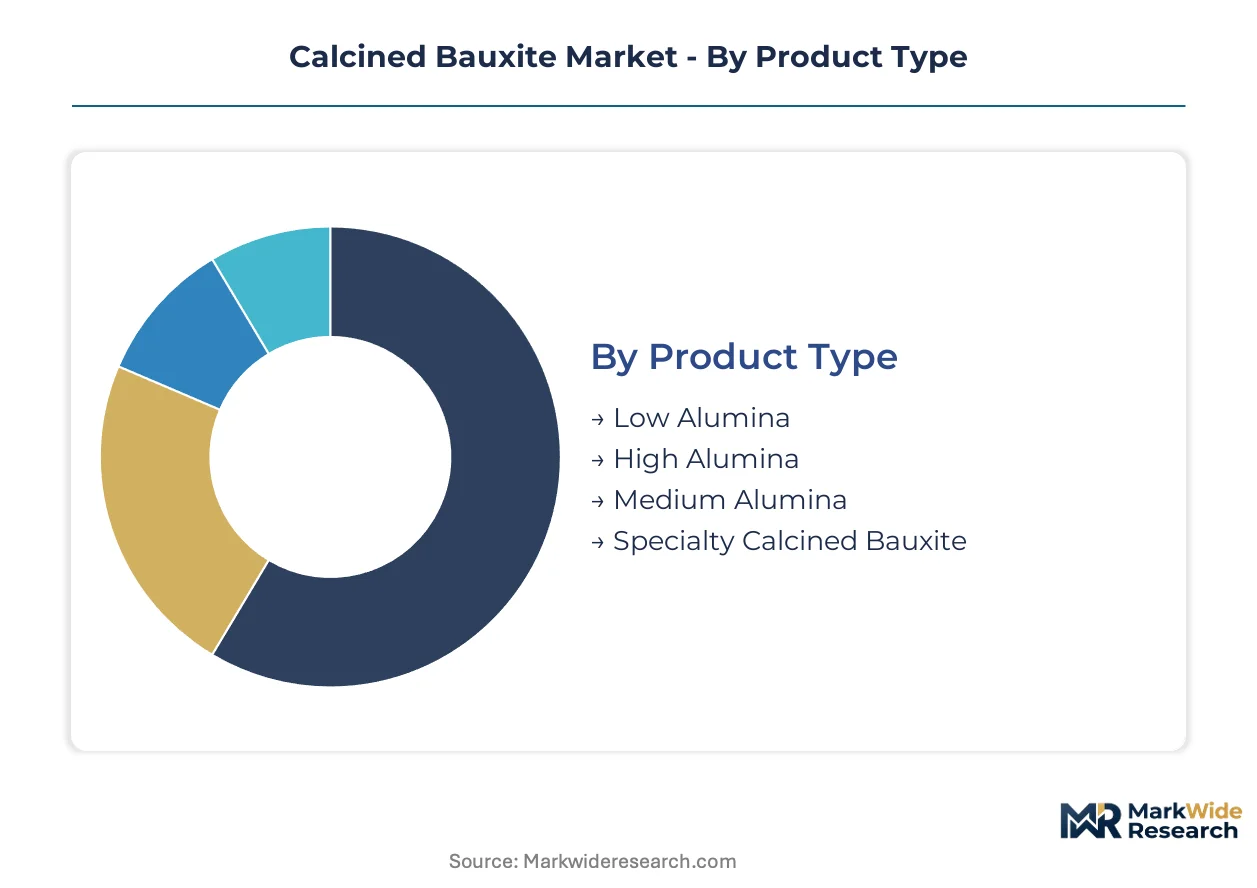
Calcined bauxite procurement decisions hinge on alumina content thresholds, thermal performance specifications, and end-use compliance requirements. Segment boundaries shift as steelmakers tighten furnace lining standards and oilfield operators demand higher-strength proppant media.
Product Type:
Mature refractory grades dominate current tonnage while emerging specialty formulations capture premium positioning in hydraulic fracturing and precision grinding applications.
- High Alumina:Thermally treated ore exceeding 85% alumina content delivers dense aggregates with Mohs hardness above 8.5. Blast furnace and ladle lining specifications in Germany and Japan concentrate demand here, with procurement teams prioritizing thermal shock resistance over unit cost.
- Specialty Calcined Bauxite:Engineered grain shapes and controlled porosity serve oilfield proppant and bonded abrasive manufacturers. North American shale operators and Scandinavian precision tool producers drive fastest uptake as performance warranties extend to downhole pressure endurance.
- Medium Alumina:Standard refractory aggregate for cement kiln preheater zones and secondary steelmaking vessels.
- Low Alumina:Cost-optimized filler grades for construction materials and non-critical industrial applications.
High alumina retains volume leadership; specialty calcined bauxite holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity refractory absorption from premium-grade precision manufacturing inputs.
- Refractory:Shaped bricks and monolithic linings for blast furnaces, ladles, and cement kilns constitute the foundational demand base. Chinese steelmakers in the Yangtze River Delta and German blast furnace maintenance contractors specify exacting alumina content ranges.
- Steelmaking:Direct reduced iron and electric arc furnace capacity expansion disproportionately pulls high-purity grades. Furnace lining life guarantees now tie aggregate sourcing to operational uptime penalties.
- Abrasives:Bonded grinding wheels and precision cutting tools blend calcined bauxite with engineered ceramic grains.
- Cement:Kiln preheater and clinker cooler linings absorb medium-alumina tonnage at specification levels below steelmaking thresholds.
Refractory commands absolute tonnage; steelmaking application climbs fastest as EAF retrofit cycles accelerate.
Grade:
Customer type differentiation splits procurement between industrial volume buyers and specification-driven chemical processors.
- Industrial Grade:Standardized refractory aggregate meeting basic thermal and mechanical thresholds for furnace construction and repair. Chinese GB standards and OSHA silica exposure documentation now filter supplier qualification.
- Metallurgical Grade:Ultra-low impurity specifications for aluminum smelting flux and specialized steel refining applications.
- Chemical Grade:Controlled reactivity and trace element limits for specialty ceramic and catalyst support manufacturing.
- Other Grades:Niche formulations for research, prototype development, and custom blending operations.
Industrial grade maintains procurement volume dominance; metallurgical grade expands most quickly as aluminum purity standards tighten.
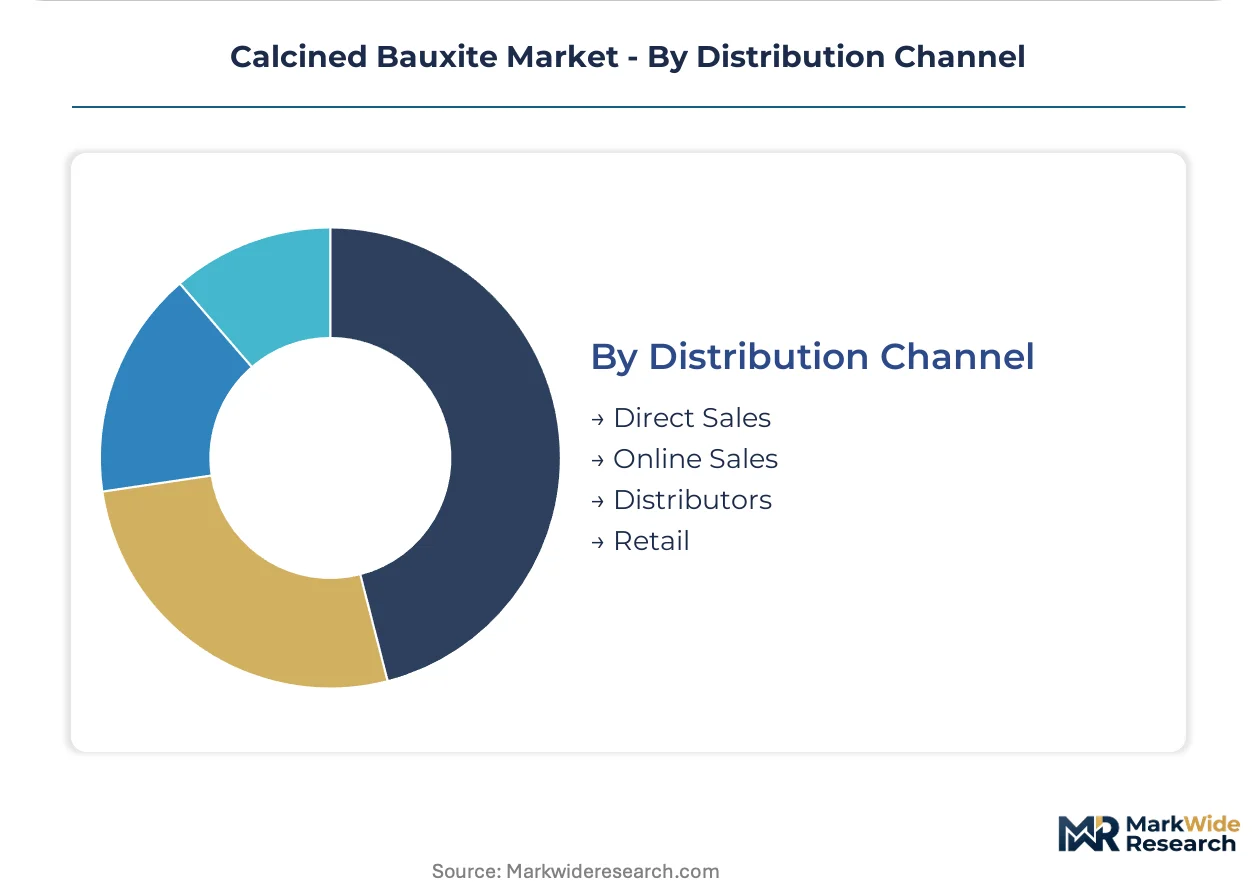
Distribution Channel:
Supply concentration patterns favor direct relationships for bulk refractory consumers while fragmented regional markets sustain distributor networks.
- Direct Sales:Long-term supply agreements link calcination facilities to steelmakers and refractory manufacturers. Technical support contracts and performance warranties increasingly unbundle from material pricing.
- Distributors:Regional inventory positioning serves mid-size refractory installers and maintenance contractors across Europe and North America.
- Online Sales:Digital procurement platforms emerge for standardized grade spot purchasing and sample qualification.
- Retail:Limited presence for small-volume construction and hobbyist abrasive applications.
Direct sales anchor volume throughput; distributor channels gain share where regional blending operations add value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes calcined bauxite primarily for steel refractories, while Germany and the United States diverge toward precision abrasive and proppant applications. This consumption-mix differential shapes regional procurement priorities and regulatory compliance investments.
China
Steelmaking furnace upgrades in the Yangtze River Delta and Shanxi province drive disproportionate tonnage absorption for high-alumina refractory linings. The MEE enforces GB standards on particulate emissions from rotary kiln calcination, forcing facility consolidation. Shanxi province hosts the dominant bauxite calcination cluster, where capacity has concentrated among upgraded producers meeting dual carbon goals.
Germany
Blast furnace maintenance contractors specify exacting alumina content ranges for shaped refractory bricks and monolithic linings. REACH authorization requirements for crystalline silica content tighten workplace exposure documentation across refractory fabrication. The Ruhr industrial region anchors European demand, where steelmakers tie aggregate sourcing to operational uptime penalties in performance-based contracts.
United States
North American shale operators pull specialty calcined bauxite grades for high-strength hydraulic fracturing proppants. OSHA silica exposure limits constrain product qualification and workplace handling protocols. Great Lakes port access enables regional blending operations that anchor supply reliability for Midwest refractory manufacturers.
India
Cement kiln preheater and clinker cooler linings absorb medium-alumina tonnage as infrastructure construction sustains clinker production. BIS standards filter industrial mineral imports for quality consistency. Gujarat and Maharashtra host the dominant refractory manufacturing clusters, where domestic calcination capacity serves both local steelmakers and export markets.
Brazil
Aluminum smelting flux applications drive metallurgical-grade procurement as primary aluminum purity standards tighten. ANVISA and environmental licensing requirements govern mining and processing operations. The Minas Gerais mining corridor concentrates bauxite ore extraction, feeding calcination facilities serving South American refractory and metallurgical markets.
Calcined Bauxite Market Key Industry Players
Capability concentration sits with specialized refractory-grade producers; scale advantage sits with diversified mining conglomerates. The market structures around three tiers: captive bauxite miners with in-house calcination, independent calciners sourcing ore on contract, and regional blenders adding logistics value. Strategic moves center on backward integration into ore supply and unbundling technical service contracts from material pricing.
Within the captive-mining tier, Bosai Minerals Group and Great Lakes Minerals exemplify archetypes of feedstock control. LKAB Minerals anchors Nordic supply reliability through vertically integrated logistics. Chinese producers including Sinocean Industrial Limited occupy positions serving domestic steel refractory demand. These company patterns illustrate how geographic ore access and port infrastructure shape competitive positioning without requiring specific operational claims.
| Leading Market Players |
|---|
| Alchemy Mineral LLC |
| EK-COMPANY AG |
| Bosai Minerals Group |
| Great Lakes Minerals LLC |
| Boud Minerals Limited |
| First Bauxite LLC |
| LKAB Minerals |
| Artha Mineral Resources |
| Sinocean Industrial Limited |
| Others |
Cost & Logistics Intelligence
Feedstock concentration in Shanxi province creates a single-source chokepoint that simultaneously widens pricing spreads between premium and standard grades and forces supply chain redesign toward multi-origin sourcing. Natural gas price volatility at calcination facilities amplifies this dynamic, compressing margins for non-integrated operators while rewarding those with captive bauxite mining and long-term fuel contracts.
Pricing Analysis
Long-term offtake agreements anchor volume pricing for steelmakers and refractory manufacturers, while spot markets handle emergency replenishment and qualification samples. Three-tier pricing structure across premium, standard, and economy levels reflects alumina content thresholds and REACH compliance certification. Pricing pressure stems from rotary kiln emission upgrade costs passed through by Chinese producers. Cement kiln operators exhibit highest price sensitivity; German blast furnace maintenance contractors prioritize thermal performance guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from steelmakers are reshaping supplier financing, forcing calciners to secure supply-chain finance facilities or accept working capital strain. Raw material sourcing draws from Shanxi province in China, Minas Gerais in Brazil, and Gujarat in India. Bauxite ore quality variance, refractory-grade specifications, and natural gas supply contracts constitute critical input dependencies. Tariff exposure on Chinese calcined bauxite into Europe and North America presents structural risk. Distribution runs through direct sales for bulk consumers and regional distributors for mid-size refractory installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated steelmakers and multinational refractory conglomerates, compressing supplier margins and restructuring procurement toward performance-based contracts with operational uptime penalties.
For Market Incumbents: Entrench feedstock security through backward integration into Guizhou or Minas Gerais bauxite mining, or through exclusive offtake agreements with Shanxi ore processors. Invest in rotary kiln emission control systems ahead of MEE enforcement waves to capture stranded competitor volume. Fused alumina substitution in precision abrasives represents the most acute technology threat requiring grade differentiation response. For New Entrants and Emerging Players: Specialty proppant grades for North American shale operators represent the most penetrable entry point, bypassing refractory market saturation and incumbent supply relationships. Nordic logistics corridors serving German precision tool manufacturers offer second-mover positioning where vertically integrated port networks are absent. A technical service unbundling strategy—selling furnace lining expertise separate from aggregate supply—opens procurement doors at Japanese and German steelmakers. For Investors and Strategic Acquirers: China's dual carbon goals and GB emission standard enforcement reshape the acquisition landscape, elevating calcination facilities with completed upgrades and MEE compliance documentation. Target calciners with demonstrated rotary kiln technician retention and sensor-integrated process control systems. The signal to watch is consolidation velocity among Shanxi province operators as closure deadlines approach.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Mining | Captive Guizhou or Minas Gerais ore supply insulates margin from Shanxi price volatility. |
| Rotary Kiln Emission Upgrade | MEE GB standard compliance secures operating license and concentrates viable output. |
| Technical Service Unbundling | Performance-based lining life guarantees separate revenue from commodity aggregate pricing. |
| Specialty Proppant Grade Development | Oilfield service demand in North American shale basins opens faster-expansion segments. |
| Nordic Logistics Integration | Vertically controlled port-to-plant networks enable premium positioning for European buyers. |
Research Approach
The analysis maps refractory-grade, proppant-grade, and abrasive-grade calcined bauxite segments, each validated through refractory plant managers, steelmaker procurement leads, rotary kiln operations directors, and oilfield service supply chain specialists. Primary interview findings triangulate against Chinese customs export data, EU REACH registration databases, SEC filings from diversified mining conglomerates, and MEE environmental compliance disclosures. Bottom-up volume estimates from calcination facility capacity and utilization rates reconcile with top-down steel refractory consumption models.
Fixed assumptions across the analysis window include sustained EAF capacity expansion in steelmaking, continued MEE enforcement of GB particulate standards, and stable alumina content thresholds in blast furnace lining specifications. The forecast framework varies natural gas price scenarios, bauxite ore quality variance, and REACH authorization timelines for crystalline silica content. Segmentation dimensions modeled encompass alumina content tier, end-use application, grade specification, and regional production hub. CAGRs derive from regression analysis against steel production forecasts and refractory consumption intensity ratios.
Macroeconomic conditions sit as an overlay; deviation in Chinese steel output, European industrial energy costs, or North American shale drilling activity would shift the trajectory. Forecasts reflect documented assumptions; regulatory enforcement intensity, synthetic aggregate substitution rates, or calcination technology breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Advanced Ceramics Market
Ceramics
Global Ceramic Coating Market
Ceramics
Refractories Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
Global Industrial Clay Market
Ceramics
Global Magnesium Silicate Market
Ceramics
Medical Ceramics Market
Ceramics
Zirconia Ceramics Market
Ceramics
Dielectric Ceramics Market
Ceramics
Traditional Ceramic Market
Ceramics
Vaterite Market
Ceramics
Industrial Ceramics Market
Ceramics
Heat-Resistant Ceramic Tableware Market
Ceramics
South Korea Ceramic Tiles Market
Ceramics
Ceramic Pigments Market