
 Nano Ceramic Coatings Market | 2026-2036
Nano Ceramic Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Ceramic Coatings Market Analytics
East Asian chemical producers is recalibrating sol-gel precursor output to match automotive and electronics pull. PPG Industries leverages its automotive OEM relationships to sustain premium liquid coating formulations across North American assembly plants. AkzoNobel anchors marine and industrial protective lines through controlled supply of powder-grade nano-ceramic systems. Cerakote specializes in thermal barrier formulations for firearms and aerospace components, occupying a defensible niche against commodity competitors.
Nano ceramic coatings constitute thin-film surface treatments, typically 1–10 microns thick, composed of nanoscale metal oxide particles—silica, alumina, titania—dispersed in ceramic matrices via sol-gel or vapor deposition processes. These coatings impart hardness ratings exceeding 9H pencil scale, chemical resistance, and hydrophobicity to substrates ranging from painted automotive panels to turbine blades. Liquid coatings dominate volume through ease of application in automotive refinish and consumer detailing channels, while thermal barrier coatings command premium positioning in aerospace turbine applications where CVD and PVD deposition methods enable precise thickness control. Spray coatings represent the fastest-growing format as industrial equipment manufacturers adopt robotic application systems for complex geometries.
EPA VOC regulations in the United States restrict solvent-borne formulation chemistries, compelling shifts toward waterborne nano-dispersions. REACH and the EU F-Gas Regulation in Europe impose substance restrictions and fluoropolymer phase-downs that reshape raw material sourcing for hydrophobic topcoats. China's GB standards and MEE environmental compliance frameworks enforce emission controls on coating production facilities. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized formulation platforms or regional product variants offer superior compliance economics.
Market Dynamics
Sol-gel manufacturing scale-up in automotive and electronics supply chains is compressing formulation costs while fragmenting supplier tiers between commodity precursors and application-specific integrated systems.
Growth Catalysts
- Automotive OEM clear coat mandates:Scratch-resistant nano-silica topcoats penetrate assembly lines as manufacturers seek 9H+ hardness ratings without solvent-borne environmental penalties.
- REACH fluoropolymer phase-downs:EU F-Gas Regulation restrictions on hydrophobic chemistries accelerate waterborne nano-dispersion R&D across protective coating portfolios.
- China MIIT advanced manufacturing policy:Domestic sol-gel capacity expansion aligns with NMPA industrial coating standards, reducing import dependency for high-purity alumina precursors.
Market Restraints
- Tetraethyl orthosilicate volatility:Petrochemical feedstock price swings compress margin predictability for sol-gel coating producers locked into annual supply agreements.
- German KBA automotive certification timelines:Extended type-approval processes for new coating chemistries delay commercialization by 18-24 months in European passenger vehicle segments.
- Physical vapor deposition capital intensity:CVD/PVD equipment thresholds exclude mid-scale applicators from aerospace thermal barrier contract bidding.
Strategic Opportunities
- India PLI scheme alignment:Electronics manufacturing incentive structures attract nano-ceramic coating investments for smartphone and semiconductor fabrication equipment protection.
- Robotic spray system integration:Industrial equipment manufacturers adopt automated application for complex turbine geometries, opening service-contract revenue streams.
- Japan METI carbon neutrality roadmap:Dual carbon goals drive public infrastructure spending on low-VOC bridge and tunnel protective coatings.
Industry Challenges
- Sol-gel chemistry PhD scarcity:Formulation science talent pipelines fail to match demand from expanding coating application centers in East Asian manufacturing clusters.
- ISO 16474 weathering certification delays:Accelerated UV and salt-spray testing backlogs extend product qualification cycles for marine coating launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Ceramic Coatings Market |
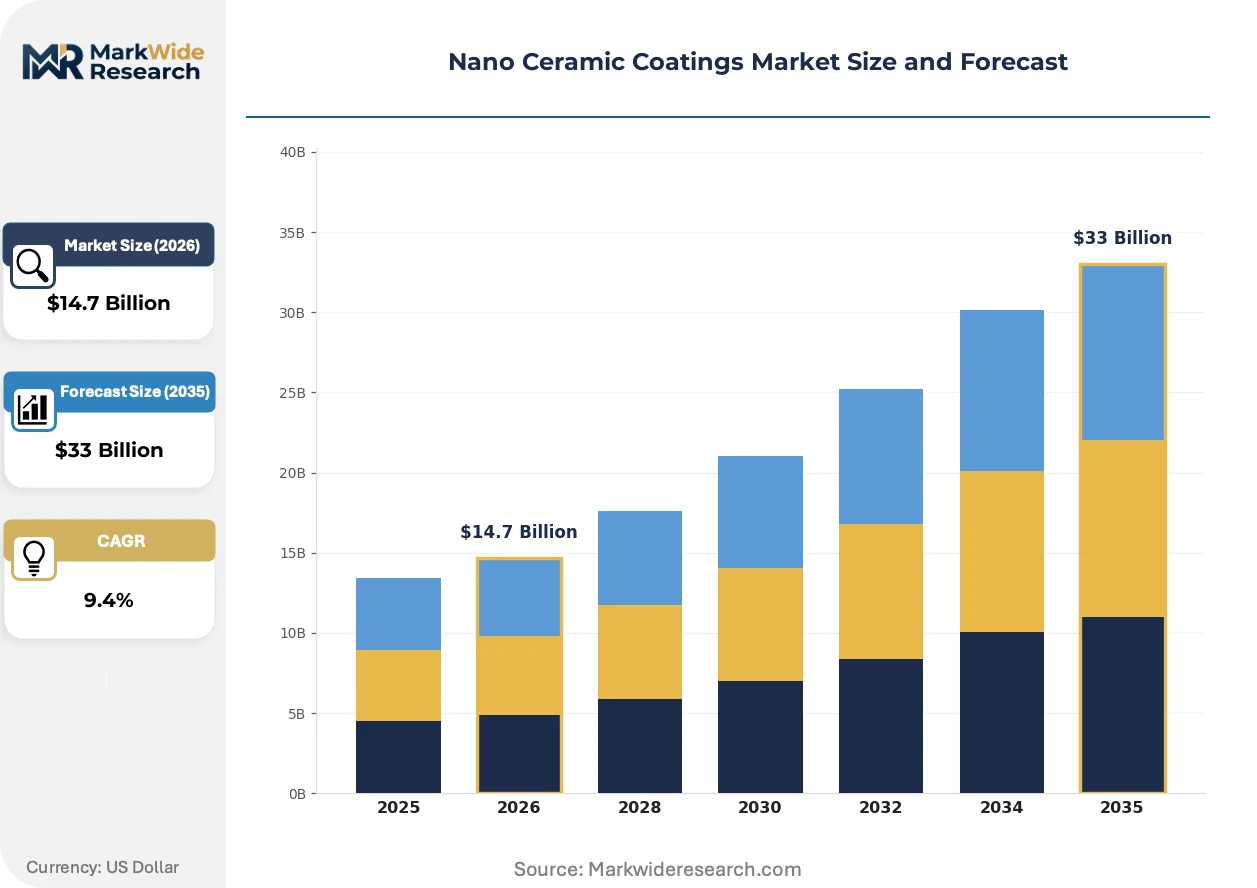
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $33 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Coatings, Spray Coatings, Paste Coatings, Powder Coatings End User: Automotive, Aerospace, Electronics, Industrial Equipment Application: Protective Coatings, Aesthetic Coatings, Functional Coatings, Thermal Barrier Coatings Technology: Sol-Gel Process, CVD, PVD, Hydrothermal Method |
| Companies Covered | PPG Industries, Sherwin-Williams, AkzoNobel, 3M, Nanovere Technologies, Cerakote, Henkel, HMG Coatings, IHI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Ceramic Coatings Market Evolving Landscape
Application technology automation and regulatory chemistry restrictions are compressing the viable formulation space while elevating performance thresholds for commercial success.
Spray-deposited nano-silica systems is consolidating application control across automotive refinish and industrial protective segments. Tier-one suppliers adopt robotic spray platforms to achieve sub-5-micron thickness uniformity on complex geometries. This precision is consolidating quality differentiation between integrated coating-applicator systems and standalone chemical suppliers.
EPA VOC emission thresholds in the United States are tightening solvent-borne formulation allowances. Coating manufacturers reformulate toward waterborne nano-dispersions with equivalent hardness properties. Automotive refinish shops in California and Texas face the steepest compliance costs, accelerating consolidation toward certified application networks.
Buyer procurement patterns favor bundled coating-plus-application service contracts over standalone chemical supply. Industrial maintenance divisions at power generation and marine operators source performance-guaranteed surface protection rather than volume-based precursor purchases. This behavioral shift is most pronounced in German and Japanese manufacturing equipment markets where total-cost-of-ownership frameworks dominate supplier selection.
Nano Ceramic Coatings Market Segmentation
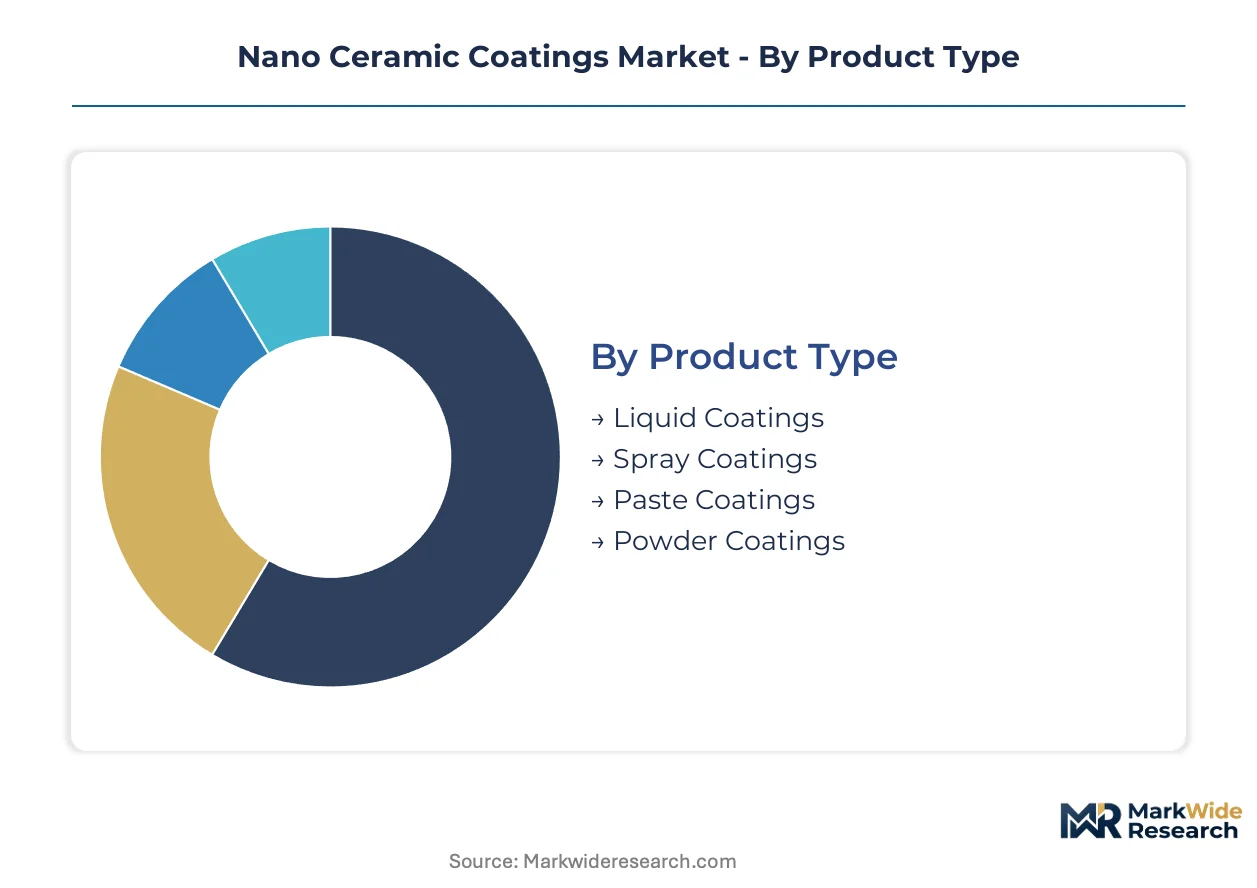
Nano ceramic coatings fragment across application methods, substrate requirements, and deposition technologies. Each axis carries distinct margin profiles and regulatory exposure that shape supplier positioning.
Product Type:
Technical sophistication and application control separate formats across automotive assembly and industrial maintenance channels.
- Liquid Coatings:Sol-gel nano-silica dispersions in solvent or waterborne carriers enable brush, dip, or spray application at 1–5 micron thickness. Automotive OEM clear coats in Germany and the United States concentrate demand here, driven by KBA and EPA compliance timelines for low-VOC formulations.
- Spray Coatings:Robotic application systems achieve sub-5-micron uniformity on complex turbine geometries. Industrial equipment manufacturers in Japan adopt this format fastest, aligning with METI carbon neutrality procurement for bridge and tunnel infrastructure.
- Paste Coatings:High-viscosity formulations for manual application in consumer detailing and marine touch-up segments.
- Powder Coatings:Electrostatic deposition of nano-ceramic particles for industrial protective lines requiring thick-film durability.
Mature deployment sits with liquid coatings. Newer deployment is concentrated in spray coatings.
End User:
Performance thresholds and certification rigor create tiered demand structures across mobility and electronics sectors.
- Automotive:Scratch-resistant 9H+ clear coats penetrate assembly lines from Detroit to Stuttgart. OEM mandates for self-healing paint protection films sustain premium formulation economics despite tetraethyl orthosilicate feedstock volatility.
- Aerospace:Thermal barrier coatings on turbine blades demand CVD/PVD precision for 50–200 micron thickness control. Physical vapor deposition capital intensity excludes mid-scale applicators from contract bidding.
- Electronics:Smartphone and semiconductor fabrication equipment protection attracts investment under India's PLI scheme alignment.
- Industrial Equipment:Power generation and marine operators source performance-guaranteed surface protection through bundled service contracts rather than standalone precursor purchases.
Volume concentration rests with automotive. Steepest expansion trajectory belongs to electronics.
Application:
Functional purpose determines deposition method selection and qualification cycle length.
- Protective Coatings:Chemical and abrasion resistance for marine hulls and chemical processing equipment. ISO 16474 weathering certification backlogs extend qualification cycles.
- Aesthetic Coatings:Gloss retention and color stability for automotive refinish and consumer goods.
- Functional Coatings:Hydrophobic and oleophobic surface properties for electronics and medical devices. REACH fluoropolymer phase-downs accelerate waterborne nano-dispersion R&D.
- Thermal Barrier Coatings:Ceramic matrix composites for gas turbine hot-section components. Aerospace OEMs specify CVD and PVD methods for precise thickness control.
Protective coatings command the broadest installed base. Thermal barrier coatings capture the highest value per square meter.
Technology:
Deposition method dictates capital requirements, scalability, and substrate compatibility.
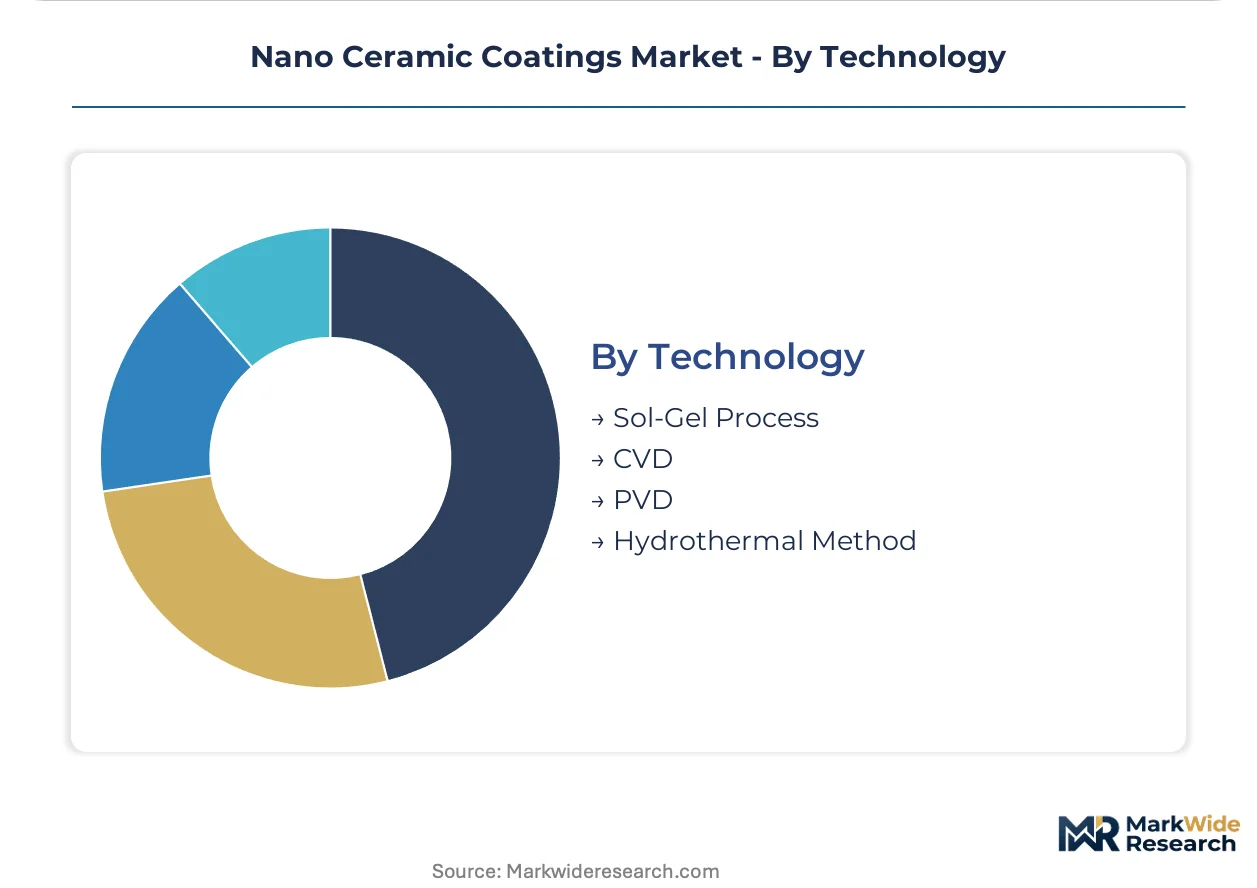
- Sol-Gel Process:Room-temperature hydrolysis of metal alkoxides produces nano-oxide networks at scale. East Asian chemical producers recalibrate precursor output to match automotive and electronics pull.
- CVD:Chemical vapor deposition enables conformal coating of complex geometries for semiconductor equipment. High-temperature process requirements limit substrate compatibility.
- PVD:Physical vapor deposition sputters ceramic targets onto turbine blades and cutting tools. Equipment thresholds exclude mid-scale applicators from aerospace contract bidding.
- Hydrothermal Method:High-pressure aqueous synthesis of crystalline nano-oxides for specialized electronics and catalyst applications.
Sol-gel dominates volume throughput. PVD anchors premium thermal barrier positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tetraethyl orthosilicate feedstock availability clusters near petrochemical corridors in the United States, Germany, and China. Automotive assembly concentration and electronics manufacturing density determine coating demand geography. Regulatory fragmentation across EPA, REACH, and MIIT frameworks forces region-specific formulation strategies.
United States
Automotive OEM clear coat mandates from Detroit assembly plants drive nano-silica consumption in Michigan and Ohio manufacturing corridors. EPA VOC emission thresholds tighten solvent-borne formulation allowances, compelling waterborne nano-dispersion shifts in California and Texas refinish markets. Houston petrochemical complexes supply alkoxide precursors to domestic sol-gel producers.
Germany
Stuttgart and Munich automotive clusters specify scratch-resistant 9H+ topcoats for premium vehicle assembly lines. KBA type-approval processes extend new chemistry commercialization timelines by 18-24 months. BASF and Evonik precursor production in Ludwigshafen anchors European sol-gel supply chains.
China
Yangtze River Delta electronics manufacturers adopt protective coatings for smartphone and semiconductor fabrication equipment under MIIT advanced manufacturing policy. NMPA-aligned industrial coating standards accelerate domestic high-purity alumina precursor capacity. Shanghai and Suzhou sol-gel facilities reduce import dependency.
Japan
Nagoya aerospace component suppliers specify thermal barrier coatings for turbine blade applications. METI carbon neutrality procurement drives public infrastructure spending on low-VOC bridge coatings in Kanto region. Tokyo Bay industrial corridors concentrate robotic spray system adoption.
India
Gujarat and Maharashtra electronics manufacturing zones attract coating investments under PLI scheme incentives for smartphone protection. CDSCO regulatory alignment with international standards accelerates medical device coating qualification. Mumbai-Pune industrial belt concentrates automotive refinish demand.
Nano Ceramic Coatings Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and application technology dimensions. The supplier base organizes into three tiers: integrated coating-applicator systems, standalone chemical suppliers, and specialized thermal barrier formulators. Consolidation pressure concentrates among mid-scale applicators excluded from aerospace contract bidding by CVD/PVD capital thresholds. Dominant competitive moves include robotic spray platform integration and waterborne formulation patent licensing.
Among North American coating conglomerates, PPG Industries and Sherwin-Williams occupy positions spanning automotive OEM relationships and refinish distribution networks. AkzoNobel anchors European marine and industrial protective lines through controlled powder-grade supply. Cerakote exemplifies the specialized thermal barrier archetype against commodity competitors.
| Leading Market Players |
|---|
| PPG Industries |
| Sherwin-Williams |
| AkzoNobel |
| 3M |
| Nanovere Technologies |
| Cerakote |
| Henkel |
| HMG Coatings |
| IHI Corporation |
| Others |
Value Network & Pricing Analysis
Automotive OEM procurement teams in Stuttgart and Detroit increasingly specify performance-guaranteed coating-plus-application bundles rather than standalone chemical purchases, forcing suppliers to absorb application risk and compressing margins on unbundled precursor sales. This behavioral shift concentrates pricing power with integrated coating-applicator systems while fragmenting standalone chemical suppliers into commodity tiers.
Pricing Analysis
Warranty-backed service bundling separates premium suppliers from commodity competitors in this market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Price differentiation hinges on ISO 16474 weathering certification status and robotic application precision. Cost compression in standard-tier liquid coatings is intensifying because of tetraethyl orthosilicate feedstock volatility. Marine refinish operators exhibit highest price sensitivity; aerospace thermal barrier contractors show lowest.
Supply Chain Analysis
Single-source vulnerability sits with German and Chinese petrochemical corridors for tetraethyl orthosilicate and high-purity alumina precursors. Geographic supply concentration clusters in Germany, China, and the United States for alkoxide feedstocks. Raw material dependencies include silica nanoparticles, alumina precursors, and fluoropolymer hydrophobic agents. Supply chain risk centers on REACH fluoropolymer phase-downs disrupting hydrophobic topcoat formulations. Distribution runs through certified application networks and direct OEM supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where CVD/PVD capital intensity and extended KBA certification timelines squeeze mid-scale applicators from aerospace and premium automotive contracting.
For Market Incumbents: Cement defensive positioning through backward integration into sol-gel precursor production in Yangtze River Delta manufacturing corridors. Lock in long-term supply agreements with tetraethyl orthosilicate producers to buffer petrochemical feedstock volatility. Invest in robotic spray platform certification to maintain tier-one automotive OEM access against emerging applicator competitors.
For New Entrants and Emerging Players: Capture white-space opportunity in India's PLI-aligned electronics manufacturing zones for smartphone and semiconductor fabrication equipment coatings. Target Gujarat and Maharashtra industrial corridors where CDSCO regulatory alignment accelerates qualification timelines. Pursue partnership-based go-to-market models with established robotic spray system integrators to bypass capital barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized thermal barrier formulators given aerospace OEM specification tightening and CVD/PVD equipment scarcity. Long-term viability favors vertically integrated coating-applicator systems with captive precursor supply and certified application networks. Monitor German KBA type-approval backlog clearance as inflection signal for new chemistry commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive tetraethyl orthosilicate supply insulates margin from petrochemical volatility in German and Chinese corridors. |
| Robotic Spray Platform Certification | Sub-5-micron thickness precision unlocks tier-one automotive OEM contracts in Stuttgart and Detroit assembly plants. |
| Waterborne Nano-Dispersion R&D Investment | REACH fluoropolymer phase-down compliance secures European protective coating market access against reformulation laggards. |
| Long-Term Supply Agreement with Aerospace OEMs | Performance-guaranteed thermal barrier contracts anchor premium pricing against commodity coating competitors. |
| Joint Venture in India PLI Zones | Electronics manufacturing incentive alignment accelerates smartphone and semiconductor coating qualification under CDSCO frameworks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with automotive OEM procurement managers, sol-gel plant engineers, marine maintenance directors, aerospace coating specifiers, and distribution channel partners combined with secondary validation from EPA emission databases, REACH substance registrations, MIIT policy circulars, and SEC 10-K chemical segment disclosures. Bottom-up coating volume estimates triangulated against top-down petrochemical feedstock consumption patterns.
Granularity-level modeling operated at product type, end user, application method, and technology deposition dimensions across the analysis window. Sol-gel process throughput, CVD/PVD equipment capacity, and regional regulatory cluster adoption curves informed segment-level projections. CAGRs derived from historical precursor trade flows and forward-looking OEM specification timelines. Forecast inputs included tetraethyl orthosilicate price trajectories and KBA type-approval pipeline clearance rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU F-Gas Regulation enforcement intensity and China dual carbon goal acceleration. Forecasts reflect documented assumptions regarding MIIT advanced manufacturing policy continuity and EPA VOC threshold stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Alumina Slurry Market
Ceramics
ME K-Feldspar Market
Ceramics
Fly Ash and Ceramic Microsphere Market
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
White Fused Alumina Market
Ceramics
Global Zirconia Oxygen Sensors Market
Ceramics
Advanced Ceramic Additives Market
Ceramics
Ceramic Proppant Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
Global Functional Ceramics Market
Ceramics
North America Activated Alumina Market
Ceramics
Controlled Pore Metal Oxide Market
Ceramics
Ceramic Frit Market
Ceramics
Co-Fired Ceramic Market
Ceramics
Wollastonite Market
Ceramics
Calcined Bauxite Market