
 Niobium Oxide Market | 2026-2036
Niobium Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Niobium Oxide Market Intelligence
The EU Green Deal's critical raw materials designation for niobium is expanding sourcing urgency across European capacitor and battery supply chains. CBMM leverages its integrated pyrochlore-to-oxide refining complex in Brazil to sustain unmatched feedstock control. Neo Performance Materials anchors North American downstream processing through its rare earth and advanced materials separation expertise. AMG Advanced Metallurgical Group competes via its specialty materials portfolio spanning tantalum and niobium verticals.
Niobium oxide comprises niobium pentoxide and suboxide variants synthesized via hydrometallurgical digestion of pyrochlore ore followed by solvent extraction and calcination, yielding high-purity powders with dielectric constants exceeding 40 for electronic applications. The material primarily serves as a precursor for multilayer ceramic capacitors, lithium-ion battery anode coatings, and superalloy grain refiners in turbine blade manufacturing. Niobium pentoxide dominates product type revenue given its established role in MLCC formulations, while niobium suboxide is gaining traction in next-generation battery anode applications where reduced oxidation states enhance lithium intercalation kinetics. Capacitor applications retain the largest share within the application dimension, though superalloy demand from aerospace component fabrication commands premium pricing through long-term offtake agreements with engine OEMs.
REACH compliance in Europe and China's GB standards for electronic materials are tightening purity thresholds and traceability requirements for niobium oxide imports. The EPA's emerging critical mineral processing guidelines in the US and Japan's METI resource security framework are reshaping how producers document environmental and supply chain credentials. Stakeholders must monitor evolving battery-grade material specifications and regional beneficiation mandates to secure qualified supplier status across diverging regulatory regimes.
Market Dynamics
Battery-grade niobium oxide specifications from electric vehicle manufacturers are compressing qualification timelines while pyrochlore supply concentrates in Brazil's Minas Gerais belt, creating structural tension between feedstock security and downstream certification demands.
Growth Catalysts
- EU Green Deal critical raw materials designation:European capacitor and battery supply chains face mandatory niobium sourcing diversification, accelerating qualified supplier audits and long-term offtake negotiations with Brazilian refiners.
- Lithium-ion anode coating applications:Automakers seeking higher charge-rate materials are expanding battery-grade niobium oxide trials, with reduced oxidation state variants enhancing lithium intercalation kinetics in next-generation cell designs.
- Japan's METI resource security framework:Japanese cathode producers are restructuring procurement standards to secure qualified niobium oxide feedstock, prioritizing traceability documentation and environmental credentials from upstream suppliers.
Market Restraints
- Pyrochlore ore concentration risk:Global feedstock supply clusters in Brazil's Minas Gerais mining belt, creating single-source dependency that amplifies disruption vulnerability from labor actions, infrastructure constraints, or export policy shifts.
- REACH compliance friction:ECHA purity thresholds and traceability requirements for niobium oxide imports impose documentation burdens and testing costs that disadvantage smaller trading intermediaries without in-house regulatory teams.
- Tantalum-niobium substitution economics:Tantalum pentoxide maintains competitive pressure in high-reliability capacitor applications where dielectric performance premiums justify alternative material selection.
Strategic Opportunities
- North American downstream processing gap:Limited domestic niobium oxide refining capacity creates white space for specialty materials separation expertise to serve US aerospace and defense superalloy demand.
- China's dual carbon goals:Beijing's emissions reduction mandates are reshaping cathode production hub procurement standards, opening qualified supplier status for producers with documented low-carbon pyrochlore-to-oxide processing.
- Solid-state battery electrolyte interfaces:Niobium suboxide coatings are emerging as interface stabilizers in solid-state cell architectures, converging with sulfide and oxide electrolyte development timelines from Korean and Japanese cell manufacturers.
Industry Challenges
- Battery-grade specification volatility:Evolving electric vehicle manufacturer anode coating requirements force continuous process recalibration, compressing qualification cycles and straining R&D resource allocation.
- Beneficiation mandate complexity:Diverging regional requirements for in-country processing—from China's GB standards to EPA emerging critical mineral guidelines—fragment compliance architecture and multiply certification timelines.
- Hydrometallurgical talent scarcity:Solvent extraction and calcination expertise for high-purity niobium oxide production concentrates among retiring specialists, constraining capacity expansion and technology transfer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Niobium Oxide Market |
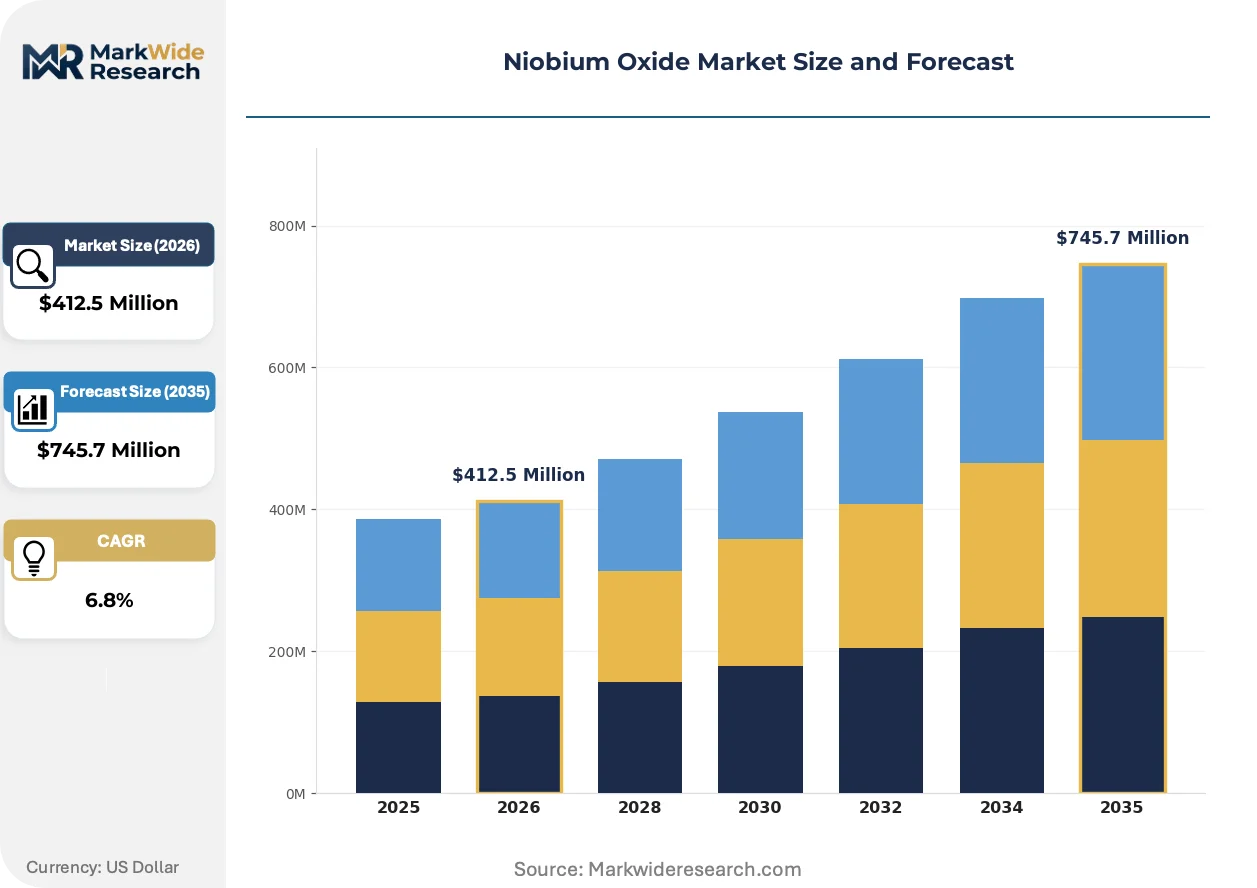
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Niobium Pentoxide, Niobium Suboxide, Niobium Oxalate, Niobium Hydroxide Application: Capacitors, Superalloys, OLED Displays, Ceramic Glazes End Use Industry: Electronics Manufacturing, Aerospace Component Fabrication, Glass Production, Chemical Processing Form: Powder, Granules, Pellets, Coatings |
| Companies Covered | Neo Performance Materials, F&X Electromaterials Limited, CBMM, AMG Advanced Metallurgical Group, Solikamsk Magnesium Works, Materion Corporation, Taki Chemical Co., Ltd, Global Advanced Metals, Merck Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Niobium Oxide Market Strategic Shifts & Innovations
Electrochemical performance engineering and regulatory traceability mandates are converging to reshape how niobium oxide grades are specified, tested, and contracted across capacitor and battery supply chains.
Advanced calcination control systems are modularizing how niobium pentoxide purity tiers are produced from identical pyrochlore feedstock. Specialty materials processors are adopting these systems to serve simultaneous MLCC and battery anode contracts without dedicated production lines. This flexibility is modularizing capacity allocation decisions and compressing minimum order quantities for qualified grades.
REACH substance registration requirements are tightening documentary evidence for niobium oxide import batches into European electronic materials supply chains. ECHA enforcement of updated dossier standards is forcing traders to secure full supply chain disclosure from Brazilian refiners. Battery-grade material shipments face the steepest compliance cost escalation as end-users demand batch-level certificates of analysis.
Long-term offtake contracting is displacing spot market purchasing among aerospace superalloy grain refiner consumers. Engine OEMs are locking multi-year niobium oxide supply agreements with fixed pricing mechanisms to secure turbine blade manufacturing continuity. This preference shift concentrates procurement leverage among vertically integrated Brazilian producers with captive pyrochlore supply.
Niobium Oxide Market Segmentation
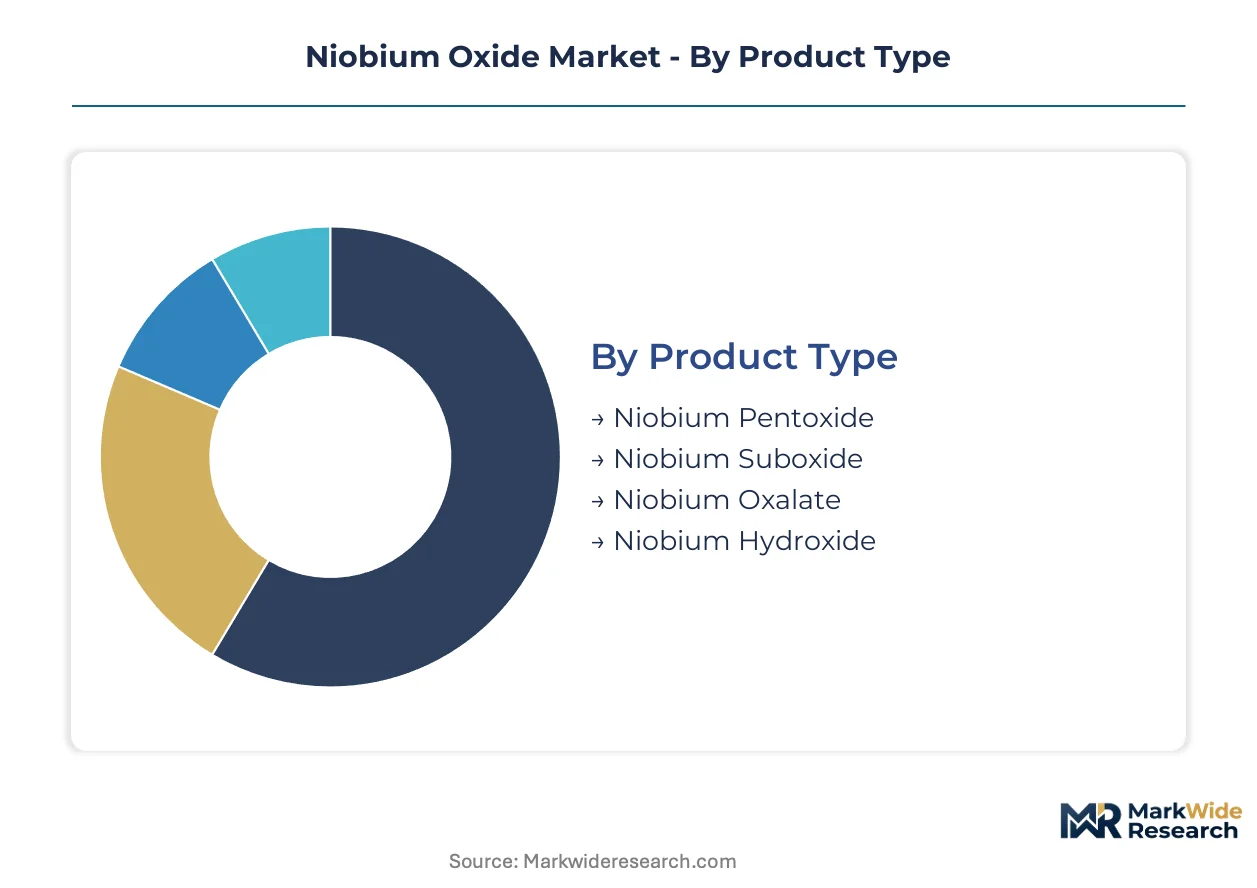
Segmentation in the niobium oxide market determines which purity grades, processing routes, and documentation packages align with specific end-use certifications. Battery-grade specifications from electric vehicle manufacturers impose stricter traceability than standard electronic materials, fragmenting supplier qualification pathways.
Product Type:
REACH substance registration requirements in Europe and China's GB standards for electronic materials impose tiered purity documentation burdens across niobium oxide variants, with battery-grade shipments facing the steepest compliance cost escalation.
- Niobium Pentoxide:High-purity Nb₂O₅ synthesized via hydrometallurgical digestion of pyrochlore ore followed by solvent extraction and calcination, yielding dielectric constants exceeding 40. Demand concentrates in multilayer ceramic capacitor formulations where ECHA purity thresholds and traceability requirements govern European import batches. Long-term offtake agreements with engine OEMs anchor pricing premiums through manufacturing continuity guarantees.
- Niobium Suboxide:Reduced oxidation state variants produced through controlled calcination atmosphere management, enhancing lithium intercalation kinetics in next-generation anode coatings. Japanese cathode producers prioritize this grade under METI resource security framework procurement restructuring, demanding environmental credentials and full supply chain disclosure from Brazilian refiners.
- Niobium Oxalate:Water-soluble precursor for specialized ceramic and catalyst applications requiring solution-based processing routes.
- Niobium Hydroxide:Intermediate feedstock for downstream oxide conversion, serving chemical processing and specialty glass manufacturers with less stringent purity tiers.
Niobium pentoxide sits at the top of the volume ranking, with niobium suboxide climbing the fastest.
Application:
Application segments diverge sharply in margin structure, with aerospace superalloy contracts commanding premium pricing through fixed mechanisms while capacitor volumes scale through modular production systems.
- Capacitors:Dominant application consuming high-purity niobium pentoxide for multilayer ceramic capacitor dielectric layers. Japanese and Korean electronics manufacturers drive procurement concentration, with qualified supplier audits accelerating under EU Green Deal critical raw materials designation.
- Superalloys:Grain refiner applications in turbine blade manufacturing command the steepest pricing premiums through multi-year offtake agreements. US aerospace and defense demand faces limited domestic refining capacity, creating supply security concerns for engine OEMs.
- OLED Displays:Emerging transparent conductive layer applications requiring ultra-high purity grades with documented low-carbon processing credentials.
- Ceramic Glazes:Volume-driven segment serving glass production hubs with standardized purity specifications and shorter qualification cycles.
Capacitors anchor current volume leadership, though superalloy pricing premiums attract backward integration investments from Brazilian producers.
End Use Industry:
Customer concentration patterns split between consolidated aerospace procurement offices and fragmented electronics manufacturing bases across East Asian production hubs.
- Electronics Manufacturing:MLCC and battery anode coating demand from Japanese, Korean, and Chinese cathode producers. Procurement is shifting toward qualified supplier status with documented environmental credentials under diverging regulatory regimes.
- Aerospace Component Fabrication:Turbine blade grain refiner demand concentrated among US and European engine OEMs with captive supply preferences for vertically integrated Brazilian refiners.
- Glass Production:Ceramic glaze and specialty optical glass applications with standardized purity requirements and spot market purchasing patterns.
- Chemical Processing:Catalyst precursor and specialty chemical intermediate demand with flexible specification tolerances.
Electronics manufacturing represents the broadest customer base, while aerospace component fabrication concentrates procurement leverage among a handful of OEMs.
Form:
Physical form selection determines packaging, handling, and dissolution protocols across downstream processing routes, with powder specifications dominating qualified grade shipments.
- Powder:Primary form for capacitor and battery anode applications requiring controlled particle size distribution and surface area specifications. Advanced calcination control systems enable modular purity tier production from identical pyrochlore feedstock.
- Granules:Free-flowing form for superalloy grain refiner applications where controlled dissolution kinetics in molten metal baths are critical.
- Pellets:Compressed form for chemical processing and catalyst manufacturing with standardized dissolution rates.
- Coatings:Pre-applied anode coating formulations for solid-state battery electrolyte interface stabilization, emerging from Korean and Japanese cell manufacturer development programs.
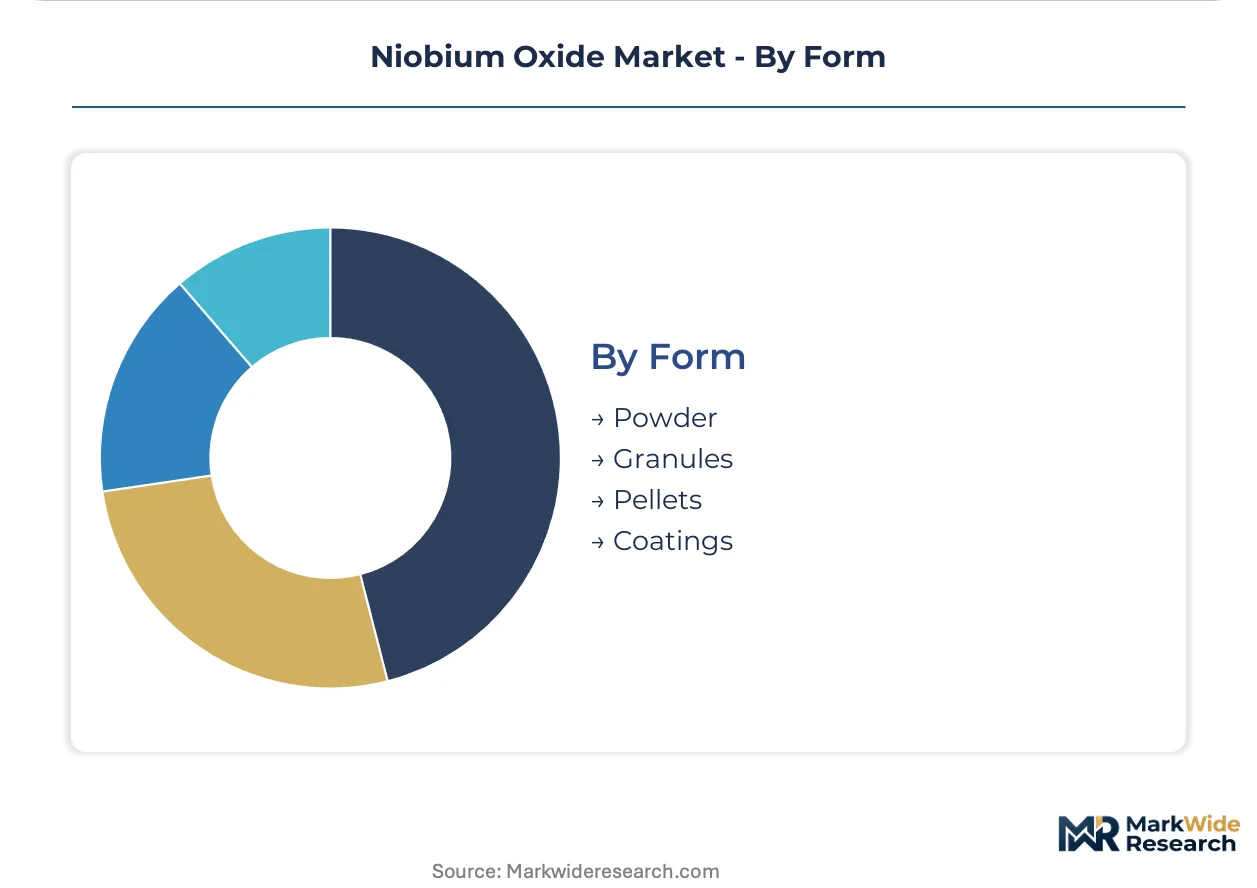
Powder maintains volume dominance, with coatings expanding most quickly alongside solid-state battery commercialization timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Niobium oxide production traces its industrial origins to Brazil's Araxá mining complex, where pyrochlore ore processing first achieved commercial scale in the mid-20th century. This Brazilian foundation established the feedstock architecture that still governs global supply flows today.
Brazil
Minas Gerais hosts the world's dominant pyrochlore-to-oxide refining infrastructure, with CBMM's integrated complex supplying the majority of global capacitor and battery-grade material. ANVISA traceability requirements for chemical imports are tightening documentation standards for export batches. The Araxá industrial corridor continues expanding calcination capacity to serve Japanese and Korean electronics manufacturers.
United States
US aerospace superalloy demand from turbine blade fabricators faces limited domestic niobium oxide refining capacity, creating supply security concerns for engine OEMs. EPA emerging critical mineral processing guidelines are reshaping how producers document environmental credentials for Defense Department contracts. The Midwest manufacturing belt relies heavily on qualified Brazilian refiner imports for grain refiner applications.
Japan
Japanese cathode producers under METI's resource security framework are restructuring procurement standards to secure qualified niobium oxide feedstock with full supply chain disclosure. Battery-grade material trials from electric vehicle manufacturers are accelerating qualification timelines for reduced oxidation state variants. The Kansai region's electronics manufacturing base drives concentrated demand for high-purity capacitor grades.
Germany
German automotive and industrial electronics sectors face mandatory niobium sourcing diversification under EU Green Deal critical raw materials designation. ECHA REACH substance registration requirements impose documentary evidence burdens for import batches into European supply chains. The Bavarian semiconductor equipment cluster is accelerating qualified supplier audits with Brazilian refiners.
China
Beijing's dual carbon goals are reshaping cathode production hub procurement standards across the Yangtze River Delta battery manufacturing corridor. GB standards for electronic materials are tightening purity thresholds and traceability requirements for niobium oxide imports. Domestic pyrochlore processing capacity remains limited, maintaining dependency on Brazilian feedstock for battery-grade specifications.
Niobium Oxide Market Key Industry Players
Capital-heavy integrated refiners compete with asset-light specialty materials traders in a market structure defined by feedstock control versus downstream certification expertise. Brazilian producers with captive pyrochlore supply dominate volume leadership, while North American and European processors compete on separation technology and qualified supplier status. Three archetypes define competitive positioning: vertically integrated mining-to-oxide refiners, advanced materials separation specialists, and trading intermediaries with regulatory compliance capabilities. Dominant competitive moves include backward integration into pyrochlore mining rights and strategic partnerships with battery cell manufacturers for qualification trials.
Among integrated Brazilian refiners, CBMM occupies the foundational position exemplifying captive feedstock control. Neo Performance Materials and AMG Advanced Metallurgical Group represent the specialty materials separation archetype, leveraging rare earth and refractory metal processing expertise to serve aerospace and electronics demand. These three companies anchor the competitive landscape across distinct capability vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Neo Performance Materials |
| F&X Electromaterials Limited |
| CBMM |
| AMG Advanced Metallurgical Group |
| Solikamsk Magnesium Works |
| Materion Corporation |
| Taki Chemical Co., Ltd |
| Global Advanced Metals |
| Merck Group |
| Others |
Cost & Logistics Intelligence
Advanced calcination control systems modularizing purity tier production from identical pyrochlore feedstock compress cost economics while simultaneously concentrating supply leverage among Brazilian refiners with captive ore access. This production-method transition reshapes how capacitor-grade and battery-grade specifications compete for shared capacity, amplifying pricing power for integrated producers.
Pricing Analysis
Long-term offtake contracting with fixed pricing mechanisms anchors the dominant pricing structure, displacing spot market purchasing among aerospace superalloy consumers. Price differentiation stems from certification grade tiers and volume scale commitments, with battery-grade material facing the steepest documentation cost escalation. Cost compression in standard electronic material tiers intensifies as modular production systems enable smaller batch qualification. Japanese cathode producers exhibit the least price sensitivity given METI resource security mandates, while trading intermediaries without in-house regulatory teams face margin erosion from REACH compliance burdens.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from engine manufacturers and Japanese electronics producers, bypassing distributor intermediaries for qualified grade shipments. Feedstock supply draws from Brazil's Minas Gerais belt with secondary concentration in Canadian and Australian tantalum-niobium operations. Pyrochlore ore, solvent extraction reagents, and calcination energy inputs constitute critical cost components. Single-source vulnerability from Brazilian supply clustering amplifies disruption risk from labor actions or export policy shifts. Distribution runs through vertically integrated refiner-direct contracts rather than spot market trading for qualified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through battery-grade specification premiums and calcination technology cost-down curves. The shift from capacitor-dominant to battery-anode demand reshapes which purity tiers command pricing power.
For Market Incumbents: Acquire hydrometallurgical talent pools and solvent extraction expertise to offset retiring specialist scarcity. Secure captive pyrochlore mining rights in Brazil's Minas Gerais expansion zones to defend against feedstock concentration risk. Lock multi-year offtake agreements with Korean and Japanese cell manufacturers before solid-state battery commercialization accelerates qualification timelines. For New Entrants and Emerging Players: The premium-economy tier gap in North American downstream processing creates entry white space for specialty materials separation expertise. Target US aerospace and defense superalloy demand where limited domestic refining capacity creates supply security concerns. Pursue qualified supplier status under EPA emerging critical mineral guidelines as the go-to-market angle for Defense Department contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light trading intermediaries facing REACH compliance cost escalation without captive feedstock. Long-term viability centers on backward integration into pyrochlore supply or downstream certification expertise. Watch for solid-state battery electrolyte interface stabilization trials as the inflection signal for niobium suboxide demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrochlore Mining | Captive ore access insulates Brazilian refiners from export policy volatility and concentrates procurement leverage. |
| Long-term Supply Agreement with Cell Manufacturers | Fixed-price offtake contracts with Korean and Japanese producers secure manufacturing continuity through qualification cycles. |
| Green Manufacturing Transition | Documented low-carbon calcination processes unlock qualified supplier status under China's dual carbon procurement mandates. |
| Capacity Expansion in Battery-Grade Production | Modular calcination systems serving simultaneous MLCC and anode coating contracts compress minimum order quantities. |
| Joint Venture for North American Downstream Processing | Specialty materials separation partnerships address US aerospace supply security gaps without full capital commitment. |
Research Approach
Direct dialogue with hydrometallurgical plant managers, cathode producer procurement leads, engine OEM supply chain directors, and ECHA regulatory compliance officers grounded the qualitative foundation. Secondary validation drew from Brazilian customs export data, SEC 10-K filings from specialty materials processors, ANVISA traceability requirement updates, and METI resource security framework documentation. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across the analysis window.
Bottom-up modeling of pyrochlore-to-oxide refining capacity and top-down consumption estimates from capacitor, battery, and superalloy end-uses structured the analytical lens. Segmentation dimensions spanned product type, application, end-use industry, and physical form across the projection horizon. CAGRs derived from capacity utilization trends, qualification timeline compression, and regulatory-driven procurement restructuring. Industry-specific inputs included solid-state battery commercialization timelines and REACH substance registration enforcement patterns.
Caveats apply where Brazilian labor actions, ECHA purity threshold revisions, or electric vehicle manufacturer anode specification pivots could materially shift the outlook. Forecasts reflect assumptions about calcination technology diffusion and battery-grade qualification success rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Metal Forging Parts Market
Metals
Global Superconducting Wire Market
Metals
South America Metal Finishing Market
Metals
Ore Metals Market
Metals
Iron Casting Market
Metals
Beryllium Copper for Telecommunication Market
Metals
Barium Market
Metals
Rolled Steel Motor Market
Metals
Zinc Plating Market
Metals
Stainless Steel Market
Metals
TMCP Steel Market
Metals
Titanium Powder Market
Metals
Aluminium Rolled Products Market
Metals
Rare Earth Metals Market
Metals
North America Aluminium Powder Market
Metals
Copper Chromium Black Market