
 Ceramics Packaging Market | 2026-2036
Ceramics Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramics Packaging Market Outlook
The ceramics packaging tier is shifting between artisanal premium positioning and mass-market commodity supply. Kyocera Corporation leverages advanced ceramic engineering to dominate high-reliability industrial segments. CoorsTek anchors North American supply through captive alumina processing and vertical manufacturing control. CeramTec GmbH specializes in precision medical-to-packaging material crossover, competing on European regulatory alignment rather than scale.
Ceramics packaging comprises fired clay-based containers—typically alumina, porcelain, or stoneware—engineered for thermal stability, chemical inertness, and repeated reuse cycles exceeding 1,000 washes. Porcelain and stoneware lead material demand where food contact safety and microwave compatibility are specified, while bone china occupies narrow premium gifting channels. Food service and retail applications drive volume, though decorative and industrial end uses capture disproportionate margin pools through limited-batch production and technical certification requirements.
EU REACH and F-Gas Regulation constrain glaze chemistry and kiln emissions across European supply chains, while FDA food contact substance notifications govern US import clearance. China's GB standards and MIIT energy-efficiency mandates reshape export-ready factory compliance costs. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and recertification delays.
Market Dynamics
The ceramics packaging sector faces structural pressure from the EU Packaging and Packaging Waste Regulation, which mandates material traceability and recycled content thresholds that reshape supplier compliance costs and factory certification timelines across export-oriented manufacturing clusters.
Growth Catalysts
- EU regulatory mandates:The Packaging and Packaging Waste Regulation accelerates restaurant and café conversion from single-use plastics to durable ceramic serveware, creating replacement demand across food service procurement channels.
- Food service sustainability targets:Chain operators specify alumina and stoneware containers for thermal stability exceeding 1,000 wash cycles, reducing lifetime cost per use against disposable alternatives.
- Jingdezhen manufacturing concentration:China's ceramic cluster supplies global private-label programs with integrated glaze chemistry and kiln firing capabilities that compress lead times for volume buyers.
Market Restraints
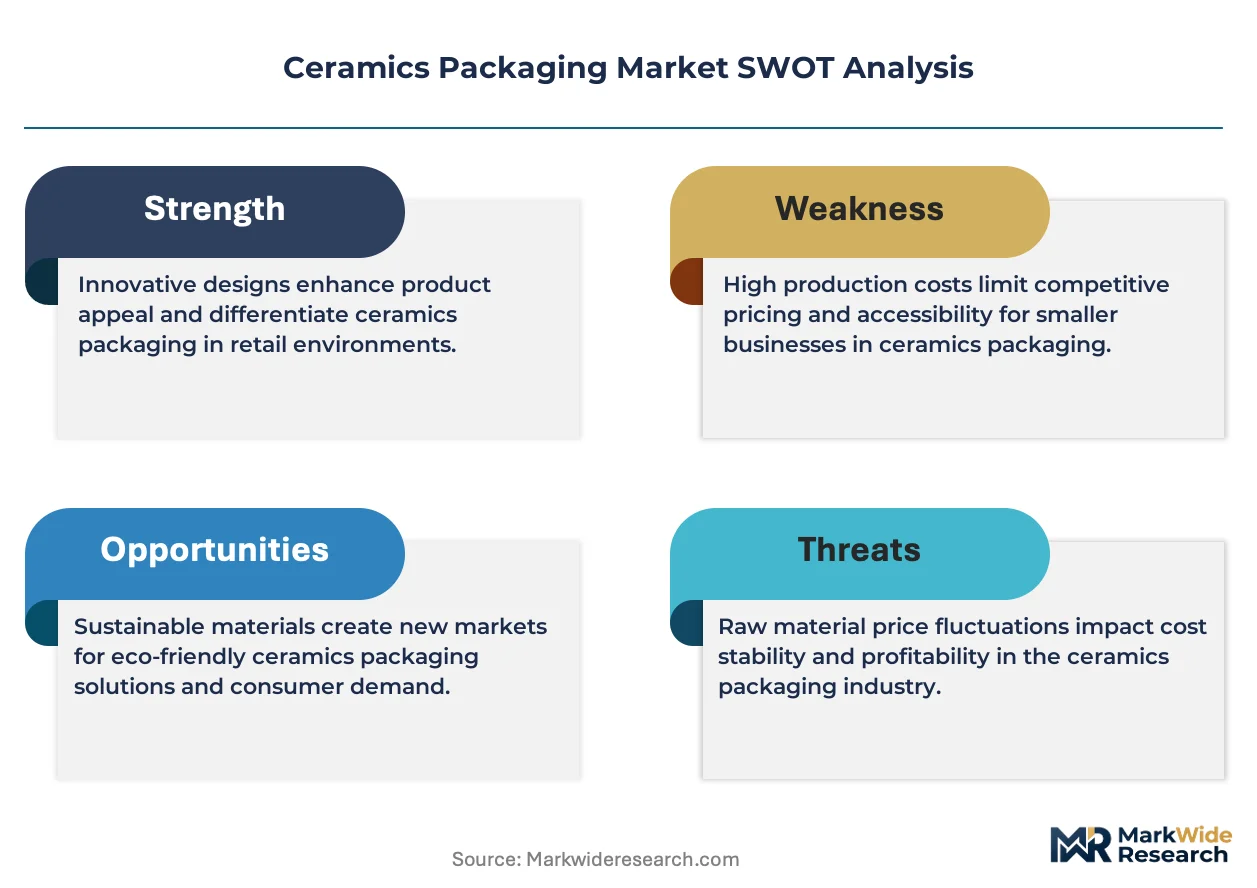
- Energy input volatility:Natural gas and electricity costs for tunnel kiln firing fluctuate with European and Asian spot markets, compressing margins for producers without captive energy supply or long-term utility contracts.
- China supply concentration:Dehua and Jingdezhen clusters control bulk porcelain and stoneware output, exposing buyers to single-origin disruption risks from environmental enforcement actions or export license modifications.
- Glaze chemistry constraints:EU REACH restrictions on heavy metal pigments and F-Gas Regulation limits on kiln emissions constrain decorative finish options and extend reformulation timelines for European-market products.
Strategic Opportunities
- Medical-to-packaging material crossover:Precision alumina formulations certified for implantable devices transfer into high-reliability pharmaceutical and laboratory packaging segments with premium pricing tolerance.
- North American reshoring incentives:US domestic production gaps in technical ceramics create openings for captive alumina processing facilities serving FDA-regulated food contact and industrial applications.
- Direct-to-restaurant distribution:Bypassing traditional hospitality supply wholesalers through manufacturer-owned digital platforms captures margin and captures specification data from independent café and boutique hotel buyers.
Industry Challenges
- Kiln engineering talent scarcity:Specialized furnace design and firing curve optimization expertise concentrates among aging practitioners in traditional ceramic regions, constraining capacity expansion for precision technical grades.
- Dual jurisdiction certification lag:Simultaneous EU REACH and FDA food contact substance notification processes extend product launch timelines by 8-14 months for formulations with novel glaze compositions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramics Packaging Market |
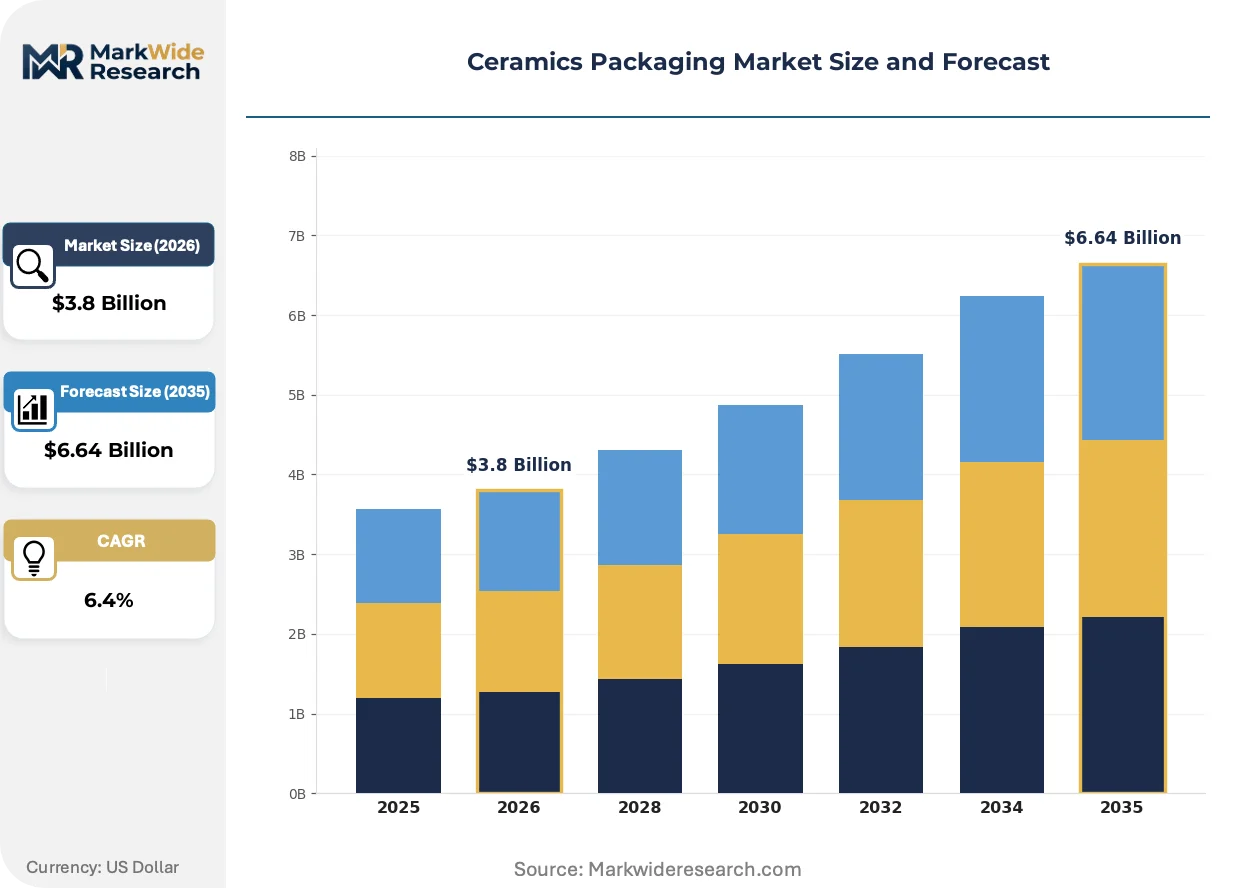
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cups, Plates, Bowls, Bottles Material: Porcelain, Stoneware, Earthenware, Bone China Application: Food Service, Retail, Industrial, Decorative End Use: Restaurants, Households, Hotels, Cafés |
| Companies Covered | Kyocera Corporation, CoorsTek, Inc., CeramTec GmbH, Morgan Advanced Materials plc, NGK Insulators, Ltd., Schott AG, AMETEK Inc., Materion Corporation, Remtec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramics Packaging Market Strategic Shifts
Digital manufacturing integration and regulatory chemistry constraints are compressing traditional production methods while opening premium segments for precision-engineered ceramic solutions.
Advanced kiln control systems is automating firing curve management across continuous tunnel operations. Food service manufacturers adopt these systems to reduce thermal variation defects and energy consumption per batch. The technology is automating quality consistency that previously required manual operator intervention, compressing rejection rates and enabling just-in-time production schedules for seasonal restaurant program launches.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent cooling systems out of ceramic glazing lines. Manufacturers retrofit facilities with aqueous-based cooling or invest in regenerative thermal oxidizers to maintain emission compliance. Italian and Spanish tableware exporters face the steepest retrofit burden where aging plant infrastructure predates 2015 environmental directive thresholds.
Restaurant group procurement consolidation is displacing fragmented distributor relationships with centralized specifications negotiated directly with ceramic manufacturers. Large hospitality operators now mandate batch-level traceability and carbon footprint documentation as contract prerequisites. This pattern is most visible in Nordic and German markets where chain penetration in casual dining exceeds independent operator share.
Ceramics Packaging Market Segmentation
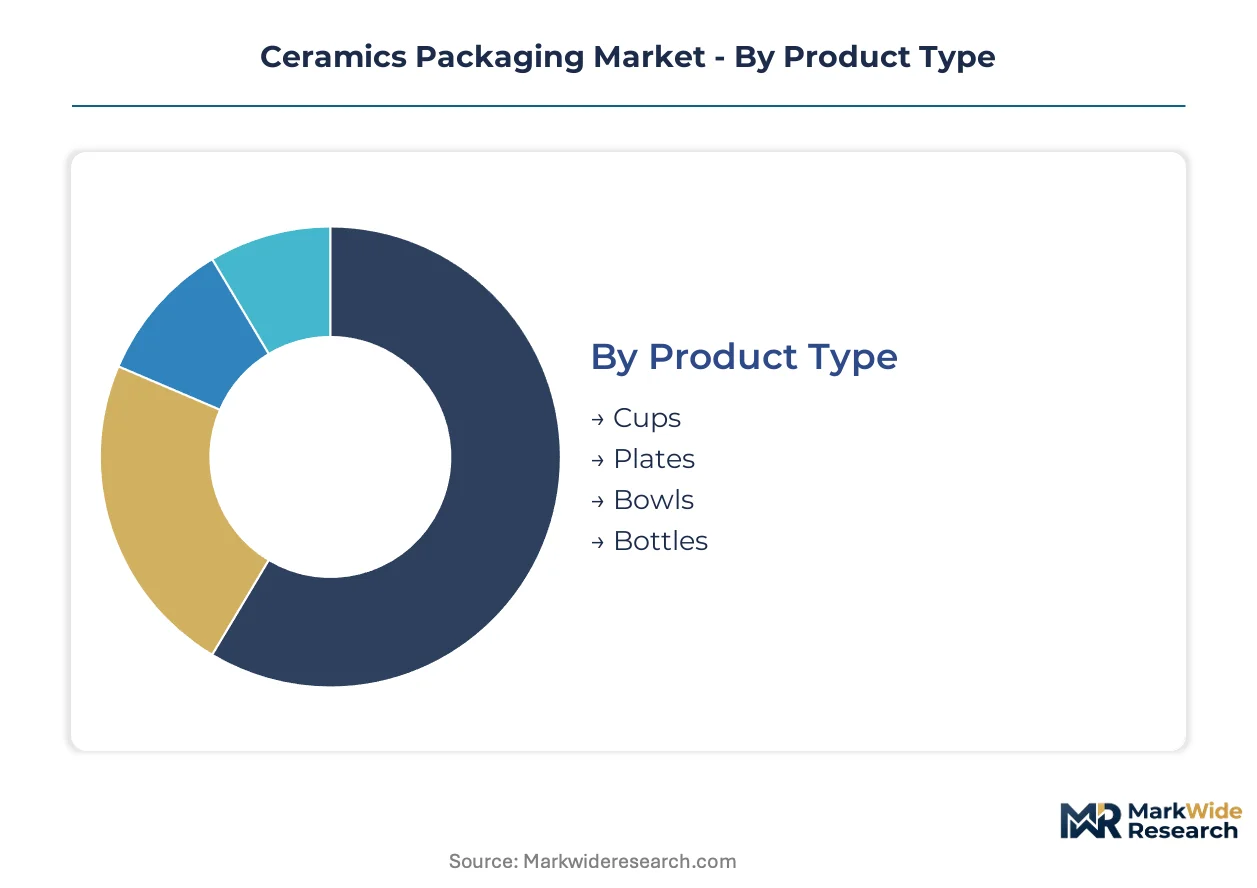
Ceramics packaging segmentation reveals divergent margin profiles across material grades and end-use specifications. Procurement patterns in food service channels favor thermal durability over decorative finish, while retail gifting segments prioritize bone china translucency and limited-batch aesthetics.
Product Type:
Volume buyers differentiate primarily by wash-cycle durability requirements and thermal shock tolerance rather than unit cost.
- Cups:Alumina-reinforced handle designs withstand commercial dishwasher cycles exceeding 1,000 washes. Chain coffee operators in Germany and Sweden specify these for thermal retention in high-throughput service environments.
- Plates:Flatware dominates procurement volumes across casual dining chains where portion standardization and stackability reduce storage footprint. Jingdezhen manufacturers supply private-label programs with integrated glaze chemistry that resists metal marking from cutlery.
- Bowls:Soup and noodle service applications in Asian food service channels drive demand for thicker wall sections and rim reinforcement.
- Bottles:Narrow premium segment for specialty oil and vinegar retail packaging where UV-blocking glaze formulations protect contents.
Plates lead volumes today; cups are gaining share fastest through coffee chain standardization programs.
Material:
Cost-to-performance ratios separate commodity procurement from premium specification tiers.
- Porcelain:Kaolin-based formulations fired above 1,200°C achieve vitrified density required for microwave and dishwasher compatibility. FDA food contact notifications and EU REACH compliance dominate export-ready production from Dehua clusters.
- Stoneware:Higher silica content delivers thermal mass preferred by casual dining operators for heat retention. Italian and Spanish manufacturers face F-Gas Regulation retrofit costs for kiln emissions compliance.
- Earthenware:Porous lower-fire clay suits decorative and limited-use retail applications where permeability is acceptable.
- Bone China:Bone ash content produces translucency valued in premium hotel tableware and corporate gifting channels. Narrow volume base commands disproportionate margin through limited-batch production.
Porcelain leads volumes today; stoneware is expanding most quickly through food service sustainability conversions.
Application:
Specification intensity varies by regulatory exposure and reuse-cycle requirements.
- Food Service:Commercial operators mandate batch-level traceability and carbon footprint documentation as contract prerequisites in Nordic markets. Thermal stability specifications exceed 1,000 wash cycles to reduce lifetime cost per use.
- Retail:Consumer-facing channels prioritize aesthetic differentiation through glaze chemistry and form factor novelty. Supermarket private-label programs source from integrated Jingdezhen manufacturers with compressed lead times.
- Industrial:Precision alumina formulations certified for laboratory and pharmaceutical containment command premium pricing through technical certification requirements.
- Decorative:Limited-batch production captures disproportionate margins through artisanal positioning and collector channel distribution.
Food service leads volumes today; industrial applications show the steepest expansion trajectory through medical-to-packaging material crossover.
End Use:
Procurement consolidation patterns separate fragmented independent operators from centralized chain specifications.
- Restaurants:Large hospitality operators negotiate direct manufacturer relationships bypassing traditional wholesale distributors. German and Nordic chain penetration exceeds independent operator share in casual dining segments.
- Hotels:Boutique and luxury properties specify bone china and custom glaze formulations for differentiated tableware programs.
- Cafés:Independent coffee operators drive demand for handle-reinforced cup designs through manufacturer-owned digital platforms that capture specification data.
- Households:Mass-market retail channels supply consumer replacement demand with standardized porcelain and stoneware sets.
Restaurants lead volumes today; cafés are climbing the fastest through direct-to-operator distribution adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China controls manufacturing volume through Jingdezhen and Dehua clusters, while Germany enforces the strictest regulatory compliance costs for European-market ceramics packaging.
China
Dehua and Jingdezhen ceramic clusters supply global private-label programs with integrated glaze chemistry and kiln firing capabilities. MIIT energy-efficiency mandates reshape export-ready factory compliance costs for international buyers. The Yangtze River Delta region concentrates technical ceramics development for high-reliability industrial applications.
Germany
Industrial food service procurement from chain operators drives alumina-reinforced container specifications exceeding 1,000 wash cycles. ECHA REACH restrictions on heavy metal pigments constrain decorative finish options for European-market products. Bavaria hosts precision ceramic engineering facilities serving medical-to-packaging material crossover segments.
United States
FDA food contact substance notifications govern import clearance for porcelain and stoneware serveware entering food service channels. Restaurant group procurement consolidation displaces fragmented distributor relationships with centralized manufacturer negotiations. The Southeast region shows expanding technical ceramics production gaps for domestic reshoring opportunities.
Italy
F-Gas Regulation phase-down schedules force refrigerant-dependent cooling systems out of ceramic glazing lines across aging tableware export facilities. Nordic and German hospitality operators mandate batch-level traceability and carbon footprint documentation from Italian suppliers. Emilia-Romagna maintains traditional kiln engineering expertise concentrated among aging practitioner networks.
Japan
METI industrial standards shape precision alumina formulation requirements for pharmaceutical and laboratory packaging segments. Domestic manufacturers leverage advanced ceramic engineering capabilities developed for electronics applications. The Nagoya industrial corridor anchors technical ceramics R&D for high-reliability containment solutions.
Ceramics Packaging Market Competitive Environment
Top-tier vendors anchor technical ceramics engineering, while mid-scale fabricators compete on regulatory alignment and geographic proximity to end-use markets. The vendor base spans Japanese precision ceramics conglomerates, North American captive processing operations, and European regulatory specialists. Three archetypes dominate: advanced materials engineers with medical-device certification heritage, vertically integrated alumina processors controlling mine-to-kiln supply chains, and regional compliance specialists competing on EU regulatory alignment. Capacity expansion and direct-to-restaurant digital distribution represent the dominant competitive moves reshaping channel relationships.
Within the precision engineering tier, Kyocera Corporation and NGK Insulators, Ltd. exemplify Japanese conglomerates with cross-sector ceramic expertise. CoorsTek, Inc. anchors North American supply through captive alumina processing capabilities. CeramTec GmbH occupies a position as the European regulatory alignment specialist competing on certification breadth rather than manufacturing scale.
| Leading Market Players |
|---|
| Kyocera Corporation |
| CoorsTek, Inc. |
| CeramTec GmbH |
| Morgan Advanced Materials plc |
| NGK Insulators, Ltd. |
| Schott AG |
| AMETEK Inc. |
| Materion Corporation |
| Remtec Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Dehua and Jingdezhen anchor manufacturing tiers, translating generational kiln expertise into pricing discipline that resists commodity erosion despite energy cost volatility. Their ownership structure enables patient capital allocation toward glaze chemistry R&D and captive clay sourcing, insulating premium tiers from spot-market input swings while compressing margins for private-label volume buyers.
Pricing Analysis
Bundled technical certification and compliance documentation commands premium positioning against unbundled commodity supply where buyers assume regulatory filing burdens. Pricing stratifies across FDA-notified, REACH-compliant, and economy tiers with differentiation resting on wash-cycle durability guarantees and carbon footprint traceability. Cost compression in economy stoneware intensifies because Jingdezhen clusters absorb energy surcharge volatility to defend volume share. Chain restaurant procurement teams show lowest price sensitivity where lifetime cost-per-use calculations favor alumina-reinforced specifications, while independent café buyers negotiate aggressively on unit economics.
Supply Chain Analysis
Direct-to-hospitality channels handle consolidated chain demand, bypassing traditional wholesale distributors that fragment independent operator procurement. Manufacturing concentrates in China, Italy, and Germany with raw material dependencies spanning kaolin deposits in Brazil and UK, alumina from Australia, and bone ash from cattle-processing regions. Single-source vulnerability runs through Jingdezhen glaze chemistry clusters where environmental enforcement actions disrupt export-ready output without alternative qualification timelines. Distribution runs through manufacturer-owned digital platforms for boutique buyers alongside legacy hospitality supply wholesalers serving fragmented independent accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU regulatory compliance costs in Germany and Italy exceed Chinese manufacturing base costs by multiples sufficient to justify reshoring incentives for technical ceramics segments.
For Market Incumbents: Deploy captive alumina processing to secure input cost predictability against natural gas volatility threatening Italian and Spanish kiln operations. Kyocera Corporation and CoorsTek, Inc. demonstrate defensive positioning through backward integration into high-purity alumina refining, insulating pharmaceutical and laboratory packaging tiers from supply disruption. Certification breadth across FDA and REACH jurisdictions protects margin pools from emerging Asian competitors lacking dual-jurisdiction filing experience. For New Entrants and Emerging Players: The price-point gap between bone china premium gifting and commodity stoneware food service creates entry space for precision-engineered alumina formulations targeting medical-to-packaging crossover segments. North American reshoring incentives present the most penetrable geography where domestic production gaps in FDA-regulated food contact applications remain unfilled. Direct-to-restaurant digital platforms offer the sharpest go-to-market angle, capturing specification data and margin from independent café buyers bypassing traditional wholesale channels. For Investors and Strategic Acquirers: Valuations sit cheapest among Italian and Spanish tableware exporters facing F-Gas Regulation retrofit burdens and aging kiln infrastructure replacement cycles. Long-term viability across the analysis window favors precision technical ceramics over decorative tableware given medical-device certification heritage transferable to pharmaceutical containment. Watch EU Packaging and Packaging Waste Regulation enforcement intensity as the inflection signal determining whether compliance-cost differentials widen or compress between European and Asian supply bases.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Alumina Processing | CoorsTek's mine-to-kiln control insulates margins from Australian bauxite price volatility. |
| Direct-to-Restaurant Digital Platform | Manufacturer-owned channels capture specification data from Nordic boutique hotel buyers. |
| Medical-to-Packaging Material Crossover | CeramTec's implantable-device certification transfers into pharmaceutical containment premiums. |
| F-Gas Regulation Retrofit Program | Italian exporters face steepest compliance burden where aging infrastructure predates 2015 thresholds. |
| Dual Jurisdiction Certification Investment | Simultaneous FDA and REACH filings extend timelines but lock out competitors lacking regulatory bandwidth. |
Study Parameters
Bottom-up food service procurement modeling reconciled against top-down kiln capacity tracking forms the analytical core of this study. Primary interviews with chain restaurant procurement directors, ceramic plant engineers, glaze chemistry specialists, and hospitality supply distributors combined with secondary validation from FDA food contact substance notifications, ECHA REACH registration databases, MIIT energy-efficiency disclosure filings, and customs trade records. Triangulation between demand-side specification intensity and supply-side certification capacity ensures segment-level accuracy.
Input-output matrices map alumina and kaolin flows through firing and finishing stages to end-use applications across the projection horizon. Segmentation dimensions include material grade, product type, application intensity, and regional regulatory cluster with CAGRs derived from wash-cycle replacement demand curves and restaurant group procurement consolidation trajectories. Kiln energy consumption per batch and glaze chemistry reformulation timelines serve as industry-specific forecast inputs.
Caveats apply where EU Packaging and Packaging Waste Regulation enforcement intensity, Chinese environmental inspection schedules, or natural gas price spikes could materially shift the outlook. Forecasts reflect documented assumptions regarding Jingdezhen cluster capacity expansion and Nordic hospitality operator sustainability target adoption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global Magnesium Silicate Market
Ceramics
Solid-Ion Conductors Market
Ceramics
Asia-Pacific Kaolin Market
Ceramics
Technical Ceramics Market
Ceramics
Graphite Crucibles Market
Ceramics
South Korea Ceramic Tiles Market
Ceramics
Methyl Silicate Market
Ceramics
Carbon-Ceramic Discs Market
Ceramics
Vaterite Market
Ceramics
Titanium Carbide Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
Cerium Nitride Market
Ceramics
Ceramic Additives Market
Ceramics
Germany Ceramic Tiles Market
Ceramics
North America Activated Alumina Market
Ceramics
Alumina Slurry Market