
 Global Zirconia Oxygen Sensors Market | 2026-2036
Global Zirconia Oxygen Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Zirconia Oxygen Sensors Market Analysis
Wide-band sensing architecture is fragmenting the traditional zirconia oxygen sensor technology stack into application-specific variants. Bosch sustains dominance through backward integration into ceramic substrate production. NGK-NTK leverages its position in exhaust system OEM supply chains across Japanese and European automakers. Continental specializes in integrated sensor modules that combine oxygen measurement with temperature and pressure compensation.
Zirconia oxygen sensors employ yttria-stabilized zirconium dioxide ceramic elements that generate voltage proportional to oxygen partial pressure differentials across the electrolyte, typically operating at temperatures between 300°C and 900°C for precise combustion control. Wide-band sensors capture the fastest growth trajectory as gasoline direct-injection and lean-burn diesel platforms require continuous lambda measurement across stoichiometric and lean operating regimes. Electrochemical technology anchors the installed base, while semiconductor-based alternatives encroach in cost-sensitive aftermarket replacement segments.
EPA tailpipe standards, Euro 7 emission limits under EMA review, and China's MEE enforcement of China VI-B provisions collectively tighten oxygen sensor accuracy requirements and durability testing protocols. Japan's METI fuel-efficiency benchmarks and ISO 26262 functional safety mandates further shape product development priorities for automotive-integrated designs. Stakeholders must monitor divergence between regional certification timelines and sensor platform standardization efforts.
Market Dynamics
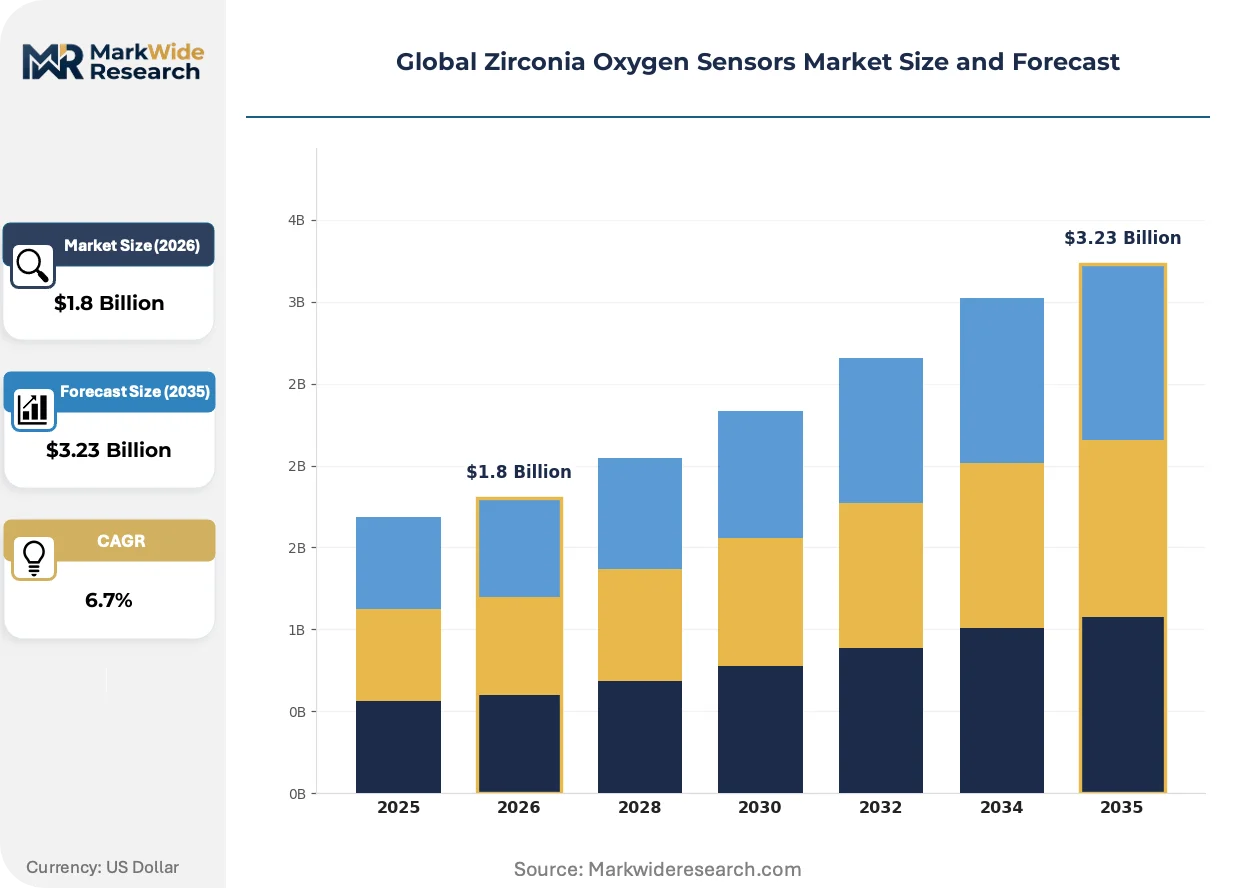
Wide-band zirconia sensor architecture is fragmenting the traditional technology stack as automotive OEMs in China and Germany expand procurement to meet Euro 7 and China VI-B tailpipe emission limits. Solid-electrolyte manufacturing advances are lowering sensor drift rates and reshaping competitive positioning across East Asian automotive manufacturing clusters.
Growth Catalysts
- Euro 7 emission limits:EMA review of tightened tailpipe standards is forcing European automotive OEMs to upgrade from narrow-band to wide-band sensing platforms for continuous lambda measurement.
- Gasoline direct-injection platforms:Lean-burn combustion architectures require precise oxygen partial pressure monitoring across stoichiometric and lean operating regimes.
- Shanghai's Pudong industrial zone:Concentrated automotive manufacturing is driving localized sensor procurement and captive ceramic substrate production.
Market Restraints
- Yttrium oxide price volatility:Stabilized zirconium dioxide ceramic production depends on rare earth supply concentration in Chinese processing facilities.
- Semiconductor-based alternatives:Cost-sensitive aftermarket replacement segments face substitution pressure from titanium dioxide and gallium oxide sensing elements.
- ISO 26262 functional safety mandates:Automotive-integrated designs require extended validation timelines and redundant sensing architectures that extend development cycles.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for advanced automotive electronics create localized manufacturing incentives for sensor module assembly.
- Integrated sensor modules:Convergence of oxygen measurement with temperature and pressure compensation opens aftermarket retrofit potential for legacy vehicle fleets.
- Japan's METI fuel-efficiency benchmarks:Stringent corporate average fuel economy targets accelerate demand for wide-band sensors in hybrid powertrain applications.
Industry Challenges
- Electrochemical calibration expertise:Solid-electrolyte manufacturing requires specialized ceramic sintering technicians with yttria-stabilization process knowledge.
- China VI-B enforcement timelines:MEE implementation schedules diverge from Euro 7 EMA review cycles, creating platform standardization friction for multinational OEMs.
- Legacy narrow-band inventory:Existing sensor stockpiles and tooling investments slow wide-band architecture migration in cost-constrained aftermarket channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Zirconia Oxygen Sensors Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wide Band, Narrow Band, Vintage Sensors, Automotive Sensors Technology: Electrochemical, Optical, Thermal, Semiconductor End User: Automotive, Aerospace, Marine, Industrial Installation: Fixed, Portable, Integrated, Standalone |
| Companies Covered | Delphi, SST Sensing, NGK-NTK, Continental, Fujikura, Bosch, Honeywell, Cubic Sensor and Instrument, Denso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Zirconia Oxygen Sensors Market Emerging Trajectories
Sensor module integration and electrochemical manufacturing precision are reshaping how zirconia oxygen sensors deliver combustion control data. Three developments are restructuring competitive positioning and procurement patterns across automotive OEM and aftermarket channels.
Wide-band sensing circuitry is digitizing lambda signal processing for gasoline direct-injection and lean-burn diesel platforms. Bosch and NGK-NTK are deploying digital heater control algorithms across Japanese and European automaker supply chains. This transition is digitizing the interface between exhaust gas measurement and engine control unit feedback loops, compressing calibration cycle times.
China's MEE enforcement of China VI-B provisions is tightening oxygen sensor accuracy requirements beyond Euro 7 draft specifications. The regulation mandates extended durability testing protocols for sensors operating in high-sulfur fuel environments. Aftermarket suppliers serving Shanghai's Pudong industrial zone are restructuring certification documentation to satisfy dual compliance frameworks.
Automotive OEM procurement is consolidating around integrated sensor modules that bundle oxygen measurement with temperature and pressure compensation. Tier-1 suppliers are displacing discrete component vendors in exhaust system supply chains. This concentration is most visible in Toyota City's manufacturing cluster, where single-source module contracts now dominate new platform development.
Global Zirconia Oxygen Sensors Market Segmentation
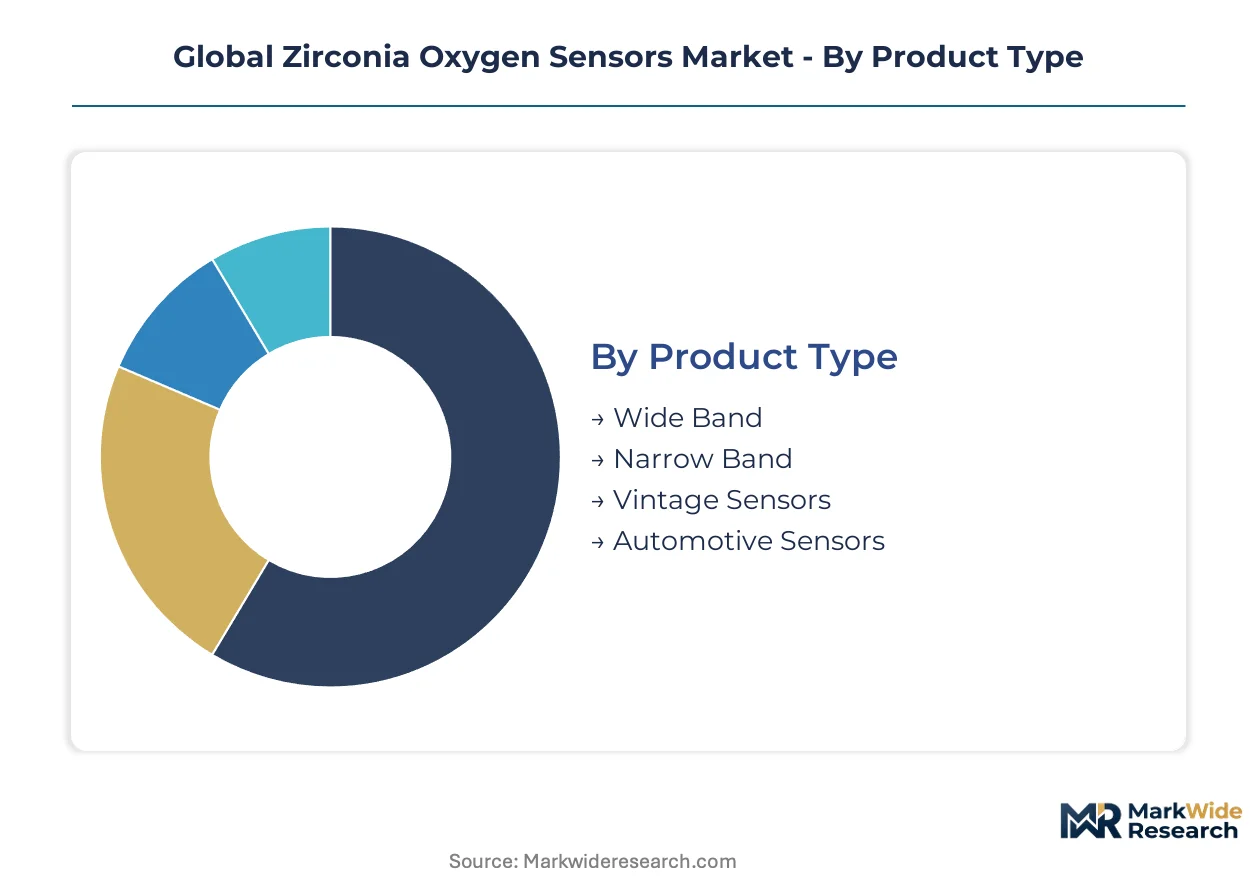
Zirconia oxygen sensor procurement patterns diverge sharply across application contexts, with emission regulation stringency and combustion architecture complexity determining technology selection. Understanding segment boundaries clarifies where wide-band architectures displace legacy narrow-band installations and where electrochemical sensing retains structural advantages over semiconductor alternatives.
Product Type:
Mature narrow-band platforms coexist with emerging wide-band architectures across divergent regulatory timelines and vehicle fleet vintages.
- Wide Band:These sensors employ dual-cell design with oxygen pump and Nernst cell circuitry to measure lambda values from 0.7 to 4.0 across lean-burn and stoichiometric combustion regimes. Gasoline direct-injection platforms in Germany and China are driving procurement concentration as Euro 7 and China VI-B standards mandate continuous air-fuel ratio monitoring beyond binary rich-lean detection.
- Narrow Band:Binary switching sensors generate voltage step-change at stoichiometric point for conventional port-fuel-injection engines. Cost-constrained aftermarket replacement demand in legacy vehicle fleets sustains volume, though platform development investment has shifted decisively toward wide-band architectures.
- Vintage Sensors:First-generation thimble designs with unheated or single-heater elements serve classic vehicle restoration and developing market retrofit applications where regulatory compliance lags Euro 7-equivalent standards.
- Automotive Sensors:Application-specific packaging with integrated connectors and protective shields dominates OEM supply chains, particularly in Toyota City's manufacturing cluster where module-level procurement concentrates.
Narrow-band architectures handle the majority of aftermarket throughput; wide-band sensors are expanding most quickly on share as Euro 7 and China VI-B implementation accelerates.
Technology:
Cost tier differentiation separates electrochemical dominance in precision applications from semiconductor encroachment in price-sensitive segments.
- Electrochemical:Yttria-stabilized zirconium dioxide solid electrolytes generate voltage proportional to oxygen partial pressure differentials across 300°C to 900°C operating windows. Automotive OEMs in Japan and Germany specify this technology for closed-loop fuel injection control where drift rates below 1% annually are mandatory.
- Optical:Fluorescence-quenching and laser absorption spectroscopy methods enable non-contact measurement in high-particulate exhaust streams. Aerospace auxiliary power unit monitoring in the United States favors optical architectures where electrochemical cell contamination risks are prohibitive.
- Thermal:Resistive and thermoelectric principles measure oxygen concentration through thermal conductivity differentials. Industrial boiler combustion optimization in Germany deploys thermal sensors for coarse excess-air monitoring where precision requirements permit broader tolerance bands.
- Semiconductor:Titanium dioxide and gallium oxide metal-oxide sensing elements offer lower unit costs but reduced accuracy and temperature stability. Aftermarket replacement channels in cost-sensitive regions are adopting semiconductor alternatives for non-critical diagnostic applications.
Electrochemical platforms command premium pricing in automotive-integrated designs; semiconductor alternatives are gaining share fastest in aftermarket replacement segments.
End User:
Application-specific performance requirements fragment demand across mobility sectors with divergent certification protocols and operating environment severity.
- Automotive:Passenger vehicle and commercial truck exhaust systems represent the dominant demand concentration, with wide-band sensors mandatory for gasoline direct-injection and lean-burn diesel platforms. EPA, Euro 7, and China VI-B tailpipe standards collectively tighten accuracy and durability specifications.
- Aerospace:Turbine engine and auxiliary power unit monitoring requires sensors surviving extreme thermal cycling and vibration profiles. Optical and electrochemical architectures compete in this segment where FAA and EASA certification timelines extend development cycles.
- Marine:Diesel and dual-fuel marine engine combustion control operates in high-sulfur fuel environments that accelerate sensor degradation. IMO emission regulations for shipping are expanding oxygen sensor deployment in two-stroke and four-stroke marine powertrains.
- Industrial:Process heating, power generation, and incineration applications demand robust sensors for continuous emissions monitoring systems. Fixed installations with heated sampling lines predominate where regulatory compliance requires documented measurement uncertainty.
Automotive applications absorb the majority of unit volume; aerospace specifications are climbing fastest on value per sensor as certification complexity increases.
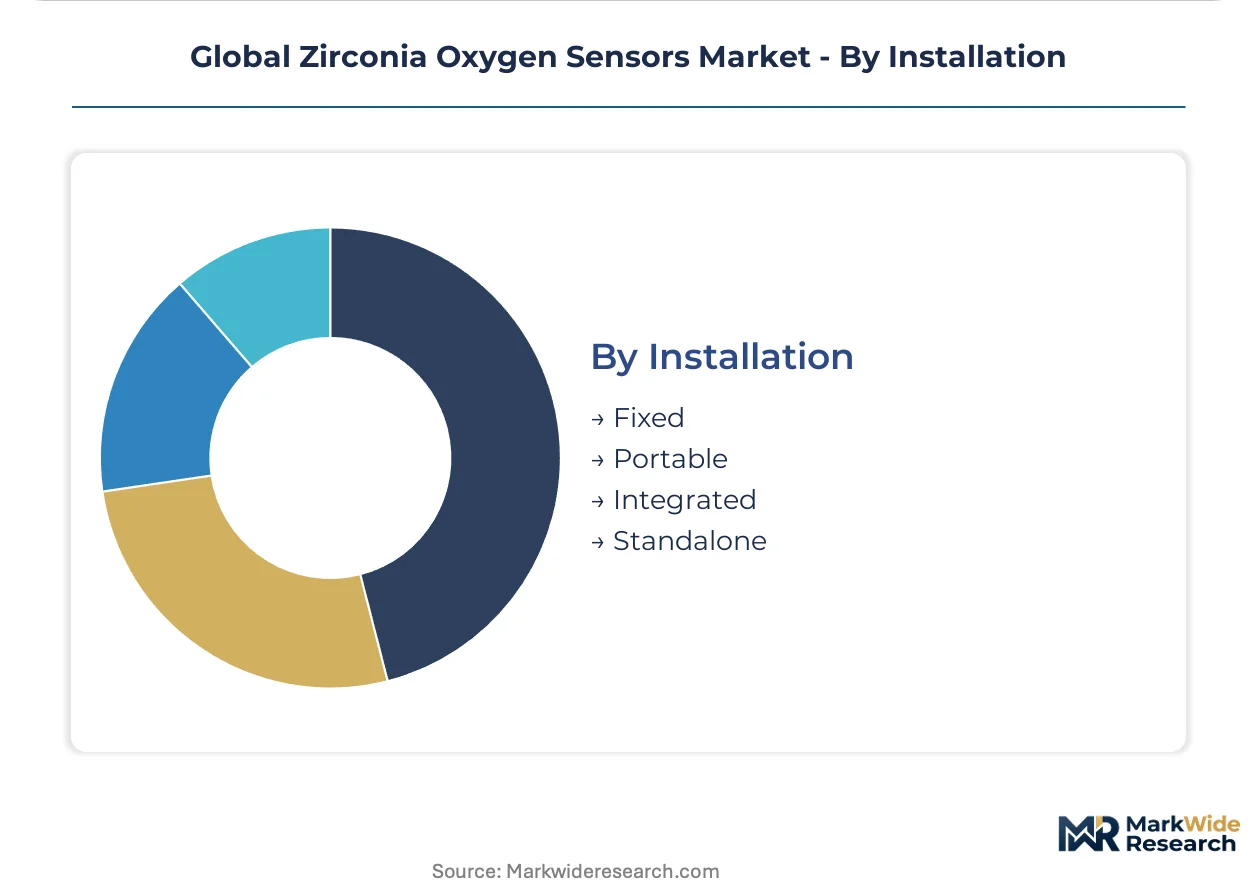
Installation:
Supply concentration in module assembly favors integrated configurations over discrete standalone components in new platform development.
- Fixed:Permanent mounting in exhaust manifolds or downpipe locations with dedicated wiring harnesses dominates OEM production. Shanghai's Pudong industrial zone manufacturing clusters source fixed sensors through single-source module contracts.
- Portable:Handheld diagnostic equipment and temporary emissions testing applications require quick-connect interfaces and battery-powered heater control. Service bay equipment suppliers in Germany and Japan specify portable architectures for workshop troubleshooting.
- Integrated:Multi-parameter modules combining oxygen sensing with temperature and pressure compensation are displacing discrete components. Tier-1 exhaust system suppliers in Toyota City and Stuttgart manufacturing clusters consolidate procurement around integrated designs.
- Standalone:Single-function sensors with analog voltage output persist in aftermarket replacement and legacy system retrofit where controller compatibility constraints prohibit digital module adoption.
Fixed installations handle the majority of production volume; integrated modules are gaining share fastest as OEM procurement consolidates around single-source supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement concentrates in manufacturing clusters where emission regulations tighten fastest. Wide-band sensor demand tracks gasoline direct-injection platform deployment and Euro 7, China VI-B compliance timelines across Germany, China, Japan, India, and the United States.
China
Shanghai's Pudong industrial zone anchors domestic sensor module assembly for BYD, SAIC, and Geely. MEE enforcement of China VI-B provisions mandates extended durability testing for high-sulfur fuel environments. Local ceramic substrate producers are scaling yttria-stabilized zirconium dioxide capacity to reduce import dependence.
Germany
Stuttgart and Munich manufacturing corridors supply Volkswagen, BMW, and Mercedes-Benz with integrated exhaust modules. EMA review of Euro 7 tailpipe standards is forcing narrow-band to wide-band platform migration. Bosch maintains backward integration into ceramic substrate production near Reutlingen.
Japan
Toyota City's supplier ecosystem concentrates procurement around single-source module contracts for hybrid powertrains. METI fuel-efficiency benchmarks accelerate wide-band sensor deployment in gasoline-electric architectures. NGK-NTK leverages exhaust system OEM relationships across domestic and European automaker supply chains.
United States
Michigan and Ohio automotive corridors source sensors for Ford, GM, and Stellantis powertrain programs. EPA tailpipe standards and California Air Resources Board zero-emission mandates shape accuracy requirements. Aftermarket replacement channels in the Southeast face semiconductor-based substitution pressure.
India
Tamil Nadu and Maharashtra manufacturing clusters serve Maruti Suzuki, Hyundai, and Tata Motors. PLI scheme incentives for advanced automotive electronics attract sensor module assembly investment. BIS certification timelines for oxygen sensor accuracy lag Euro 7 implementation by approximately 24 months.
Global Zirconia Oxygen Sensors Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. Consolidation around integrated module suppliers is displacing discrete component vendors in OEM supply chains. Three archetypes dominate: ceramic substrate-integrated manufacturers, exhaust system module integrators, and aftermarket replacement specialists. Strategic moves center on backward integration into solid-electrolyte production and geographic expansion into China VI-B compliance markets.
Within the integrated manufacturing tier, Bosch and NGK-NTK exemplify substrate-integrated production models, while Continental occupies a position among module-focused system suppliers. Delphi and Denso represent diversified automotive electronics conglomerates with sensor portfolio breadth. SST Sensing and Cubic Sensor and Instrument sit within the specialist tier serving non-automotive industrial applications. Honeywell and Fujikura anchor diversified industrial technology positions where oxygen sensing represents one vertical among several measurement domains.
| Leading Market Players |
|---|
| Delphi |
| SST Sensing |
| NGK-NTK |
| Continental |
| Fujikura |
| Bosch |
| Honeywell |
| Cubic Sensor and Instrument |
| Denso |
| Others |
Supply Flow & Price Mechanics
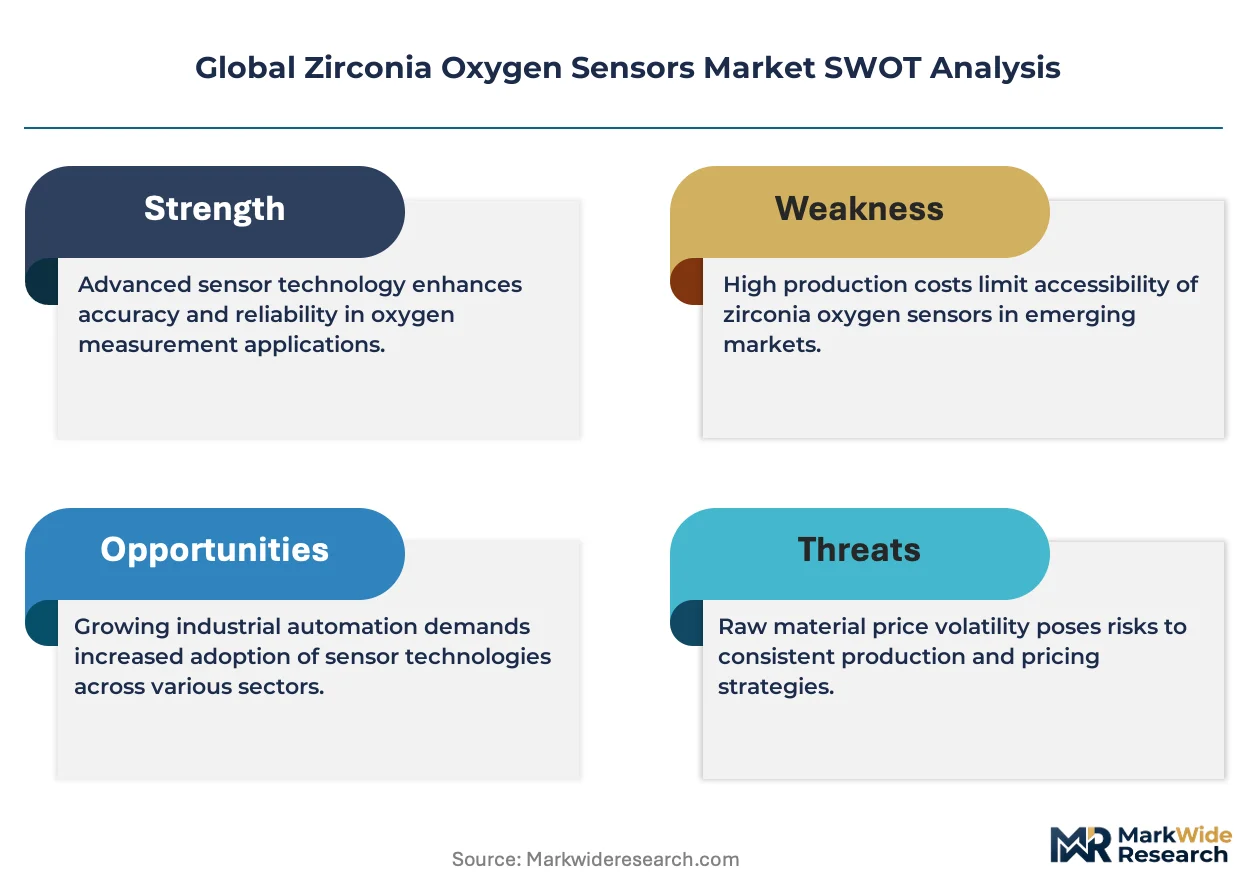
Chinese yttrium oxide processing concentration determines margin distribution across ceramic substrate tiers, with downstream sensor module assemblers capturing value through ISO 26262 certification premiums and captive heater control algorithm development.
Pricing Analysis
Cost-plus contracts with yttrium oxide London Metal Exchange indexation dominate procurement between ceramic substrate producers and integrated module suppliers. Pricing stratifies across automotive-grade electrochemical platforms, aftermarket semiconductor alternatives, and industrial thermal sensors based on drift rate specifications and EPA/Euro 7 certification tier. Cost compression in narrow-band aftermarket channels is intensifying because semiconductor-based titanium dioxide substitutes erode unit economics. Tier 1 automotive OEMs exhibit lowest price sensitivity due to single-source module mandates, while independent aftermarket distributors face acute margin pressure.
Supply Chain Analysis
Export controls on advanced ceramic sintering equipment limit technology transfer to Indian and Southeast Asian manufacturing aspirants, constraining supply expansion outside established production corridors. Solid-electrolyte manufacturing draws from Chinese rare earth processing, Japanese yttria-stabilization expertise, and German precision sintering equipment. Single-source vulnerability concentrates in Shanghai's Pudong industrial zone ceramic substrate foundries. Distribution runs through Tier 1 exhaust system integrators in Toyota City and Stuttgart, with aftermarket channels served by independent distributors in Michigan and Ohio automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wide-band architecture fragmentation creates specialist opportunities as gasoline direct-injection platform proliferation generates application-specific sensor variants beyond standardized narrow-band replacements.
For Market Incumbents: Entrench through backward integration into yttria-stabilized zirconium dioxide ceramic substrate production and captive digital heater control algorithm development. Semiconductor-based aftermarket substitutes threaten narrow-band volume; defend through Euro 7 pre-certification partnerships with Stuttgart and Shanghai OEM procurement offices. Priority lever: ISO 26262 functional safety validation redundancy. For New Entrants and Emerging Players: India's PLI scheme automotive electronics corridors represent the most penetrable entry point for sensor module assembly investment. Marine diesel high-sulfur fuel environment specifications offer second white-space target with IMO compliance tailwinds. Go-to-market angle: dual China VI-B and Euro 7 certification documentation as competitive discriminator against single-standard incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward ceramic substrate-integrated manufacturers with captive rare earth supply arrangements and established automotive OEM module contracts. Long-term viability hinges on China VI-B enforcement timeline synchronization with Euro 7 implementation. Signal to watch: divergence between MEE durability testing protocols and EMA review cycles as platform standardization friction indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Production | Bosch's Reutlingen facility demonstrates margin capture through captive yttria-stabilized zirconium dioxide supply. |
| Wide-Band Architecture Platform Standardization | NGK-NTK's Toyota City contracts show how single-source module procurement consolidates exhaust system supply chains. |
| Dual Certification Documentation Investment | Aftermarket suppliers serving Shanghai's Pudong zone restructure compliance frameworks for China VI-B and Euro 7 overlap. |
| Digital Heater Control Algorithm Development | Continental's integrated sensor modules compress calibration cycle times through digitized lambda signal processing. |
| Geographic Manufacturing Footprint Expansion | India's PLI scheme incentives attract sensor module assembly investment from Tamil Nadu automotive clusters. |
Methodological Framework
A spread of perspectives from Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distribution channel heads, and ceramic substrate manufacturing technicians converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with exhaust system integrators in Toyota City and Stuttgart with validation against EPA certification filings, EMA Euro 7 draft submissions, MEE China VI-B enforcement documentation, and vehicle production databases. Bottom-up unit demand estimates triangulated against top-down automotive sensor content-per-vehicle analysis.
Demand-supply balance modeling across the projection horizon incorporated vehicle class stratification, propulsion architecture differentiation, regional emission regulation stringency tiers, and sensor technology substitution elasticity. CAGRs derived from segment-level unit growth rate reconciliation with value-per-sensor trajectory analysis. Industry-specific inputs included gasoline direct-injection platform deployment schedules and hybrid powertrain sensor redundancy requirements.
Practitioners should monitor Euro 7 EMA review timeline acceleration, MEE China VI-B enforcement schedule shifts, and semiconductor-based aftermarket substitution rates for early signals of forecast deviation. Forecasts reflect assumptions about ceramic substrate capacity expansion trajectories and rare earth supply concentration stability. Material shifts in yttrium oxide price volatility regimes or dual carbon policy implementation in Chinese processing facilities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
Diatomite Market
Ceramics
Global Ceramic Coating Market
Ceramics
Ceramic Frit Glass Market
Ceramics
Earthenware Market
Ceramics
Ceramic Solid End Mills Market
Ceramics
Heat-Resistant Ceramic Tableware Market
Ceramics
Ceramic Substrate Market
Ceramics
Asia-Pacific Activated Alumina Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
Titanates Market
Ceramics
Glass Ceramics Market
Ceramics
Titanium Carbide Market
Ceramics
Global Functional Ceramics Market
Ceramics
Carbon-Ceramic Discs Market