
 Solid-Ion Conductors Market | 2026-2036
Solid-Ion Conductors Market Size, Share, and Industry Trends Forecast 2026-2036
Solid-Ion Conductors Market Analytics
Modular cell packaging is broadening buyer choice across solid-ion conductor supply chains. QuantumScape leverages its proprietary ceramic separator architecture to target automotive OEM direct supply relationships. Solid Power anchors its position through backward integration into sulfide electrolyte manufacturing. BrightVolt specializes in thin-film polymer formats for wearable and medical micro-battery applications.
Solid-ion conductors are crystalline or amorphous materials that permit ionic transport without liquid electrolyte, typically achieving conductivities above 10⁻⁴ S/cm at room temperature through optimized lattice structures or grain-boundary engineering. Their primary commercial purpose is eliminating flammable organic solvents from electrochemical cells while enabling lithium-metal anode compatibility. Sulfide conductors currently lead in ionic conductivity metrics but face manufacturing challenges around moisture sensitivity and processing infrastructure. Oxide conductors occupy a more mature position in ceramic fuel cell membranes where thermal stability outweighs room-temperature performance requirements. Polymer electrolytes compete on roll-to-roll processability, with composite formulations blending ceramic fillers to bridge the conductivity gap.
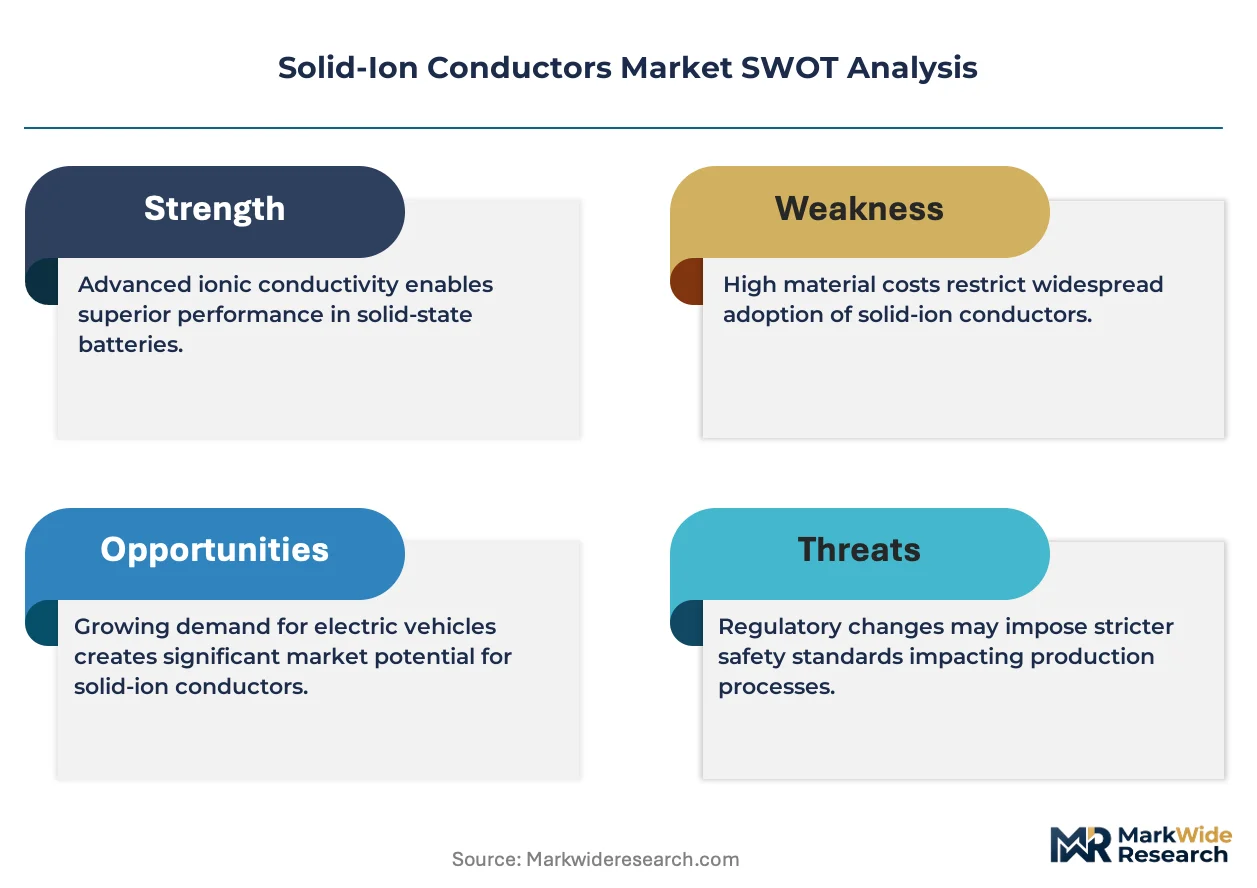
The US Inflation Reduction Act and EPA vehicle emissions standards are tightening the regulatory frame for liquid-electrolyte lithium-ion systems, indirectly accelerating solid-state qualification timelines. REACH and the EU Battery Regulation from ECHA are imposing traceability and recyclability mandates that favor simplified solid-cell architectures with fewer volatile components. Stakeholders must monitor electrolyte-air stability benchmarks and dry-room capital requirements as the gap between laboratory performance and gigafactory yield becomes the decisive commercial filter.
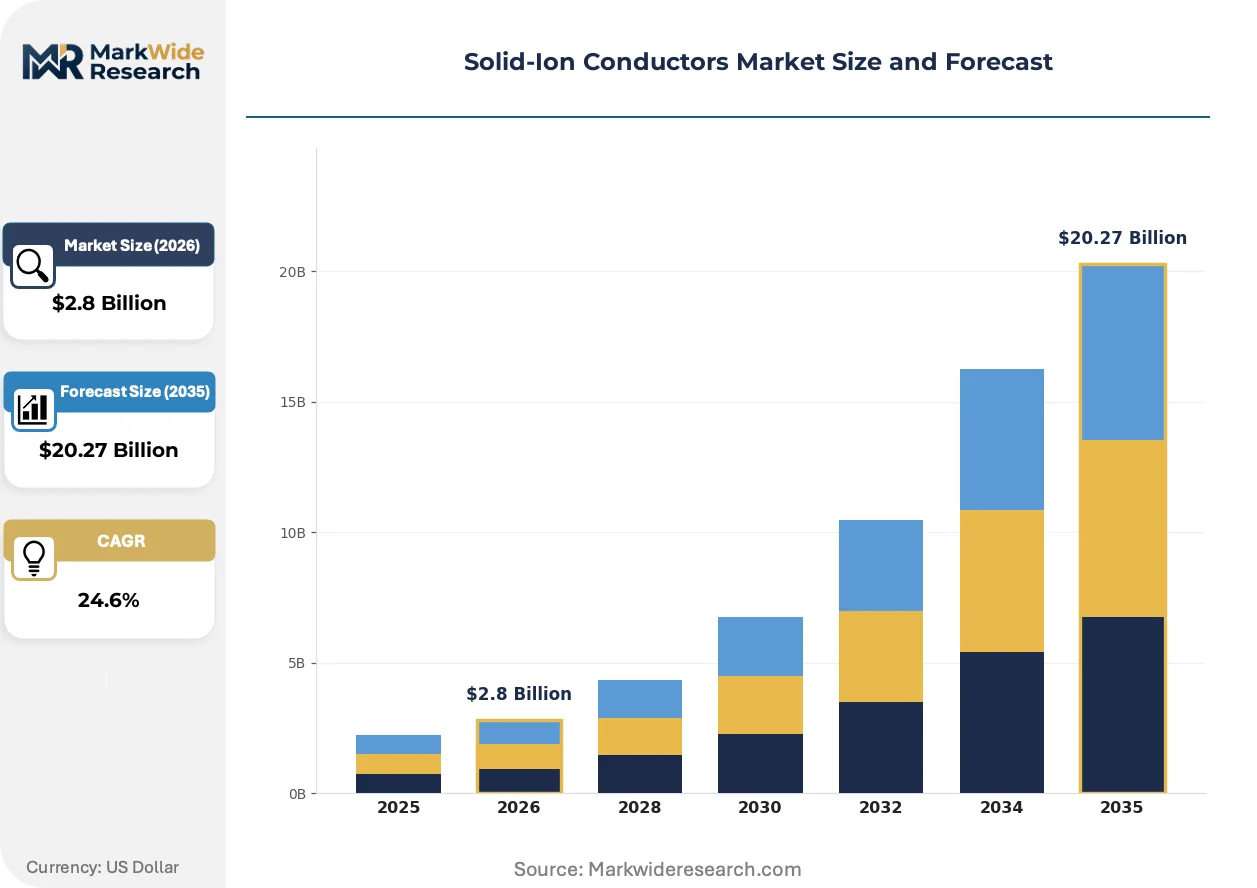
Market Dynamics
The transition from liquid to solid electrolyte architectures is compressing qualification timelines as automotive OEMs demand lithium-metal compatibility for next-generation battery packs. This structural shift is forcing electrolyte suppliers to reconfigure manufacturing footprints around moisture-free processing infrastructure.
Growth Catalysts
- US Inflation Reduction Act clean energy credits:Domestic production incentives are redirecting capital toward sulfide and oxide electrolyte gigafactories in Michigan and Nevada.
- Electric vehicle platform electrification:Automotive OEMs are accelerating solid-state procurement as lithium-metal anodes achieve cycle-life thresholds for series production.
- South Korean pilot line scaling:Samsung SDI and SK On are expanding sulfide-based cell capacity, concentrating supply chain know-how in Gyeonggi-do and Seosan clusters.
Market Restraints
- Argon-atmosphere dry-room capex:Sulfide electrolyte production requires sub-ppm moisture environments, locking out mid-scale entrants without billion-dollar facility commitments.
- Japanese ceramic powder supply concentration:High-purity lithium sulfide precursors route through Osaka and Nagoya trading houses, creating single-source vulnerability.
- Oxide sintering temperature limits:Garnet-structured conductors require 1000°C+ firing cycles that constrain throughput and energy efficiency versus polymer alternatives.
Strategic Opportunities
- Thin-film polymer medical micro-batteries:Wearable glucose monitors and implantable cardiac devices are absorbing solid-polymer formats that liquid electrolytes cannot safely miniaturize.
- EU Battery Regulation recyclability mandates:Simplified solid-cell architectures with fewer volatile components align with ECHA traceability requirements for passport-compliant supply chains.
- All-solid-state aviation auxiliary power:FAA thermal-runway safety guidelines are creating entry paths for oxide electrolytes in commercial aircraft battery systems.
Industry Challenges
- Dendrite suppression engineering talent:Lithium-metal interface stabilization requires electrochemists with rare combinations of ceramic processing and solid-state physics expertise.
- Gigafactory yield gap closure:Laboratory-scale ionic conductivities above 10⁻³ S/cm collapse in pilot lines due to grain-boundary contamination and pressing uniformity failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid-Ion Conductors Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Electrolyte, Oxide Conductors, Sulfide Conductors, Composite Electrolytes Application: Battery Systems, Fuel Cells, Supercapacitors, Sensors End User: Automotive, Consumer Electronics, Energy Storage, Industrial Technology: Solid-State Technology, Nanocomposite Technology, Hybrid Systems, Membrane Technology |
| Companies Covered | Cymbet Corporation, BrightVolt, Excellatron Solid State, Polyplus Battery, Johnson Battery Technologies, Ilika, QuantumScape, Solid Power, Ampcera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid-Ion Conductors Market Evolving Landscape
Process innovation is overtaking materials discovery as the primary competitive lever, with manufacturing scalability now determining which electrolyte chemistries reach automotive qualification. Dry-electrode coating and continuous sintering methods are compressing the gap between research-cell performance and production-line consistency.
Composite polymer-ceramic electrolytes are absorbing the flexibility advantages of roll-to-roll processing while grafting conductivity gains from oxide filler loadings. EV battery pack engineers at Korean and German OEMs are qualifying these formats for 2027 platform integration. The hybrid approach is absorbing market share from pure sulfide development programs that remain trapped in dry-room bottlenecks.
REACH substance restrictions and the EU Battery Regulation are tightening the regulatory frame for liquid-electrolyte lithium-ion systems, indirectly accelerating solid-state qualification timelines. ECHA mandates on PFAS and fluorinated solvents are eliminating incumbent electrolyte formulations from 2027 production windows. European cell manufacturers are responding by fast-tracking sulfide pilot lines to secure chemistry-agnostic platform positions.
Automotive procurement teams are consolidating supplier relationships around vertically integrated electrolyte-to-cell providers, displacing the multi-tier component sourcing that characterized liquid-lithium-ion supply chains. Tier 1 battery makers are absorbing sulfide powder production capabilities in-house to protect intellectual property around interface engineering. This concentration is most visible in South Korea, where Samsung SDI and SK On have terminated external electrolyte development partnerships in favor of captive sulfide synthesis operations.
Solid-Ion Conductors Market Segmentation
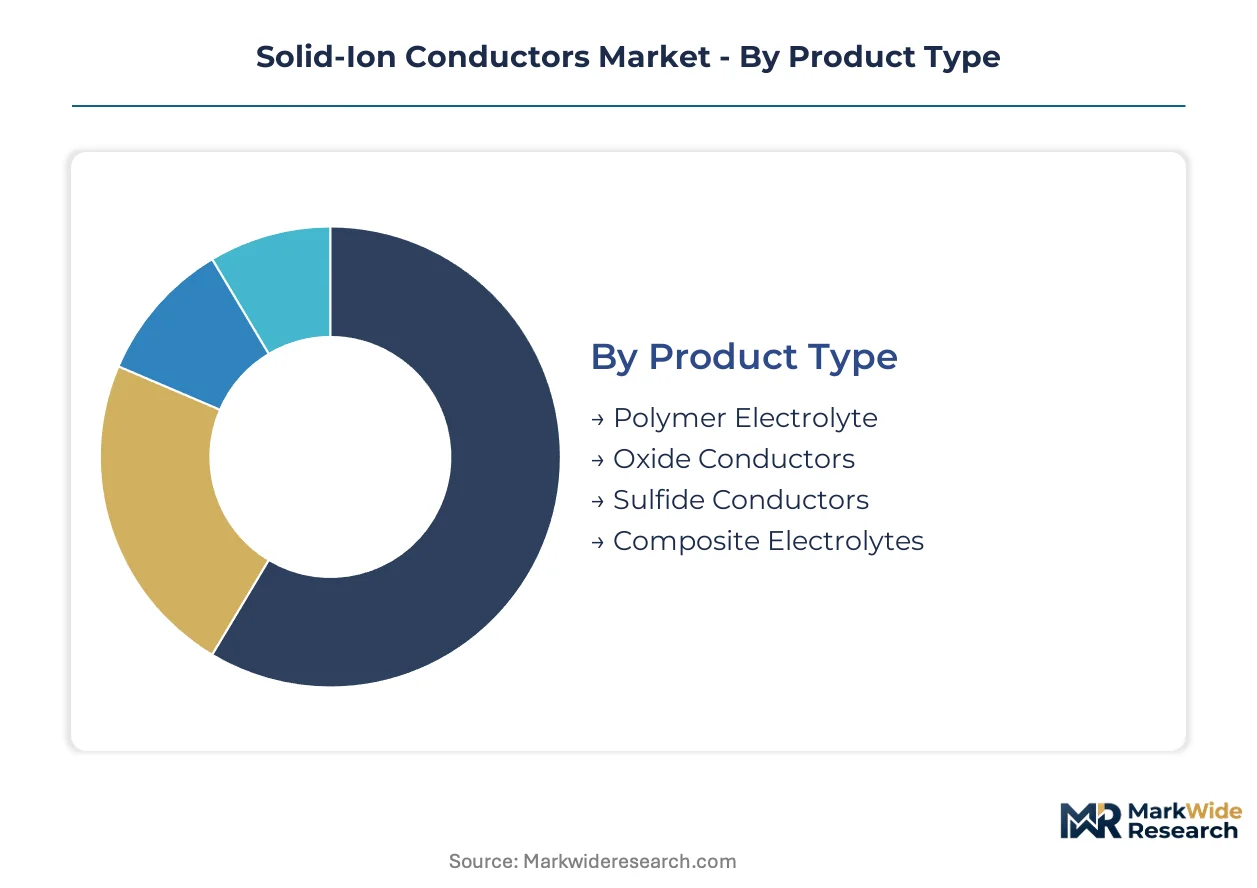
Segmentation in solid-ion conductors reveals how capital deployment, technical risk, and end-use requirements fragment the competitive landscape. Each dimension exposes different barriers to entry and margin structures.
Product Type:
Capital intensity varies sharply across chemistries, with sulfide processing demanding billion-dollar dry-room infrastructure while polymer lines scale at fractionally lower thresholds.
- Sulfide Conductors:Lithium sulfide-based crystalline structures achieve ionic conductivities above 10⁻³ S/cm through optimized grain-boundary engineering. Samsung SDI and SK On in South Korea are concentrating procurement around sulfide stacks for automotive qualification, though argon-atmosphere processing constraints lock out mid-scale competitors.
- Oxide Conductors:Garnet-structured ceramics such as LLZO deliver thermal stability exceeding 1000°C firing cycles. Demand concentrates in solid oxide fuel cell membranes where Japanese trading houses in Osaka and Nagoya control precursor supply, creating single-source vulnerability for non-integrated buyers.
- Polymer Electrolyte:Roll-to-roll processable formats compete on manufacturing flexibility rather than peak conductivity.
- Composite Electrolytes:Hybrid polymer-ceramic formulations graft oxide filler loadings into flexible matrices.
Sulfide conductors absorb the bulk of installed capacity; composite electrolytes are expanding most quickly.
Application:
Application segmentation tracks how performance requirements reshape qualification timelines and customer concentration.
- Battery Systems:Solid-state lithium-metal cells eliminate flammable organic solvents while enabling energy density gains. US Inflation Reduction Act credits are redirecting capital toward Michigan and Nevada gigafactories as OEMs accelerate procurement for platform electrification.
- Fuel Cells:Oxide conductors serve as ceramic electrolyte membranes in high-temperature systems. Japanese and German industrial gas suppliers dominate membrane supply relationships, with METI-funded consortia anchoring technical development in Tokyo-Osaka corridors.
- Supercapacitors:Ion-conductive separators bridge power density and cycle life requirements.
- Sensors:Miniaturized solid-electrolyte formats enable implantable and wearable device architectures.
Battery systems command the deepest capital commitments; sensors are climbing the fastest.
End User:
End-user segmentation exposes how volume scale and certification burden vary across customer categories.
- Automotive:OEM qualification cycles span 4-7 years with lithium-metal interface stabilization as the critical technical gate. Korean and German manufacturers are consolidating supplier relationships around vertically integrated electrolyte-to-cell providers, displacing multi-tier sourcing.
- Energy Storage:Grid-scale installations prioritize cycle life and thermal safety over energy density. ECHA traceability mandates under EU Battery Regulation favor simplified solid-cell architectures with fewer volatile components.
- Consumer Electronics:Thin-film polymer formats address wearable and medical micro-battery requirements.
- Industrial:Process control and automation systems absorb ceramic sensor formats.
Automotive absorbs the bulk of R&D expenditure; energy storage is gaining share fastest.
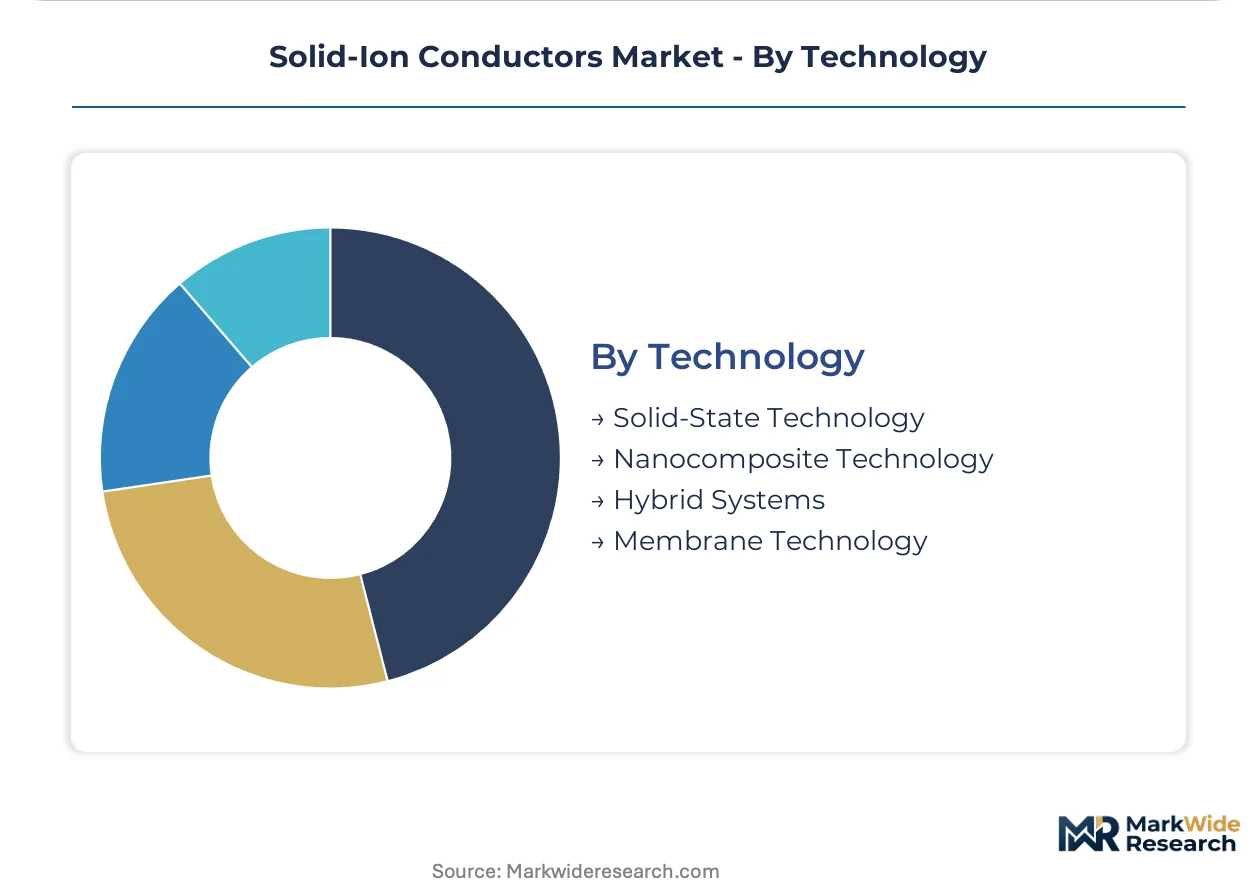
Technology:
Technology segmentation tracks how manufacturing methodology determines scalability and intellectual property protection.
- Solid-State Technology:All-solid architectures eliminate liquid electrolyte entirely. FAA thermal-runway safety guidelines are creating entry paths for oxide electrolytes in commercial aircraft auxiliary power systems, with qualification timelines compressing as dry-electrode coating methods mature.
- Nanocomposite Technology:Ceramic filler dispersion within polymer matrices bridges conductivity and processability. Korean cell manufacturers are qualifying these formats for platform integration as pure sulfide programs remain trapped in dry-room bottlenecks.
- Hybrid Systems:Layered or gradient architectures combine multiple conductor types.
- Membrane Technology:Thin-film deposition methods enable micro-scale device integration.
Solid-state technology anchors the deepest patent portfolios; nanocomposite approaches are scaling most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in East Asian manufacturing corridors while consumption demand concentrates in North American and European automotive assembly zones. This geographic split shapes capital deployment patterns across the solid-ion conductor supply chain. Raw material refining and electrolyte synthesis concentrate where chemical processing infrastructure and battery cell manufacturing overlap.
United States
Automotive OEMs in Michigan and Nevada are accelerating solid-state battery procurement for platform electrification. The Inflation Reduction Act's clean energy manufacturing credits redirect capital toward domestic sulfide and oxide electrolyte production. Detroit-area engineering clusters absorb the bulk of pilot line qualification activity as lithium-metal anode compatibility testing compresses timelines.
South Korea
Samsung SDI and SK On are scaling sulfide-based cell capacity in Gyeonggi-do and Seosan industrial corridors. The country's national industrial regulator under METI-aligned frameworks supports captive electrolyte synthesis operations. Korean cell manufacturers are terminating external partnerships in favor of in-house sulfide powder production to protect interface engineering intellectual property.
Japan
Osaka and Nagoya trading houses control high-purity lithium sulfide precursor supply for regional battery manufacturers. METI-funded consortia anchor technical development in Tokyo-Osaka corridors for garnet-structured oxide conductors. Japanese ceramic powder suppliers face concentration risk as non-integrated buyers seek alternative sourcing pathways.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria are consolidating supplier relationships around vertically integrated electrolyte-to-cell providers. ECHA traceability mandates under EU Battery Regulation favor simplified solid-cell architectures with fewer volatile components. Stuttgart-area engineering centers qualify composite polymer-ceramic formats for 2027 platform integration.
China
Domestic cell manufacturers are expanding oxide conductor capacity for solid-state programs targeting aviation auxiliary power systems. The country's dual carbon goals under MEE frameworks accelerate dry-electrode coating method deployment. Yangtze River Delta chemical processing clusters absorb capital for moisture-free sulfide electrolyte infrastructure.
Solid-Ion Conductors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across solid-ion conductor supply tiers. The vendor base organizes around three strategic archetypes: vertically integrated battery cell manufacturers, dedicated electrolyte material suppliers, and thin-film deposition equipment providers. Consolidation pressure intensifies as automotive OEMs demand direct supplier relationships rather than multi-tier sourcing. Capacity expansion and backward integration into sulfide powder production represent the dominant competitive moves.
Among North American specialists, QuantumScape and Solid Power exemplify contrasting strategic positions within the solid-state battery ecosystem. Cymbet Corporation and BrightVolt occupy positions in the thin-film polymer segment for wearable and medical micro-battery applications. Johnson Battery Technologies represents the diversified industrial conglomerate archetype with cross-sector energy storage interests. These companies anchor different supply chain tiers without overlapping core technology positioning.
| Leading Market Players |
|---|
| Cymbet Corporation |
| BrightVolt |
| Excellatron Solid State |
| Polyplus Battery |
| Johnson Battery Technologies |
| Ilika |
| QuantumScape |
| Solid Power |
| Ampcera |
| Others |
Value Network & Pricing Analysis
Argon-atmosphere dry-room capex flows through sulfide electrolyte pricing tiers as sub-ppm moisture processing requirements stratify procurement costs across automotive OEMs, mid-scale cell manufacturers, and research-scale buyers. Lithium sulfide precursor purity grades from Osaka and Nagoya trading houses anchor input cost structures before volume scale and certification level reshape final contract terms downstream.
Pricing Analysis
Cost-down pressure on sulfide electrolyte tiers accelerates because Korean cell manufacturers are consolidating captive powder production and terminating external supply relationships. Three-tier pricing structure across premium, standard, and economy levels separates automotive qualification-grade material from industrial fuel cell membranes and research-scale batches. Price differentiation rests on ISO/UL certification tier and volume scale, with medical micro-battery polymer formats commanding stability premiums. Automotive OEMs exhibit lowest price sensitivity due to platform electrification timelines, while research institutions face acute budget constraints.
Supply Chain Analysis
Refurbishment flows for solid-state cell manufacturing equipment remain nascent as dry-room infrastructure achieves decade-long depreciation cycles without secondary market liquidity. Geographic supply concentration centers on South Korea, Japan, and China for sulfide precursor synthesis and oxide ceramic processing. Raw material dependencies draw from high-purity lithium sulfide, garnet-structured LLZO powders, and polymer electrolyte resins. Single-source vulnerability pervades Japanese ceramic powder trading houses in Osaka and Nagoya corridors. Distribution runs through vertically integrated battery cell manufacturers rather than multi-tier component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argon-atmosphere dry-room infrastructure scarcity props pricing power for incumbent sulfide electrolyte producers as billion-dollar facility commitments lock out mid-scale competition. Capacity bottlenecks at Japanese precursor suppliers reinforce supply concentration.
For Market Incumbents: Hedge against composite polymer-ceramic substitution by accelerating in-house sulfide powder production in Gyeonggi-do and Seosan clusters. Secure lithium sulfide precursor offtake agreements with Osaka trading houses before non-integrated buyers diversify sourcing. Backward integration into ceramic separator architecture protects intellectual property around lithium-metal interface engineering. For New Entrants and Emerging Players: The gap between premium automotive qualification-grade sulfide electrolytes and economy-tier research-scale materials creates white-space entry points. Target thin-film polymer medical micro-battery applications where BrightVolt and Cymbet Corporation occupy specialist positions with limited scale. Pursue direct supply relationships with wearable glucose monitor and implantable cardiac device manufacturers bypassing automotive qualification barriers. For Investors and Strategic Acquirers: Samsung SDI and SK On terminating external electrolyte partnerships is the leading indicator that vertical integration is displacing multi-tier sourcing across the solid-state battery ecosystem. Long-term viability favors electrolyte-to-cell providers with captive sulfide synthesis and dry-room operational expertise. Monitor FAA thermal-runway safety guideline adoption for oxide electrolytes in commercial aviation auxiliary power as inflection signal for non-automotive demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Sulfide Powder Production | Korean cell manufacturers protect interface engineering IP through in-house synthesis operations in Gyeonggi-do. |
| Dry-Electrode Coating Scale-Up | Continuous sintering methods compress laboratory-to-gigafactory yield gaps for automotive qualification. |
| Composite Polymer-Ceramic Qualification | German OEMs in Stuttgart-area engineering centers fast-track hybrid formats for 2027 platform integration. |
| Medical Micro-Battery Specialization | Thin-film polymer formats address wearable and implantable device requirements liquid electrolytes cannot safely miniaturize. |
| Aviation Auxiliary Power Certification | FAA thermal-runway safety guidelines create entry paths for oxide electrolytes in commercial aircraft battery systems. |
Research Methodology
Independent corroboration across solid-state battery engineering directors, automotive OEM platform procurement leads, and ceramic powder trading house account managers underwrites the qualitative findings. Primary interviews with dry-room infrastructure contractors, lithium sulfide precursor suppliers, and ECHA regulatory affairs specialists combined with secondary validation from SEC filings, METI-funded consortium disclosures, and EU Battery Regulation implementation guidance. Customs data on lithium sulfide trade flows, FAA certification dockets for aviation battery systems, and hospital procurement databases for implantable medical devices anchored bottom-up and top-down triangulation.
Comparable-period anchoring to historical solid-state battery pilot line deployment schedules structured the forecast window across the analysis window. Segmentation dimensions modeled include conductor chemistry type, application category, end-user industry, and manufacturing technology approach. CAGRs were derived from electrolyte production capacity buildout trajectories, automotive platform electrification timelines, and regulatory qualification compression effects. Dry-room capital expenditure cycles and lithium-metal anode cycle-life thresholds served as industry-specific forecast inputs.
Inputs from Korean industrial regulator filings and Japanese METI consortium reports were available through the study window; gaps in Chinese domestic aviation battery certification progress introduce uncertainty bands around oxide conductor demand projections. Forecasts reflect documented assumptions on sulfide electrolyte moisture sensitivity resolution and composite polymer-ceramic conductivity bridging. Practitioners should monitor FAA guideline finalization and ECHA PFAS restriction implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
Global Magnesium Silicate Market
Ceramics
Refractories Market
Ceramics
North America Barium Carbonate Market
Ceramics
Controlled Pore Metal Oxide Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Colloidal Alumina Market
Ceramics
Automotive Ceramics Market
Ceramics
2N High Purity Alumina Market
Ceramics
Ceramic Frit Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
India Kaolin Market
Ceramics
Titanates Market
Ceramics
Activated Alumina Market
Ceramics
South Korea Ceramic Tiles Market