
 Reinforcement Materials Market | 2026-2036
Reinforcement Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Reinforcement Materials Market Intelligence
Direct procurement channels between raw fiber producers and tier-one automotive suppliers is reshaping traditional distributor roles in the reinforcement materials supply chain. Owens Corning leverages its integrated glass melting and fiber forming operations to secure cost positions in wind blade reinforcement. Toray Industries Inc anchors its competitive stance through carbon fiber leadership in aerospace primary structures. DuPont de Nemours Inc differentiates via aramid fiber technology for ballistic and industrial reinforcement applications.
Reinforcement materials encompass fibers, metals, and composite additives engineered to improve tensile strength, stiffness, and dimensional stability in host matrices such as concrete, thermoset resins, or thermoplastics. Glass fiber dominates by volume due to its cost-performance ratio in construction and marine hull laminates, while carbon fiber commands premium positioning in aerospace structural components where specific strength requirements justify material costs. Steel reinforcement maintains mature, high-volume demand in concrete construction across developing infrastructure markets. Fiber-reinforced plastic forms are gaining specification share in automotive underbody panels seeking mass reduction without sacrificing crash performance.
The EU Green Deal and REACH chemical registration frameworks are tightening embodied carbon and substance disclosure requirements for construction materials imported into Europe. EPA industrial emissions standards and OSHA silica exposure limits in the United States are elevating compliance costs for glass fiber and mineral wool manufacturing facilities. China's GB standards and dual carbon goals are mandating energy intensity reductions in basalt fiber and steel rebar production. Stakeholders must monitor evolving carbon border adjustment mechanisms and material passport requirements that will determine competitive access across major demand centers.
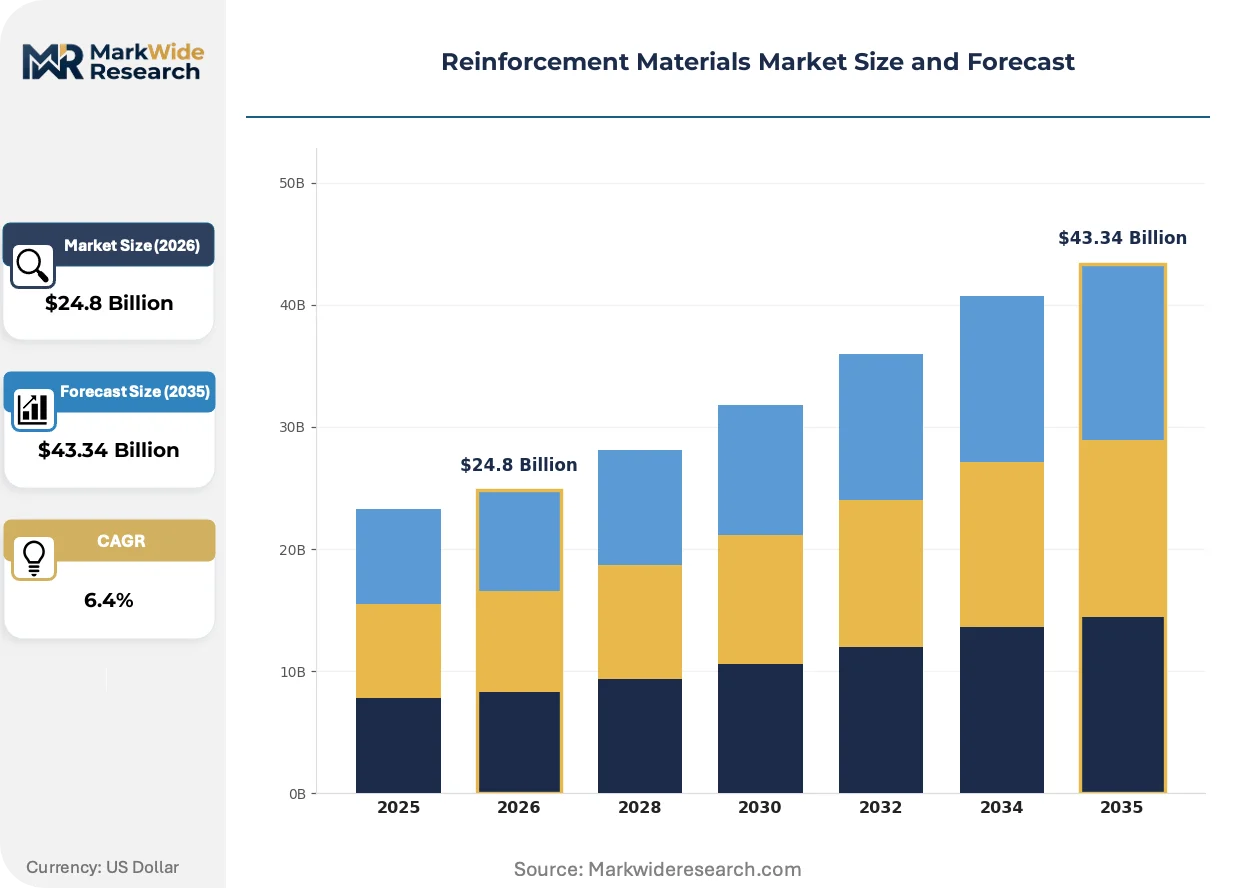
Market Dynamics
The EU Green Deal's embodied carbon thresholds are compressing specification windows for steel and synthetic fibers, forcing suppliers to revalidate material passports and source low-carbon feedstocks to retain access to European infrastructure projects.
Growth Catalysts
- State-backed infrastructure:China's rail and wind energy expansion consumes substantial basalt fiber and high-strength steel reinforcement volumes, anchoring regional demand concentration.
- REACH chemical disclosure:The EU framework mandates substance transparency for construction imports, redirecting procurement toward certified low-carbon alternatives with traceable supply chains.
- Fiber-reinforced polymer composites:Construction contractors in Brazil and India specify these materials for seismic resilience and accelerated curing in high-humidity environments.
Market Restraints
- Energy cost volatility:Glass fiber and carbon fiber production depend on natural gas and electricity inputs, exposing margins to European and Asian utility price spikes.
- Chinese supply concentration:Basalt fiber and steel rebar capacity clusters in Hebei and Shandong provinces, creating single-point vulnerability for global availability.
- Recyclability limitations:Thermoset composite reinforcement lacks economically viable end-of-life processing, constraining circular economy compliance in jurisdictions with extended producer responsibility laws.
Strategic Opportunities
- Bio-based fiber development:Flax and hemp reinforcement variants align with France's national low-carbon construction targets and qualify for green public procurement preferences.
- Direct supplier-automaker channels:Tier-one automotive manufacturers bypass traditional distributors to secure carbon fiber volumes for electric vehicle battery enclosures and structural members.
- Carbon border adjustment mechanisms:The EU's phased implementation creates first-mover advantage for reinforcement producers with verified low-emission production processes and documented supply chain emissions.
Industry Challenges
- Composite repair technician scarcity:Wind blade and marine hull maintenance require specialized fiber layup and resin infusion skills that outpace vocational training program output.
- Multi-standard certification complexity:Reinforcement materials for aerospace primary structures must satisfy FAA, EASA, and CAAC qualification protocols simultaneously, extending approval timelines.
- Legacy concrete specification inertia:Structural engineering codes in mature markets embed steel rebar as default reinforcement, slowing fiber-reinforced polymer adoption despite performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reinforcement Materials Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fiber, Steel, Reinforced Plastic, Glass Application: Construction, Aerospace, Automotive, Marine Form: Sheet, Rod, Coil, Grid End User: Manufacturers, Contractors, Designers, Engineers |
| Companies Covered | BASF SE, Honeywell International Inc., Owens Corning, N.V. Bekaert S.A., Hyosung Advanced Materials, Toray Industries Inc, DuPont de Nemours Inc., Solvay, Teijin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reinforcement Materials Market Strategic Shifts & Innovations
Digital thread technology is compressing design-to-production cycles for complex reinforcement geometries, while regulatory pressure on embodied carbon accelerates material substitution decisions across construction and transportation end-uses.
Automated fiber placement systems with integrated in-situ monitoring are digitizing quality assurance for aerospace-grade carbon fiber preforms. Boeing and Airbus tier suppliers deploy these systems to reduce scrap rates and compress layup cycle times. The technology is digitizing workforce requirements, shifting labor demand from manual layup technicians toward robotics operators and data analysts.
The EU AI Act's risk classification framework is elevating documentation burdens for reinforcement materials used in safety-critical infrastructure. Suppliers must demonstrate algorithmic transparency in automated manufacturing quality systems to maintain CE marking eligibility. German and French construction material distributors report extended compliance preparation periods as they adapt procurement specifications to these requirements.
Buyers in automotive and wind energy sectors now consolidate reinforcement procurement under single-source agreements with raw fiber producers, bypassing regional distributors entirely. This channel compression concentrates price negotiation leverage with volume purchasers and marginalizes mid-tier distributors lacking direct mill relationships. The pattern is most pronounced in Germany and China, where OEM procurement teams maintain dedicated commodity management functions for carbon and glass fiber categories.
Reinforcement Materials Market Segmentation
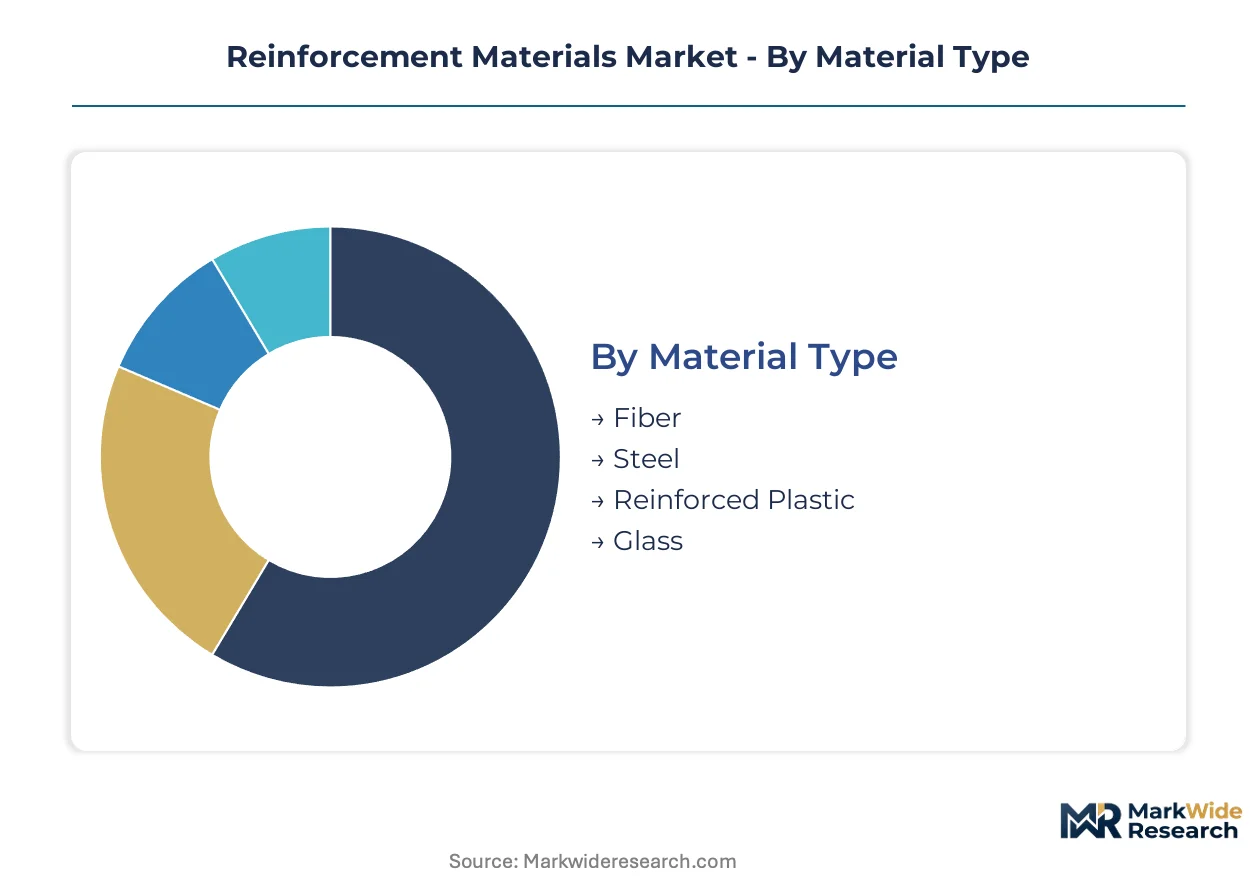
Segmentation in reinforcement materials reveals divergent cost-performance tradeoffs across material classes and form factors. Specification decisions in construction, aerospace, and automotive end-uses hinge on tensile strength requirements, processing compatibility, and regulatory compliance thresholds.
Material Type:
Mature commodity categories coexist with emerging high-performance alternatives across distinct price-performance tiers.
- Steel:Carbon and alloy grades dominate concrete reinforcement with established supply chains and code-compliant performance. Contractors in India and Brazil specify high-strength rebar for seismic-resistant infrastructure, though embodied carbon scrutiny under EU Green Deal thresholds is compressing specification windows for conventional production routes.
- Fiber:Glass, carbon, and aramid variants deliver specific strength advantages in composite matrices. Wind blade manufacturers in China and Germany consume substantial glass fiber volumes for rotor spar caps, while aerospace tier suppliers specify carbon fiber for primary structural members where weight reduction justifies premium positioning.
- Reinforced Plastic:Thermoset and thermoplastic composites integrate continuous or discontinuous fiber reinforcement for corrosion resistance and design flexibility. Marine hull fabricators specify these materials for accelerated curing in high-humidity environments.
- Glass:E-glass and S-glass formulations anchor cost-sensitive applications with proven processability in open mold and pultrusion operations.
Steel retains volume leadership; fiber holds the steepest expansion curve.
Application:
End-use concentration patterns reflect infrastructure investment cycles and transportation electrification priorities.
- Construction:Concrete reinforcement for buildings, bridges, and tunnels represents the foundational demand base. China's state-backed rail expansion consumes substantial basalt fiber and high-strength steel volumes, anchoring regional procurement concentration.
- Aerospace:Primary and secondary structural components require qualification-grade carbon fiber preforms with documented traceability. Boeing and Airbus tier suppliers deploy automated fiber placement to compress layup cycle times and reduce scrap rates.
- Automotive:Underbody panels, battery enclosures, and structural members specify glass and carbon fiber composites for mass reduction without sacrificing crash performance. Tier-one manufacturers bypass distributors to secure direct mill relationships.
- Marine:Hull laminates and superstructure components leverage glass fiber corrosion resistance in saltwater environments. Specialized fiber layup skills constrain maintenance capacity expansion.
Construction commands the largest absolute volumes; automotive demonstrates the most rapid specification shift toward fiber alternatives.
Form:
Processing method and end-use geometry dictate form factor selection across manual and automated fabrication workflows.
- Sheet:Flat laminates serve panel applications in automotive bodywork and marine decking with tailored fiber orientation for directional strength. Automated cutting systems reduce nesting waste in high-volume operations.
- Rod:Pultruded profiles provide linear reinforcement in concrete structures and composite framing members. India's infrastructure contractors specify these for accelerated construction timelines.
- Coil:Continuous wound configurations facilitate automated processing in filament winding and tape laying operations for pressure vessels and pipe applications.
- Grid:Open mesh structures enable composite-concrete hybrid systems with optimized bond characteristics and reduced material usage.
Sheet dominates fabrication throughput; rod configurations are gaining share fastest in infrastructure applications.
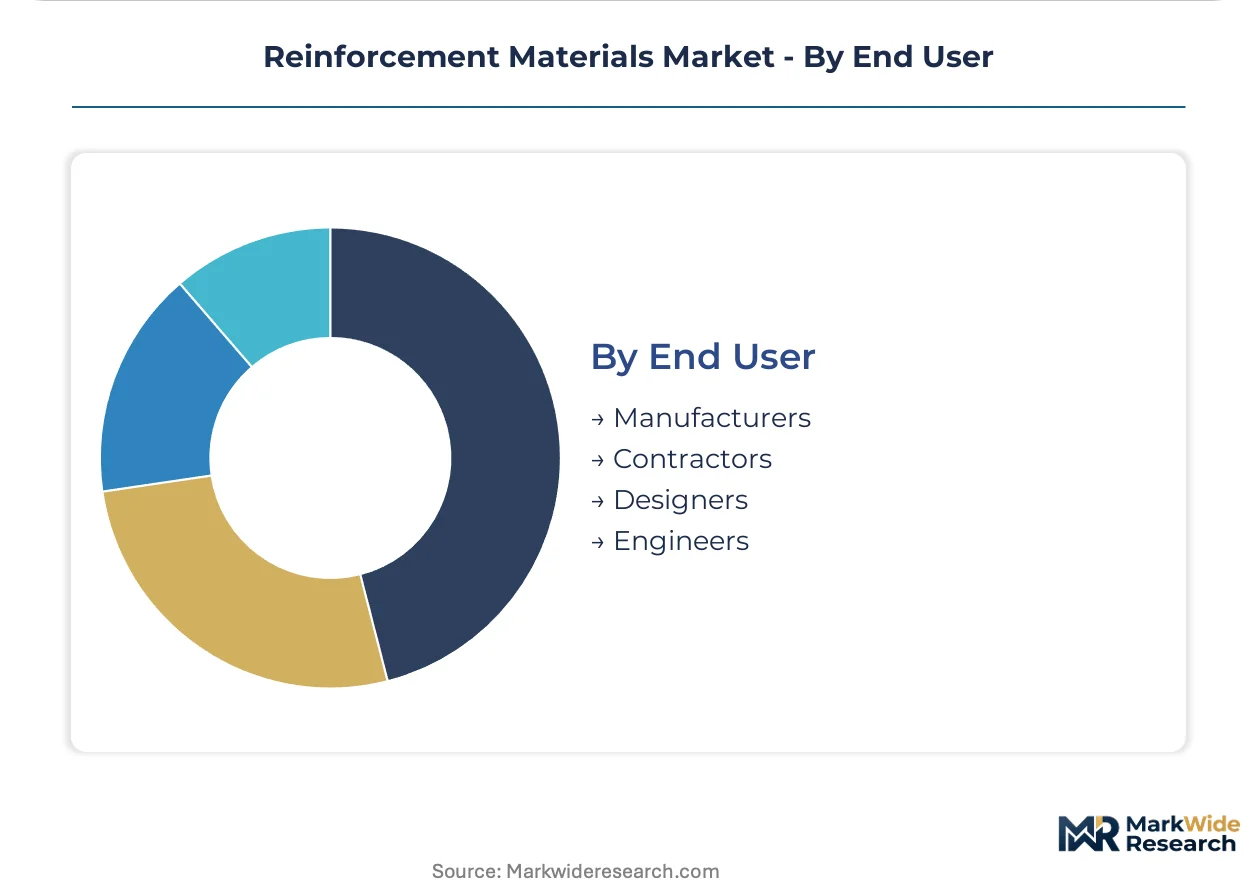
End User:
Procurement sophistication varies sharply across the value chain from specification authority to installation execution.
- Manufacturers:Tier-one automotive and aerospace OEMs consolidate purchasing under dedicated commodity management functions. Direct fiber producer relationships disintermediate traditional distributors in Germany and China.
- Contractors:Construction execution teams select reinforcement based on code compliance, availability, and labor skill requirements. Brazilian and Indian contractors specify fiber-reinforced polymer composites for seismic resilience.
- Designers:Architectural and engineering firms embed material selection decisions in early-stage specifications that constrain downstream procurement options. EU Green Deal embodied carbon thresholds redirect their preferences toward low-carbon alternatives.
- Engineers:Structural analysis professionals validate performance claims against multi-standard certification protocols including FAA, EASA, and CAAC requirements for safety-critical applications.
Manufacturers exercise the strongest price leverage; designers are expanding influence fastest through early-stage specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Chinese producers of basalt fiber and steel rebar, while European buyers absorb carbon border adjustment premiums. German automotive OEMs and French construction authorities now demand verified low-carbon material passports. India's infrastructure contractors specify fiber-reinforced polymers for seismic resilience.
China
State-backed rail expansion and wind energy projects consume substantial basalt fiber and high-strength steel reinforcement volumes. GB standards and dual carbon goals mandate energy intensity reductions in Hebei and Shandong production clusters. Capacity concentration in these provinces creates single-point vulnerability for global availability.
Germany
Automotive OEM procurement teams maintain dedicated commodity management functions for carbon and glass fiber categories. EU Green Deal embodied carbon thresholds compress specification windows for conventional steel and synthetic fibers. The Eindhoven-Rotterdam-Antwerp corridor hosts automated fiber placement systems for aerospace-grade preforms.
United States
EPA industrial emissions standards and OSHA silica exposure limits elevate compliance costs for glass fiber manufacturing. Boeing tier suppliers deploy automated layup systems to reduce scrap rates in carbon fiber preform production. The Pacific Northwest and Southeast states concentrate wind blade fabrication demanding glass fiber volumes.
India
Infrastructure contractors specify fiber-reinforced polymer composites for accelerated curing in high-humidity environments. BIS certification requirements and PLI scheme incentives redirect procurement toward domestic reinforcement production. Maharashtra and Gujarat industrial corridors anchor composite manufacturing for construction and marine applications.
Brazil
Seismic-resistant infrastructure specifications drive fiber-reinforced polymer adoption in high-rise construction. ANVISA and environmental agency frameworks govern chemical disclosure for imported construction materials. São Paulo and Rio de Janeiro metropolitan contractors lead specification shifts toward corrosion-resistant reinforcement alternatives.
Reinforcement Materials Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in raw fiber and metal production. The vendor base spans integrated glass melters, carbon fiber precursors, and steel alloy producers with divergent capital intensity requirements. Three archetypes dominate: integrated fiber-to-composite producers, specialty chemical compounders, and steel rebar manufacturers with blast furnace assets. Capacity expansion and direct supplier-automaker channel development represent the dominant competitive moves.
Within the integrated fiber tier, Owens Corning and Toray Industries Inc occupy positions reflecting captive supply chain control. DuPont de Nemours Inc exemplifies the specialty chemical archetype through aramid fiber technology. These three anchors illustrate how geographic production concentration and material-specific process knowledge create defensive positioning against distributor disintermediation.
| Leading Market Players |
|---|
| BASF SE |
| Honeywell International Inc. |
| Owens Corning |
| N.V. Bekaert S.A. |
| Hyosung Advanced Materials |
| Toray Industries Inc |
| DuPont de Nemours Inc. |
| Solvay |
| Teijin Limited |
| Others |
Cost & Logistics Intelligence
The Eindhoven-Rotterdam-Antwerp corridor's freight cost dynamics amplify pricing power for Chinese basalt fiber producers while compressing margins for European distributors serving automotive OEMs with just-in-time carbon fiber requirements. Energy-intensive glass melting operations in Hebei province leverage coal-fired electricity subsidies to undercut European competitors on standard-grade reinforcement, forcing EU suppliers to retreat toward configured-to-order aerospace preforms where certification barriers protect price premiums.
Pricing Analysis
The customization-premium spread separates commodity glass fiber sold on volume contracts from aerospace-grade carbon fiber preforms priced per qualification batch. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FAA/EASA-qualified materials commanding substantial markups over industrial-grade alternatives. Pricing pressure stems from Chinese state-backed capacity expansion in Hebei and Shandong, which floods spot markets with undifferentiated basalt fiber. Construction contractors in India and Brazil exhibit highest price sensitivity, while aerospace tier suppliers prioritize traceability over unit cost.
Supply Chain Analysis
Upstream feedstock supply draws from petroleum-based precursor chemicals for carbon fiber, silica sand for E-glass melting, and iron ore for steel rebar production. Manufacturing gravity centers on China for basalt fiber and steel rebar, Germany for automotive-grade carbon fiber preforms, and the United States for aerospace-qualified materials. Single-source vulnerability concentrates in Chinese provincial production clusters, where environmental enforcement actions or energy rationing cascade through global availability. Distribution runs through direct mill-OEM relationships in automotive and wind energy, bypassing traditional distributor networks entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reinforcement materials market sits in early-stage cyclical recovery, with China's state-backed infrastructure stimulus and EU Green Deal procurement mandates restocking demand pipelines after the 2022-2024 construction downturn.
For Market Incumbents: Insulate core positions through backward integration into precursor chemical production and captive glass melting capacity in low-energy-cost geographies. Carbon fiber leaders must defend aerospace qualification portfolios against emerging Chinese competitors by accelerating FAA/EASA dual-certification timelines. Steel rebar manufacturers face margin compression from EU carbon border adjustments and should redirect capacity toward high-strength seismic grades for Indian and Brazilian infrastructure. For New Entrants and Emerging Players: Southeast Asian composite manufacturing corridors offer underpenetrated access to marine hull fabricators seeking corrosion-resistant reinforcement alternatives to steel. Brazil's seismic-resistant construction codes create specification entry points for fiber-reinforced polymer rod producers willing to invest in ANVISA chemical disclosure compliance. A technical-service-heavy go-to-market model, embedding application engineers with contractor specification teams, outperforms price-competing against established distributors. For Investors and Strategic Acquirers: Automated fiber placement system integrators with aerospace tier relationships represent the most defensible acquisition archetype, given digitization trends compressing layup cycle times. Long-term viability hinges on positioning upstream of automotive battery enclosure and wind blade manufacturing expansion. Watch for EU carbon border adjustment implementation pace as the critical inflection signal determining competitive access premiums for low-carbon reinforcement producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemicals | Captive acrylonitrile supply secures carbon fiber margin stability against petrochemical volatility. |
| Automated Fiber Placement System Deployment | Boeing and Airbus tier suppliers reduce scrap rates while compressing qualification timelines for aerospace preforms. |
| Low-Carbon Material Passport Certification | EU Green Deal compliance unlocks specification access for European infrastructure and automotive procurement. |
| Direct Mill-OEM Supply Agreement | Tier-one automotive manufacturers bypass distributors to secure carbon fiber volumes for battery enclosures. |
| Bio-Based Fiber Pilot Production | Flax and hemp variants qualify for France's green public procurement preferences under national low-carbon targets. |
Research Approach
A standing panel of composite manufacturing plant managers, Tier 1 automotive procurement directors, wind blade fabrication engineers, and construction contractor specification leads provided ongoing calibration against field conditions. Primary interviews with these stakeholders combined with secondary validation through customs trade data, SEC 10-K filings from listed fiber producers, GB standards documentation, and EU ETS emissions disclosures. Bottom-up volume modeling across material type and application segments triangulated against top-down macroeconomic infrastructure investment forecasts.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning material type, end-use application, form factor, and geographic production hub. CAGRs derived from regression analysis of historical capacity utilization rates, infrastructure investment cycles, and substitution elasticity between steel and fiber-reinforced alternatives. Industry-specific inputs included wind energy installation forecasts, automotive platform electrification roadmaps, and EU carbon border adjustment implementation schedules.
Practitioners should monitor Chinese provincial environmental enforcement actions, EU material passport regulatory finalization, and automotive OEM battery enclosure specification shifts for early signals requiring forecast revision. Cross-checking against IEA clean energy investment tracking and national infrastructure budget appropriations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Carbon Graphite Market
Advanced Materials
Wood Foam Market
Advanced Materials
Si-C Anode Material Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
Flexible Bio-Foams Market
Advanced Materials
Inorganic Non-Metallic Materials Market
Advanced Materials
Cathode Active Material Market
Advanced Materials
Anisotropic Conductive Films (ACF) Market
Advanced Materials
US Graphene Market
Advanced Materials
Cubic Boron Nitrates Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Global Graphene Market
Advanced Materials
Liquid Thermal Interface Materials Market
Advanced Materials
Global Advanced Phase Change Materials Market
Advanced Materials
Electromagnetic Shielding Market
Advanced Materials
Silica Aerogel Market