
 Global Barium Petroleum Sulfonate Market | 2026-2036
Global Barium Petroleum Sulfonate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Barium Petroleum Sulfonate Market Foresight
The capital-intensity divergence between integrated petrochemical majors and regional sulfonate specialists is bifurcating competitive dynamics across the Global Barium Petroleum Sulfonate Market. BASF SE leverages its backward integration into alkylbenzene feedstocks to sustain margin stability across European supply chains. Chevron Corporation anchors its position through captive refinery-sourced base oils that feed directly into sulfonate manufacturing. Xinji Rongchao Petroleum Chemical competes on cost-optimized powdered form output serving domestic Chinese lubricant blenders.
Barium petroleum sulfonate refers to a metal-organic compound synthesized via neutralization of petroleum-derived sulfonic acids with barium hydroxide, typically yielding products with molecular weights between 900 and 1,200 g/mol and base numbers of 15–30 mg KOH/g. The compound functions primarily as a rust inhibitor and detergent-dispersant in lubricating oils and as an emulsifier in oil-based drilling fluids. Liquid concentrate formulations dominate volume flows due to their compatibility with automated blending systems at lubricant manufacturers, while powdered form variants command premium positioning in remote oilfield services where transport costs favor reduced water content. Emulsion-grade sulfonates represent the fastest-growing application segment as operators shift toward synthetic-based drilling fluids in high-temperature well environments.
EPA regulations under the Toxic Substances Control Act and REACH restrictions on heavy metal content in lubricant additives are elevating purity requirements for barium petroleum sulfonate entering North American and European channels. China's NMPA and GB standards for petroleum-derived chemicals impose parallel testing protocols that shape export eligibility for Asian producers. The EU Green Deal's trajectory toward lower-carbon lubricant formulations is forcing reformulation decisions across the value chain. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate certification costs that will determine competitive access in premium additive segments.
Market Dynamics
Deepwater exploration intensification in Brazil's pre-salt basins and West African margins is pulling sulfonate demand toward high-performance emulsion grades, while REACH and EPA heavy-metal limits force simultaneous purity upgrades across legacy supply chains.
Growth Catalysts
- Deepwater drilling expansion:Operators in Brazil's Búzios and Mero fields are specifying synthetic-based drilling fluids that require emulsion-grade barium petroleum sulfonates for thermal stability above 150°C.
- REACH Annex XVII amendments:ECHA's tightened heavy metal restrictions in lubricant additives are accelerating substitution of calcium sulfonates with purified barium variants in European marine engine oils.
- China's lubricant self-sufficiency drive:Domestic blenders in Shandong and Jiangsu provinces are scaling captive sulfonate intermediate production to reduce import dependency for API Group II/III base oil formulations.
Market Restraints
- Barium hydroxide cost volatility:Concentrated mining output from China's Guizhou province creates input price spikes that compress margins for non-integrated sulfonate manufacturers.
- Substitution by calcium petroleum sulfonates:Lower-toxicity calcium variants are capturing share in automotive lubricant applications where extreme-pressure performance requirements are less stringent.
- EPA TSCA Section 5 premanufacture review:New chemical notifications for modified sulfonate structures add 90-180 day regulatory delays for product line extensions targeting North American channels.
Strategic Opportunities
- High-temperature geothermal drilling:Iceland's Krafla and Indonesia's Wayang Windu geothermal projects are testing sulfonate-stabilized drilling fluids above 200°C wellbore conditions.
- EU Green Deal lubricant circularity mandates:Refillable industrial lubricant systems in German manufacturing clusters are creating demand for sulfonate formulations optimized for extended fluid life cycles.
- Direct-to-blender digital platforms:Specialty chemical distributors in the US Gulf Coast are launching automated procurement portals that bypass traditional multi-tier distribution for mid-volume lubricant manufacturers.
Industry Challenges
- Specialized chemical engineering talent scarcity:Sulfonate process optimization requires expertise in sulfonation kinetics and metal soap chemistry that is concentrated among retiring specialists at European petrochemical institutes.
- Multi-jurisdiction certification timelines:Simultaneous EPA PMN filings, REACH registration updates, and China GB standard compliance testing extend product launch cycles by 14-18 months for global additive suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Barium Petroleum Sulfonate Market |
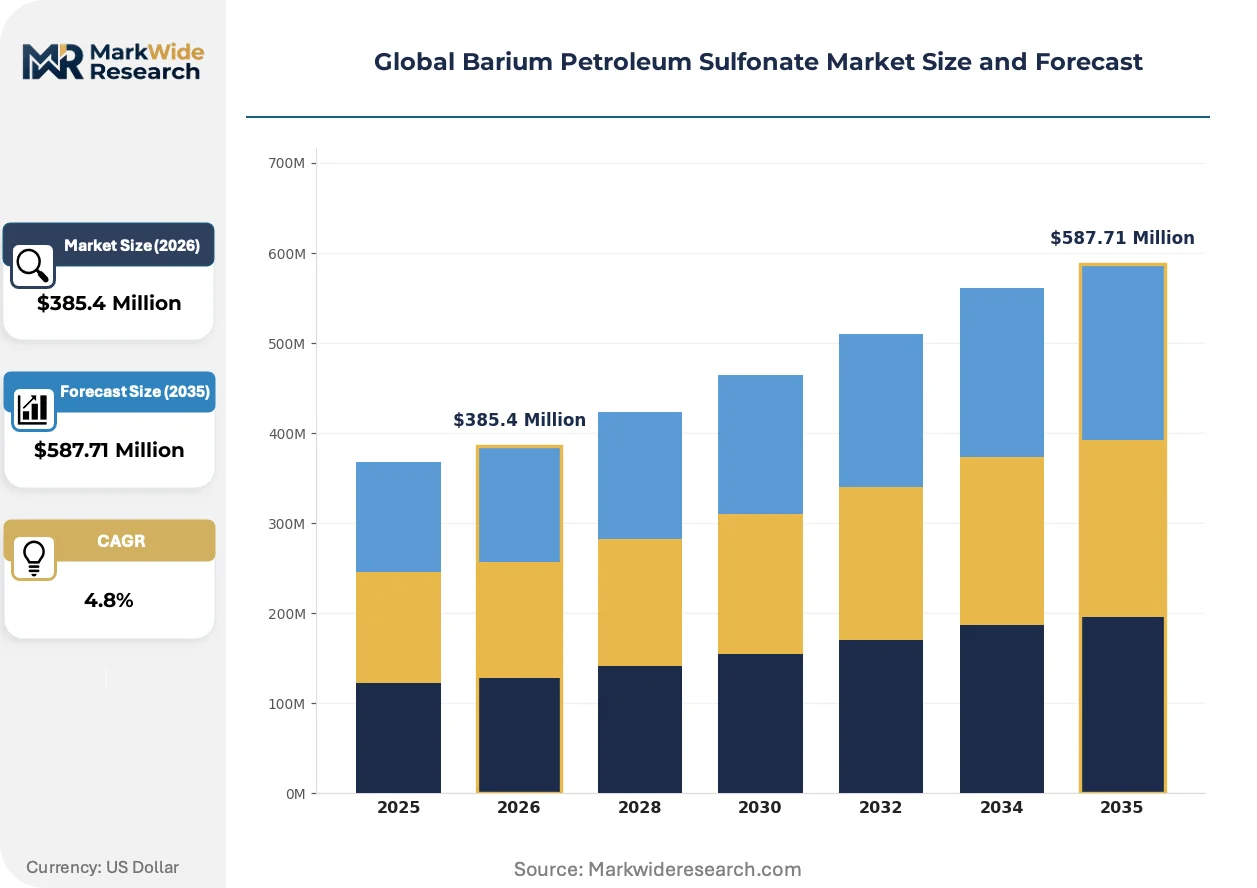
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Concentrate, Powdered Form, Granular, Emulsion Application: Drilling Fluids, Corrosion Inhibitors, Lubricants, Emulsifiers, Additives End User Industry: Oilfield Services, Petrochemical Plants, Lubricant Manufacturers, Chemical Processing, Refining Units Packaging Type: Drums, Bulk Bags, Carboys, Intermediate Bulk Containers, Totes |
| Companies Covered | BASF SE, ExxonMobil, Chevron Corporation, Unicorn Petroleum Industries, Eastern Petroleum, Xinji Rongchao Petroleum Chemical, Lanxess AG, Chemtura Corporation, MORESCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Barium Petroleum Sulfonate Market Shifts & Advancements
Sulfonate chemistry is undergoing functional specialization as end-users fragment requirements across thermal stability, biodegradability, and compatibility with synthetic base stocks. Three convergent developments are restructuring competitive positioning.
Synthetic ester-barium sulfonate hybrid emulsifiers are displacing conventional petroleum-derived sulfonates in high-temperature drilling applications. Operators in Norway's Johan Sverdrup field and US Gulf deepwater projects are specifying these hybrids for wellbore temperatures exceeding 175°C. The displacement is compressing demand for standard-grade liquid concentrates in premium oilfield service contracts.
REACH restriction proposals on persistent organic pollutants in metalworking fluids are forcing reformulation of sulfonate-based rust inhibitors across European automotive supply chains. ECHA's 2023-2024 consultations on lubricant additive ecotoxicity are prompting German and French metalworking fluid blenders to pre-certify alternative sulfonate structures. The regulatory pressure is most acute in precision machining segments serving aerospace tier-1 suppliers.
Integrated lubricant manufacturers are consolidating sulfonate procurement through long-term offtake agreements rather than spot market purchases. This behavioral shift is disintermediating traditional chemical distributors in the US Midwest and Northeast industrial corridors. The consolidation is most visible among railroad and mining equipment lubricant blenders seeking supply security for high-volume detergent-dispersant programs.
Global Barium Petroleum Sulfonate Market Segmentation
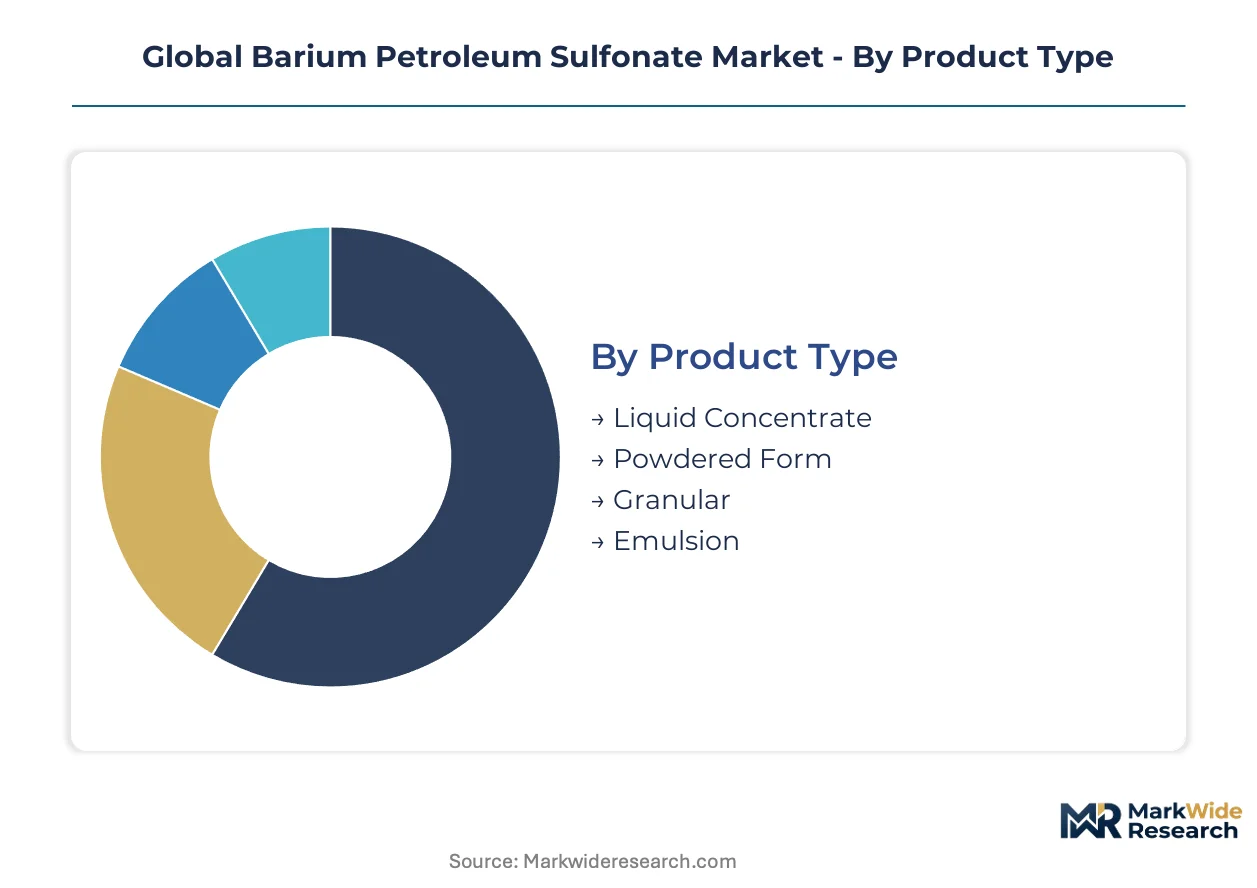
Segmentation in barium petroleum sulfonate reveals how formulation chemistry and logistics economics split margin capture between integrated refiners and specialty distributors. Product form and packaging density determine freight cost absorption, while application-grade purity requirements gate access to premium oilfield contracts.
Product Type:
Liquid concentrate formulations command the widest margin pools due to their compatibility with automated blending infrastructure at lubricant manufacturers.
- Liquid Concentrate:Water-based solutions with 50-70% active sulfonate content enable precision dosing in continuous lubricant production lines. Demand concentrates among API Group II/III base oil blenders in the US Gulf Coast and Rotterdam refining corridors, where automated metering systems minimize handling losses. EPA TSCA compliance documentation adds certification overhead that favors suppliers with established North American regulatory files.
- Powdered Form:Spray-dried particles with <5% moisture content reduce transport costs for remote oilfield deployments. Xinji Rongchao and similar Chinese producers compete on cost-optimized output serving domestic lubricant blenders in Shandong province, where rail freight to inland drilling sites favors reduced water weight.
- Granular:Intermediate moisture content suits regional distributors lacking liquid handling infrastructure.
- Emulsion:Synthetic-based drilling fluid grades with enhanced thermal stability above 150°C are climbing the share rankings in Brazil's pre-salt and West African deepwater contracts.
Liquid concentrate holds installed capacity. Emulsion is rotating up the share rankings.
Application:
Application segmentation tracks how end-use performance requirements fragment procurement specifications across temperature thresholds and metal content limits.
- Drilling Fluids:Synthetic-based formulations for high-temperature wellbores above 175°C specify emulsion-grade sulfonates with modified molecular weight distributions. Norway's Johan Sverdrup field and US Gulf deepwater operators drive specification tightening.
- Corrosion Inhibitors:Rust-preventive films in metalworking fluids face REACH restriction proposals on persistent organic pollutants, forcing German and French blenders toward pre-certified alternative structures.
- Lubricants:Detergent-dispersant programs in railroad and mining equipment lubricants consolidate procurement through long-term offtake agreements.
- Emulsifiers:Oil-water interface stabilization for synthetic drilling systems.
- Additives:Multi-functional packages combining rust inhibition with extreme-pressure performance.
Drilling fluids command specification premiums. Corrosion inhibitors face regulatory compression.
End User Industry:
End user segmentation exposes divergent supply chain power between captive refinery integration and third-party specialty chemical distribution.
- Oilfield Services:Schlumberger, Halliburton, and Baker Hughes specify emulsion-grade sulfonates for deepwater contracts, with procurement consolidating through direct manufacturer relationships rather than distributor intermediaries.
- Petrochemical Plants:Integrated majors like BASF SE and Chevron Corporation leverage backward integration into alkylbenzene feedstocks and captive base oil supply.
- Lubricant Manufacturers:Independent blenders in China's Jiangsu province scale captive sulfonate intermediate production to reduce import dependency.
- Chemical Processing:Specialty emulsifier demand for industrial coatings and adhesives.
- Refining Units:Internal consumption for finished lubricant production.
Oilfield services drive specification innovation. Lubricant manufacturers are consolidating backward.
Packaging Type:
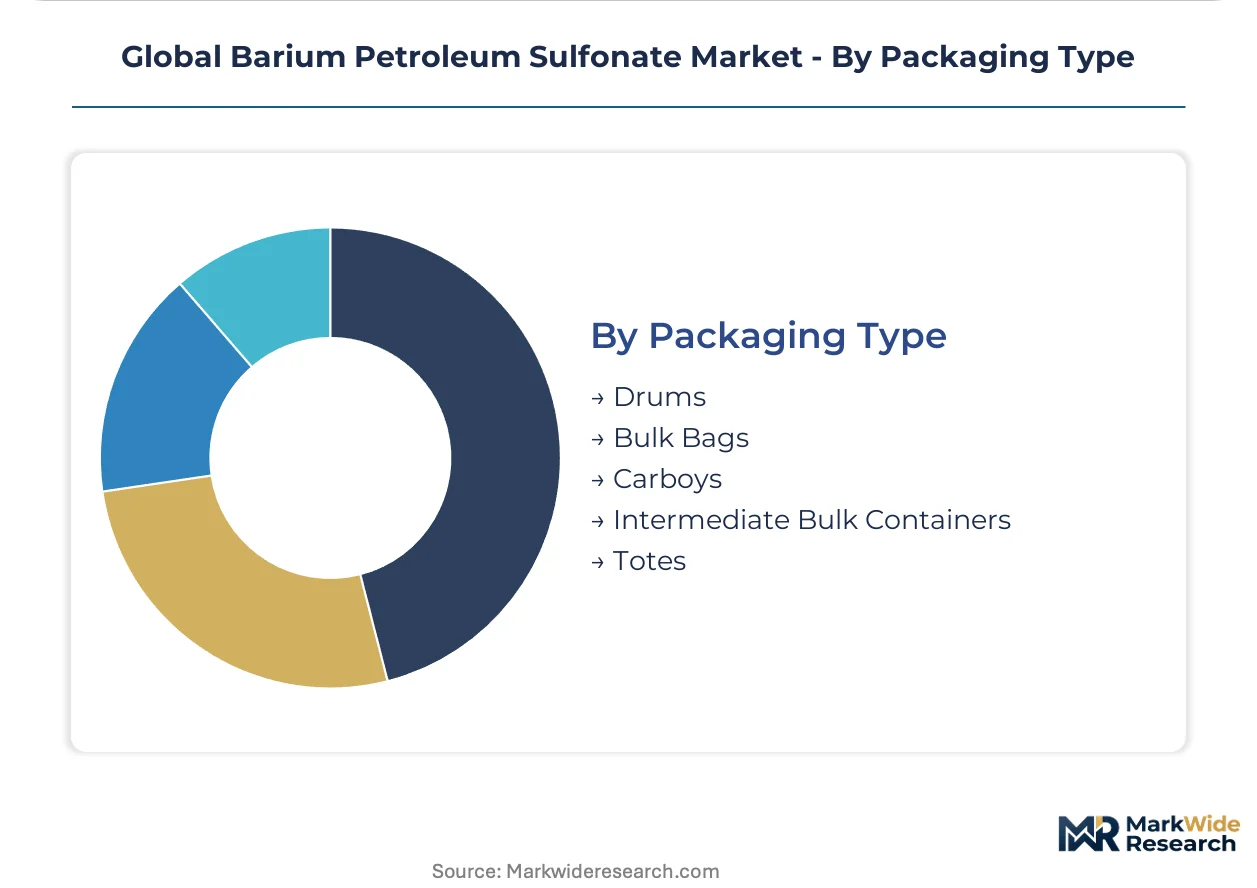
Packaging economics determine freight cost allocation and inventory turnover velocity across remote versus concentrated demand geographies.
- Drums:Standard 200-liter steel containers dominate mid-volume lubricant blender procurement in industrial corridors with established chemical handling infrastructure.
- Bulk Bags:One-ton flexible intermediate bulk containers reduce per-kilogram packaging cost for powdered form shipments to remote oilfield supply bases.
- Carboys:Smaller-volume plastic containers suit laboratory and pilot-scale formulation testing.
- Intermediate Bulk Containers:Reusable 1,000-liter totes serve manufacturing clusters with closed-loop logistics systems.
- Totes:Single-use flexible containers for liquid concentrate in automated dispensing environments.
Drums retain volume leadership. Bulk bags are gaining share in remote logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing leverage through captive barium hydroxide sourcing from Guizhou mining operations, while European blenders absorb REACH compliance premiums that widen the trans-Atlantic cost spread. This asymmetry is redirecting investment toward integrated sulfonate manufacturing in East Asian refining corridors.
United States
Deepwater operators in the Gulf of Mexico specify emulsion-grade sulfonates for wellbore temperatures exceeding 175°C. EPA TSCA Section 5 premanufacture review adds 90-180 day delays for modified sulfonate structures entering North American channels. Houston's petrochemical corridor hosts automated lubricant blending infrastructure that favors liquid concentrate procurement.
China
Domestic lubricant manufacturers in Shandong and Jiangsu provinces scale captive sulfonate intermediate production to reduce import dependency. NMPA and GB standards impose parallel testing protocols that shape export eligibility for Asian producers. Xinji Rongchao Petroleum Chemical anchors cost-optimized powdered form output serving inland drilling sites via rail freight.
Germany
ECHA's tightened heavy metal restrictions under REACH Annex XVII accelerate substitution of calcium sulfonates with purified barium variants in marine engine oils. The EU Green Deal's trajectory toward lower-carbon lubricant formulations forces reformulation decisions across industrial supply chains. BASF SE leverages backward integration into alkylbenzene feedstocks from its Ludwigshafen complex.
Brazil
Pre-salt basin exploration in Búzios and Mero fields pulls sulfonate demand toward high-performance emulsion grades for synthetic-based drilling fluids. ANVISA and environmental licensing requirements shape chemical additive import protocols. Operators specify thermal stability above 150°C for deepwater well environments.
Norway
Johan Sverdrup field development drives specification tightening for synthetic ester-barium sulfonate hybrid emulsifiers. ECHA consultations on lubricant additive ecotoxicity prompt pre-certification of alternative sulfonate structures for North Sea deployment. Stavanger's oilfield services cluster consolidates procurement through direct manufacturer relationships.
Global Barium Petroleum Sulfonate Market Competitive Landscape
Concentration sits with integrated petrochemical majors that control alkylbenzene feedstock and captive base oil supply. The vendor base spans three functional tiers: multinational chemical conglomerates with backward integration, regional sulfonate specialists optimizing powdered form output, and oilfield service distributors managing emulsion-grade logistics. Competitive dynamics bifurcate between margin-stable European supply chains and cost-driven Asian production. Dominant moves include long-term offtake agreements that disintermediate traditional distributors and capacity expansion in Shandong province to serve China's lubricant self-sufficiency drive.
Within the integrated chemical tier, BASF SE and Chevron Corporation exemplify divergent integration strategies. BASF anchors European supply chains through captive alkylbenzene production, while Chevron leverages refinery-sourced base oils feeding directly into sulfonate manufacturing. Xinji Rongchao Petroleum Chemical occupies the regional specialist position, competing on cost-optimized powdered form output for domestic Chinese blenders. These three anchors illustrate how feedstock control, geographic proximity to demand, and product form specialization stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| BASF SE |
| ExxonMobil |
| Chevron Corporation |
| Unicorn Petroleum Industries |
| Eastern Petroleum |
| Xinji Rongchao Petroleum Chemical |
| Lanxess AG |
| Chemtura Corporation |
| MORESCO Corporation |
| Others |
Supply & Pricing Matrix
Calcium petroleum sulfonate substitution in automotive lubricant applications is simultaneously shifting procurement geography toward Chinese barium hydroxide suppliers and compressing margin pools for non-integrated European manufacturers. This displacement dynamic concentrates pricing power with Guizhou mining-linked producers while forcing REACH-compliant blenders to absorb certification premiums that widen trans-Atlantic cost spreads.
Pricing Analysis
Configured-to-order emulsion-grade sulfonates for deepwater drilling command substantial premiums over standard liquid concentrate formulations. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in thermal stability certification and base number precision. Cost compression in mid-grade liquid concentrates is intensifying because Xinji Rongchao and similar Chinese producers are scaling cost-optimized powdered output. Railroad and mining equipment lubricant blenders exhibit lowest price sensitivity due to long-term offtake agreements, while independent automotive lubricant manufacturers face acute margin pressure from calcium sulfonate alternatives.
Supply Chain Analysis
Strategic stockpiling of barium hydroxide feedstock dominates inventory strategy among integrated petrochemical majors seeking insulation from Guizhou mining output volatility. Supply concentrates in China, Germany, and the United States, with raw material flows drawing from petroleum-derived sulfonic acid streams and barium hydroxide mining operations. Single-source vulnerability in Chinese barium hydroxide concentrate creates structural exposure for non-integrated sulfonate manufacturers. Distribution runs through direct manufacturer relationships with oilfield service majors and specialty chemical distributors serving mid-volume lubricant blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized chemical engineering expertise in sulfonation kinetics and metal soap chemistry has become the constraining asset, with retirement waves at European petrochemical institutes creating capability gaps that integrated majors are racing to backfill through targeted recruitment and knowledge-capture programs.
For Market Incumbents: Fortify captive feedstock positions through backward integration into alkylbenzene supply or long-term offtake agreements with Guizhou barium hydroxide producers. Calcium sulfonate substitution in automotive applications demands accelerated R&D investment in high-temperature emulsion grades for geothermal and deepwater drilling to defend premium positioning. REACH Annex XVII compliance documentation should be pre-positioned ahead of ECHA restriction proposals to compress certification timelines for European marine engine oil formulations. For New Entrants and Emerging Players: Lead with emulsion-grade sulfonate development for geothermal drilling applications above 200°C wellbore conditions, where specification gaps exist and incumbent certification portfolios remain thin. Iceland's Krafla and Indonesia's Wayang Windu projects offer penetrable entry points with direct-to-operator sales models bypassing established distributor relationships. Digital procurement platforms targeting US Gulf Coast mid-volume lubricant manufacturers provide a channel innovation angle against legacy multi-tier distribution. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional sulfonate specialists in China's Shandong province that have scaled powdered form capacity but lack emulsion-grade technology transfer. Long-term viability hinges on exposure to oilfield services consolidation and the durability of deepwater exploration commitments across Brazil's pre-salt and West African margins. The inflection signal to watch is ECHA's final determination on persistent organic pollutant restrictions in metalworking fluids, which would accelerate reformulation demand and premium-grade sulfonate procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkylbenzene Feedstocks | BASF SE's Ludwigshafen complex demonstrates margin stability through captive sulfonic acid supply. |
| Emulsion-Grade Capacity Expansion | Synthetic-based drilling fluid demand in Norway's Johan Sverdrup field pulls specification innovation. |
| Long-Term Offtake Agreements with Oilfield Services | Schlumberger and Halliburton procurement consolidation disintermediates traditional chemical distributors. |
| REACH Pre-Certification Investment | German and French metalworking fluid blenders face ECHA pressure to validate alternative sulfonate structures. |
| Direct-to-Blender Digital Platform Launch | US Gulf Coast automated procurement portals bypass multi-tier distribution for mid-volume manufacturers. |
Research Methodology
A standing panel of lubricant formulation chemists, oilfield services procurement directors, petrochemical plant managers, and REACH regulatory consultants provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation from customs and trade databases, American Chemistry Council reports, SEC 10-K filings, and ECHA registration databases enabled bottom-up and top-down triangulation of market sizing and growth trajectories.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product form, application-grade purity tier, end-use industry vertical, and regional production hub classification. CAGRs were derived from production capacity buildout schedules, exploration commitment timelines in named deepwater basins, and regulatory implementation trajectories for heavy metal restrictions.
The analysis sits within stated boundaries; outcomes outside sustained deepwater exploration investment, stable barium hydroxide mining output, and current REACH restriction timelines would require recalibration. Forecasts reflect documented assumptions regarding substitution elasticity between barium and calcium sulfonates, certification timeline durations, and oilfield services procurement consolidation patterns. Practitioners should keep alternative scenarios live as ECHA ecotoxicity consultations and EPA TSCA premanufacture review timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
Defoamers Market
Surfactants
Natural Surfactants Market
Surfactants
Sodium Lauroyl Glycinate Market
Surfactants
Global Amphoteric Surfactants Market
Surfactants
Detergent Chemicals Market
Surfactants
Surfactant Cleansers and Adjuvants Market
Surfactants
Emulsion Stabilizers Market
Surfactants
Specialty Surfactants Market
Surfactants
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market
Surfactants
Global Surfactants Market
Surfactants
Disodium Laureth Sulfosuccinate Market
Surfactants
Polysorbate 40 Market
Surfactants
Global Silicone Surfactants Market
Surfactants
Emulsifying Wax Market
Surfactants
Sulfosuccinate Market