
 Cubic Boron Nitrates Market | 2026-2036
Cubic Boron Nitrates Market Size, Share, and Industry Trends Forecast 2026-2036
Cubic Boron Nitrates Market Outlook
Subscription-based tool reconditioning and performance monitoring software is consolidating how cubic boron nitride value migrates from product to service in advanced manufacturing supply chains. Element Six leverages its synthetic diamond heritage to anchor cBN crystal growth capabilities across European precision engineering markets. Saint-Gobain competes through vertical control of ceramic bond systems that integrate its own cBN grain formulations. Showa Denko specializes in high-purity powder grades for semiconductor packaging applications where thermal conductivity specifications are tightening.
Cubic boron nitride is a synthetic crystalline material produced under high-pressure high-temperature conditions from hexagonal boron nitride precursors, exhibiting hardness second only to diamond alongside superior thermal stability above 1,000°C in oxygen-free environments; its primary industrial purpose centers on machining ferrous alloys and superalloys where diamond abrasives suffer chemical degradation from iron-carbon reactions. The abrasives application segment dominates current volume flows through automotive camshaft and crankshaft grinding operations, while electronic packaging represents the fastest-growing structural pocket as gallium nitride and silicon carbide power devices drive substrate cooling requirements. Coated cBN products command premium positioning where tool life extension justifies per-unit price multiples over conventional powder formulations.
The EPA enforces workplace respirable crystalline silica limits that shape cBN powder handling protocols and personal protective equipment mandates across United States manufacturing facilities, while REACH registration requirements in Europe restrict certain hexavalent chromium-containing bond chemistries used in conventional cBN grinding wheel formulations. China's SAMR implements national standards for synthetic superabrasive purity grades that determine market access for imported cBN materials. Stakeholders must monitor evolving semiconductor substrate specifications and regional mining equipment demand cycles to calibrate capacity commitments across powder synthesis and compact fabrication stages.
Market Dynamics
High-pressure high-temperature synthesis capacity concentration in China's Shanxi Province is restructuring supply availability for electronics-grade cubic boron nitride, while REACH compliance and EPA particulate standards simultaneously elevate specification barriers for market entry.
Growth Catalysts
- Gallium nitride power devices:Thermal conductivity requirements for substrate cooling are pulling premium cBN grades into semiconductor packaging applications at accelerating rates.
- REACH registration requirements:European restrictions on hexavalent chromium bond chemistries are advantaging compliant synthetic superabrasive suppliers with certified alternative formulations.
- Automotive camshaft grinding:Hardened steel machining operations in Germany and Japan are expanding coated cBN procurement to extend tool life in high-volume production environments.
Market Restraints
- HPHT energy intensity:Synthesis of electronics-grade crystals requires sustained energy inputs that concentrate production in regions with subsidized industrial power.
- Shanxi Province concentration:Domestic Chinese crystal growers control expanding shares of high-purity powder capacity, creating geographic supply vulnerability.
- Diamond substitute persistence:Non-ferrous machining applications retain diamond abrasive preference where iron-carbon reactivity is absent.
Strategic Opportunities
- Tool reconditioning services:Subscription-based performance monitoring software is capturing value migration from product sales to recurring revenue models in advanced manufacturing supply chains.
- SAMR national standards:China's purity grade certifications create pathways for compliant importers to access domestic electronics manufacturing demand.
- Ceramic bond integration:Vertical control of bond system formulation enables differentiated grinding wheel performance positioning against commodity powder competitors.
Industry Challenges
- Crystallography expertise scarcity:HPHT synthesis operation requires specialized personnel that outpaces technical training pipeline output in established manufacturing regions.
- Respirable silica compliance:OSHA workplace exposure mandates necessitate capital-intensive ventilation and personal protective equipment deployment across United States handling facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cubic Boron Nitrates Market |
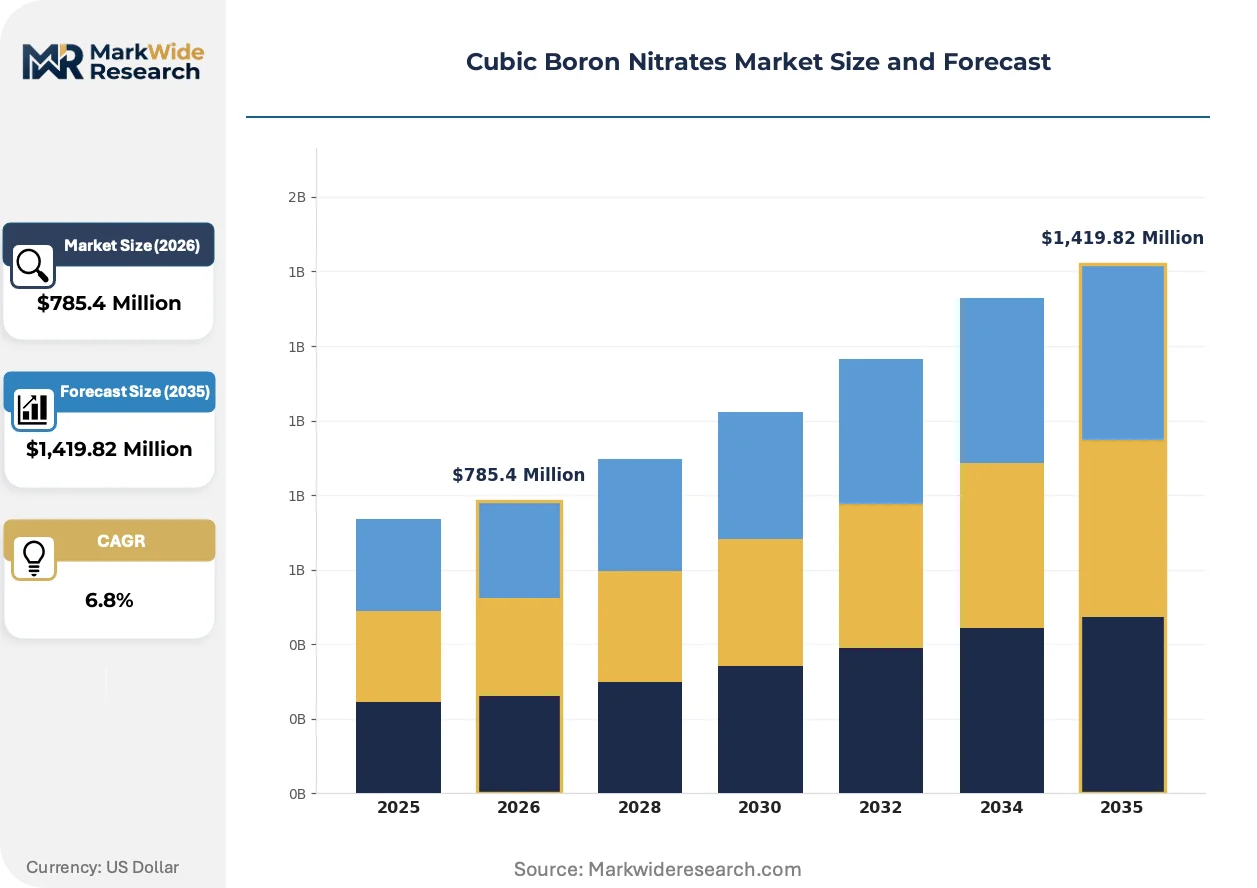
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,419.82 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Coated, Compacts Application: Abrasives, Cutting Tools, Electronic Packaging, Protective Coatings End User: Aerospace, Automotive, Electronics, Energy Distribution Channel: Direct Sales, Online Retail, Distributors, Dealers |
| Companies Covered | Saint-Gobain, 3M, Element Six, Sandvik AB, Showa Denko, Sumitomo Electric Industries, ILJIN Diamond, Momentive Performance Materials, H.C. Starck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cubic Boron Nitrates Market Strategic Shifts
Material science advances and regulatory stringency are compressing traditional product lifecycles while opening adjacent application spaces for thermally stable superabrasives.
Polycrystalline cBN compact formulations are converging with ceramic matrix composite integration techniques developed for aerospace turbine component machining. Tier-one automotive suppliers in Stuttgart and Nagoya are qualifying these hybrid tools for Inconel exhaust valve seat cutting where thermal shock resistance determines batch consistency. The convergence is compressing acceptable price premiums for coated products against conventional bonded wheels.
EPA enforcement of respirable crystalline silica limits is mandating closed-system powder handling infrastructure across United States grinding wheel fabrication plants. Facility retrofit timelines extend 18-24 months for mid-cap producers, advantaging early-compliant operators with available capacity. Bond chemistry R&D is accelerating water-based formulation development to eliminate hexavalent chromium from European-bound product lines.
After-sales service unbundling is fragmenting traditional distributor relationships as cutting tool manufacturers deploy direct telemetry for wear-state monitoring. German automotive OEMs now specify performance-guaranteed contracts rather than per-unit procurement for camshaft grinding operations. This restructuring concentrates volume with vertically integrated suppliers capable of crystal growth, compact fabrication, and predictive analytics deployment.
Cubic Boron Nitrates Market Segmentation
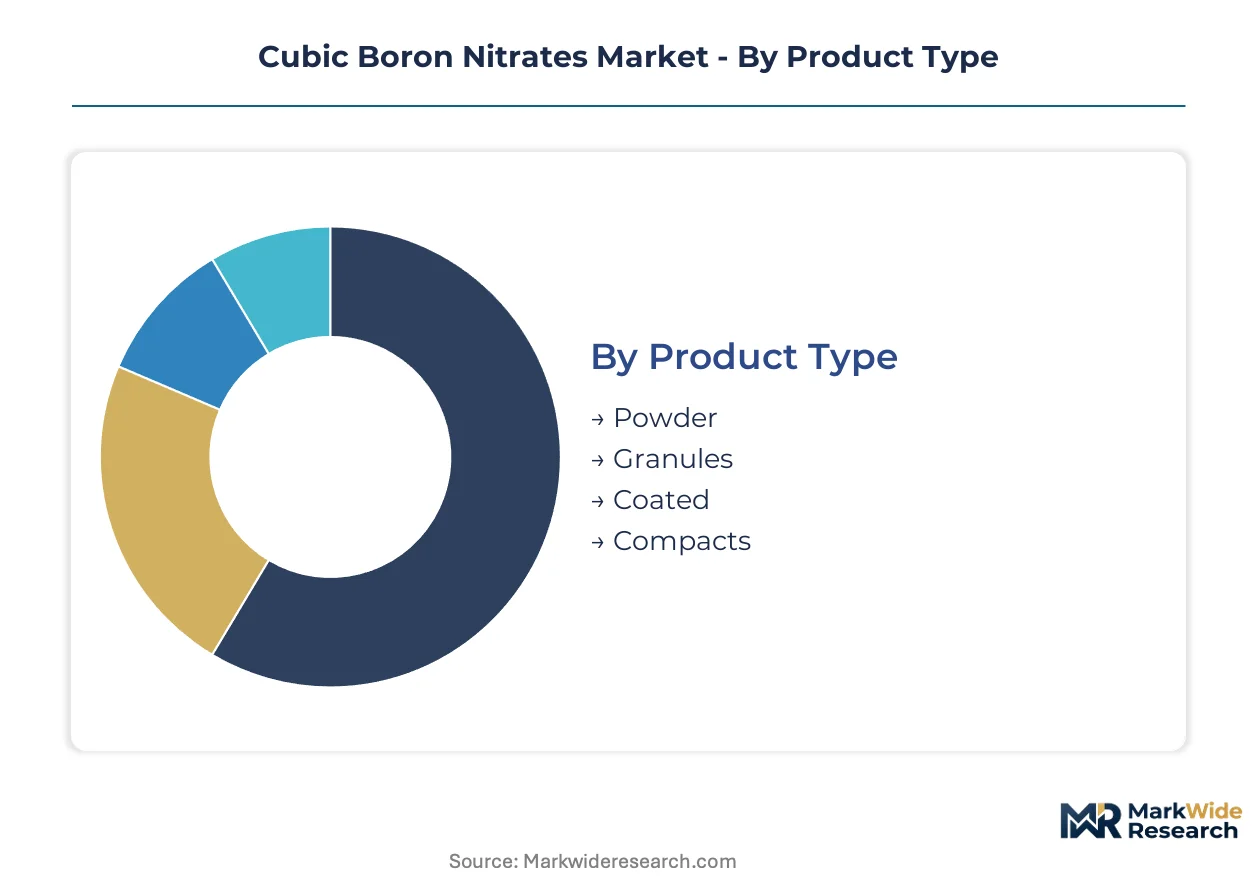
Cubic boron nitrate market segmentation reveals distinct procurement patterns across product forms, with coating technologies and compact geometries commanding premium positioning in precision manufacturing supply chains. Application-driven demand fragmentation requires suppliers to maintain parallel certification tracks for abrasive grinding versus semiconductor thermal management specifications.
Product Type:
Buyers differentiate primarily by manufacturing process compatibility and surface area requirements for bond system integration.
- Powder:Fine crystalline grades range from 0.5 to 500 micrometers in controlled particle size distributions, serving as feedstock for bonded grinding wheels and loose abrasive lapping compounds. Demand concentrates in Germany's automotive camshaft grinding sector where Bayerische Motoren Werke and Daimler Truck specify narrow particle distribution tolerances for batch consistency.
- Compacts:Polycrystalline cBN sintered bodies integrate with tungsten carbide substrates through high-pressure high-temperature bonding, delivering cutting edges for hardened steel turning operations. Japanese machine shops in Aichi Prefecture are expanding compact procurement for Inconel exhaust valve machining as thermal shock resistance specifications tighten.
- Coated:Chemical vapor deposition layers of titanium nitride or aluminum oxide extend tool life through reduced crater wear in high-speed cutting.
- Granules:Agglomerated forms suit blast finishing and mass finishing applications where controlled breakdown rates determine surface roughness outcomes.
Powder leads volumes today; compacts are gaining share fastest.
Application:
End-use specifications diverge sharply between mechanical material removal and passive thermal management functions.
- Abrasives:Bonded wheels and honing stones leverage cBN's chemical inertness against ferrous workpieces where diamond suffers graphitization. Automotive crankshaft production lines in Stuttgart and Detroit specify vitrified bond wheels with ceramic bond systems for 60 HRC steel finishing operations.
- Electronic Packaging:Heat spreader substrates exploit thermal conductivity exceeding 600 W/m·K for gallium nitride power device cooling. China's Shanxi Province crystal growers are scaling high-purity powder output specifically for substrate manufacturers serving Shenzhen semiconductor packaging facilities.
- Cutting Tools:Indexable inserts and solid round tools address nickel-based superalloy machining in aerospace turbine blade production.
- Protective Coatings:Thin-film deposition onto tool substrates enhances oxidation resistance above 800°C in dry machining environments.
Abrasives leads volumes today; electronic packaging is climbing the fastest.
End User:
Procurement scale and specification stringency vary dramatically between volume-driven automotive and qualification-heavy aerospace segments.
- Automotive:Powertrain component manufacturers specify coated cBN grades for camshaft and crankshaft grinding where throughput economics dominate tooling decisions. German OEMs in Baden-Württemberg are consolidating suppliers around vertically integrated providers offering crystal growth through predictive wear analytics.
- Electronics:Semiconductor packaging houses demand 99.9%+ purity grades with controlled oxygen content for thermal interface materials in gallium nitride device substrates.
- Aerospace:Turbine engine manufacturers require extensive qualification documentation for Inconel and titanium alloy machining applications.
- Energy:Oil and gas drilling tool producers specify wear-resistant compacts for downhole bearing applications in abrasive formations.
Automotive leads volumes today; electronics is expanding most quickly.
Distribution Channel:
Channel selection reflects customer technical support requirements and order fragmentation patterns across end-user scale tiers.
- Direct Sales:Large-volume automotive and aerospace accounts negotiate multi-year supply agreements with technical service attachments, bypassing distributor margins for crystal growth through compact fabrication integration. German automotive OEMs now specify direct telemetry-enabled performance contracts rather than per-unit procurement.
- Distributors:Regional inventory stocking and application engineering support serve mid-tier job shops and specialty manufacturers with fragmented order patterns.
- Online Retail:Standardized powder grades and consumable wheels move through digital channels for small-scale metalworking operations.
- Dealers:Local representation provides grinding wheel specification assistance and reconditioning services for captive maintenance departments.
Direct sales leads volumes today; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan command premium-grade procurement for automotive grinding operations, while China's Shanxi Province scales electronics-grade synthesis capacity at subsidized energy costs that reshape supply availability.
United States
Automotive powertrain manufacturers in Detroit specify coated cBN grades for crankshaft finishing where throughput economics dominate. EPA respirable crystalline silica enforcement mandates closed-system powder handling infrastructure with 18-24 month retrofit timelines for mid-cap producers. Grinding wheel fabrication clusters in Ohio and Michigan face compliance-driven consolidation pressure.
Germany
Bayerische Motoren Werke and Daimler Truck in Baden-Württemberg consolidate suppliers around vertically integrated providers offering crystal growth through predictive wear analytics. REACH registration restricts hexavalent chromium bond chemistries, advantaging compliant synthetic superabrasive suppliers with certified alternatives. Stuttgart anchors European demand for Inconel exhaust valve machining tools.
China
Domestic crystal growers in Shanxi Province scale high-pressure high-temperature synthesis capacity for semiconductor packaging substrates serving Shenzhen facilities. SAMR national standards for synthetic superabrasive purity grades determine market access for imported materials. Subsidized industrial electricity concentrates electronics-grade production in this northern province.
Japan
Machine shops in Aichi Prefecture expand compact procurement for thermal shock-resistant Inconel machining as aerospace specifications tighten. METI industrial policy supports advanced materials manufacturing competitiveness against regional rivals. Nagoya-based automotive suppliers qualify hybrid ceramic matrix composite tools for exhaust valve seat cutting.
South Korea
Memory and logic chip packaging houses demand 99.9%+ purity grades with controlled oxygen content for gallium nitride device thermal management. The country's national industrial standards body aligns certification requirements with export market access protocols. Seoul Capital Area semiconductor clusters pull premium cBN grades into substrate cooling applications.
Cubic Boron Nitrates Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with coated product premiums concentrating among integrated crystal growers while commodity powder flows through regional distributors. The vendor base organizes into three tiers: multinational material science conglomerates with captive synthesis capacity, mid-scale compact fabricators serving automotive tier-one suppliers, and regional powder processors filling spot orders for job shops. Consolidation pressures favor players with backward integration into HPHT crystal growth and forward integration into telemetry-enabled tool services. Strategic moves center on ceramic bond chemistry R&D and direct automotive OEM contracting bypassing traditional distribution.
Among diversified industrial material groups, Saint-Gobain and 3M occupy positions spanning bond system formulation through finished grinding wheel supply. Element Six exemplifies the synthetic diamond heritage archetype, anchoring European precision engineering markets through inherited high-pressure synthesis expertise. Showa Denko sits within the high-purity specialization tier, representing semiconductor-facing suppliers where thermal conductivity specifications command premium positioning against commodity grades.
| Leading Market Players |
|---|
| Saint-Gobain |
| 3M |
| Element Six |
| Sandvik AB |
| Showa Denko |
| Sumitomo Electric Industries |
| ILJIN Diamond |
| Momentive Performance Materials |
| H.C. Starck |
| Others |
Value Chain & Pricing Dynamics
German automotive OEM consolidation around performance-guaranteed contracts rather than per-unit procurement is forcing suppliers to absorb tool-life risk and recapture margin through predictive service bundling. This demand-side restructuring concentrates pricing power with vertically integrated crystal growers capable of telemetry-enabled wear analytics deployment.
Pricing Analysis
Capacity additions in China's Shanxi Province are reshaping price floors for electronics-grade powder as subsidized energy inputs undercut established synthesis economics. Three-tier pricing structure across premium, standard, and economy levels separates coated compact formulations from uncoated compacts from commodity powder grades. Cost compression in standard-tier bonded wheels is intensifying because REACH-compliant ceramic bond R&D elevates formulation expenses. Tier-one automotive suppliers in Stuttgart and Nagoya exhibit least price sensitivity due to throughput economics dominance, while mid-cap job shops in fragmented distributor channels remain most responsive to per-unit discounts.
Supply Chain Analysis
China's SAMR national standards for synthetic superabrasive purity grades are reshaping sourcing requirements for electronics-grade material entering domestic semiconductor packaging facilities. HPHT synthesis capacity concentrates in China, Germany, and Japan, with raw material feedstock drawing from hexagonal boron nitride precursors sourced through controlled thermal processing operations. Single-source vulnerability concentrates in Shanxi Province crystal growth facilities where subsidized industrial electricity anchors electronics-grade output. Distribution runs through direct sales channels for large-volume automotive accounts and regional distributors serving fragmented job shop demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as gallium nitride power device thermal specifications pull premium cBN grades into semiconductor packaging applications where purity thresholds command sustained margin premiums.
For Market Incumbents: Hedge diamond substitute encroachment in non-ferrous machining by accelerating ceramic matrix composite tool development for Inconel exhaust valve applications. Deepen backward integration into HPHT crystal growth capacity in Germany and Japan to defend against Shanxi Province cost structures. Capture service revenue migration through predictive wear analytics deployment for Stuttgart-based automotive OEMs. For New Entrants and Emerging Players: Enter via white-space targeting of water-based bond chemistry formulations for REACH-compliant European grinding wheel production. Focus initial penetration on mid-tier U.S. grinding wheel fabricators facing EPA respirable silica compliance-driven retrofit timelines. Qualify compact supply relationships with Aichi Prefecture machine shops seeking thermal shock-resistant Inconel machining solutions. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized semiconductor-facing suppliers possessing 99.9%+ purity certification pathways under China's SAMR standards. Long-term viability over a multi-year horizon favors acquisition targets combining captive HPHT synthesis with ceramic bond formulation expertise. Monitor gallium nitride power device substrate qualification timelines as inflection indicator for electronics-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| HPHT Synthesis Capacity Expansion | Shanxi Province crystal growers scale output for Shenzhen semiconductor packaging demand. |
| Ceramic Bond Chemistry R&D | Saint-Gobain and compliant suppliers capture REACH-restricted hexavalent chromium substitution opportunities. |
| Performance-Guaranteed Contracting | German automotive OEMs shift procurement from per-unit to telemetry-enabled tool-life agreements. |
| Water-Based Formulation Development | Mid-cap U.S. fabricators eliminate hexavalent chromium to access European-bound product lines. |
| Predictive Analytics Platform Deployment | Element Six and integrated suppliers capture value migration from product sales to recurring service revenue. |
Study Parameters
Coverage spans Germany, Japan, China, and the United States, with primary inputs from each regional cluster combining interviews with HPHT synthesis plant managers, automotive Tier 1 procurement leads, semiconductor packaging technical directors, and grinding wheel distribution channel partners. Secondary validation draws from EPA enforcement documentation, ECHA REACH registration databases, SAMR national standards filings, and SEC disclosures from listed superabrasive suppliers. Bottom-up volume builds across powder, compact, and coated product tiers triangulate against top-down spending estimates from end-use industries.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions include product form, application function, end-user industry, and regional production hub. CAGRs derive from fitted growth curves incorporating HPHT energy cost trajectories, semiconductor substrate specification evolution, and automotive production cycle indicators. Forecast inputs specifically model Shanxi Province capacity expansion timelines and REACH compliance transition schedules.
The model holds under stable regulatory enforcement intensity and continued gallium nitride device adoption; deviation in EPA particulate standard stringency or automotive electrification pace would shift electronics-grade versus abrasives demand balance. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Europe Next Generation Anode Materials Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Borophene Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Global Diamond-Like Carbon (DLC) Market
Advanced Materials
Wood Foam Market
Advanced Materials
Thermal Spray Market
Advanced Materials
Reinforcement Materials Market
Advanced Materials
Thermal Spray Materials Market
Advanced Materials
Carbon Prepreg Market
Advanced Materials
Transparent Wood Market
Advanced Materials
North America Plasma Powder Market
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Artificial Marble Products Market
Advanced Materials
Natural Single Crystal Diamond Market