
 Liquid Thermal Interface Materials Market | 2026-2036
Liquid Thermal Interface Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Thermal Interface Materials Market Foresight
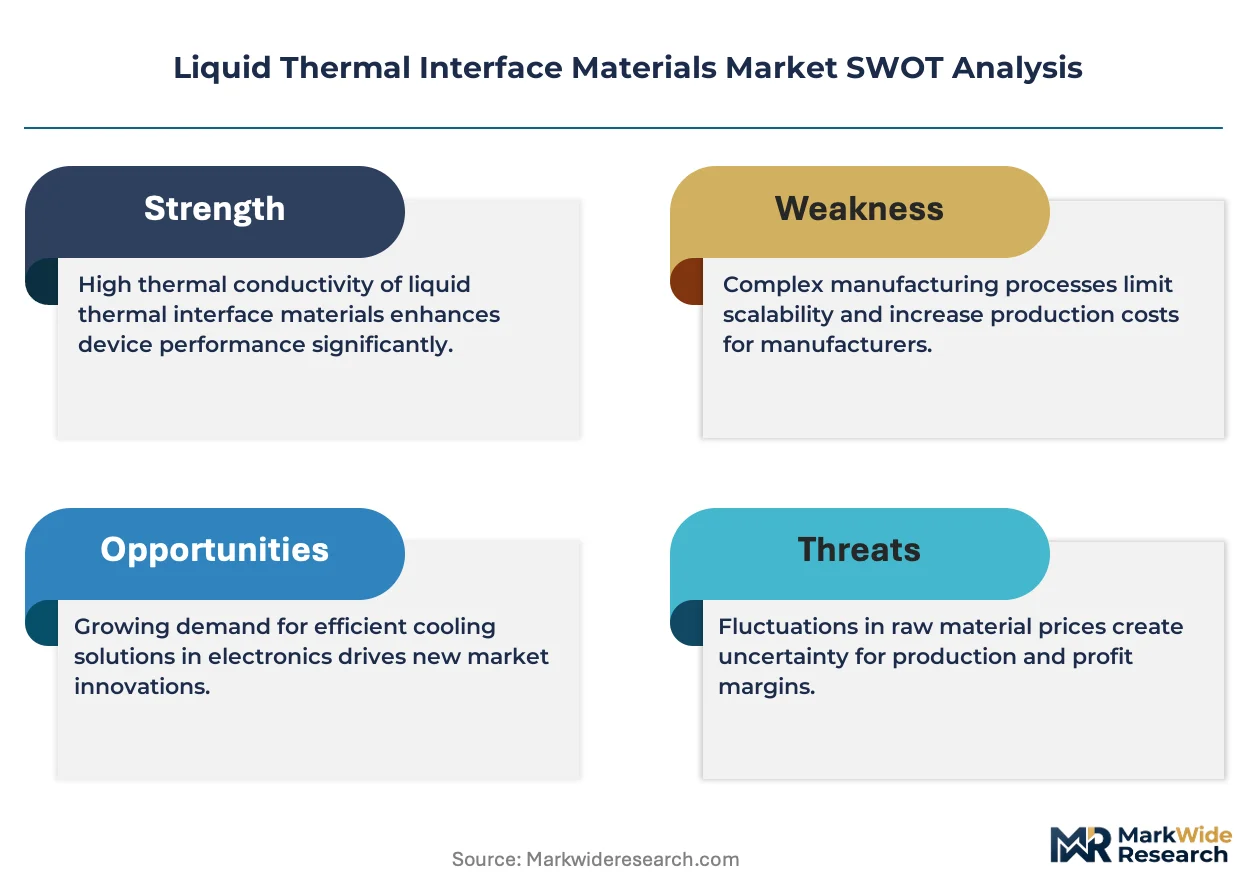
Buyer concentration among hyperscale data center operators and electric vehicle OEMs is hardening procurement leverage across the supply base. Henkel AG & Co. KGaA anchors European automotive electronics programs with localized compounding capacity. Dow competes through backward integration into silicone precursor supply. Shin-Etsu Chemical dominates Asian semiconductor foundry channels with gel-based formulations engineered for sub-3nm node thermal budgets.
Liquid thermal interface materials are flowable compounds—typically silicone, hydrocarbon, or phase-change matrices loaded with ceramic or metallic fillers—applied between heat-generating components and dissipating surfaces to minimize thermal contact resistance. These materials operate across thermal conductivity ranges from 0.5 W/m·K for non-conductive grades to above 8 W/m·K for metal-filled variants, enabling continuous heat transfer in assemblies where solid gap pads cannot conform to microscopic surface irregularities. Gel-based products command premium positioning in semiconductor test and burn-in applications where automated dispensing and reworkability protect high-value dies. Water-based formulations occupy cost-sensitive consumer electronics segments where thermal loads remain moderate and environmental discharge regulations constrain solvent use. Conductive variants sustain the fastest trajectory as gallium nitride and silicon carbide power devices multiply heat flux densities beyond legacy material limits.
The EPA regulates volatile organic compound emissions from solvent-based TIM manufacturing in the United States, pushing formulators toward aqueous and 100% solids systems. REACH and RoHS frameworks in Europe restrict halogenated flame retardants and heavy metal fillers, compelling reformulation of legacy conductive pastes. China's MEE enforces dual carbon compliance on chemical production, adding carbon intensity audits to material qualification protocols. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent substance restrictions threaten to fragment product portfolios and inflate compliance overhead for suppliers serving multiple end markets.
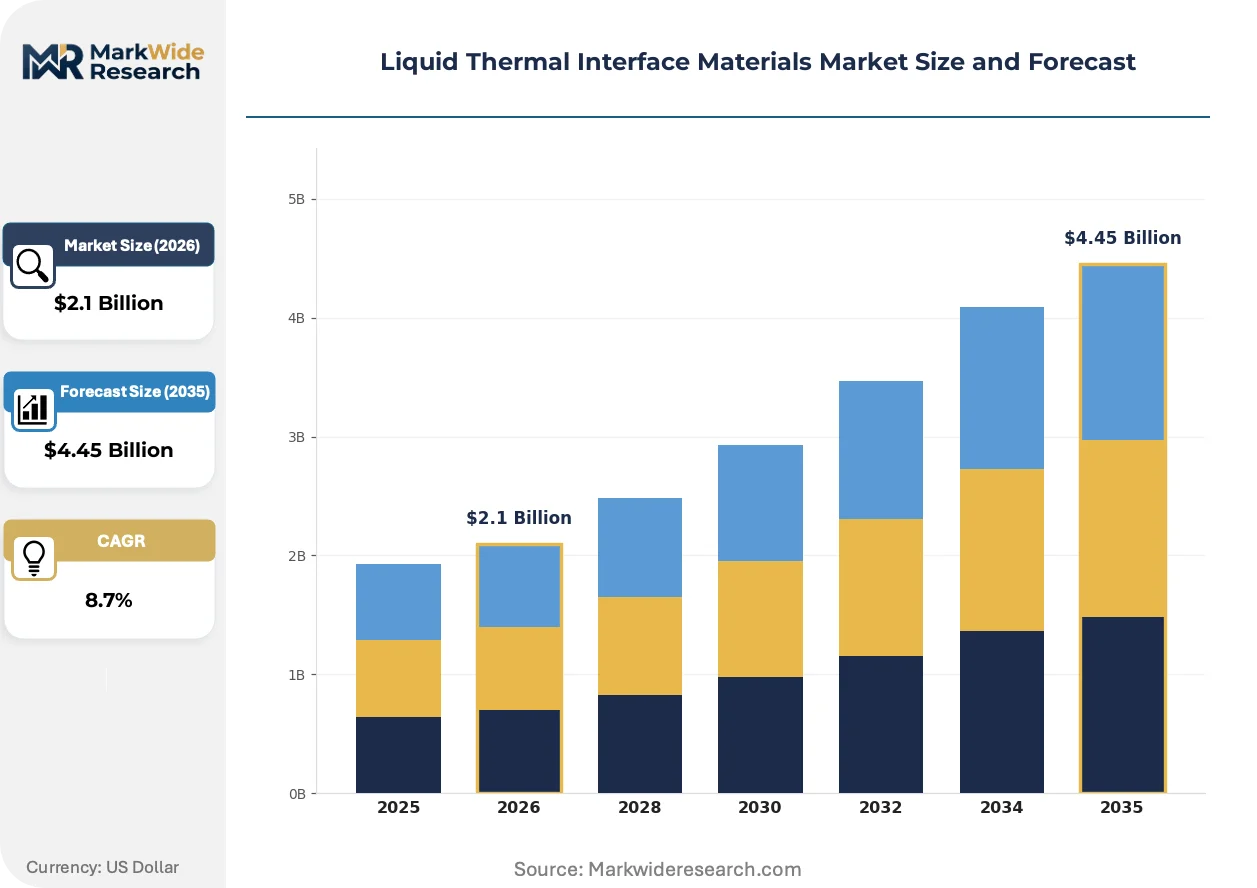
Market Dynamics
Heat flux densities from gallium nitride and silicon carbide power devices now exceed the thermal management capacity of legacy gap pad materials, forcing a wholesale transition to flowable compounds that conform to microscopic surface irregularities at sub-3nm semiconductor nodes.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for high-global-warming-potential refrigerants accelerate substitution with phase-change thermal interface materials in automotive battery packs and data center cooling loops.
- East Asian semiconductor fabrication:Taiwan and South Korea foundries are scaling automated dispensing of gel-based formulations for test and burn-in applications where reworkability protects high-value dies.
- China's dual carbon goals:Carbon intensity audits under MEE enforcement add material qualification protocols that favor aqueous and 100% solids TIM systems over solvent-based alternatives.
Market Restraints
- Silicone precursor concentration:Dow's backward integration into silicone monomer supply creates dependency risk for non-integrated formulators competing on metal-filled conductive variants.
- Halogenated flame retardant restrictions:REACH and RoHS frameworks in Europe compel costly reformulation of legacy conductive pastes, compressing margins for suppliers serving multi-jurisdictional end markets.
- Technical ceiling on thermal conductivity:Ceramic filler loading limits in flowable matrices constrain performance below what bare metal interfaces achieve, restricting penetration in extreme heat flux defense electronics.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Contract assembly migration to Indian smartphone and server production clusters creates first-mover advantage for localized TIM compounding capacity.
- Water-based formulation penetration:EPA volatile organic compound emission rules push formulators toward aqueous systems in cost-sensitive consumer electronics where thermal loads remain moderate.
- GaN-SiC convergence:Power device architectures combining gallium nitride switching with silicon carbide substrates multiply heat flux densities beyond legacy material limits, opening premium positioning for metal-filled variants above 8 W/m·K.
Industry Challenges
- Sub-3nm thermal budget engineering:Semiconductor foundries demand gel-based products with automated dispensing precision that few formulators have validated at production scale.
- Regulatory fragmentation overhead:Divergent substance restrictions between EPA, REACH, and China's MEE threaten to fragment product portfolios and inflate compliance costs for suppliers serving multiple end markets.
- Carbon audit integration:Dual carbon compliance protocols require formulators to embed lifecycle carbon accounting into material qualification workflows, extending time-to-revenue for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Thermal Interface Materials Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based, Non-conductive, Gel-based, Conductive Application: Consumer Electronics, Automotive Electronics, Industrial Equipment, Telecommunications End User: OEMs, Aftermarket Providers, Manufacturers, Energy Sector Distribution Channel: Retail, Online, Direct Sales, Wholesalers |
| Companies Covered | Honeywell International Inc., 3M, Henkel AG & Co. KGaA, Parker Hannifin Corporation, Dow, Indium Corporation, Momentive, Shin-Etsu Chemical, Fujipoly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Thermal Interface Materials Market Shifts & Advancements
Formulation chemistry and dispensing automation are converging to address thermal management gaps that solid gap pads cannot bridge, while regulatory pressure on solvent systems accelerates aqueous and 100% solids alternatives.
Metal-filled conductive variants are expanding into defense and aerospace power electronics where gallium nitride and silicon carbide devices generate heat flux densities exceeding 500 W/cm². Prime contractors in the United States and select European NATO suppliers are qualifying these materials for radar and directed energy applications. The technology is expanding into segments previously served by thermal epoxies, compressing the addressable market for non-reworkable alternatives.
China's MEE enforcement of dual carbon goals on chemical production is tightening carbon intensity audits for material qualification protocols. Domestic formulators must now submit lifecycle carbon data alongside thermal performance specifications to qualify for automotive and data center procurement programs. Suppliers without verified low-carbon supply chains face exclusion from state-backed infrastructure tenders in Beijing and Shanghai metropolitan clusters.
Hyperscale data center operators are consolidating supplier relationships around formulators offering automated dispensing integration and predictive inventory management. Channel relationships that relied on distributor stocking are giving way to direct vendor-managed inventory agreements with real-time consumption monitoring. This pattern concentrates most visibly in Northern Virginia and Frankfurt am Main cloud campus developments where thermal interface material consumption exceeds container-scale monthly volumes.
Liquid Thermal Interface Materials Market Segmentation
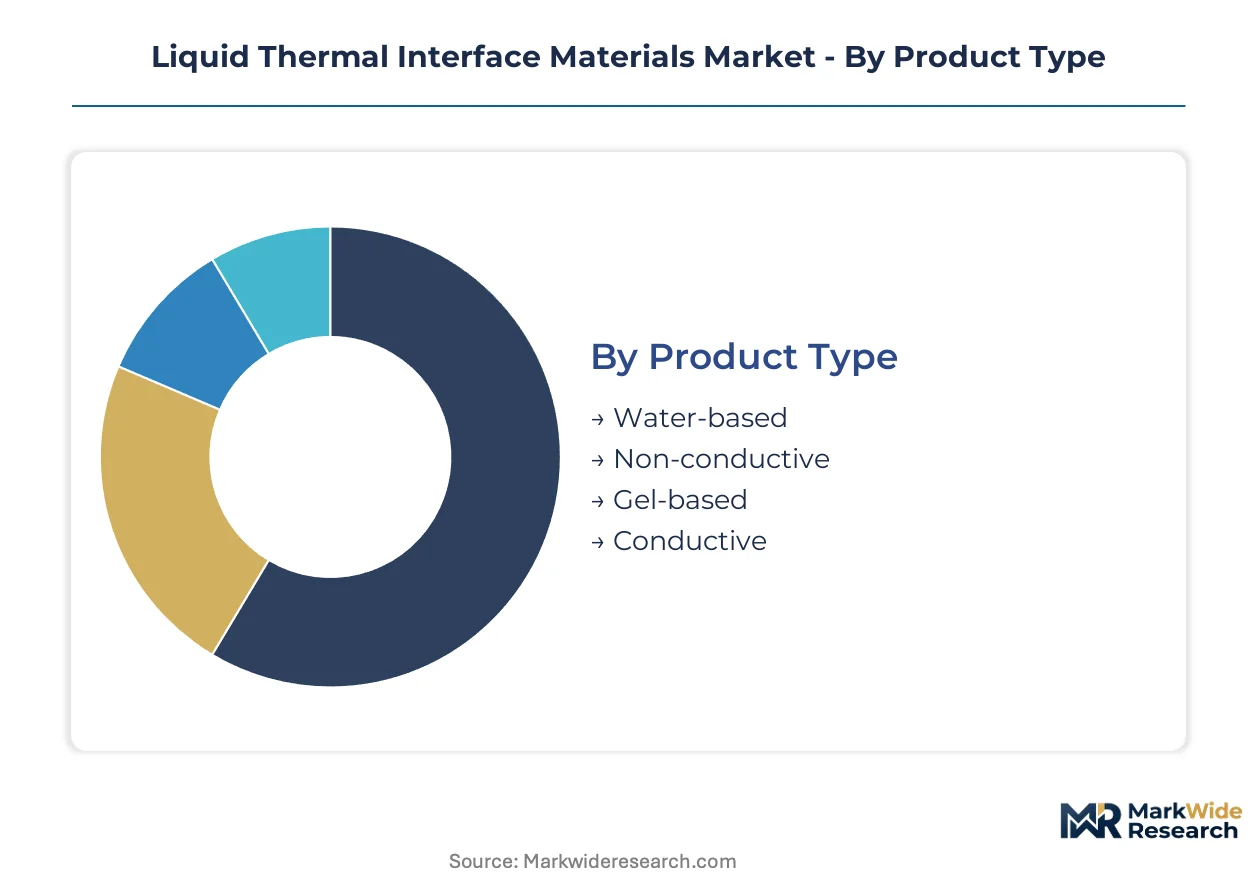
Liquid thermal interface materials segment across formulation chemistry, application thermal load, procurement scale, and channel access. Each dimension reveals distinct margin structures and competitive dynamics that shape supplier positioning.
Product Type:
Volume concentrates in cost-optimized aqueous and non-conductive grades, while premium positioning belongs to metal-filled conductive and precision gel formulations.
- Water-based:Aqueous emulsions with moderate ceramic filler loading serve cost-sensitive consumer electronics where EPA volatile organic compound rules constrain solvent alternatives. Smartphone and laptop assembly lines in Vietnam and Mexico specify these grades for thermal loads below 50 W/cm².
- Non-conductive:Silicone or hydrocarbon matrices loaded with alumina or boron nitride isolate electrically active components in automotive battery management systems. Hyundai and BYD procurement programs specify non-conductive grades for cell-to-pack thermal barriers where dielectric strength exceeds 10 kV/mm.
- Gel-based:Thixotropic silicone formulations enable automated dispensing with reworkability for semiconductor test sockets.
- Conductive:Metal-filled pastes with thermal conductivity above 8 W/m·K target gallium nitride power modules.
Today's leader: Non-conductive. Tomorrow's challenger: Conductive.
Application:
Application segmentation tracks heat flux density and regulatory exposure, with automotive and telecom commanding premium pricing against cost-optimized consumer tiers.
- Consumer Electronics:Water-based and standard silicone grades dominate laptop, tablet, and smartphone assembly where thermal budgets stay moderate and environmental discharge rules favor aqueous systems. Foxconn and Pegatron procurement in Taiwan and India drives volume.
- Automotive Electronics:Phase-change and non-conductive compounds manage battery pack thermal runaway risks and power inverter heat dissipation. EU F-Gas Regulation compliance accelerates substitution away from refrigerant-dependent cooling toward solid-state thermal management.
- Industrial Equipment:Motor drives and automation controllers specify mid-range silicone greases with extended service life.
- Telecommunications:Base station power amplifiers and optical transceivers deploy gel-based and conductive variants for 5G infrastructure thermal cycling endurance.
Automotive electronics absorbs the steepest expansion trajectory as electric vehicle production scales.
End User:
Procurement scale and technical integration requirements separate integrated OEM programs from fragmented aftermarket channels.
- OEMs:Tesla, Samsung, and Apple direct procurement teams negotiate vendor-managed inventory agreements with real-time consumption monitoring, favoring formulators with automated dispensing integration.
- Aftermarket Providers:Independent repair networks and refurbishment specialists purchase smaller lots through distributor channels with limited technical support.
- Manufacturers:Contract electronics assemblers in India's PLI scheme zones specify TIMs for smartphone and server production migration.
- Energy Sector:Solar inverter and wind turbine OEMs source thermal materials for power conversion electronics in utility-scale installations.
OEM direct procurement commands pricing power. Aftermarket channels face margin compression from distributor markups.
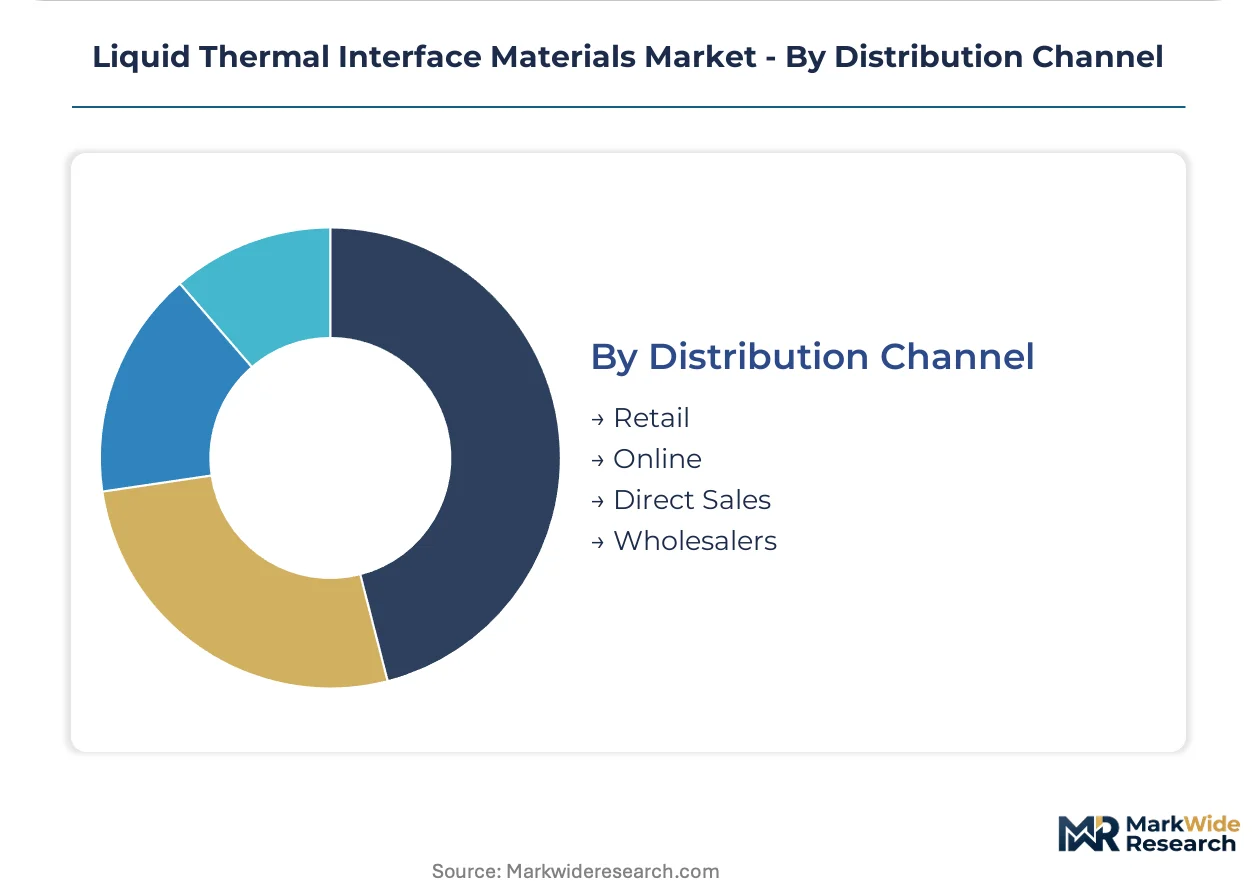
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and supply chain control preferences across customer tiers.
- Retail:Small-lot sales to hobbyists and repair technicians through electronics component stores with limited thermal performance data.
- Online:E-commerce platforms serve mid-size contract manufacturers with standardized grades and rapid delivery.
- Direct Sales:Henkel and Dow field engineers co-develop formulations with automotive and semiconductor OEMs at dedicated technical centers.
- Wholesalers:Regional distributors stock standard silicone greases for industrial maintenance and repair operations.
Direct sales captures the highest value contracts. Online channels are gaining share fastest among mid-tier assemblers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and thermal engineers concentrate in East Asian semiconductor clusters, German automotive corridors, and North American defense electronics hubs, anchoring regional formulation capabilities to distinct end-use demand centers.
China
Electric vehicle OEMs and hyperscale data center operators in Beijing and Shanghai metropolitan clusters drive procurement of aqueous TIM systems. MEE carbon intensity audits now embed lifecycle accounting into material qualification protocols for state-backed infrastructure tenders. Yangtze River Delta chemical parks host domestic formulators scaling metal-filled conductive variants for gallium nitride power modules.
United States
Defense prime contractors and cloud campus developers in Northern Virginia consume container-scale monthly volumes of gel-based and metal-filled formulations. EPA volatile organic compound rules push formulators toward 100% solids systems for consumer electronics assembly. Greater Boston and Pacific Northwest semiconductor equipment vendors qualify automated dispensing integration for sub-3nm node thermal budgets.
Germany
Automotive electronics programs at BMW, Volkswagen, and Mercedes-Benz specify phase-change compounds for battery thermal management under EU F-Gas Regulation compliance timelines. REACH and RoHS frameworks restrict halogenated flame retardants, compelling reformulation of legacy conductive pastes. Baden-Württemberg and Bavaria host Henkel's localized compounding capacity serving European OEM direct procurement.
South Korea
Samsung Electronics and SK Hynix foundries in Seoul Capital Area and Busan-Ulsan clusters scale automated dispensing of gel-based formulations for test and burn-in applications. Domestic formulators face carbon audit integration requirements under tightening environmental enforcement. Daegu-Gyeongbuk electronics manufacturing corridors absorb premium TIM grades for 5G infrastructure thermal cycling endurance.
Taiwan
TSMC and MediaTek drive concentrated demand for sub-3nm node thermal budget materials in Hsinchu Science Park and Tainan wafer fabrication facilities. Gel-based products with reworkability protect high-value dies during semiconductor test socket operations. Local distributors face displacement as hyperscale operators consolidate around direct vendor-managed inventory agreements with real-time consumption monitoring.
Liquid Thermal Interface Materials Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry tiers, creating a bifurcated structure where scale-driven material science giants anchor automotive and semiconductor channels while regional compounders serve cost-optimized consumer segments. The vendor base organizes around three strategic archetypes: backward-integrated silicone precursor producers, application-engineered formulation houses with automated dispensing partnerships, and carbon-audit-compliant domestic suppliers serving state-backed procurement. Competitive moves concentrate on M&A to secure filler supply chains and capacity expansion in Indian PLI scheme zones to capture smartphone and server assembly migration.
Among diversified chemical conglomerates, Dow and Henkel AG & Co. KGaA exemplify contrasting integration strategies—Dow through captive silicone monomer supply and Henkel through localized automotive compounding. Shin-Etsu Chemical occupies a specialist position within Asian semiconductor foundry channels. These three anchors represent the competitive tension between upstream material control and application-specific formulation engineering that defines procurement leverage dynamics.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| 3M |
| Henkel AG & Co. KGaA |
| Parker Hannifin Corporation |
| Dow |
| Indium Corporation |
| Momentive |
| Shin-Etsu Chemical |
| Fujipoly |
| Others |
Supply & Pricing Matrix
Backward integration into silicone monomer supply anchors Dow's pricing power across metal-filled conductive variants while non-integrated formulators face raw material cost volatility. Henkel's localized compounding in Baden-Württemberg captures automotive OEM premiums through EU F-Gas Regulation compliance positioning, whereas aqueous system producers compete on carbon audit scores for Chinese state-backed tenders.
Pricing Analysis
Capacity additions in India's PLI scheme zones are reshaping price floors for standard silicone greases serving contract electronics assembly. Three-tier pricing structure across premium, standard, and economy levels separates gel-based semiconductor formulations from water-based consumer grades and metal-filled defense variants. Cost compression in aqueous systems intensifies because EPA volatile organic compound rules constrain solvent alternatives. Smartphone assemblers in Vietnam exhibit highest price sensitivity; defense prime contractors in Northern Virginia show lowest.
Supply Chain Analysis
Silicone precursor supply rests on Japanese and German specialty chemical producers with captive monomer capacity. Ceramic filler loading draws from Chinese alumina processors and Korean boron nitride refiners. Single-source vulnerability concentrates in high-purity spherical alumina for sub-3nm node thermal budgets. Distribution runs through direct vendor-managed inventory agreements with hyperscale data center operators displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where gallium nitride and silicon carbide power device proliferation forces specification upgrades toward metal-filled variants above 8 W/m·K. Procurement consolidation around automated dispensing integration favors formulators with technical service depth over commodity suppliers.
For Market Incumbents: Lock in filler supply chains through long-term offtake agreements with Korean and Japanese ceramic processors to defend against raw material cost volatility. Secure automated dispensing validation partnerships with Greater Boston semiconductor equipment vendors before sub-3nm node thermal budget requirements harden qualification barriers. For New Entrants and Emerging Players: E-commerce platform routes into mid-tier Indian contract assemblers offer lowest competitive friction against established direct sales relationships. Target smartphone and server production clusters in India's PLI scheme zones with aqueous formulations qualified for moderate thermal loads below 50 W/cm². For Investors and Strategic Acquirers: Consolidation pressure builds where carbon audit capabilities separate qualified suppliers from excluded bidders in Chinese state-backed infrastructure tenders. Acquisition target archetype: domestic Chinese formulators with verified low-carbon supply chains and MEE qualification protocols already embedded. Watch gallium nitride power module ramp rates as inflection indicator for metal-filled variant demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursors | Dow's captive monomer supply insulates margin structure against ceramic filler cost volatility. |
| Automated Dispensing Partnership | Shin-Etsu's equipment vendor alliances protect semiconductor foundry channel exclusivity. |
| Carbon Audit Certification | MEE compliance protocols qualify domestic Chinese formulators for Beijing infrastructure tenders. |
| Localized Compounding Capacity | Henkel's Baden-Württemberg plant captures EU F-Gas Regulation-driven automotive premiums. |
| Metal-Filled Variant Scale-Up | Defense prime contractor qualification opens directed energy and radar thermal management segments. |
Research Methodology
Coverage spans East Asian semiconductor clusters, German automotive corridors, and North American defense electronics hubs, with primary inputs from each. Thermal materials procurement directors at hyperscale data center operators, automotive electronics platform engineers, and semiconductor foundry packaging specialists contributed operational data. Secondary validation drew from EPA emission filings, ECHA REACH substance restrictions, and Chinese MEE carbon audit protocols. Bottom-up formulation chemistry demand modeling triangulated against top-down end-use consumption estimates.
Granularity-level framing applied product type, application thermal load, and procurement scale dimensions at country-level resolution across the analysis window. CAGRs derived from segment-level volume trajectories weighted by regional production intensity. Forecast inputs incorporated gallium nitride power device deployment curves and EU F-Gas Regulation phase-down timelines.
The model assumes a particular technology adoption path; alternative pathways for liquid metal interface materials would alter the outlook. Forecasts reflect assumptions about sub-3nm node thermal budget engineering feasibility and MEE enforcement consistency. A small set of named triggers—defense procurement acceleration, Indian PLI scheme expansion, and carbon audit protocol harmonization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Advanced Polymer Composites Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Advanced Composite Materials Market
Advanced Materials
Lithium Tantalate Crystal Market
Advanced Materials
Rigid Foam Market
Advanced Materials
Chemistry 4.0 Market
Advanced Materials
Corundum Market
Advanced Materials
Cubic Boron Nitrates Market
Advanced Materials
US Graphene Market
Advanced Materials
Global Thermal Interface Materials Market
Advanced Materials
Extracellular Matrix Proteins Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Flexible Bio-Foams Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
North America Next Generation Anode Materials Market