
 Dental Resins Market | 2026-2036
Dental Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Resins Market Outlook
Glass ionomer formulations are recalibrating cost-performance tradeoffs in pediatric and geriatric restorations. GC Corporation leverages captive R&D pipelines to sustain leadership in bioactive glass compositions. Kerr Corporation anchors North American supply chains through direct dental dealer networks. 3M Company differentiates via proprietary nanofiller technology that commands premium positioning in aesthetic dentistry.
Dental resins comprise synthetic polymer matrices—typically bis-GMA, UDMA, or TEGDMA—loaded with inorganic filler particles ranging from 0.04 to 20 microns, cured through visible-light photoinitiation to produce hardened restorations with compressive strengths exceeding 250 MPa. Their primary purpose is to reconstruct tooth structure while mimicking optical properties of natural enamel and dentin. Composite resins capture the dominant share of restorative value owing to universal applicability across anterior and posterior indications. Nanohybrid resins represent the fastest-expanding product tier as clinicians demand polishability rivaling porcelain alongside fracture resistance for load-bearing occlusal surfaces. Pre-filled syringe formats concentrate margin pools through reduced chairside waste and improved dosing precision.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations compel manufacturers to maintain exhaustive biocompatibility testing per ISO 10993 protocols before commercial release. Japan's PMDA enforces additional local clinical evaluation standards that filter market entry for imported resin systems. Stakeholders must monitor evolving regulatory convergence between FDA recognition of international standards and MDR's heightened post-market surveillance demands to anticipate compliance cost trajectories.
Market Dynamics
EU MDR biocompatibility documentation requirements are restructuring competitive entry barriers for polymer-based dental materials, forcing manufacturers to rebuild quality management systems around post-market surveillance obligations.
Growth Catalysts
- Digital dentistry throughput:Chairside CAD/CAM systems in Germany, Japan, and the United States are accelerating material consumption rates as same-day restoration protocols become standard.
- ISO 10993-5 cytotoxicity testing harmonization:Converging biocompatibility standards across FDA and EU notified bodies are reducing redundant testing costs for multi-jurisdictional launches.
- Nanohybrid resin polishability:Orthodontic centers are expanding attachment applications where aesthetic performance matches porcelain veneer outcomes.
Market Restraints
- Silica filler supply concentration:High-purity nanofiller production clusters in limited geographic zones, creating input vulnerability for premium composite formulations.
- Japan PMDA clinical evaluation requirements:Mandatory local testing protocols extend registration timelines for imported resin systems by 18-24 months versus FDA 510(k) pathways.
- Glass ionomer cost-performance recalibration:Bioactive glass formulations in pediatric and geriatric segments are capturing price-sensitive volumes that composite resins cannot match.
Strategic Opportunities
- Direct dental dealer channel consolidation:North American supply chain reorganization is opening acquisition targets for integrated material-distribution platforms.
- Pre-filled syringe format premiumization:Dosing precision improvements are creating margin expansion in aesthetic dentistry practices seeking waste reduction.
- Photoinitiator wavelength optimization:Visible-light curing systems converging with LED polymerization technology are enabling faster chairside throughput in high-volume clinics.
Industry Challenges
- Biocompatibility documentation talent scarcity:ISO 10993 protocol expertise sits concentrated among specialized regulatory consultants, inflating compliance staffing costs.
- Legacy amalgam displacement certification:Dentist retraining requirements for composite placement techniques are slowing material substitution rates in established practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Resins Market |
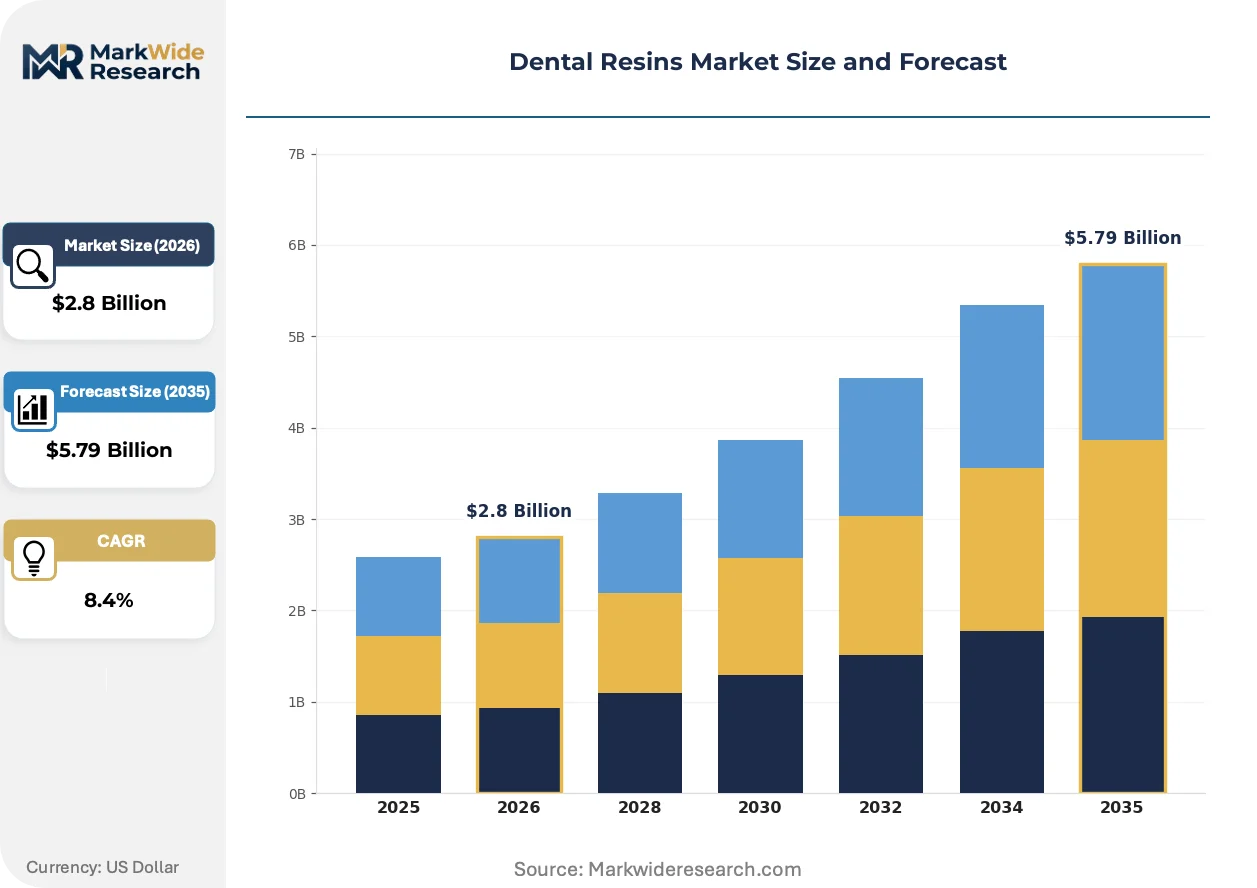
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Resins, Glass Ionomer Resins, Hybrid Resins, Nanohybrid Resins End User: Dental Clinics, Hospitals, Research Laboratories, Orthodontic Centers Application: Restorative Procedures, Aesthetic Dentistry, Orthodontics, Preventive Treatments Form: Paste, Liquid, Gel, Pre-filled Syringe |
| Companies Covered | GC Corporation, Kerr Corporation, 3M Company, Shofu Dental Corporation, SDI Limited, Dentsply Sirona, Kuraray Noritake Dental, Ultradent Products Inc, Ivoclar Vivadent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Resins Market Strategic Shifts
Material science advances and regulatory convergence are compressing product development cycles while redistributing value capture toward biocompatibility-certified manufacturers.
Photoinitiator systems are overtaking conventional camphorquinone formulations in high-intensity LED curing applications. Aesthetic dentistry practices are adopting Type I photoinitiators for 20-second polymerization cycles. This chemistry shift is overtaking manufacturer R&D priorities as clinicians demand faster chairside throughput without compromising degree-of-conversion metrics.
EU MDR Annex I general safety and performance requirements are mandating clinical evaluation reports for all polymer-based dental materials regardless of prior CE marking status. Notified bodies in Germany and the Netherlands are rejecting legacy technical documentation that lacks post-market clinical follow-up data. Nanohybrid resin manufacturers are responding by establishing European authorized representatives with dedicated vigilance reporting capabilities.
Group purchasing organizations in the United States are consolidating procurement volumes across dental service organization networks. Traditional dental dealer relationships are fragmenting as DSOs negotiate direct manufacturer contracts for nanohybrid and bulk-fill resin categories. This concentration is most visible in California and Texas where multi-location practices exceed 50-site thresholds for exclusive supply agreements.
Dental Resins Market Segmentation
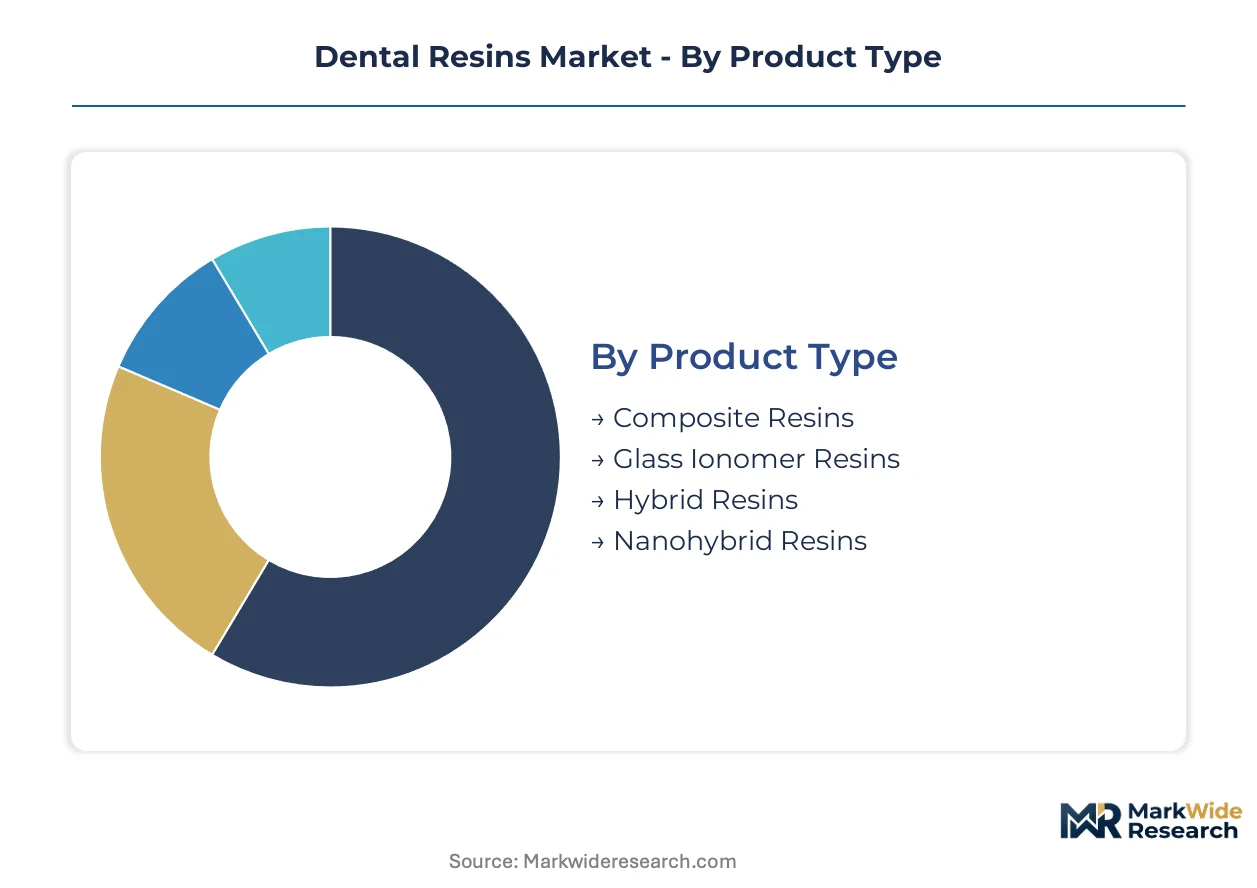
Dental resins fragment across performance tiers that align with procedural economics and regulatory certification levels. Material selection hinges on curing speed, polishability, and biocompatibility documentation depth.
Product Type:
Customization intensity spans from commodity glass ionomers to precision-engineered nanohybrids with proprietary filler architectures.
- Composite Resins:Bis-GMA and UDMA matrices loaded with 0.04-20 micron silica or quartz fillers deliver compressive strengths exceeding 250 MPa. Demand concentrates in Germany and the United States where chairside CAD/CAM throughput drives bulk consumption for posterior restorations.
- Glass Ionomer Resins:Bioactive glass compositions release fluoride ions and chemically bond to tooth structure without adhesive primers. Pediatric and geriatric clinics in Japan favor these for cost-sensitive Class V restorations where moisture tolerance outweighs aesthetic demands.
- Hybrid Resins:Intermediate filler loading balances mechanical properties with handling characteristics for general practitioners.
- Nanohybrid Resins:Sub-100 nanometer filler distributions achieve porcelain-mimicking polishability; orthodontic centers deploy these for aesthetic aligner attachments.
Most installed capacity flows through composite resins. Expansion is steepest in nanohybrid formulations.
End User:
Procurement authority concentrates differently across settings—DSO networks versus independent practices versus institutional purchasing.
- Dental Clinics:Independent and group practices generate the majority of restorative material volume through direct dealer relationships. California and Texas DSOs exceeding 50-site thresholds negotiate exclusive nanohybrid supply contracts.
- Hospitals:Academic medical centers in Germany combine restorative training programs with bulk procurement of glass ionomer systems for emergency departments.
- Research Laboratories:ISO 10993 biocompatibility testing facilities and university polymer science departments validate novel photoinitiator formulations.
- Orthodontic Centers:Specialized practices prioritize aesthetic performance for attachment bonding and clear aligner fabrication.
Volume leadership sits with dental clinics. Procurement consolidation is advancing fastest through hospital system affiliates.
Application:
Reimbursement coding and procedure duration create divergent material specifications across clinical indications.
- Restorative Procedures:Direct fillings for caries and trauma reconstruction demand rapid polymerization and wear resistance. Bulk-fill composites reduce incremental placement steps in high-volume United States practices.
- Aesthetic Dentistry:Veneers, diastema closures, and shade-matched anterior restorations command premium nanohybrid resins with Type I photoinitiators for 20-second curing cycles.
- Orthodontics:Bracket bonding and aligner attachment applications require precise viscosity control and enamel adhesion strength.
- Preventive Treatments:Pit and fissure sealants utilize flowable low-viscosity formulations for pediatric prophylaxis.
Restorative applications anchor material throughput. Aesthetic dentistry commands the highest per-procedure resin expenditure.
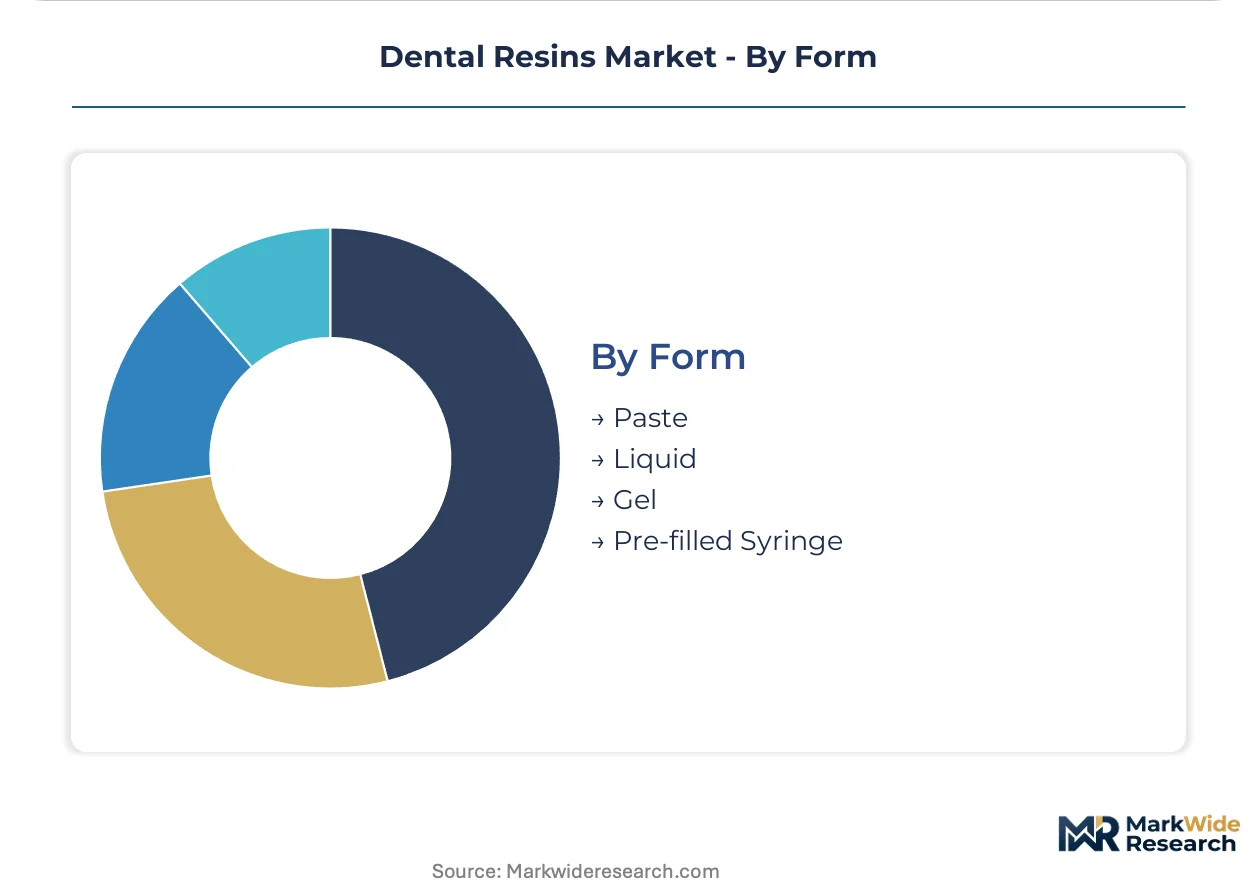
Form:
Packaging format determines dosing precision, shelf stability, and chairside workflow integration.
- Pre-filled Syringe:Unit-dose delivery eliminates mixing variability and reduces waste in aesthetic practices. German dental dealers report margin premiums for single-patient-dispensed nanohybrid systems.
- Paste:Scoopable compules and jars dominate bulk restorative applications where operators control incremental placement.
- Liquid:Low-viscosity flowables and sealants penetrate fissure anatomy for preventive indications.
- Gel:Thixotropic conditioners and bonding agents optimize enamel etching and primer application.
Pre-filled syringe formats capture expanding share in premium positioning. Paste remains the default for posterior load-bearing restorations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The dental resins sector concentrates in advanced manufacturing clusters where digital dentistry infrastructure and regulatory sophistication converge. Germany's precision polymer industry, Japan's materials science base, and the United States' clinical adoption rates create distinct demand profiles. Each geography presents unique entry barriers shaped by local certification requirements and procurement consolidation patterns.
United States
California and Texas dental service organizations exceeding 50-site thresholds negotiate exclusive nanohybrid supply contracts, compressing traditional dealer margins. FDA 510(k) clearance pathways maintain streamlined entry for biocompatibility-tested materials per ISO 10993 protocols. Greater Boston's academic medical centers anchor restorative training programs that drive bulk procurement of photoinitiator-optimized formulations.
Germany
Chairside CAD/CAM throughput in Bavaria and Baden-Württemberg accelerates material consumption as same-day restoration protocols become standard practice. EU MDR Annex I requirements mandate clinical evaluation reports for all polymer-based dental materials, forcing manufacturers to establish European authorized representatives with dedicated vigilance reporting. The Eindhoven-Randstad corridor hosts notified bodies rejecting legacy technical documentation lacking post-market clinical follow-up data.
Japan
Pediatric and geriatric clinics in Kanto and Kansai regions favor glass ionomer systems for cost-sensitive Class V restorations where moisture tolerance outweighs aesthetic demands. PMDA enforces mandatory local clinical evaluation standards that extend registration timelines for imported resin systems by 18-24 months versus FDA pathways. Tokyo's orthodontic centers deploy nanohybrid resins for aesthetic aligner attachments matching porcelain veneer outcomes.
China
Domestic manufacturers in Yangtze River Delta clusters are scaling nanofiller production capacity to reduce import dependency for premium composite formulations. NMPA alignment with ISO 10993-5 cytotoxicity testing standards is converging biocompatibility documentation with FDA and EU requirements. Shanghai's dental hospitals combine restorative training with bulk procurement negotiations that favor localized supply chains.
United Kingdom
London and Southeast England's group purchasing organizations consolidate procurement volumes across dental service organization networks, fragmenting traditional dealer relationships. MHRA post-Brexit regulatory pathways maintain EU MDR-equivalent biocompatibility documentation requirements for polymer-based materials. The Midlands manufacturing corridor hosts specialized ISO 10993 testing facilities serving continental European launches.
Dental Resins Market Competitive Environment
Strategic partnerships dominate the current landscape as manufacturers seek integrated material-distribution platforms and shared regulatory compliance infrastructure. The vendor base fragments across three tiers: multinational conglomerates with captive R&D pipelines, mid-scale specialists in bioactive glass or nanofiller technology, and regional distributors consolidating procurement volumes. Two archetypes define positioning: vertically integrated polymer science conglomerates controlling filler production through backward integration, and regulatory-certified specialists monetizing ISO 10993 documentation depth. Geographic expansion and technology licensing represent the dominant competitive vectors, with European authorized representative capabilities becoming a scarce differentiator under MDR post-market surveillance obligations.
Within the multinational conglomerate tier, GC Corporation, 3M Company, and Dentsply Sirona exemplify divergent strategic postures. Tokyo-based GC Corporation occupies a position anchored in bioactive glass composition leadership, while St. Paul-based 3M Company exemplifies nanofiller technology premiumization through proprietary architectures. Charlotte-based Dentsply Sirona sits within the integrated equipment-materials ecosystem, representing the convergence of CAD/CAM system deployment with consumable resin supply. These three entities illustrate how geographic origin and corporate structure shape competitive positioning without dictating specific product-market outcomes.
| Leading Market Players |
|---|
| GC Corporation |
| Kerr Corporation |
| 3M Company |
| Shofu Dental Corporation |
| SDI Limited |
| Dentsply Sirona |
| Kuraray Noritake Dental |
| Ultradent Products Inc |
| Ivoclar Vivadent |
| Others |
Value Chain & Pricing Dynamics
High-purity silica nanofiller production costs in Germany and Japan cascade through three distinct pricing tiers for finished composite formulations. Raw material concentration in these precision polymer clusters enables premium capture for ISO 10993-certified nanohybrid resins while pressuring margins on standard composite grades.
Pricing Analysis
Input-cost pass-through from specialized nanofiller suppliers governs tiered pricing across premium, standard, and economy resin grades. Certification depth under FDA 510(k) and EU MDR pathways differentiates price bands, with biocompatibility documentation investments commanding 15-30 point spreads over commodity formulations. Pricing pressure stems from glass ionomer substitution in pediatric segments where moisture tolerance trumps aesthetic performance. Dental service organizations in California and Texas exhibit lowest price sensitivity through volume-negotiated exclusive contracts, while independent clinics in Japan remain most responsive to per-unit cost differentials.
Supply Chain Analysis
Freight cost volatility from Yangtze River Delta nanofiller plants to European compounding facilities is reshaping regional sourcing strategies. Manufacturing gravity centers on Germany, Japan, and the United States for precision polymer synthesis, with China scaling captive filler production to reduce import dependency. Formulations rest on high-purity silica, photoinitiator chemicals, and bioactive glass compositions as critical inputs. Single-source vulnerability concentrates in specialized ISO 10993 testing capacity for EU MDR compliance documentation. Distribution runs through direct dental dealer networks in North America and authorized representative structures for European market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental resins market functions as a geographic-arbitrage play where PMDA registration timelines in Japan extend 18-24 months beyond FDA 510(k) pathways, compressing returns for entrants lacking parallel submission capabilities.
For Market Incumbents: Acquire European authorized representative capabilities with dedicated vigilance reporting infrastructure to defend against MDR post-market surveillance obligations. Consolidate nanofiller supply agreements in Germany and Japan to secure input cost stability against Yangtze River Delta capacity expansion. Channel control through direct dental dealer relationships in Texas and California DSO networks remains the critical margin defense lever against procurement concentration.
For New Entrants and Emerging Players: Begin with orthodontic center attachments in Japan's Kanto region where aesthetic performance requirements match premium nanohybrid specifications but local clinical evaluation standards filter multinational competition. Target glass ionomer cost-performance gaps in pediatric and geriatric Class V restorations where moisture tolerance creates substitution headroom against composite incumbents. A specialized ISO 10993 testing partnership accelerates multi-jurisdictional launch timelines.
For Investors and Strategic Acquirers: Consolidation pressure builds where biocompatibility documentation talent scarcity inflates compliance staffing costs beyond mid-scale specialist capacity. Long-term viability over the next decade hinges on backward integration into nanofiller production or captive regulatory consulting infrastructure. Acquisition candidates include regional distributors with 50-plus site DSO relationships in California and Texas, or European authorized representatives with established vigilance reporting systems. The signal to watch is FDA recognition of international standards converging with MDR post-market surveillance demands, which would compress compliance cost differentials between tier-one and tier-two manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nanofiller Production | Captive high-purity silica supply secures input cost stability for premium composite formulations against Yangtze River Delta expansion. |
| European Authorized Representative Acquisition | Dedicated vigilance reporting capabilities satisfy EU MDR Annex I post-market surveillance obligations for polymer-based materials. |
| Direct Dental Dealer Network Consolidation | Integrated material-distribution platforms capture margin pools from DSO procurement concentration in California and Texas. |
| Photoinitiator Wavelength Optimization Partnership | Type I photoinitiator chemistry for 20-second LED curing cycles matches high-volume clinic throughput demands. |
| ISO 10993 Testing Facility Investment | Specialized cytotoxicity protocol expertise reduces redundant testing costs for FDA and EU multi-jurisdictional launches. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both procedural volume trends and regulatory compliance cost structures. Primary discussions engaged dental materials procurement managers at German CAD/CAM centers, regulatory affairs leads at polymer manufacturers, orthodontic center directors in Tokyo, and GPO contracts managers at California DSOs. Secondary validation drew from FDA 510(k) filings, EU MDR notified body guidance documents, PMDA clinical evaluation standards, and customs data for nanofiller trade flows. Bottom-up resin consumption modeling triangulated against top-down market sizing from digital dentistry equipment deployment rates.
Historical reference periods anchored the projection framework to pre-pandemic baseline volumes and post-MDR implementation compliance cost trajectories. Segmentation dimensions spanned product type tiers, end-user procurement authority, application reimbursement coding, and packaging format workflow integration. CAGRs derived from material throughput per chairside CAD/CAM system and substitution rates from amalgam to composite restorations. Forecast inputs included photoinitiator chemistry adoption curves and DSO site expansion patterns in Texas and California.
Several conditions sit outside the modeled scope, including raw material price shocks from energy cost volatility, unanticipated regulatory divergence between FDA and EU MDR recognition agreements, and disruptive ceramic or 3D-printed restoration technologies. Forecasts reflect assumptions about continued digital dentistry adoption and stable biocompatibility documentation requirements. A model refresh is warranted upon material change in EU MDR post-market surveillance enforcement intensity or PMDA streamlining of local clinical evaluation standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Tooth Filling Materials Market
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Acrylic Dental Material Market
Dental Materials
Dental Biomaterials Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Global Dental Cements Market
Dental Materials
Fluoride Materials Market
Dental Materials
Global Dental Membrane and Bone Graft Substitutes Market
Dental Materials
Dental Wax Market
Dental Materials
Solid Toothpaste Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Global Demineralized Bone Matrix Market
Dental Materials
Global Dental Adhesive Market
Dental Materials
Global Teeth Whitening Product Market
Dental Materials
Dental Fluoride Varnish Market
Dental Materials
Dental Alginate Market