
 Inorganic Non-Metallic Materials Market | 2026-2036
Inorganic Non-Metallic Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Non-Metallic Materials Market Analytics
Aftermarket service revenue for high-performance ceramic linings is narrowing as original equipment manufacturers capture lifecycle value through extended warranty contracts. Solvay SA leverages its fluoropolymer-ceramic hybrid expertise to dominate aerospace thermal barrier applications. BASF SE anchors its position through backward integration into specialty alumina powders for electronics substrates. DuPont de Nemours Inc. competes on ceramic matrix composite formulations for energy sector turbine components.
Inorganic non-metallic materials encompass ceramics, glass, mineral silicates, and engineered composites that lack metallic bonding and typically exhibit high thermal stability, electrical insulation, and chemical resistance. These materials are manufactured through sintering, melting, or sol-gel processes and serve primarily as structural, insulating, or chemically inert components across heavy industry. Ceramics and silicates command the deepest margin pools due to energy-intensive kiln requirements and limited supplier base concentration. Glass applications in electronics substrates represent the fastest-expanding demand vector as semiconductor packaging requirements intensify. Construction-grade composites remain mature with pricing disciplined by regional raw material proximity.
EPA emissions standards for glass melting furnaces and REACH chemical safety registrations for silicate formulations shape product compliance costs and market access thresholds in North America and Europe. China's MEE enforces dual carbon targets that restrict high-energy ceramic production without carbon capture retrofitting. Stakeholders must monitor regulatory divergence between carbon-border-adjusted European markets and production-cost-driven Asian supply bases to calibrate capacity allocation and certification investments.
Market Dynamics
China's MEE dual carbon enforcement is compressing kiln capacity while simultaneously accelerating carbon capture retrofitting mandates, forcing producers to choose between asset stranding and technology reinvestment.
Growth Catalysts
- Semiconductor packaging substrates:Advanced glass-ceramic interposers for high-bandwidth memory stacks are pulling capacity expansion from display glass producers in Taiwan and South Korea.
- REACH chemical safety registrations:ECHA's tightened silicate hazard classifications are filtering out marginal European suppliers and consolidating margin pools among compliant incumbents.
- Structural reinforcement ceramics:Germany's industrial cluster around Cologne is scaling fiber-reinforced concrete additives for tunnel and bridge megaprojects.
Market Restraints
- Natural gas price volatility:Glass and ceramic kiln operations remain tethered to European and Asian spot gas markets, compressing operating margins during supply shocks.
- Specialty alumina supply concentration:Captive bauxite refining in Guinea and Australia limits independent processor access to high-purity feedstock for electronics substrates.
- Refractory lifetime extension:Improved ceramic matrix composite durability is compressing replacement cycles for steel industry linings.
Strategic Opportunities
- India's PLI scheme for specialty materials:Domestic ceramic substrate manufacturing incentives are attracting technology transfer partnerships from established Japanese and German producers.
- Solid-state battery electrolytes:Lithium-stabilized garnet and NASICON ceramic formulations represent uncontracted demand from automotive cell manufacturers.
- EU Carbon Border Adjustment Mechanism:CBAM phase-in creates first-mover advantage for European producers with verified low-carbon kiln operations.
Industry Challenges
- Refractory installation technician scarcity:Specialized high-temperature lining crews are aging out faster than apprenticeship programs in Germany and Japan can replenish.
- ISO 14001 environmental management recertification:Compressed audit timelines for multi-site ceramic producers are straining compliance bandwidth.
- Legacy furnace control system integration:Retrofitting carbon capture monitoring into 1980s-vintage kiln automation requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Non-Metallic Materials Market |
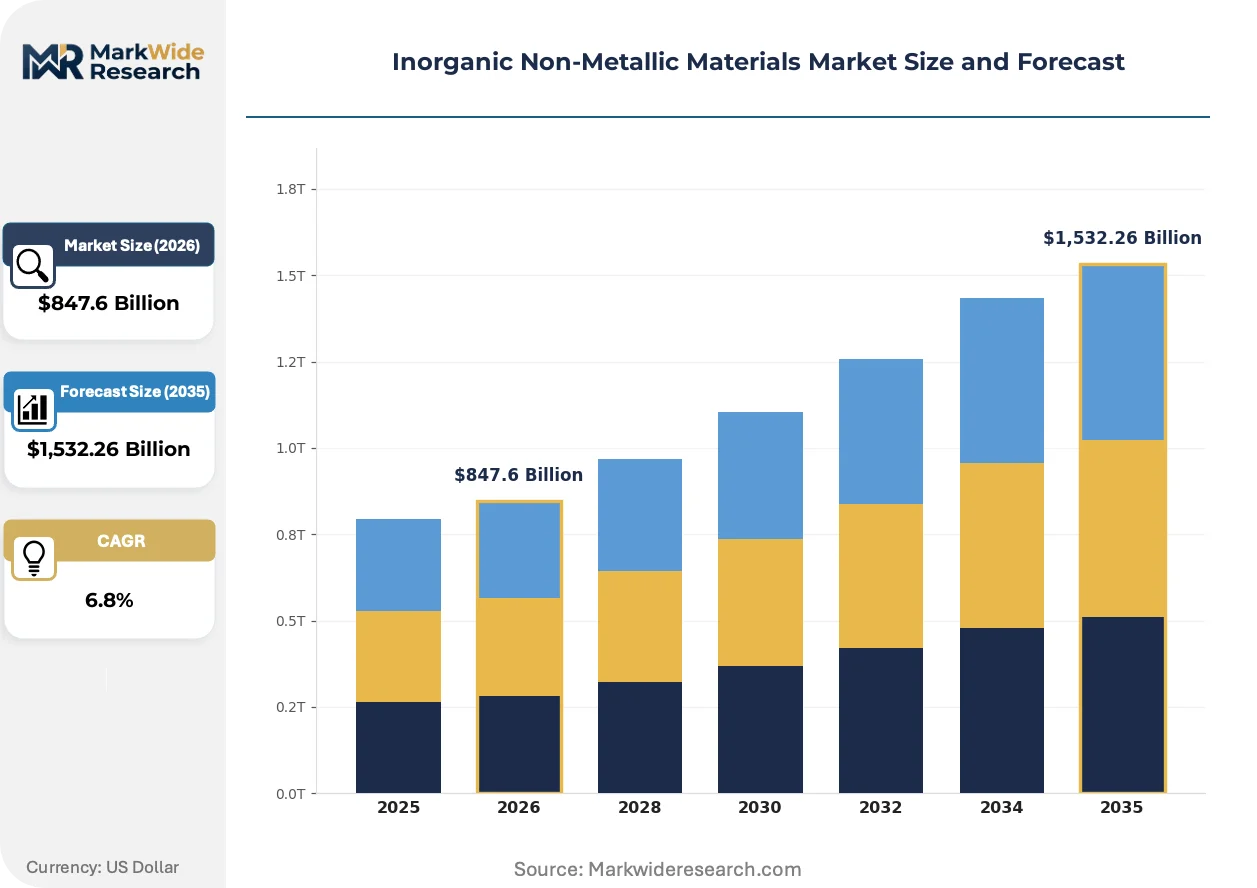
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $1,532.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Ceramics, Glass, Composites, Silicates Application: Chemical Manufacturing, Electronics, Construction, Insulation End Use Industry: Aerospace, Automotive, Medical, Energy Form Factor: Powders, Granules, Sheets, Coatings |
| Companies Covered | Solvay SA, Mitsubishi Chemical Corporation, BASF SE, LG Chem Ltd., Evonik Industries AG, Dow Chemical Company, Akzo Nobel N.V., Arkema Group, DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Non-Metallic Materials Market Evolving Landscape
Additive manufacturing of technical ceramics is collapsing prototyping-to-production timelines while simultaneously enabling topology-optimized geometries impossible with conventional pressing or casting methods.
Cold sintering processes using transient solvents rather than thermal diffusion are rendering obsolete energy-intensive furnace operations for oxide ceramic densification. Medical device manufacturers in Switzerland and orthopedic implant specialists in the Netherlands are piloting hydrothermal consolidation for zirconia and alumina components. The structural consequence is a 60-80% reduction in embodied energy per kilogram of finished ceramic, compressing the carbon intensity gap between European and Asian supply bases.
EPA's forthcoming Maximum Achievable Control Technology standards for glass melting furnaces will mandate regenerative thermal oxidizer retrofits or equivalent emissions capture. Container glass producers serving beverage and pharmaceutical packaging face $15-40 million per furnace compliance investments. Specialty borosilicate and optical glass manufacturers in Pennsylvania and Ohio are accelerating electric melter pilot programs to preempt regulatory deadlines.
Aftermarket service unbundling is disrupting traditional refractory supply relationships. Steel and cement producers are separating material procurement from installation and maintenance, awarding multi-year performance contracts to specialized service integrators. This pattern is most visible in Japan's integrated steel mills and Germany's independent cement grinding operations, where total cost of ownership modeling now dominates supplier selection criteria.
Inorganic Non-Metallic Materials Market Segmentation
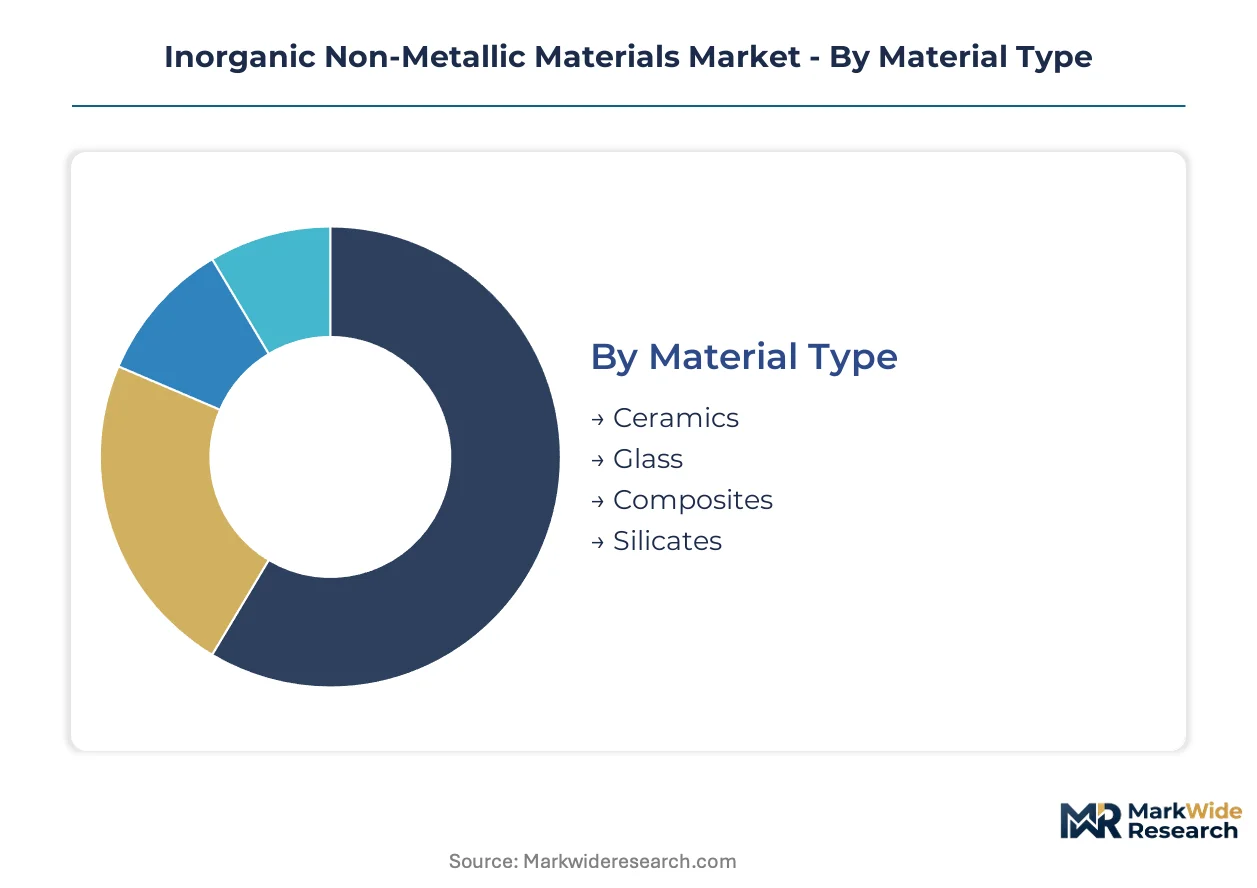
Segmentation in inorganic non-metallic materials separates commodity construction inputs from precision-engineered electronic substrates. Each dimension—material chemistry, application intensity, end-use performance requirements, and physical form—carries distinct margin structures and regulatory exposure.
Material Type:
Cost tier differentiation separates energy-intensive kiln products from lower-temperature processed alternatives.
- Ceramics:Sintered oxide and non-oxide compounds formed at temperatures exceeding 1,200°C. Structural ceramics for Germany's Cologne-Düsseldorf industrial cluster absorb tightening MEE emissions benchmarks through carbon capture retrofits.
- Glass:Amorphous silica-based materials melted in regenerative furnaces. Electronics substrate demand from Taiwan and South Korean semiconductor packagers is pulling capacity away from container glass operations.
- Composites:Fiber-reinforced matrices combining ceramic or glass with polymer binders. Construction-grade formulations in tunnel and bridge megaprojects leverage regional raw material proximity for cost discipline.
- Silicates:Crystalline and amorphous metal-silicon-oxygen compounds. REACH hazard classifications from ECHA are filtering marginal European suppliers and consolidating compliant incumbents.
Ceramics holds installed capacity. Glass is rotating up the share rankings.
Application:
Application intensity determines whether specifications prioritize thermal stability, electrical insulation, or chemical inertness.
- Electronics:High-bandwidth memory interposers and semiconductor packaging substrates. Advanced glass-ceramic formulations from display glass producers in Taiwan and South Korea are climbing the fastest.
- Construction:Structural reinforcement and thermal insulation in infrastructure. Germany's fiber-reinforced concrete additives for tunnel projects anchor mature demand with pricing disciplined by regional feedstock access.
- Chemical Manufacturing:Corrosion-resistant linings and catalytic supports. Refractory lifetime extension from improved ceramic matrix composites compresses replacement cycles for steel industry installations.
- Insulation:Thermal and electrical barrier materials. Energy sector turbine components from Pennsylvania and Ohio manufacturers face EPA Maximum Achievable Control Technology compliance investments.
Construction commands volume leadership. Electronics is rotating up the share rankings.
End Use Industry:
Customer type segmentation separates specification-driven aerospace and medical buyers from cost-sensitive automotive and energy purchasers.
- Energy:Turbine hot-section components and solid-state battery electrolytes. Lithium-stabilized garnet and NASICON ceramic formulations from automotive cell manufacturers represent uncontracted demand expansion.
- Aerospace:Thermal barrier coatings and ceramic matrix composites. Fluoropolymer-ceramic hybrid expertise dominates hot-section applications where operating temperatures exceed 1,300°C.
- Automotive:Catalytic converters, sensors, and brake components. India's PLI scheme for specialty materials attracts technology transfer partnerships from established Japanese producers.
- Medical:Orthopedic implants and diagnostic device housings. Swiss and Dutch manufacturers pilot hydrothermal consolidation for zirconia components with 60-80% embodied energy reduction.
Energy holds installed capacity. Medical is rotating up the share rankings.
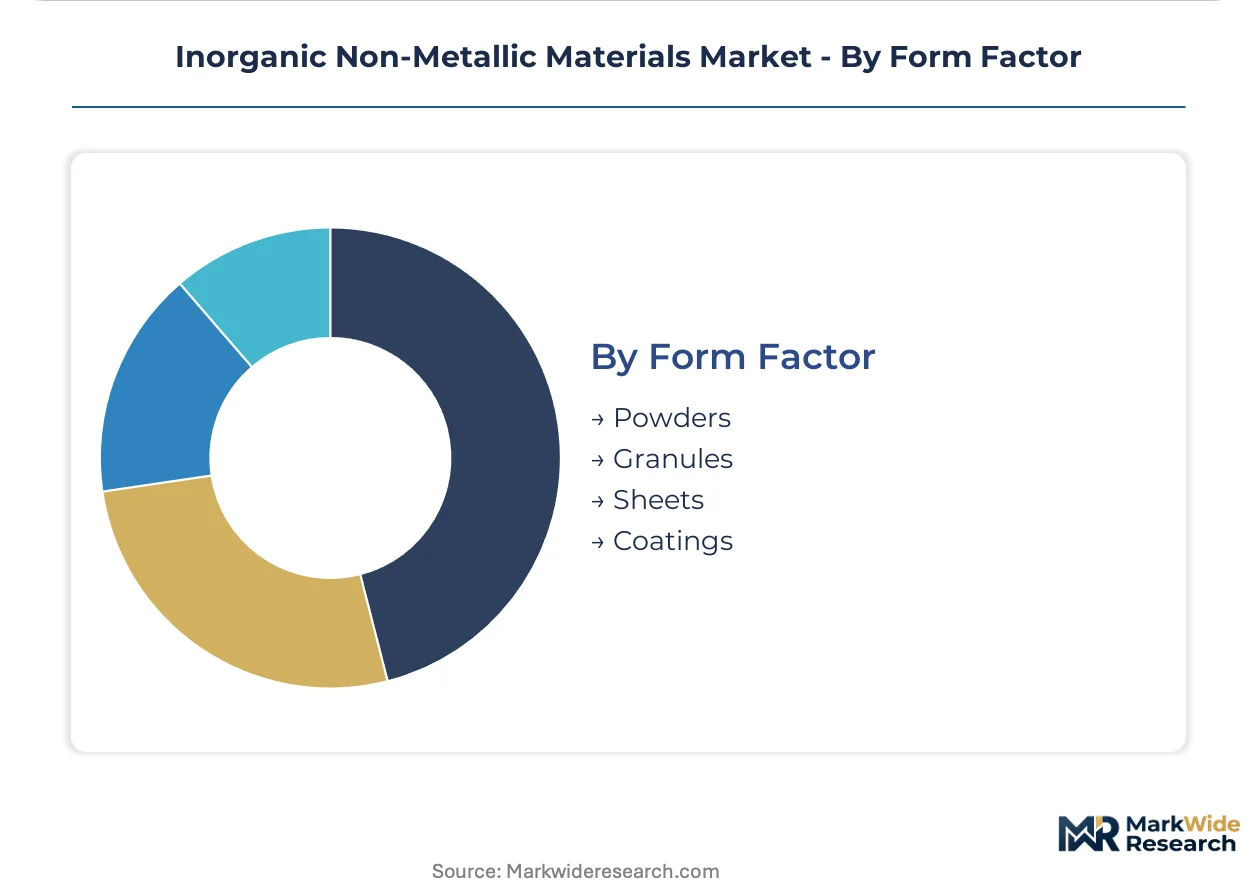
Form Factor:
Physical form dictates processing methodology, logistics economics, and downstream conversion requirements.
- Powders:Finely milled particulates for pressing, spraying, or additive manufacturing. Cold sintering processes using transient solvents are displacing energy-intensive furnace operations for oxide densification.
- Sheets:Flat-rolled or cast panels for substrates and barriers. Electronics interposer demand from high-bandwidth memory stacks concentrates procurement among Taiwan and South Korean producers.
- Granules:Sized particulates for refractory gunning and filtration. Steel and cement producers in Japan and Germany unbundle material procurement from installation through multi-year performance contracts.
- Coatings:Applied surface layers for wear resistance and thermal protection. Additive manufacturing of technical ceramics collapses prototyping-to-production timelines while enabling topology-optimized geometries.
Powders holds installed capacity. Sheets is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kiln capacity concentrates in jurisdictions with captive energy access and established refractory installation expertise. China's MEE dual carbon enforcement is compressing operational flexibility while Germany's industrial ceramics cluster absorbs technology reinvestment mandates. Taiwan and South Korean electronics substrate producers are pulling capacity from container glass operations.
China
Glass furnace operators face MEE emissions benchmarks that restrict high-energy ceramic production without carbon capture retrofitting. The dual carbon goals are forcing producers to choose between asset stranding and technology reinvestment. Shandong Peninsula manufacturers are accelerating electric melter pilot programs to preempt regulatory deadlines.
Germany
The Cologne-Düsseldorf industrial cluster scales fiber-reinforced concrete additives for tunnel and bridge megaprojects. REACH chemical safety registrations from ECHA filter marginal suppliers and consolidate margin pools among compliant incumbents. Bavaria-based specialty alumina processors anchor backward integration into electronics substrate feedstock.
United States
Container glass producers in Pennsylvania and Ohio face EPA Maximum Achievable Control Technology standards mandating regenerative thermal oxidizer retrofits. Specialty borosilicate manufacturers accelerate electric melter pilots to preempt compliance investments. Midwest refractory installation crews are aging out faster than apprenticeship programs can replenish.
Taiwan
Display glass producers are climbing the electronics substrate rankings as high-bandwidth memory interposer demand intensifies. Semiconductor packaging requirements pull capacity expansion from traditional container glass operations. Kaohsiung-based fabricators dominate advanced glass-ceramic formulation procurement.
Japan
Integrated steel mills unbundle refractory material procurement from installation through multi-year performance contracts. METI industrial standards shape ceramic matrix composite durability benchmarks that compress replacement cycles. Nagoya-based producers exemplify the aftermarket service integration model.
Inorganic Non-Metallic Materials Market Competitive Landscape
Integrated chemical conglomerates and specialized ceramic manufacturers split the market along technology-intensity lines. The vendor base organizes around three strategic archetypes: fluoropolymer-ceramic hybrid specialists, backward-integrated alumina powder producers, and ceramic matrix composite formulators. Dominant competitive moves include capacity expansion into semiconductor substrate manufacturing and strategic partnerships for solid-state battery electrolyte development.
Within the integrated chemical conglomerate tier, Solvay SA and BASF SE exemplify divergent strategic positioning. Solvay anchors fluoropolymer-ceramic hybrid expertise for aerospace thermal barrier applications. BASF occupies a position defined by backward integration into specialty alumina powders for electronics substrates. DuPont de Nemours Inc. sits within the ceramic matrix composite formulation segment serving energy sector turbine component demand.
| Leading Market Players |
|---|
| Solvay SA |
| Mitsubishi Chemical Corporation |
| BASF SE |
| LG Chem Ltd. |
| Evonik Industries AG |
| Dow Chemical Company |
| Akzo Nobel N.V. |
| Arkema Group |
| DuPont de Nemours Inc. |
| Others |
Value Network & Pricing Analysis
Kiln overcapacity in Shandong Province is forcing glass furnace operators into aggressive price competition while simultaneously accelerating carbon capture retrofitting investments that reshape supplier cost structures across the value chain.
Pricing Analysis
China's MEE dual carbon enforcement dictates the pricing tier structure across the inorganic non-metallic materials sector. Three-tier pricing structure across premium, standard, and economy levels separates carbon-capture-compliant producers from conventional operators and stranded asset risks. Price differentiation hinges on certification grade under REACH hazard classifications and volume scale in electronics substrate procurement. Cost compression in container glass is intensifying because EPA Maximum Achievable Control Technology compliance investments are diverting capital from price-competitive capacity. Cement grinding operations in Germany exhibit the least price sensitivity due to total cost of ownership contracting, while construction-grade silicate buyers in emerging markets remain highly price-sensitive.
Supply Chain Analysis
Specialty alumina feedstock draws from captive bauxite refining in Guinea and Australia, with high-purity processing concentrated in Germany and Japan. Raw material dependencies include fluoropolymer resins for aerospace thermal barriers, lithium compounds for solid-state battery electrolytes, and rare earth stabilizers for electronics-grade zirconia. Single-source vulnerability in high-bandwidth memory interposer substrates from Taiwan and South Korean producers creates chokepoint exposure for semiconductor packagers. Distribution runs through regional refractory service integrators in Japan and Germany that unbundle material procurement from installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery electrolyte commercialization represents a high-growth disruption as automotive cell manufacturers scramble for lithium-stabilized garnet and NASICON ceramic supply contracts ahead of platform standardization.
For Market Incumbents: Pre-empt specialty alumina powder supply constraints through backward integration into bauxite refining or long-term offtake agreements with Guinean and Australian processors. Carbon capture retrofitting mandates from China's MEE compress operational flexibility for conventional kiln operators, creating technology reinvestment leverage for first movers with verified low-carbon operations. For New Entrants and Emerging Players: Build out cold sintering process capabilities for oxide ceramic densification to exploit the 60-80% embodied energy reduction advantage over conventional furnace operations. India's PLI scheme for specialty materials offers the most penetrable geography for technology transfer partnerships, with domestic ceramic substrate manufacturing incentives attracting established Japanese and German producers seeking tariff-advantaged capacity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among refractory service integrators that have unbundled installation and maintenance from material procurement through multi-year performance contracts. Long-term viability across the analysis window favors acquisition targets with demonstrated carbon capture retrofitting execution and electronics substrate qualification from Taiwan or South Korean semiconductor packagers. The signal to watch is contract structure evolution in Japan's integrated steel mills toward total cost of ownership modeling dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofitting | China's MEE dual carbon enforcement compresses kiln capacity for non-compliant operators while rewarding first movers with verified low-carbon operations. |
| Electronics Substrate Capacity Expansion | Taiwan and South Korean display glass producers are pulling capacity from container glass to serve high-bandwidth memory interposer demand. |
| Cold Sintering Process Commercialization | Hydrothermal consolidation for zirconia and alumina components reduces embodied energy 60-80% versus conventional furnace densification. |
| Backward Integration into Specialty Alumina | BASF SE anchors position through captive supply of high-purity feedstock for semiconductor packaging substrates. |
| Refractory Service Integration | Steel and cement producers in Japan and Germany award multi-year performance contracts separating material procurement from installation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant managers at glass and ceramic kiln operations, procurement leads at semiconductor packaging houses, refractory installation contractors, and technical R&D directors at specialty alumina processors. Secondary validation drew from customs and trade data, SEC 10-K filings, EPA emissions compliance disclosures, and ECHA REACH registration databases. Bottom-up capacity and production estimates were triangulated against top-down demand modeling from end-use industry consumption patterns.
Calibration against historical capacity utilization rates and regulatory compliance cost trajectories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tier, application intensity, end-use performance requirements, and physical form factor, with additional granularity on carbon intensity certification status. CAGRs were derived from slope-consistent growth trajectory fitting rather than single-point extrapolation. Key forecast inputs encompass MEE enforcement timelines for carbon capture retrofitting and semiconductor packaging substrate pull-through rates from Taiwan and South Korean producers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-supported kiln operators or unexpected EPA acceleration of Maximum Achievable Control Technology deadlines would shift outcomes substantially. Cross-checking against EIA industrial energy consumption benchmarks and IEA clean technology deployment trackers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Global Electrostrictive Material Market
Advanced Materials
Middle East Polyether Ether Ketone (Peek) Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Thermal Spray Materials Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
Natural Single Crystal Diamond Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Advanced Carbon Materials Market
Advanced Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market
Advanced Materials
Buckminsterfullerene Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
Boron Nitride Market
Advanced Materials
Superconducting Materials Market
Advanced Materials
North America Next Generation Anode Materials Market
Advanced Materials
Nanofibrillar Cellulose Market
Advanced Materials
Europe Aerogel Market