
 Global Advanced Phase Change Materials Market | 2026-2036
Global Advanced Phase Change Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Phase Change Materials Market Intelligence
Procurement of advanced PCMs is pivoting from a concentrated base in legacy industrial applications toward a more fragmented set of buyers in high-growth sectors. BASF leverages its vast chemical production scale to serve large-volume applications in construction. Honeywell International Inc. specializes in high-performance materials for electronics and aerospace thermal management. Rubitherm Technologies GmbH focuses on specific temperature-controlled logistics solutions, offering a portfolio of organic and inorganic PCMs.
Advanced phase change materials are substances engineered to store and release large amounts of thermal energy at a nearly constant temperature. Their function relies on the principle of latent heat of fusion, absorbing heat during melting and releasing it upon solidification. Salt hydrates and paraffin wax formulations constitute major material type segments, differentiated by their operating temperature ranges and cost profiles. Applications in building insulation drive volume, while electronics cooling commands higher margins for specialized microcapsules.
Regulations such as the EU's REACH framework and the Corporate Sustainability Reporting Directive steer material selection toward non-toxic, sustainable PCM options. In the United States, EPA rules on chemical substances and state-level building energy codes influence market access and product specifications. The central decision for material suppliers involves balancing investment in bio-based PCM research against scaling up production of established paraffin-based products.
Market Dynamics
The central dynamic in the advanced phase change materials market is the bifurcation of demand between high-volume, cost-sensitive building applications and high-margin, performance-driven electronics cooling. This split is intensified by global energy efficiency mandates and the miniaturization of electronic devices.
Growth Catalysts
- Energy Efficiency Mandates:The EU Green Deal and similar building energy codes in North America and China compel the use of thermal energy storage solutions, with PCMs integrated into insulation and building materials to reduce HVAC loads.
- Cold Chain Logistics:Expansion in the transport of temperature-sensitive pharmaceuticals and perishable foods requires passive thermal packaging solutions, where salt hydrate and paraffin PCMs ensure stable temperature profiles without active power.
- Data Center Cooling:Rising heat densities in high-performance computing and data centers create demand for specialized microencapsulated PCMs in advanced thermal management systems, including direct-to-chip and immersion cooling applications.
Market Restraints
- Higher Cost of Sustainable PCMs:The premium cost of bio-based and eutectic salt PCMs compared to conventional paraffin wax formulations restricts their use in large-scale, price-sensitive construction projects, slowing market penetration.
- Long-Term Stability Issues:Certain inorganic PCMs, particularly salt hydrates, can suffer from performance degradation, such as subcooling and phase segregation, over many thermal cycles, creating reliability concerns for long-life applications like building envelopes.
- Substitution by Conventional Insulation:In many retrofit applications, high-performance conventional insulation materials like foam panels offer a lower-cost and more familiar alternative for improving thermal resistance, competing directly with PCM-enhanced products.
Strategic Opportunities
- Smart Textiles and Apparel:The integration of microencapsulated PCMs into fibers and fabrics presents a significant opportunity in performance sportswear, protective workwear, and medical garments for personal thermal regulation.
- Electric Vehicle Battery Management:PCMs offer a passive, lightweight, and non-parasitic method for thermal management of EV battery packs, helping to maintain optimal operating temperatures and extend battery life and safety.
- Circular and Bio-based Materials:Developing PCMs from renewable feedstocks or designing them for full recyclability aligns with circular economy principles and corporate sustainability goals, creating a distinct value proposition under frameworks like the EU's CSRD.
Industry Challenges
- Performance Standardization Deficit:The absence of universally adopted standards for testing and reporting PCM properties like latent heat capacity and thermal cyclability creates ambiguity for engineers, hindering confident specification and adoption.
- Complex Encapsulation Manufacturing:Scaling the production of microencapsulated PCMs for electronics and textiles requires sophisticated chemical processes and significant capital investment, creating a barrier to entry for smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Phase Change Materials Market |
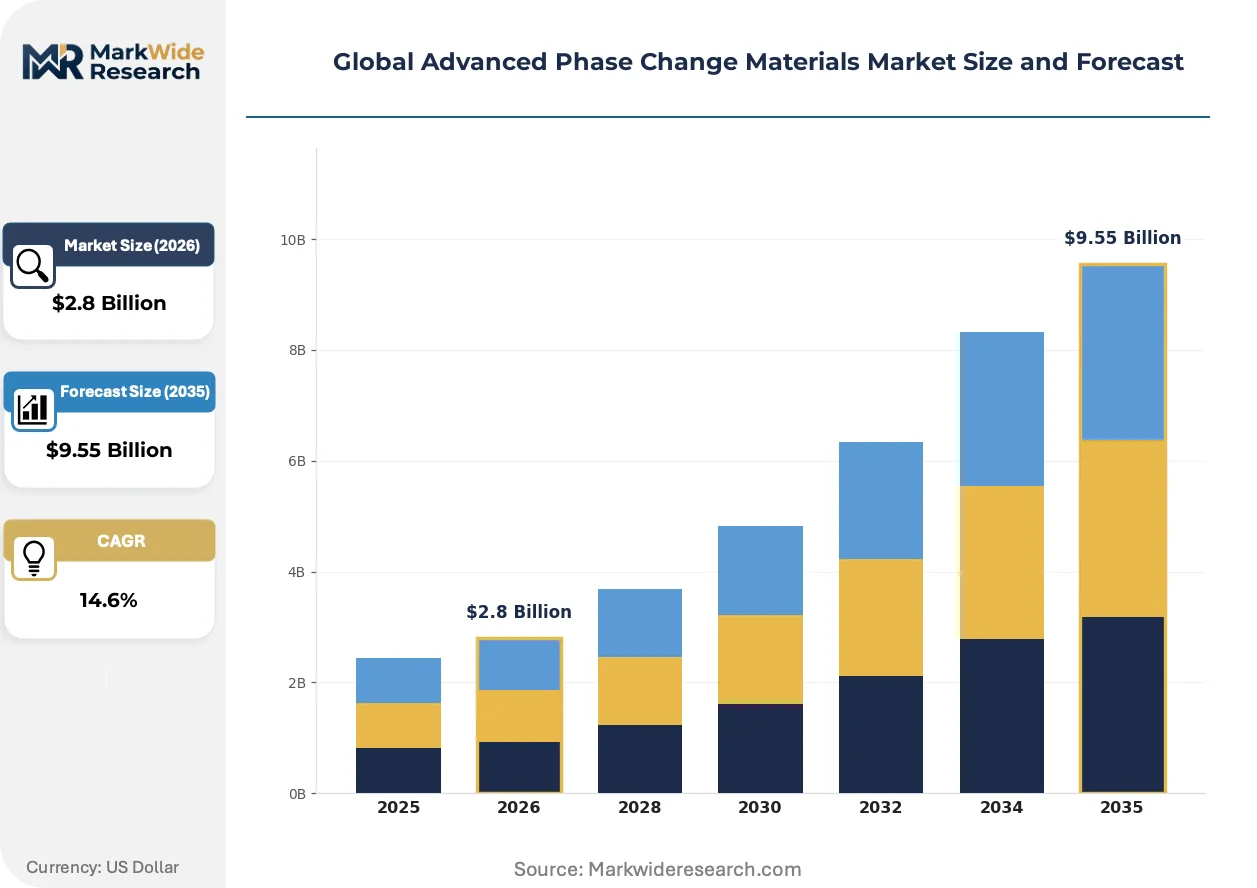
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paraffin Wax, Fatty Acids, Salt Hydrates, Eutectic Mixtures, Polyethylene Glycol Application: Building Insulation, Thermal Energy Storage, Textiles, Electronics Cooling, Automotive Thermal Management Form: Slabs, Microcapsules, Panels, Powders, Granules End User Industry: Renewable Energy Plants, Construction Companies, Apparel Manufacturers, Consumer Electronics Firms, Transportation Providers |
| Companies Covered | BASF, Croda International plc, Rubitherm Technologies GmbH, Honeywell International Inc., Outlast Technologies, Phase Change Energy Solutions, Entropy Solutions, DuPont de Nemours, Pluss Advanced Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Phase Change Materials Market Strategic Shifts & Innovations
Material science is enabling the development of form-stable and shape-stabilized PCMs, moving the technology beyond simple bulk containment. This evolution allows for direct integration into composite materials, building components, and textiles, expanding the addressable applications for passive thermal management.
Form-stable composite PCMs, which embed materials like paraffin within a supporting polymer matrix, provide structural integrity while storing and releasing thermal energy. The construction sector is adopting these composites in products such as PCM-infused gypsum board, concrete, and plaster. This innovation is decentralizing thermal regulation from dedicated HVAC equipment into the passive fabric of the building envelope itself.
The EU's Corporate Sustainability Reporting Directive (CSRD) is pressuring manufacturers to provide transparent lifecycle data for their products. This regulatory driver creates a clear market advantage for PCMs with verifiable environmental credentials, such as bio-based formulations derived from plant oils or recycled sources. Consequently, the bio-based and salt hydrate segments are actively marketing their lower carbon footprint to appeal to specifiers working on green-certified building projects.
A notable demand-side shift from component purchasing to integrated system specification is occurring in high-tech sectors. Electronics and aerospace engineers are increasingly sourcing complete thermal modules that combine PCMs with heat sinks, encapsulation, and thermal interface materials. This trend is most visible in North American and European markets, where system-level performance validation and supply chain simplification are prioritized over the cost of individual raw materials.
Global Advanced Phase Change Materials Market Segmentation
Understanding the varied requirements across end-use sectors and material properties is critical for navigating the advanced phase change materials market. Different applications prioritize specific thermal performance characteristics, cost structures, and integration methods. This segmentation provides a granular view of demand drivers and material selection criteria.
Material Type:
Material selection for advanced phase change materials often hinges on the specific operating temperature range and desired cost profile for the end application.
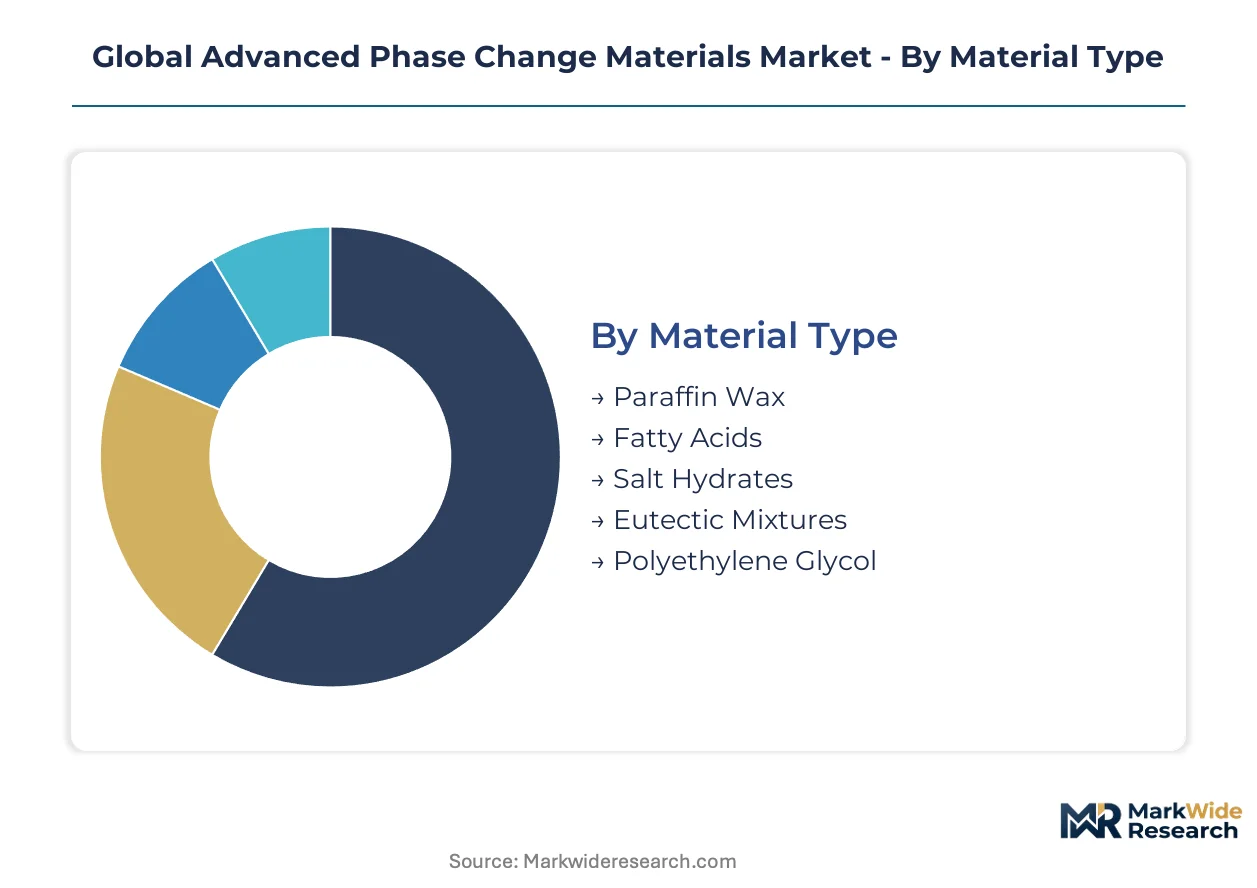
- Paraffin Wax:These organic PCMs are hydrocarbon compounds known for their chemical stability, non-corrosiveness, and wide range of melting points. Demand concentrates in building insulation projects across China, where cost-effectiveness and scalability are paramount.
- Salt Hydrates:Inorganic PCMs formed by combining inorganic salts with water, offering high latent heat storage capacity and non-flammability. Building insulation and cold chain logistics for pharmaceuticals in Europe drive adoption due to their stable temperature control.
- Fatty Acids:Derived from natural sources, these bio-based organic PCMs offer good thermal stability and are increasingly preferred for sustainable building certifications.
- Eutectic Mixtures:These are blends of two or more components that melt and freeze congruently at a single, sharp temperature lower than their individual constituents. Specialized thermal management systems for electronics utilize these formulations.
- Polyethylene Glycol:A synthetic polymer that functions as a PCM, offering tunable melting points and good thermal cycling stability. Textile manufacturers integrate these for personal thermal regulation in performance apparel.
Volume sits with Paraffin Wax; growth tilts toward Eutectic Mixtures.
Application:
The performance requirements of advanced phase change materials vary significantly depending on their intended use, influencing material form and integration.
- Building Insulation:PCMs are integrated into walls, roofs, and floors to absorb and release heat, reducing energy consumption for heating and cooling. This application drives the largest volume across residential and commercial construction projects, particularly in North America and Europe, due to energy efficiency mandates.
- Electronics Cooling:Specialized microencapsulated PCMs manage heat in high-power electronic components, including data centers and portable devices. This segment commands higher margins, driven by the miniaturization of electronic devices and increasing thermal loads.
- Thermal Energy Storage:This broadly encompasses large-scale systems for industrial processes or solar thermal power plants, storing excess heat for later use.
- Textiles:Microencapsulated PCMs are embedded into fabrics for personal thermal comfort in sportswear, medical garments, and protective clothing.
- Automotive Thermal Management:PCMs regulate temperatures in electric vehicle batteries and cabin climate control systems, extending battery life and enhancing passenger comfort.
The largest share resides with Building Insulation, while Electronics Cooling demonstrates the fastest expansion.
Form:
The physical configuration of advanced phase change materials determines their ease of integration into various products and systems.
- Microcapsules:Tiny spheres encapsulating PCM, allowing for dispersion into textiles, paints, and advanced composites without leakage. Electronics cooling and smart textiles in Germany utilize these for precise thermal regulation.
- Panels:Pre-fabricated rigid or semi-rigid boards containing PCM, designed for direct integration into building envelopes or cold chain packaging. Construction companies in France adopt these for efficient installation and enhanced thermal mass.
- Slabs:Larger, solid blocks of PCM used in bulk thermal storage applications or as components in specialized containers.
- Powders:Fine particulate PCMs suitable for mixing into other materials or for specific industrial processes where surface area is critical.
- Granules:Small, solid particles of PCM, often used as additives in construction materials like concrete or plaster.
Dominant adoption centers on Panels, with Microcapsules gaining momentum.
End User Industry:
Specific operational needs and regulatory pressures within each industry dictate the type and scale of advanced phase change materials deployment.
- Construction Companies:These firms integrate PCMs into building materials to meet stringent energy performance standards and improve thermal comfort. Large-scale residential and commercial developments in China represent significant demand for PCM-enhanced insulation.
- Consumer Electronics Firms:Manufacturers of smartphones, laptops, and data center equipment use PCMs for passive thermal management, preventing overheating and extending device lifespan. Innovation in South Korea drives demand for high-performance microencapsulated solutions.
- Renewable Energy Plants:Solar thermal and concentrated solar power (CSP) facilities employ PCMs for storing excess heat, improving grid stability and dispatchability.
- Apparel Manufacturers:Textile companies incorporate PCMs into fabrics for temperature-regulating clothing, targeting performance wear and medical applications.
- Transportation Providers:Logistics companies and automotive manufacturers utilize PCMs for maintaining stable temperatures in cold chain packaging and electric vehicle battery packs.
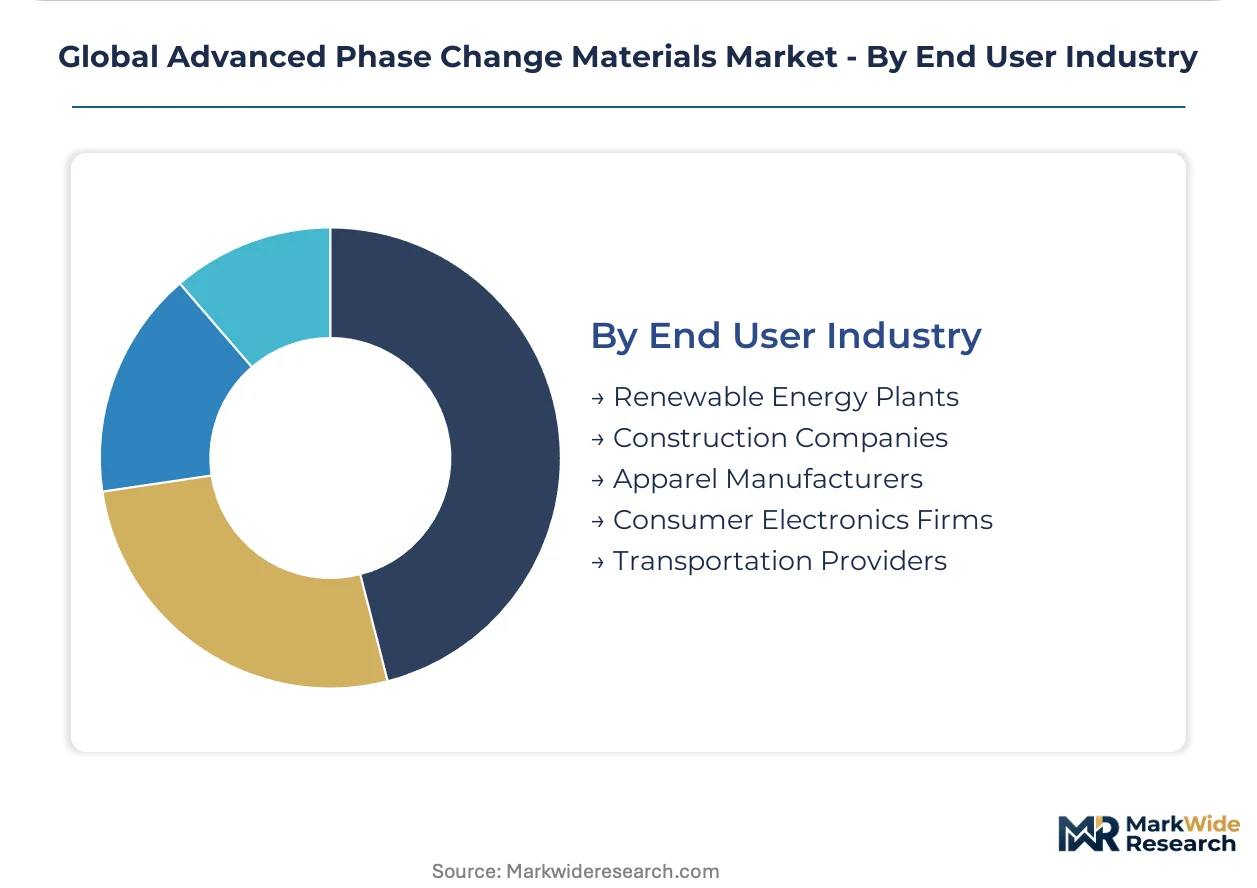
The primary consumption comes from Construction Companies, and Consumer Electronics Firms are experiencing accelerated demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for advanced phase change materials is evident across key global markets. China dominates the construction sector, while European nations prioritize energy efficiency mandates. North America drives innovation in electronics cooling and thermal management applications.
China
China's extensive construction projects and renewable energy installations create substantial demand for advanced PCMs. The nation's dual carbon goals compel the integration of thermal energy storage solutions in new buildings. Major manufacturing hubs like the Yangtze River Delta actively deploy PCM-enhanced building materials for improved energy performance.
United States
The United States exhibits strong demand for PCMs in high-performance electronics cooling and building energy efficiency. EPA rules on chemical substances guide material selection, alongside state-level building energy codes. Technology clusters in Silicon Valley and research institutions in Massachusetts drive specialized microencapsulated PCM adoption for data centers.
Germany
Germany's focus on energy efficiency and sustainable building practices fuels PCM adoption in construction and automotive sectors. The EU Green Deal and REACH framework influence material selection towards non-toxic, bio-based options. Industrial regions such as Bavaria emphasize PCM integration into electric vehicle battery thermal management systems.
India
India's expanding construction sector and cold chain logistics requirements present significant opportunities for advanced PCMs. The Bureau of Indian Standards (BIS) influences building material specifications, promoting energy-efficient solutions. Urban centers like Mumbai and Delhi observe increased interest in PCM-enhanced insulation for commercial and residential developments.
Japan
Japanese consumer electronics firms and smart textile manufacturers are significant consumers of advanced phase change materials. The Ministry of Economy, Trade and Industry (METI) supports research into high-performance materials for electronics cooling. The Kanto region, including Tokyo, sees concentrated development and application of microencapsulated PCMs for advanced thermal management.
Global Advanced Phase Change Materials Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized high-performance applications. The competitive landscape for advanced phase change materials features a tiered structure, reflecting diverse market demands. Strategic archetypes include large-scale chemical manufacturers, niche thermal management solution providers, and bio-based material innovators. Capacity expansion for bulk materials and targeted R&D for microencapsulated formulations represent dominant competitive moves.
Within the specialized segment, Honeywell International Inc., known for high-performance materials, exemplifies a focus on electronics and aerospace thermal management. BASF, a large chemical producer, represents the scale-driven end, serving high-volume construction applications. Rubitherm Technologies GmbH occupies a position among niche solution providers, specializing in specific temperature-controlled logistics. These companies anchor different parts of the value chain, from raw material supply to integrated thermal solutions.
| Leading Market Players |
|---|
| BASF |
| Croda International plc |
| Rubitherm Technologies GmbH |
| Honeywell International Inc. |
| Outlast Technologies |
| Phase Change Energy Solutions |
| Entropy Solutions |
| DuPont de Nemours |
| Pluss Advanced Technologies |
| Others |
Cost & Logistics Intelligence
Construction companies' aggregated demand for advanced PCMs drives a contract-based pricing model, emphasizing volume discounts and long-term supply agreements. This pricing structure reflects the need for predictable costs in large-scale building projects.
Pricing Analysis
The market exhibits a clear volume-vs-margin split, with high-volume building insulation applications prioritizing cost-effectiveness and specialized electronics cooling commanding premium prices for performance. Contract-based long-term offtake agreements dominate the construction sector, while value-based pricing applies to specialized microencapsulated PCMs for high-tech uses. Price differentiation stems from material type, such as bio-based formulations, and specific performance characteristics like thermal cycling stability. Pricing softness in bulk paraffin-based PCMs reflects competition from conventional insulation materials. Construction companies remain highly price-sensitive, whereas consumer electronics firms prioritize performance over marginal cost increases.
Supply Chain Analysis
Certification and qualification gating significantly influence supply chain access for advanced phase change materials, particularly for applications under stringent regulatory frameworks like the EU's REACH. Geographic supply concentration for bulk PCMs centers on China and India, driven by raw material availability and manufacturing scale. Specialized formulations, including eutectic mixtures and microcapsules, often originate from Germany and the United States. The supply chain draws from petrochemical derivatives for paraffin wax and inorganic salts for salt hydrates. Commodity price volatility for these base chemicals presents a structural supply chain risk. Distribution runs through a combination of direct sales to large construction and electronics OEMs, alongside specialized chemical distributors for smaller-volume, high-performance materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The advanced phase change materials market represents a consolidation play, as the performance standardization deficit pressures smaller, less-differentiated players towards acquisition or exit.
For Market Incumbents: To counter the threat of substitution by conventional insulation, incumbents must invest in scaling production of cost-effective, PCM-infused building materials. Deepening vertical integration into key raw materials like specialized polymers for encapsulation provides supply security and cost control. Prioritizing R&D into bio-based PCMs, coupled with robust lifecycle assessment data, reinforces market position under evolving sustainability mandates.
For New Entrants and Emerging Players: Enter via niche, high-margin applications where performance differentiation outweighs initial material cost. Smart textiles and electric vehicle battery management represent penetrable segments due to their specific thermal regulation requirements. A go-to-market angle emphasizing verifiable sustainability credentials for bio-based PCMs aligns with corporate ESG objectives, particularly in European markets.
For Investors and Strategic Acquirers: The window for entry favors specialist chemical investors seeking to capitalize on the bifurcation of demand. Long-term viability rests with companies that can bridge the cost-performance gap for sustainable PCMs or master complex encapsulation technologies. An acquisition target archetype involves mid-sized firms with proprietary bio-based PCM formulations or advanced microencapsulation capabilities. The signal to watch is the widespread adoption of circular economy principles in building codes and automotive battery regulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Bio-based PCMs | Increases supply of sustainable materials, meeting EU Green Deal demand. |
| Advanced Microencapsulation R&D | Enables smaller, more efficient thermal management in consumer electronics. |
| Strategic Partnership with EV OEM | Secures significant volume for PCMs in electric vehicle battery packs. |
| Certification for Building Materials | Facilitates broader adoption of PCM-enhanced insulation in construction projects. |
| Integrated Thermal Module Development | Simplifies procurement for electronics and aerospace engineers in North America. |
Research Approach
Independent corroboration across industry association reports, patent databases, and government energy efficiency mandates underwrites the qualitative findings and quantitative forecasts within this analysis. This study combines insights from primary interviews with chemical engineers, construction project managers, and electronics thermal design leads. Secondary validation draws from public financial filings, academic research, and trade publications. The analysis employs both bottom-up market sizing and top-down validation to ensure comprehensive coverage.
The forecast framework anchors the projection horizon to comparable historical reference periods, establishing a consistent basis for trend analysis. This analytical approach models market dynamics across material type, application, form, end-user industry, and specific operating temperature ranges. Compound annual growth rates derive from a multi-factor regression analysis, integrating inputs such as global construction spending, electric vehicle production forecasts, and energy efficiency policy implementation across the modeling period.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme raw material price volatility or unforeseen regulatory shifts in chemical substance management. The forecasts reflect assumptions regarding technological advancements and market adoption rates. A model refresh is warranted upon material change in global energy efficiency mandates or major breakthroughs in alternative thermal management solutions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Global Diamond-Like Carbon (DLC) Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
Superconducting Materials Market
Advanced Materials
Solar Encapsulation Materials Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Boron Nitride Market
Advanced Materials
Middle East Polyether Ether Ketone (Peek) Market
Advanced Materials
Flexible Bio-Foams Market
Advanced Materials
Glass Reinforced Vinyl Ester (GRV) Market
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
Europe Next Generation Anode Materials Market
Advanced Materials
Nomex Honeycomb Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market