
 Carbon Graphite Market | 2026-2036
Carbon Graphite Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Graphite Market Analysis
Ultra-high purity battery-grade specifications is collapsing the cost premium between synthetic and natural graphite feedstocks. SGL Carbon leverages captive needle coke supply to sustain electrode quality consistency. GrafTech International anchors North American graphite electrode production through vertical integration into petroleum needle coke. HEG Ltd. competes on scale in India's electric arc furnace electrode segment.
Carbon graphite encompasses crystalline carbon structures engineered for thermal conductivity, electrical conductivity, and lubricity across purity grades from 85% to 99.99% carbon content, produced via graphitization at temperatures exceeding 2,500°C. Graphite electrode commands the largest value pool in steel recycling applications, while graphite powder captures expanding margin in lithium-ion battery anode formulations. Graphite flake supply tightens as industrial equipment buyers and automotive component manufacturers compete for crystalline feedstock.
EPA emissions standards in the United States and EU Green Deal carbon border adjustments are reshaping graphite sourcing requirements for battery and steel sector buyers. REACH compliance in Europe and China's GB standards for battery materials are forcing purification technology upgrades across the supply chain. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate qualification costs and sourcing restrictions.
Market Dynamics
Battery anode procurement is consolidating around spherical graphite specifications, compressing feedstock qualification windows and forcing purification technology upgrades across the supply chain. This specification tightening is redrawing competitive boundaries between synthetic and natural graphite producers.
Growth Catalysts
- EU Green Deal carbon border adjustments:Steelmakers in Europe are accelerating electric arc furnace conversion, lifting electrode consumption as scrap-based production displaces blast furnace output.
- Spherical graphite processing:Battery-grade anode material commands premium qualification status, pulling investment into micronization and purification capacity expansion.
- China's dual carbon goals:Domestic graphite electrode producers face output caps that tighten export availability, redirecting procurement flows toward alternative suppliers.
Market Restraints
- Needle coke supply concentration:Petroleum-based feedstock for ultra-high power electrodes relies on a limited set of oil refinery byproduct streams, creating input cost volatility.
- Geographic processing dominance:Spherical graphite purification capacity concentrates in China, exposing battery supply chains to single-jurisdiction qualification dependencies.
- Silicon anode substitution:Next-generation lithium-ion formulations are incorporating silicon composites that reduce graphite loading requirements per cell.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic battery manufacturing incentives are creating localized anode material demand that lacks established supply infrastructure.
- Recycled graphite recovery:End-of-life battery processing is emerging as a secondary feedstock stream for anode material qualification.
- Solid-state battery convergence:Solid electrolyte architectures require modified graphite morphologies, opening specification windows for differentiated products.
Industry Challenges
- High-temperature graphitization expertise:Operating furnaces above 2,500°C requires specialized process engineering talent that remains scarce outside established production clusters.
- Battery qualification timelines:OEM cell testing protocols extend 18-24 months, compressing effective product development cycles for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Graphite Market |
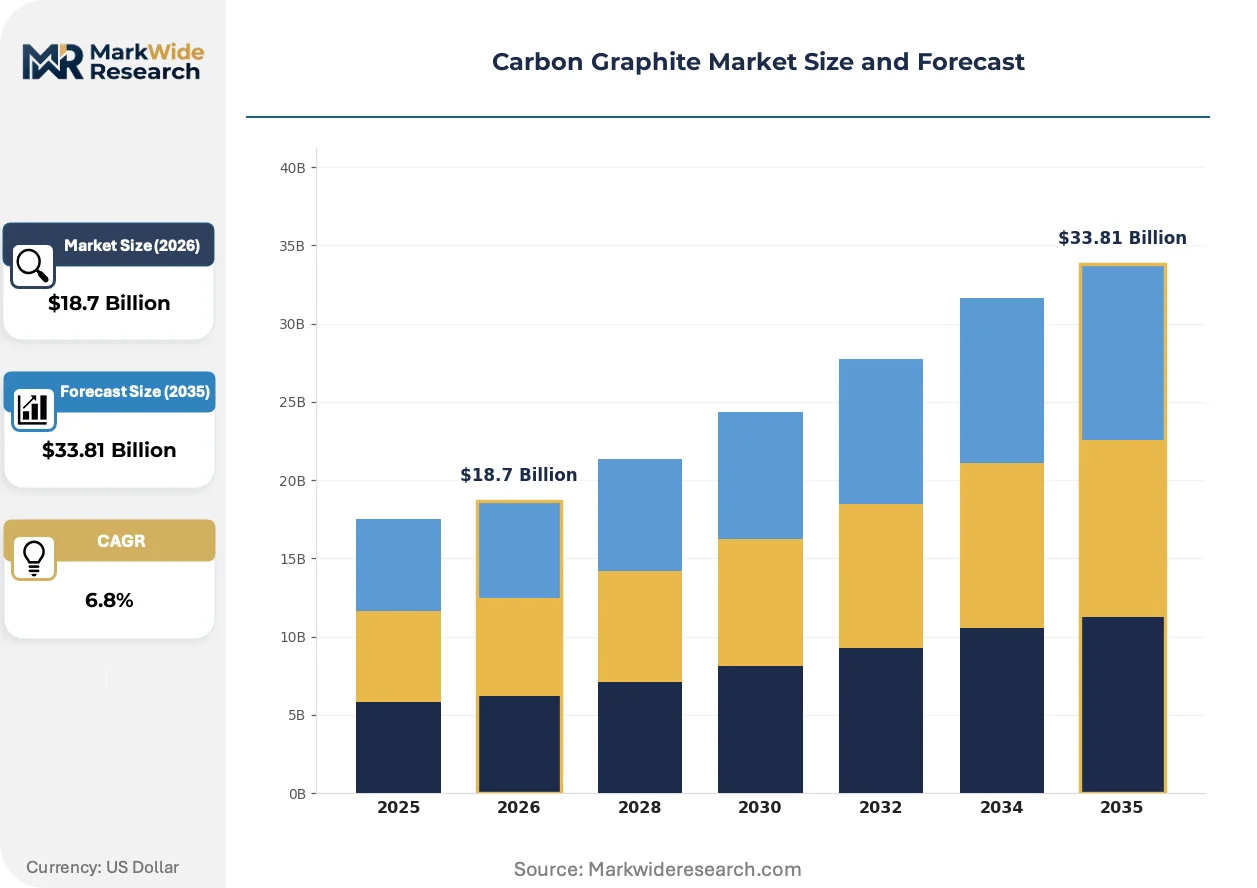
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphite Powder, Graphite Electrode, Graphite Block, Graphite Flake Application: Batteries, Lubricants, Steel Manufacturing, Brake Linings End User: Aerospace, Automotive Components, Electronics, Industrial Equipment Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | SGL Carbon, GrafTech International, HEG Ltd., Tokai Carbon Co., Ltd., Mersen S.A., Cabot Corporation, Imerys, Asbury Carbons, BTR New Material Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Graphite Market Emerging Trajectories
Graphite supply chains are bifurcating between commodity industrial grades and battery-qualified specialties, with purification technology becoming the primary value-capture mechanism. This divergence is forcing capital allocation decisions that favor either scale or specification depth.
Coated spherical graphite is miniaturizing particle size distributions to optimize lithium-ion intercalation kinetics. Battery cell manufacturers are adopting sub-10 micron specifications for fast-charge applications, compressing the performance gap between synthetic and purified natural feedstocks. This particle size reduction is miniaturizing the addressable supplier base to those with advanced classification and surface treatment capabilities.
REACH compliance in Europe is mandating supply chain transparency for critical raw materials including graphite. The regulation requires documented provenance and environmental footprint declarations for battery-grade material entering the EU market. Anode producers are responding by securing third-party certification and restructuring procurement contracts to include traceability clauses.
Long-term offtake agreements are displacing spot market transactions as the dominant procurement mechanism for battery-grade graphite. Cell manufacturers are locking multi-year supply commitments directly with processors, bypassing traditional trading intermediaries. This contracting shift is most pronounced in South Korea and Japan, where battery producers face IRA-linked sourcing restrictions that require documented supply chain mapping.
Carbon Graphite Market Segmentation
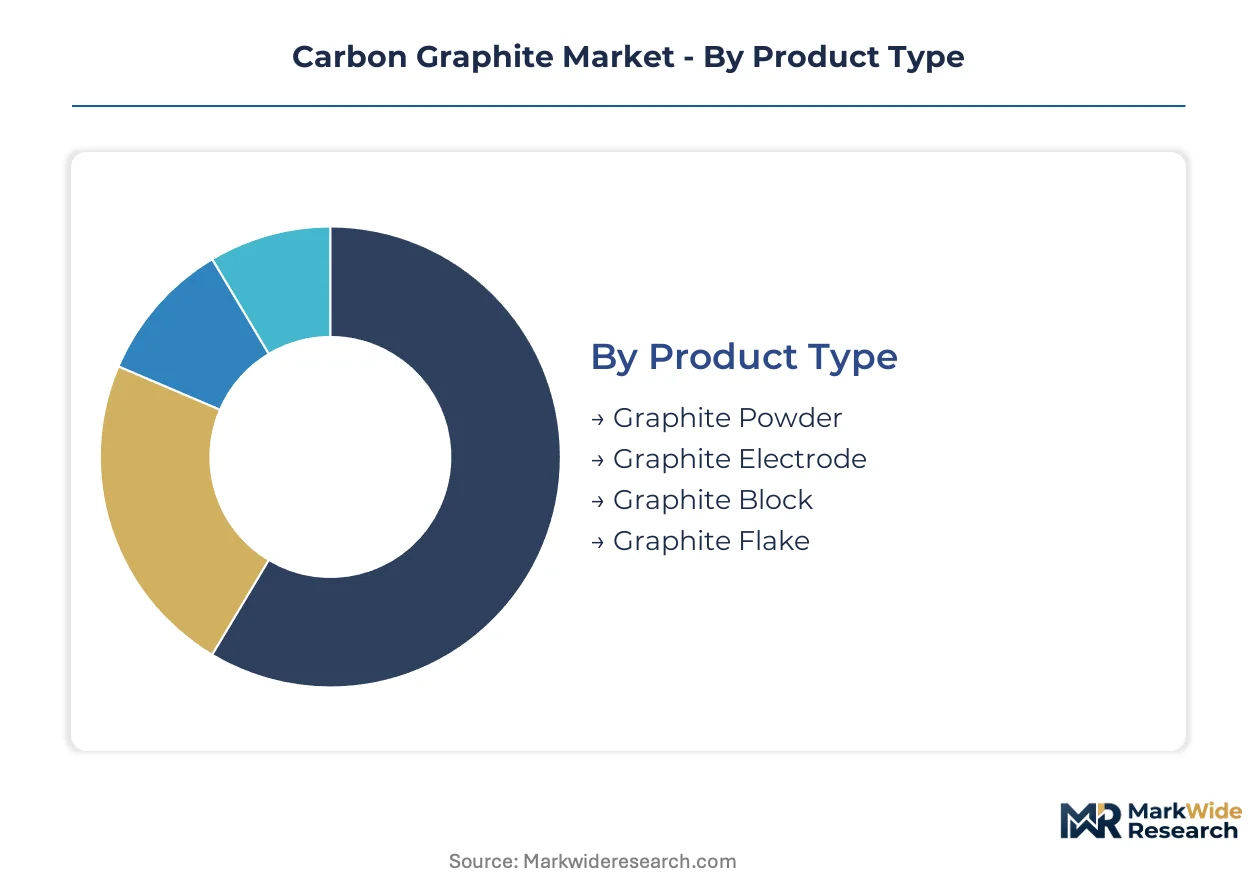
Carbon graphite market segmentation reveals divergent supply chain configurations across product grades and end-use specifications. Battery-grade spherical graphite demands export-oriented purification capacity while industrial electrodes serve regional steel recycling clusters.
Product Type:
Graphite powder and electrodes anchor domestic production networks in China and India, while flake and block grades flow through international trading hubs.
- Graphite Powder:Micronized carbon structures with 99.9%+ purity specifications serve lithium-ion battery anode formulations. South Korean and Japanese cell manufacturers dominate procurement through multi-year offtake agreements that bypass spot markets.
- Graphite Electrode:Ultra-high power grades manufactured from petroleum needle coke sustain electric arc furnace operations. Turkish and Italian steelmakers represent concentrated demand pockets as EU Green Deal carbon border adjustments accelerate scrap-based production.
- Graphite Block:Isostatically pressed forms serve semiconductor and metallurgical applications requiring dimensional stability.
- Graphite Flake:Crystalline feedstock sources from Mozambique and Madagascar deposits compete for battery and industrial qualification.
Graphite electrode holds the largest share; momentum sits with graphite powder.
Application:
Cost-tier stratification separates premium battery-grade purification from commodity industrial lubricant formulations.
- Batteries:Spherical graphite anode material requires acid-washing and thermal purification to meet cell manufacturer specifications. IRA-linked sourcing restrictions in the United States force documented supply chain mapping for qualified material entry.
- Steel Manufacturing:Electric arc furnace electrodes consume the highest tonnage of ultra-high power graphite grades. EPA emissions standards in the United States tighten coke oven byproduct availability, constraining needle coke feedstock for electrode production.
- Lubricants:Fine powder grades serve high-temperature industrial machinery applications.
- Brake Linings:Friction material formulations incorporate synthetic graphite for thermal management.
Steel manufacturing captures volume leadership; batteries are climbing the fastest.
End User:
Customer-type concentration varies sharply between specification-heavy aerospace qualification and volume-driven automotive procurement.
- Automotive Components:Brake systems and sealing applications consume molded graphite shapes at scale. German and Japanese OEMs enforce material certification requirements that filter supplier bases to ISO-qualified processors.
- Electronics:Thermal interface materials and semiconductor fixtures demand isotropic graphite with controlled thermal expansion coefficients.
- Aerospace:Satellite and aircraft applications require extended qualification cycles for high-reliability carbon-carbon composites.
- Industrial Equipment:Foundry crucibles and heat exchangers represent price-sensitive replacement demand.
Automotive components command the largest share; aerospace shows the steepest expansion trajectory.
Distribution Channel:
Supply concentration favors direct contracting for battery-grade material while industrial grades flow through distributor networks.
- Direct Sales:Long-term offtake agreements dominate battery anode procurement as cell manufacturers secure multi-year spherical graphite commitments. South Korean battery producers lead this contracting shift to satisfy IRA documentation requirements.
- Distributors:Regional stockists serve fragmented industrial equipment and metallurgical end-users with standardized electrode and block grades.
- Online Sales:Specialty powder grades for research and prototyping move through digital channels.
- Retail:Small-format products for maintenance applications reach end-users through industrial supply houses.
Direct sales holds the largest share; momentum sits with distributor consolidation around qualified battery material.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spherical graphite purification capacity concentrates overwhelmingly in China, yet battery cell qualification requirements are forcing geographic diversification of processing assets. Jurisdictions with IRA-linked documentation mandates and carbon border adjustments are redirecting procurement flows toward qualified alternative suppliers.
China
Shandong and Heilongjiang provinces host the majority of global spherical graphite processing capacity serving battery anode demand. GB standards for battery materials and dual carbon goals under MEE oversight are tightening output caps on graphite electrode producers. Dalian and Qingdao processing clusters are expanding micronization capacity to meet sub-10 micron specifications for fast-charge applications.
United States
Domestic battery cell manufacturing expansion under IRA incentives is creating qualified anode material demand that lacks established supply infrastructure. EPA emissions standards constrain petroleum needle coke availability for electrode production from refinery byproduct streams. Ohio and Tennessee processing investments are advancing to satisfy documented supply chain mapping requirements for qualified material entry.
Germany
Electric arc furnace conversion in the Ruhr and Saar steel regions is lifting ultra-high power electrode consumption as scrap-based production displaces blast furnace output. EU Green Deal carbon border adjustments and REACH compliance under ECHA oversight are mandating supply chain transparency for battery-grade material imports. Bavarian automotive component manufacturers enforce ISO-qualified processor certification for brake system and sealing applications.
South Korea
Cell manufacturers in the Seoul Capital Area and Busan-Ulsan corridor dominate spherical graphite procurement through multi-year offtake agreements that bypass spot markets. IRA-linked sourcing restrictions require documented supply chain mapping, driving direct contracting with qualified processors. Domestic qualification timelines extend 18-24 months, compressing effective product development cycles for new material entrants.
India
Electric arc furnace electrode demand concentrates in Gujarat and Maharashtra steel recycling clusters competing on scale with Chinese imports. PLI scheme incentives for advanced chemistry cells are creating localized anode material demand that lacks established purification infrastructure. HEG Ltd. and domestic competitors face qualification gaps against battery-grade specifications that require acid-washing and thermal purification technology upgrades.
Carbon Graphite Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with purification specialists commanding battery-grade premiums while scale operators dominate industrial electrode volumes. The vendor base separates into three tiers: integrated needle coke-to-electrode producers, spherical graphite purification specialists, and commodity powder processors serving lubricant and friction applications. Strategic moves center on backward integration into petroleum needle coke supply and multi-year offtake contracting with battery cell manufacturers to lock qualification status.
Among German-integrated producers, SGL Carbon exemplifies captive needle coke supply archetypes sustaining electrode quality consistency, while GrafTech International anchors North American production through upstream control over petroleum needle coke feedstock. HEG Ltd. occupies a position within India's scale-driven electric arc furnace electrode segment competing on volume against qualified battery-grade specialists.
| Leading Market Players |
|---|
| SGL Carbon |
| GrafTech International |
| HEG Ltd. |
| Tokai Carbon Co., Ltd. |
| Mersen S.A. |
| Cabot Corporation |
| Imerys |
| Asbury Carbons |
| BTR New Material Group Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between South Korean cell manufacturers and Chinese spherical graphite processors lock in multi-year supply access while anchoring price visibility against IRA-linked documentation requirements. This contracting structure compresses spot market liquidity and concentrates pricing power with qualified purification specialists.
Pricing Analysis
EU Green Deal carbon border adjustments dictate the pricing tier structure across battery-grade and industrial graphite segments. Three-tier pricing structure across premium, standard, and economy levels separates IRA-compliant qualified material from REACH-certified industrial grades and unverified commodity powder. Cost compression in battery-grade spherical graphite is intensifying because purification capacity expansion lags cell manufacturing buildout. Automotive OEM procurement teams show highest price sensitivity, while aerospace qualification programs absorb premium tiers.
Supply Chain Analysis
Strategic stockpile preferences dominate battery anode procurement as cell manufacturers secure 18-24 month qualification pipelines against single-source vulnerabilities. Concentration in China, Mozambique, and Madagascar feeds crystalline flake feedstock into Shandong and Heilongjiang purification clusters. Needle coke supply rests on petroleum refinery byproduct streams from US Gulf Coast and Japanese oil majors. Tariff exposure on Chinese-processed spherical graphite is redirecting procurement flows toward alternative suppliers. Distribution runs through direct sales contracts for battery material and regional distributors for industrial electrodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon graphite sits in early-cycle expansion as electric vehicle battery manufacturing scales ahead of qualified anode material supply infrastructure. IRA-linked sourcing restrictions and EU carbon border adjustments are accelerating documented supply chain investments.
For Market Incumbents: Compound qualification status through captive needle coke supply and multi-year offtake contracting with Seoul Capital Area cell manufacturers. Silicon anode substitution threatens long-term graphite loading requirements; defend through micronization capacity for sub-10 micron fast-charge specifications. Backward integration into petroleum needle coke secures electrode quality consistency against EPA emissions constraints. For New Entrants and Emerging Players: Differentiate on purification technology for India's PLI scheme battery manufacturing incentives, where domestic anode material demand lacks established supply infrastructure. Target spherical graphite processing for South Korean IRA documentation requirements. White-space exists in recycled graphite recovery from end-of-life batteries. Go-to-market through direct qualification partnerships with Busan-Ulsan corridor cell manufacturers. For Investors and Strategic Acquirers: Purification specialists with documented supply chain mapping capability represent the most defensible acquisition archetype for a five-to-ten year holding window. Solid-state battery convergence requiring modified graphite morphologies signals inflection when OEM testing protocols accelerate. Watch for qualification timeline compression as battery cell manufacturers bypass traditional trading intermediaries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke | SGL Carbon and GrafTech International anchor electrode quality through captive petroleum feedstock supply. |
| Micronization Capacity Expansion | Dalian and Qingdao processing clusters target sub-10 micron specifications for fast-charge battery applications. |
| Multi-year Offtake Contracting | South Korean cell manufacturers lock supply commitments to satisfy IRA-linked sourcing documentation mandates. |
| Recycled Graphite Recovery Investment | End-of-life battery processing emerges as secondary feedstock stream for anode material qualification. |
| REACH Compliance Certification | ECHA oversight mandates supply chain transparency for battery-grade material entering European markets. |
Methodological Framework
A spread of perspectives from electrode plant managers, battery cell procurement leads, petroleum needle coke supply specialists, and spherical graphite purification engineers converged on the working assumptions. Primary interview insights combined with secondary validation from customs trade data, SEC filings of listed electrode producers, ECHA REACH registration databases, and IRA documentation guidance. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across the analysis window.
Segmentation dimensions modeled include product type hierarchy, application-grade stratification, end-user concentration patterns, and distribution channel configuration. CAGRs derived from regression against electric arc furnace conversion rates and lithium-ion cell manufacturing expansion trajectories. Forecast inputs incorporated GB standards compliance costs and dual carbon goal output caps under MEE oversight.
Decision-makers should treat outputs as directional under base assumptions of sustained EV adoption and stable needle coke refinery byproduct availability; material deviation would warrant model refresh. Revision becomes warranted when silicon anode loading ratios or solid-state battery commercialization timelines cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
APAC Advanced Building Materials Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Synthetic Graphite Market
Advanced Materials
Glass Reinforced Vinyl Ester (GRV) Market
Advanced Materials
Bioactive Glass Market
Advanced Materials
Thermal Spray Market
Advanced Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Advanced Carbon Materials Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Borophene Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Global Advanced Composites Market
Advanced Materials
Global Synthetic Diamond Market
Advanced Materials
North America Plasma Powder Market