
 Wood Foam Market | 2026-2036
Wood Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Foam Market Analytics
Multi-source procurement of wood fiber feedstock is pivoting toward vertically integrated mill operations across Nordic suppliers. BASF leverages captive resin chemistry to anchor its position in polyurethane-modified wood foam formulations. Huntsman Corporation competes through specialized isocyanate systems that bond engineered wood fibers at lower densities. Armacell sustains geographic dominance in European insulation channels with rigid foam boards manufactured near timber sources.
Wood foam is a cellular material manufactured from lignocellulosic fibers bonded with polyurethane, phenolic, or bio-based adhesives through controlled foaming and curing processes, yielding densities between 30 and 250 kg per cubic meter for thermal insulation and structural cushioning applications. Rigid foam dominates margin pools in building envelope applications where lambda values below 0.035 W per meter-Kelvin command specification premiums. Flexible foam is expanding fastest in furniture manufacturing as European producers phase out petroleum-based polyurethane slabs. Composite foam occupies a niche but defensible position in automotive interior panels where multi-material bonding meets crashworthiness standards.
REACH and the EU Green Deal are restricting formaldehyde emissions and mandating recycled content thresholds in construction materials, directly shaping product formulation roadmaps for wood foam manufacturers. ECHA substance evaluations are accelerating substitution of petrochemical binders with lignin-derived adhesives in certified building products. Stakeholders must monitor bio-based feedstock certification schemes and polymer precursor supply agreements to secure compliant volume expansion.
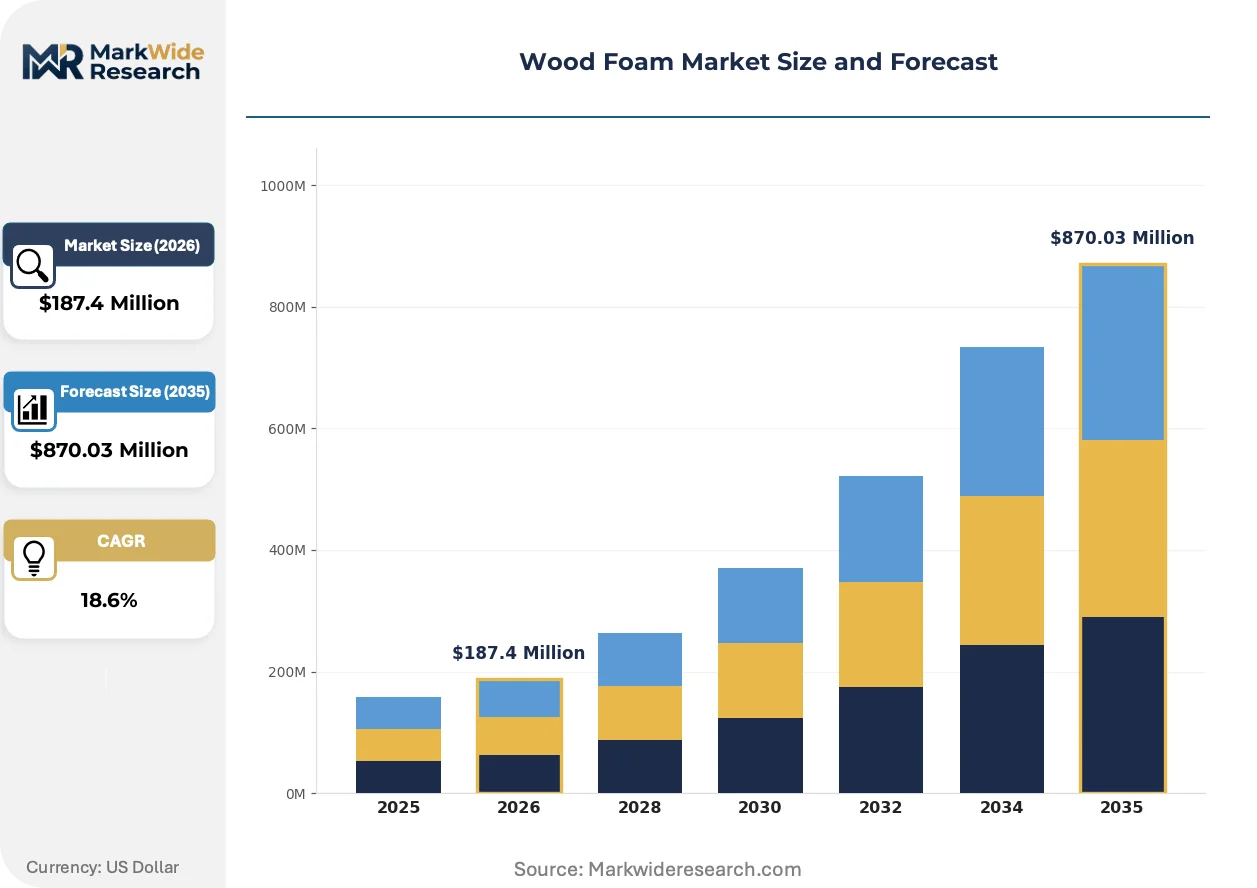
Market Dynamics
REACH compliance in Europe is compressing formulation timelines for wood foam manufacturers, forcing simultaneous substitution of petrochemical binders and recertification of entire product portfolios before the 2026 enforcement window closes.
Growth Catalysts
- EU Green Deal mandates:Recycled content thresholds in construction materials are pulling lignin-derived adhesive formulations into certified building products across Germany and Sweden.
- Automotive lightweighting specifications:Crashworthiness standards for interior panels are expanding procurement of composite wood foam by tier-one suppliers in Stuttgart and Wolfsburg.
- Nordic forestry cluster proximity:Vertically integrated mill operations in Finland are shortening raw fiber supply chains to rigid foam insulation panel producers.
Market Restraints
- Isocyanate price volatility:Polyurethane precursor costs fluctuate with crude oil indices, compressing margins on medium-density formulations.
- German construction permit delays:Local zoning procedures for passive house retrofits extend project timelines and defer insulation procurement decisions.
- Mineral wool substitution:Stone wool manufacturers in Eastern Europe are underbidding wood foam on lambda-value-equivalent specifications in price-sensitive tenders.
Strategic Opportunities
- Furniture manufacturing conversion:Polish and Czech upholstery producers are phasing out petroleum-based polyurethane slabs, creating white space for flexible wood foam penetration.
- ECHA substance evaluation tailwinds:Accelerated substitution timelines for formaldehyde-emitting binders favor early movers with lignin-adhesive certifications.
- Direct mill-to-fabricator channels:Bypassing traditional insulation distributors in Nordic markets captures margin previously lost to layered markup structures.
Industry Challenges
- Bio-based feedstock certification complexity:Chain-of-custody documentation for FSC- and PEFC-compliant lignocellulosic sources requires dedicated compliance personnel.
- Legacy equipment retrofit costs:Phenolic resin foam lines require capital-intensive reconfiguration to process polyurethane-modified wood fiber slurries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Foam Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Foam, Flexible Foam, Spray Foam, Composite Foam Application: Packaging, Insulation, Furniture, Automotive Material: Wood Fiber, Adhesives, Polyurethane, Other Chemicals End User: Construction, Furniture Manufacturing, Automotive Industry, Retail |
| Companies Covered | Huntsman Corporation, Armacell, BASF, Rogers Corporation, Recticel, Dow, Woodbridge Group, Carpenter Co., Covestro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Foam Market Evolving Landscape
Formulation chemistry and procurement patterns are diverging sharply between rigid insulation and flexible cushioning segments, with regulatory pressure acting as the primary accelerant on both fronts.
Lignin-derived adhesive systems are unifying thermal performance with bio-based content claims in rigid foam boards. German envelope contractors are specifying these formulations on municipal housing projects. This convergence is compressing the premium that petrochemical-bonded products previously commanded in lambda-value-sensitive tenders.
REACH Annex XIV authorization procedures are extending substitution deadlines for formaldehyde-releasing resins. Wood foam producers are accelerating phenolic-to-polyurethane formulation pivots ahead of 2026 sunset dates. Nordic suppliers with captive resin chemistry are capturing specification share from importers dependent on legacy binders.
Long-term supply agreements are displacing spot-market fiber purchasing among major insulation fabricators. German construction consortia are locking multi-year lignocellulosic volumes directly with Finnish mill operators. This pattern is most visible in Bavaria and Baden-Württemberg, where passive house build rates exceed national averages.
Wood Foam Market Segmentation
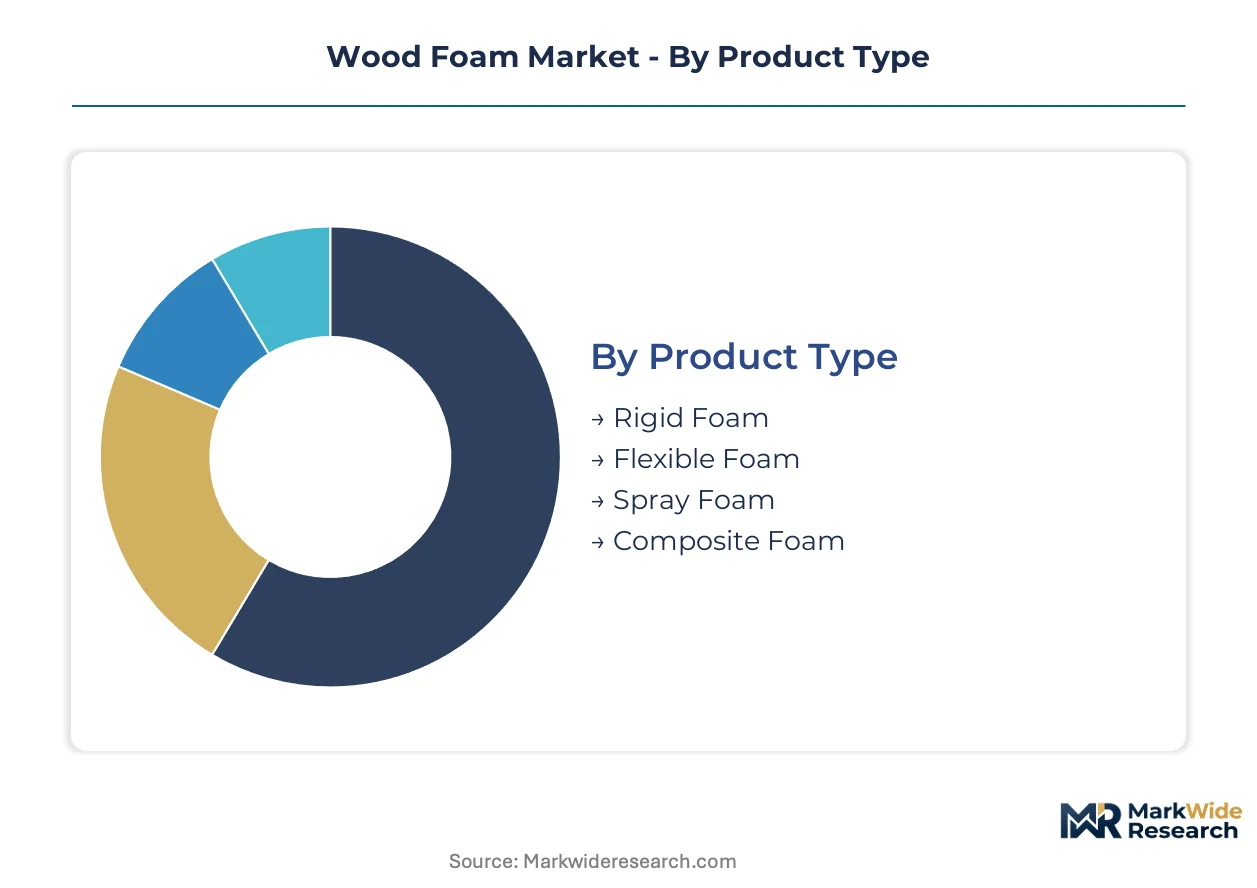
Segmentation in wood foam reveals how formulation chemistry and density specifications map to distinct margin structures. Procurement patterns diverge sharply between rigid insulation boards and flexible cushioning grades.
Product Type:
Customization intensity spans from commodity spray systems to precision-engineered rigid boards with certified lambda values.
- Rigid Foam:High-density panels bonded with polyurethane or phenolic resins achieve thermal conductivity below 0.035 W/m·K. German envelope contractors specify these for passive house retrofits in Bavaria where municipal codes mandate stringent U-values.
- Flexible Foam:Lower-density formulations compress and recover for upholstery and bedding applications. Polish furniture manufacturers are converting production lines from petroleum-based polyurethane to lignocellulosic alternatives ahead of EU Green Deal thresholds.
- Spray Foam:On-site applied systems fill irregular cavities in historic building renovations. Application requires certified installer networks.
- Composite Foam:Multi-layer structures bond wood fiber cores with facing materials for automotive interior panels. Crashworthiness specifications from Stuttgart tier-one suppliers drive qualification protocols.
Most installed capacity flows through Rigid Foam. Expansion is steepest in Flexible Foam.
Application:
End-use requirements dictate adhesive selection and certification burdens across diverging value chains.
- Insulation:Building envelope specifications dominate volume demand. REACH compliance deadlines are forcing reformulation of legacy phenolic systems across Nordic manufacturing clusters.
- Furniture:Upholstery and bedding producers prioritize compression set recovery and emissions profiles. Czech manufacturers are phasing out conventional polyurethane slabs.
- Packaging:Protective cushioning for electronics and appliances favors molded shapes with controlled density gradients. E-commerce fulfillment growth sustains order flow.
- Automotive:Interior panel applications combine acoustic dampening with crash safety standards. Wolfsburg-area suppliers qualify materials through extended OEM validation cycles.
Insulation commands the largest production footprint. Furniture applications are climbing the fastest as petroleum-phase-out deadlines approach.
Material:
Feedstock and binder chemistry determine bio-based content claims and regulatory compliance positioning.
- Wood Fiber:Lignocellulosic feedstock from FSC-certified Nordic forests provides structural skeleton and thermal resistance. Finnish mill operators are locking multi-year supply agreements with German fabricators.
- Polyurethane:Isocyanate and polyol systems bond fibers at controlled densities. Crude oil price volatility compresses margins on medium-density formulations.
- Adhesives:Lignin-derived and bio-based binders satisfy EU Green Deal recycled content mandates. ECHA substance evaluations favor early movers with certified formulations.
- Other Chemicals:Catalysts, surfactants, and flame retardants complete formulation packages. REACH Annex XIV restrictions constrain halogenated additive selection.
Wood Fiber constitutes the dominant input by mass. Adhesives represent the fastest-moving substitution target as formaldehyde restrictions tighten.
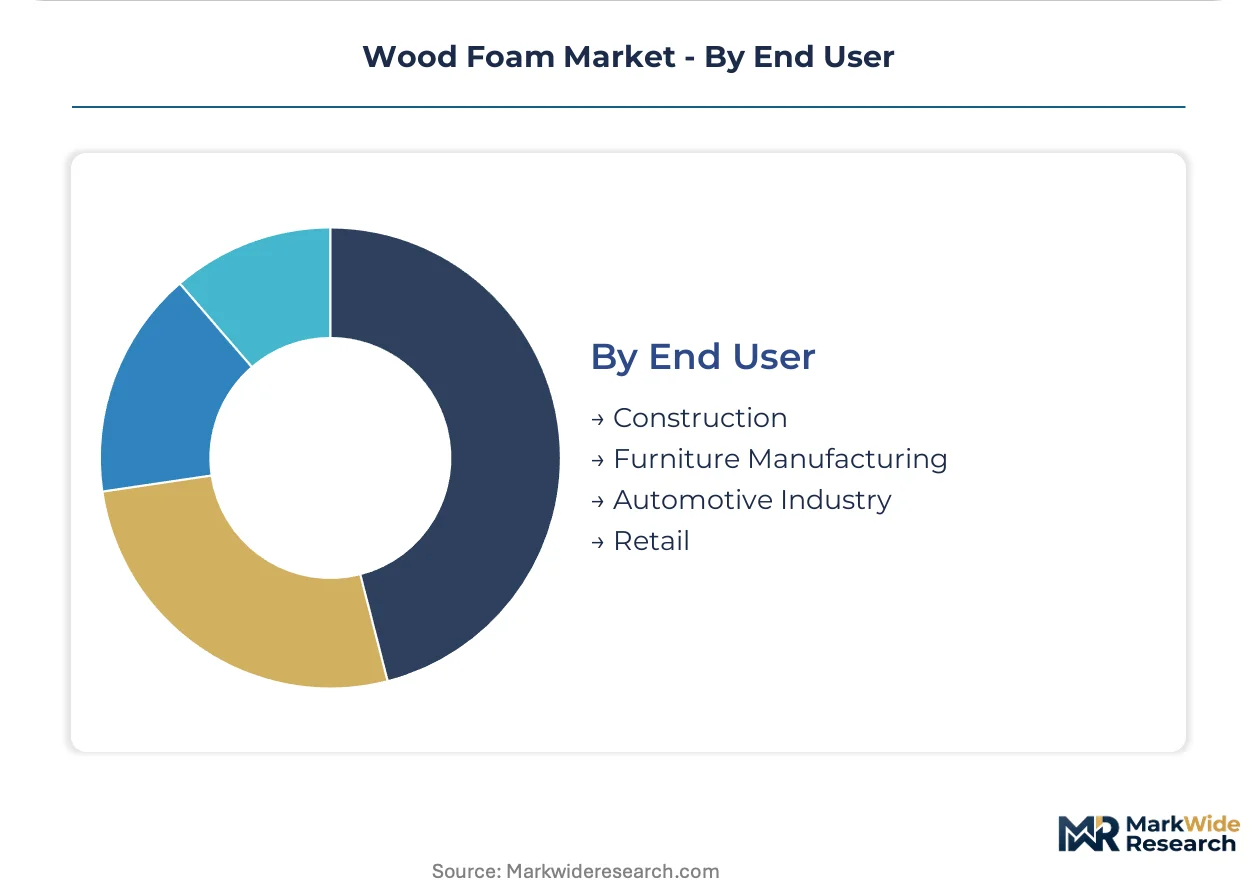
End User:
Customer scale and specification authority fragment procurement channels across project-based and contract manufacturing models.
- Construction:General contractors and envelope specialists purchase rigid boards through distributor networks or direct mill channels. German permit delays for passive house retrofits defer some procurement decisions.
- Furniture Manufacturing:Polish and Czech upholstery producers source flexible foam slabs in volume contracts. Specifications emphasize emissions testing and compression durability.
- Automotive Industry:Tier-one interior suppliers in Stuttgart and Wolfsburg enforce rigorous material qualification protocols. Multi-year platform contracts lock in approved formulations.
- Retail:DIY channels and specialty distributors serve renovation contractors and small-scale builders. Stocking requirements favor standardized dimension boards.
Construction channels absorb the majority of rigid foam output. Furniture Manufacturing is gaining share fastest as petroleum-phase-out conversions accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nordic forestry cluster spanning Finland, Sweden, and Germany concentrates raw lignocellulosic feedstock supply for rigid foam insulation panels. German envelope contractors in Bavaria and Baden-Württemberg are scaling procurement of high-density boards ahead of municipal passive house mandates. REACH compliance deadlines and EU Green Deal recycled content thresholds are compressing formulation timelines across European manufacturing bases.
Germany
Passive house retrofit codes in Bavaria and Baden-Württemberg are pulling rigid foam insulation volumes into municipal housing projects. ECHA substance evaluations under REACH Annex XIV are accelerating substitution of formaldehyde-releasing phenolic resins ahead of 2026 sunset dates. Stuttgart-area automotive tier-one suppliers are qualifying composite wood foam for interior crashworthiness specifications.
Sweden
Vertically integrated mill operations in Värmland and Gävleborg are locking multi-year fiber supply agreements with German fabricators. EU Green Deal mandates on recycled content in construction materials are favoring lignin-derived adhesive formulations in certified building products. Stockholm-based envelope contractors are specifying bio-based bonded boards for public housing retrofits.
Finland
Forestry clusters in Central Finland and North Karelia are shortening raw fiber supply chains to rigid foam panel producers through direct mill-to-fabricator channels. REACH compliance requirements are compressing margins on medium-density polyurethane formulations tied to isocyanate price volatility. Tampere-area insulation fabricators are securing captive resin chemistry through upstream partnerships.
Poland
Furniture manufacturers in Silesia and Greater Poland are converting upholstery production lines from petroleum-based polyurethane slabs to lignocellulosic flexible foam. EU Green Deal phase-out deadlines for conventional petroleum foams are creating white space for bio-based alternatives. Łódź-area bedding producers are prioritizing emissions testing and compression durability in volume contracts.
United States
Building envelope contractors in the Pacific Northwest and Northeast Corridor are evaluating rigid wood foam boards for high-performance retrofits. EPA regulations on formaldehyde emissions from composite wood products are shaping adhesive selection for imported panel systems. Seattle-area passive house developers are piloting Nordic-sourced insulation for multi-family projects.
Wood Foam Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based adhesive certifications and direct mill partnerships. The vendor base stratifies between captive resin chemists, specialized isocyanate formulators, and regional insulation fabricators with timber-proximate manufacturing. Three archetypes dominate: integrated chemical-resin suppliers, Nordic fiber-to-foam specialists, and automotive-focused composite laminators. Capacity expansion in Finnish mill operations and strategic partnerships for lignin-derived binder scale-up represent the dominant competitive moves.
Among integrated chemical suppliers, BASF and Huntsman Corporation exemplify the resin-chemistry archetype, anchoring positions in polyurethane-modified formulations through upstream control over precursor systems. Armacell occupies a position within the insulation-fabricator tier, representing geographic dominance in European distribution channels through timber-proximate board manufacturing. These three companies illustrate how competitive positioning diverges between chemical-integration depth and channel-specific fabrication scale.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Armacell |
| BASF |
| Rogers Corporation |
| Recticel |
| Dow |
| Woodbridge Group |
| Carpenter Co. |
| Covestro |
| Others |
Value Network & Pricing Analysis
Specialized resin chemists in the Nordic forestry cluster command wage premiums that compress margin spreads between premium-certified and standard-grade rigid foam boards. Labor-cost differentials between Finnish mill towns and Polish fabrication zones widen pricing-tier spreads as REACH compliance deadlines force simultaneous reformulation investments.
Pricing Analysis
Input-cost pass-through from isocyanate and lignin-derived adhesive markets shapes contract structures across density grades. Pricing stratifies across premium-lambda, standard-performance, and economy-thickness tiers, with certification-grade differentiation widening spreads. Cost compression in medium-density polyurethane formulations intensifies because crude oil index volatility feeds directly into precursor costs. Construction contractors in price-sensitive Eastern European tenders exhibit highest price sensitivity; Stuttgart-area automotive tier-one suppliers show lowest sensitivity due to multi-year platform lock-ins.
Supply Chain Analysis
EU Green Deal recycled-content mandates and REACH Annex XIV substance restrictions are reshaping raw fiber sourcing toward FSC-certified Nordic origins. Feedstock draws from Finland, Sweden, and Germany, with phenolic resin and polyurethane precursor chemistry anchoring formulation costs. Single-source vulnerability concentrates in isocyanate supply chains tethered to petrochemical refining clusters. Distribution runs through direct mill-to-fabricator channels in Bavaria and passive house retrofit corridors, bypassing traditional insulation distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in wood foam rests on lignin-adhesive cost curves flattening against petrochemical binder volatility, with premium-tier certification spreads widening as REACH deadlines force specification upgrades.
For Market Incumbents: Lock in multi-year fiber supply agreements with Finnish and Swedish mill operators before competitor offtake crowds spot markets. Secure captive resin chemistry partnerships to defend against Huntsman Corporation's isocyanate system penetration in medium-density segments. Accelerate phenolic-to-polyurethane formulation pivots ahead of ECHA sunset enforcement. For New Entrants and Emerging Players: Begin with Polish and Czech furniture manufacturing conversions, where petroleum-based polyurethane phase-out deadlines create immediate white space for flexible foam penetration. Target Silesia upholstery producers with lignin-adhesive certification bundles and direct technical service support. Establish installer certification networks for spray foam retrofit applications in historic German building stock. For Investors and Strategic Acquirers: Chemical companies with bio-based binder pipelines are the most active acquirer in this space, seeking Nordic fiber-to-foam specialists to complete vertical integration. Long-term viability hinges on lignin-adhesive scale-up economics crossing petrochemical cost parity. Watch ECHA substance evaluation acceleration timelines as inflection indicators for certification-premium capture windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lignin Chemistry | BASF's captive resin development secures bio-based binder supply ahead of REACH deadlines. |
| Long-term Supply Agreement | Armacell's Finnish mill partnerships compress fiber procurement costs for Bavarian insulation channels. |
| Green Manufacturing Transition | Lignin-derived adhesive certifications unlock EU Green Deal compliant public housing specifications. |
| Capacity Expansion | Finnish rigid foam board additions target German passive house retrofit demand clusters. |
| Joint Venture | Automotive tier-one suppliers in Stuttgart partner for crashworthiness-qualified composite foam qualification. |
Research Methodology
Coverage spans Germany, Sweden, Finland, Poland, and the United States, with primary inputs from each market informing demand-side validation. Plant managers at Nordic insulation fabricators, procurement leads at German envelope contractors, technical R&D directors at resin chemistry suppliers, and distribution channel partners in Central European furniture manufacturing provided structured interview data. Secondary sources include ECHA substance evaluation databases, EU Green Deal implementation trackers, customs trade data on lignocellulosic feedstock flows, and SEC filings from integrated chemical suppliers. Bottom-up volume modeling triangulates against top-down construction and automotive production forecasts.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product type tier, application end-use, adhesive chemistry class, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation calibrated to historical capacity utilization and announced expansion timelines. Industry-specific inputs encompass REACH enforcement probability weightings and EU Green Deal recycled-content threshold implementation schedules.
Several conditions sit outside the modeled scope, including unannounced M&A activity, breakthrough bio-adhesive technologies, and trade policy shifts affecting isocyanate import flows. Forecasts reflect documented assumptions on regulatory timeline adherence and feedstock certification penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Global Advanced Composites Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
Silica Aerogel Market
Advanced Materials
Nanofibrillar Cellulose Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
Thermal Spray Market
Advanced Materials
US Graphene Market
Advanced Materials
Europe Graphene Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Densified Silica Fume Market
Advanced Materials
Europe Next Generation Anode Materials Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
Hexagonal Boron Nitride (HBN) Market