
 Natural Fiber Reinforcement Materials Market | 2026-2036
Natural Fiber Reinforcement Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Fiber Reinforcement Materials Market Outlook
The EU Green Deal is shifting procurement criteria across European automotive tier-1 suppliers toward bio-based feedstocks. TECNARO GMBH leverages its ARBOFORM and ARBOBLEND compounds to anchor supply relationships with German OEM interior programs. BASF SE sustains R&D intensity in cellulose-reinforced thermoplastics through its Ludwigshafen materials campus. Bcomp differentiates with ampliTex flax fiber prepregs that occupy premium motorsport and luxury electric vehicle niches.
Natural fiber reinforcement materials incorporate bast fibers, leaf fibers, or regenerated cellulose into polymer matrices at loadings of 30-50 weight percent, yielding specific tensile moduli competitive with E-glass composites while reducing part mass 15-25 percent. Hemp and jute product types dominate volume flows into automotive interiors and construction composites, where cost parity with mineral fiber alternatives determines procurement decisions. Non-woven and biocomposite forms capture expanding margin pools as furniture manufacturers and packaging converters seek drop-in replacements for petroleum-based reinforcements under extended producer responsibility frameworks.
REACH restrictions on synthetic fiber additives and the EU F-Gas Regulation's indirect pressure on energy-intensive glass manufacturing are tightening compliance boundaries for incumbent composite suppliers. EPA toxicity evaluations under the Toxic Substances Control Act and India's BIS standards for bio-based building materials create divergent certification pathways that fragment market access protocols. Stakeholders must monitor regulatory convergence between ECHA substance restrictions and emerging state-level procurement mandates in California and New York before committing to regional production footprints.
Market Dynamics
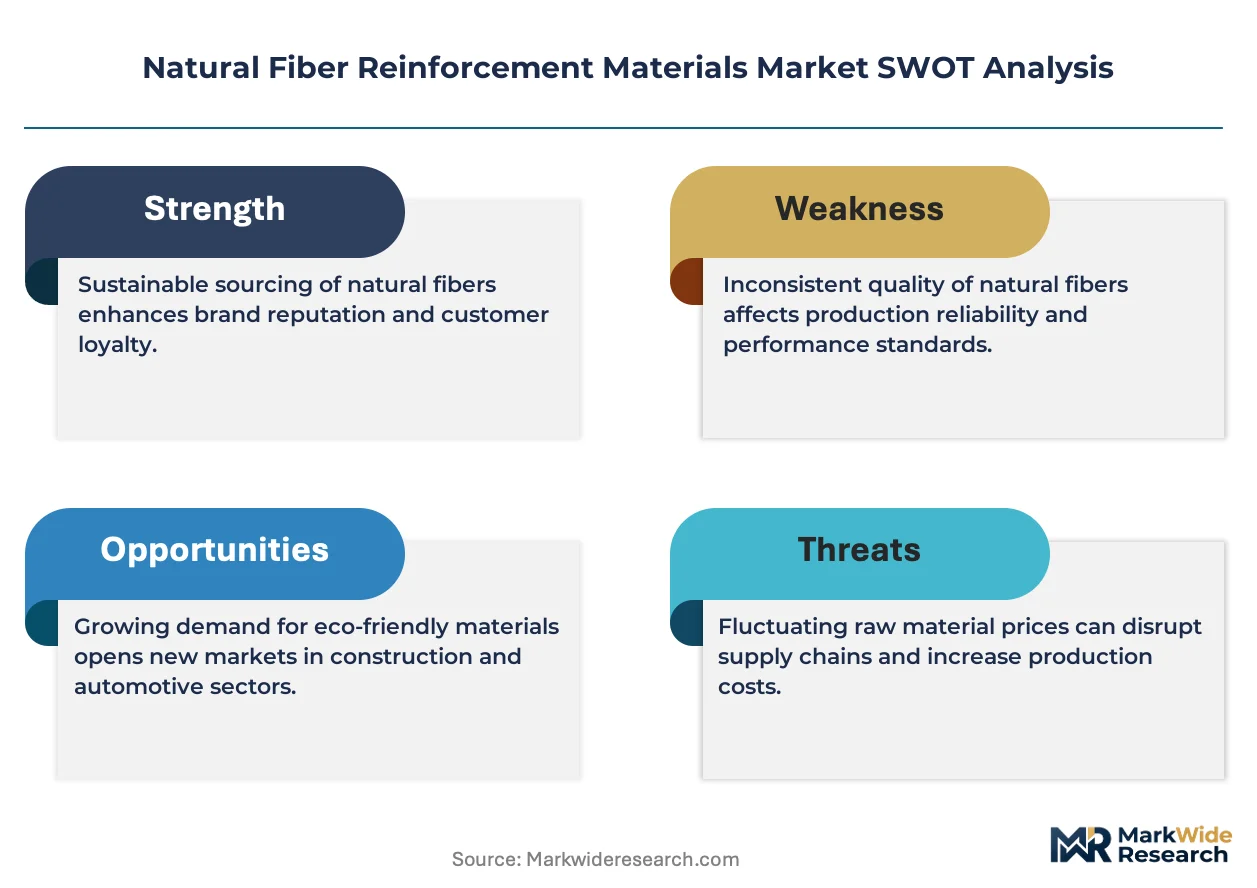
The EU Green Deal's material circularity mandates are compressing substitution timelines for glass fiber in automotive interiors, forcing tier-1 suppliers to requalify bio-composite feedstocks ahead of 2030 model cycles.
Growth Catalysts
- REACH additive restrictions:ECHA substance limitations on synthetic fiber coatings are disqualifying incumbent composite suppliers from German OEM interior programs.
- Automotive lightweighting:Bavaria's supply corridor is consolidating procurement around bast fiber compounds that reduce part mass 15-25 percent versus E-glass alternatives.
- Extended producer responsibility:EU packaging waste directives are mandating bio-based reinforcement quotas for furniture and consumer goods manufacturers.
Market Restraints
- Hemp fiber supply concentration:Processing capacity clusters in Canada's prairie provinces and France's Champagne-Ardenne region, creating geographic vulnerability to weather-driven crop yield swings.
- Moisture sensitivity thresholds:Natural fiber composites face technical barriers in exterior automotive applications where hygroscopic expansion exceeds OEM tolerance specifications.
- Glass fiber cost parity:Energy-intensive E-glass manufacturing in China maintains price competitiveness through subsidized natural gas inputs, undercutting bio-composite margin structures.
Strategic Opportunities
- India's BIS bio-building standards:Gujarat's jute processing belt is expanding capacity to serve construction composite demand under emerging national certification pathways.
- Cellulose nanofibril convergence:Regenerated cellulose reinforcement is penetrating premium packaging applications where barrier performance requirements previously excluded natural fibers.
- Motorsport validation channel:Bcomp's ampliTex flax prepregs are establishing performance credibility that transfers to luxury electric vehicle programs.
Industry Challenges
- Biocomposite processing expertise gap:Injection molders lack trained technicians for optimizing screw profiles and temperature zones specific to high-loading natural fiber compounds.
- Multi-standard certification timelines:Suppliers must simultaneously navigate EPA toxicity evaluations under TSCA, India's BIS bio-material protocols, and ECHA REACH dossier requirements.
- Legacy paint line compatibility:Natural fiber surface chemistry interferes with standard automotive coating adhesion, requiring capital-intensive primer system modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Fiber Reinforcement Materials Market |
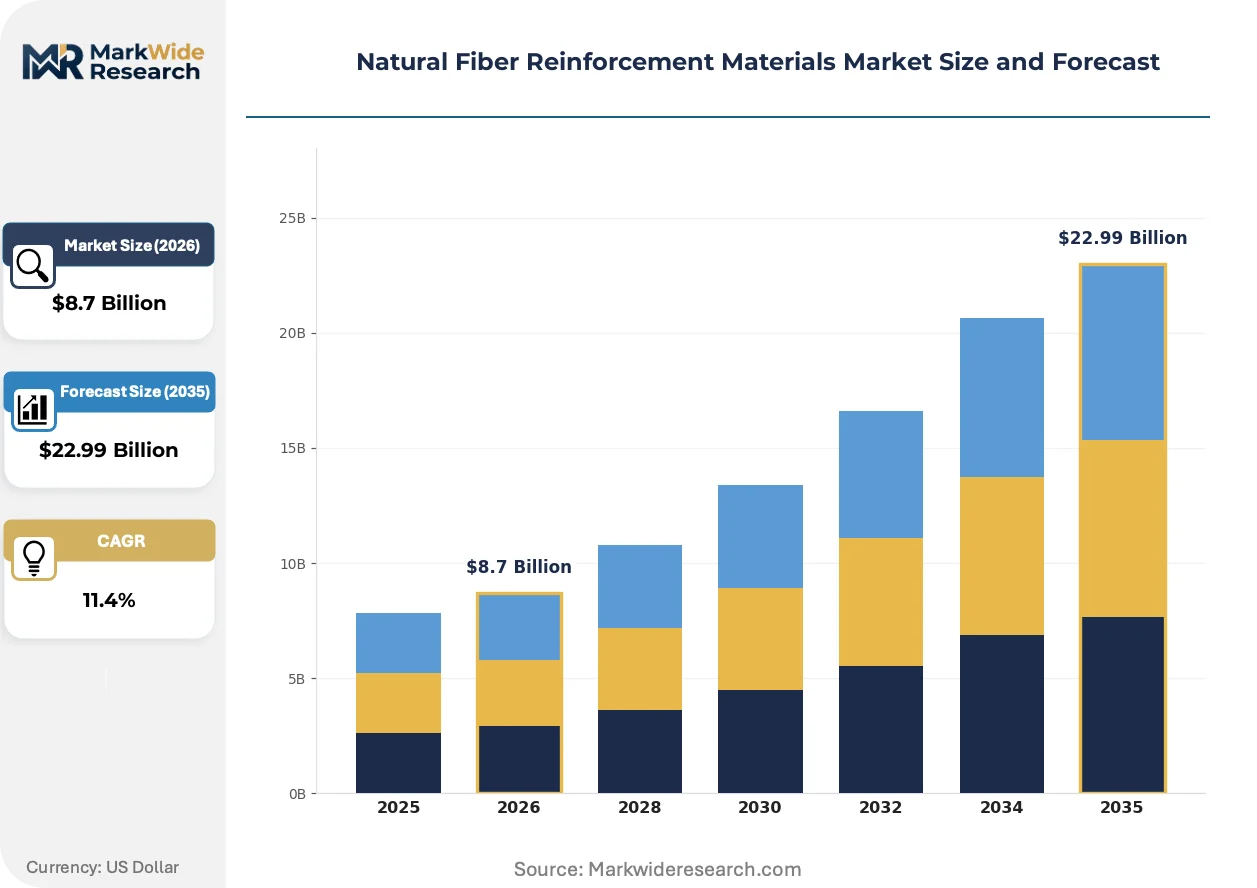
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose, Hemp, Jute, Kenaf Application: Automotive Interiors, Construction Composites, Consumer Goods, Packaging End User: Aerospace, Building Industry, Furniture Manufacturers, Textile Industry Form: Non-woven, Woven, Composite Mats, Biocomposites |
| Companies Covered | TECNARO GMBH, Trex Company, Inc., BASF SE, UPM, Bcomp, DuPont, HempFlax, Polyvlies Franz Beyer GmbH, Procotex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Fiber Reinforcement Materials Market Strategic Shifts
Non-woven natural fiber mat production is overtaking woven textile forms as the dominant reinforcement architecture, compressing cycle times and enabling automated preforming for complex geometries.
Flax fiber prepregs are overtaking glass fiber sheet molding compounds in European electric vehicle battery enclosures and trunk floors, with German OEMs specifying ampliTex grades for 2027 platform launches. The shift is overtaking incumbent thermoset suppliers who lack natural fiber processing experience, forcing partnerships with agricultural fiber processors.
REACH restrictions on perfluorinated additives are tightening compliance boundaries for synthetic fiber manufacturers, redirecting R&D investment toward bio-based sizing chemistry. The F-Gas Regulation's indirect pressure on energy-intensive glass manufacturing is accelerating substitution timelines. Automotive tier-1 suppliers in Stuttgart and Munich are requalifying hemp-reinforced polypropylene for A-surface interior panels.
Automotive OEMs are consolidating supplier relationships around compounders who control fiber sourcing through captive agricultural partnerships. Procurement teams are disqualifying vendors who rely on spot-market bast fiber purchases. The concentration is most visible in Germany's automotive supply corridor, where TECNARO and BASF SE are anchoring multi-year supply agreements with Bavarian OEM interior programs.
Natural Fiber Reinforcement Materials Market Segmentation
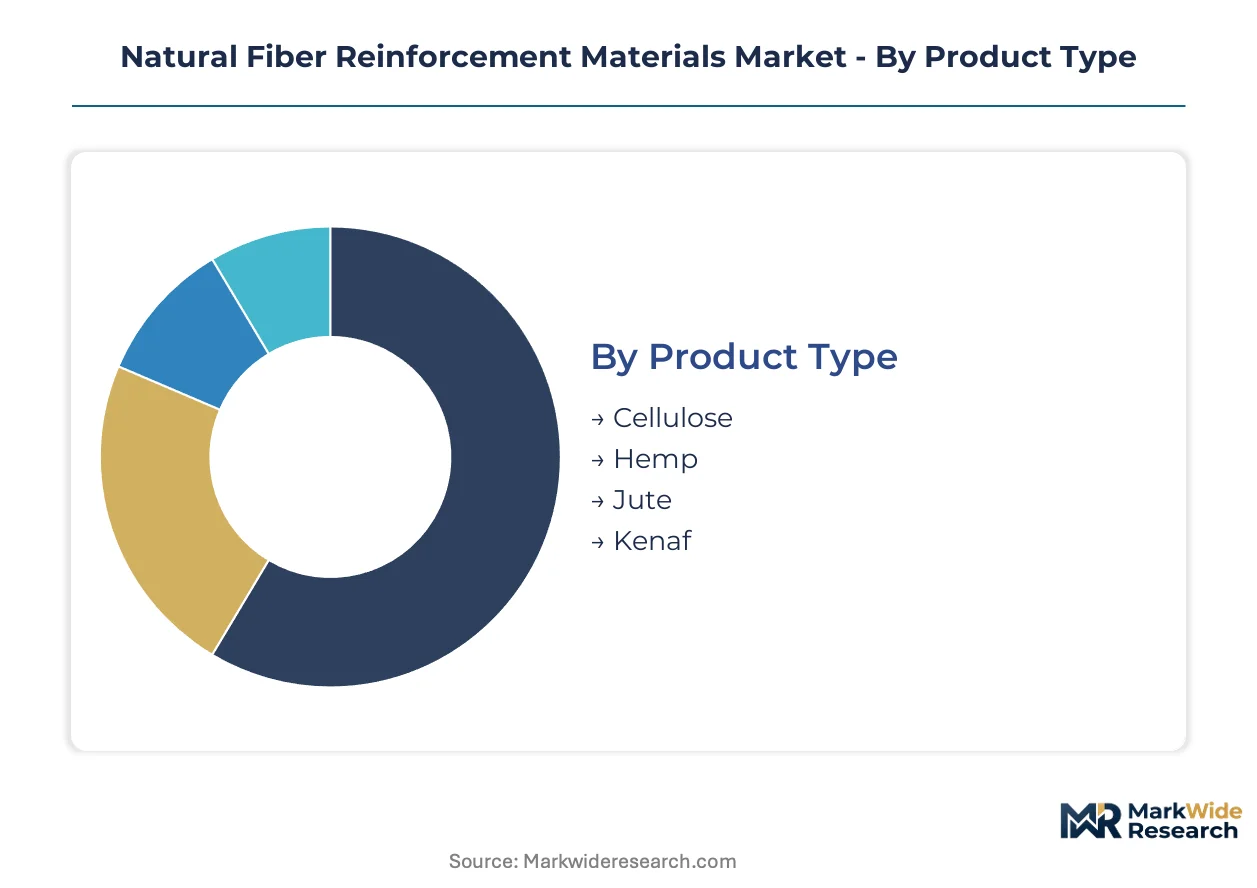
Natural fiber reinforcement materials fragment across four distinct dimensions that determine procurement pathways and margin capture. Product type and form dictate processing compatibility with polymer matrices, while application and end-user concentration shape regional demand corridors and certification requirements.
Product Type:
Hemp and jute dominate volume flows through established agricultural supply chains, while cellulose and kenaf occupy narrower premium niches with distinct technical specifications.
- Hemp:Bast fibers with cellulose content exceeding 70 percent deliver tensile strength parity with E-glass at 40 percent lower density. Bavarian automotive tier-1 suppliers specify hemp-reinforced polypropylene for A-surface interior panels under EU Green Deal circularity mandates.
- Jute:Coarser fiber architecture suits compression-molded construction composites and lower-cost automotive applications. Gujarat's processing belt is expanding capacity to serve India's emerging BIS bio-building standards for infrastructure reinforcement.
- Cellulose:Regenerated cellulose nanofibrils enable thin-film barrier applications in premium packaging where moisture sensitivity thresholds exclude conventional bast fibers.
- Kenaf:Rapid growth cycle and drought tolerance position this segment for geographic diversification of supply away from European and South Asian concentration.
Mature deployment sits with hemp. Newer deployment is concentrated in kenaf as processors seek climate-resilient feedstock alternatives.
Application:
Automotive interiors absorb the majority of compounder capacity, though construction composites and packaging applications are climbing the fastest as regulatory frameworks mature.
- Automotive Interiors:Door panels, seat backs, and trunk floors utilize 30-50 weight percent fiber loadings in polypropylene matrices. German OEMs are requalifying bio-composite feedstocks ahead of model cycle deadlines.
- Construction Composites:Non-woven mats replace glass fiber in facade panels and structural insulated panels. France's Champagne-Ardenne region anchors European supply for this segment.
- Consumer Goods:Furniture frames and electronics housings drive demand under extended producer responsibility frameworks mandating bio-based content quotas.
- Packaging:Cellulose nanofibril reinforcement penetrates barrier coatings and molded pulp applications where petroleum-based alternatives face REACH restriction pressure.
Procurement consolidation centers on automotive interiors. Steepest expansion trajectory belongs to packaging as food-contact certification pathways standardize.
End User:
Building industry and furniture manufacturers represent volume demand, while aerospace qualification programs and textile technical applications command premium pricing tiers.
- Building Industry:Structural panels and insulation systems specify natural fiber composites under national green building codes. India's construction sector is driving capacity expansion in Gujarat's jute processing corridor.
- Furniture Manufacturers:Flat-pack furniture frames and upholstery substrates utilize non-woven mat forms for automated cutting and edge-finishing operations.
- Aerospace:Secondary structural applications and cabin interior components pursue qualification under FAA and EASA flammability standards, with flax prepregs establishing validation through motorsport channels.
- Textile Industry:Technical textiles and geotextiles deploy woven natural fiber architectures for erosion control and agricultural applications.
Commercial maturity rests with building industry adoption. Emerging qualification activity concentrates in aerospace as Bcomp's ampliTex prepregs transfer performance credibility from motorsport.
Form:
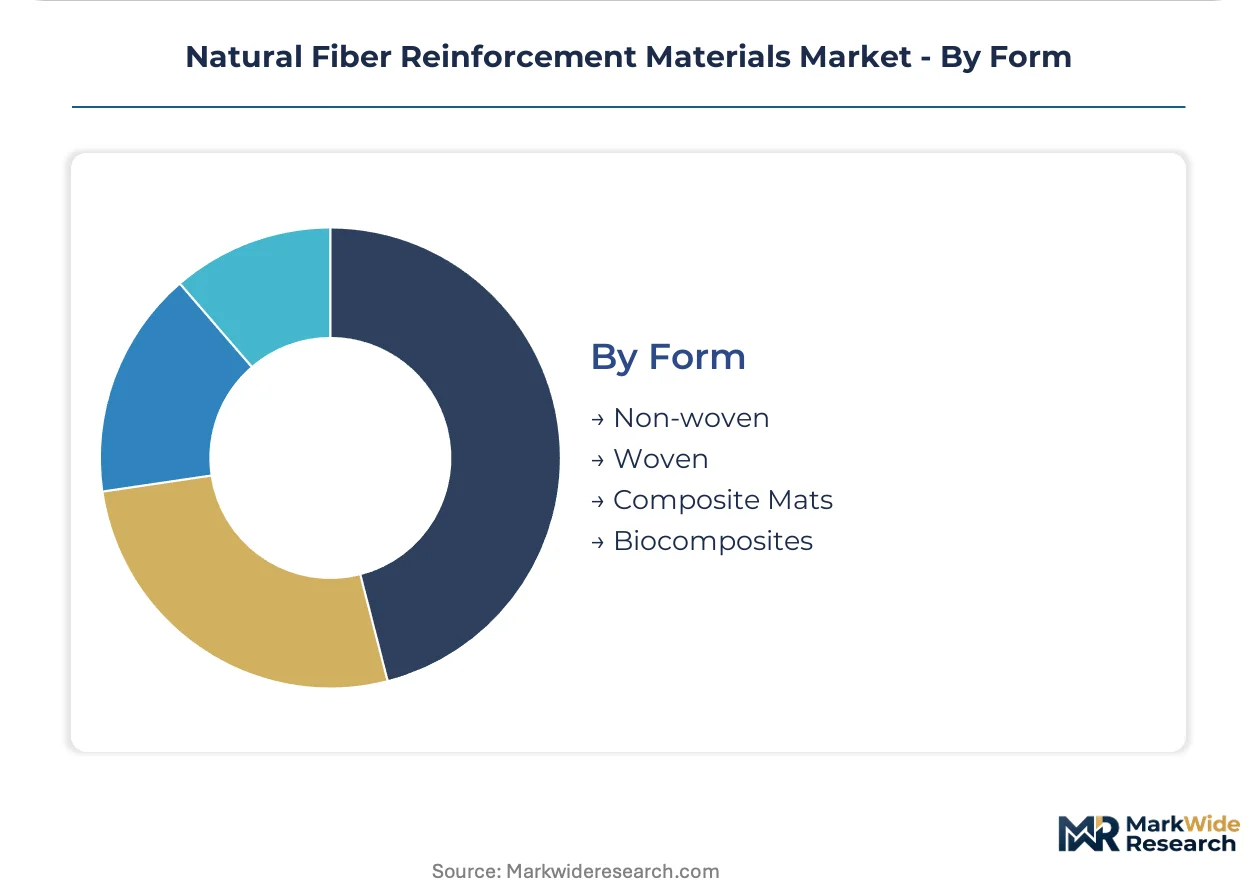
Non-woven architectures are displacing woven forms as automated preforming requirements reshape compounder processing economics.
- Non-woven:Random fiber orientation enables isotropic mechanical properties and rapid thermoforming cycle times. This form captures expanding share in automotive interior programs.
- Biocomposites:Pre-compounded pellets with optimized fiber length distribution reduce injection molding complexity for processors lacking natural fiber expertise.
- Woven:Controlled fiber alignment delivers directional strength for structural applications, though higher labor content constrains cost competitiveness.
- Composite Mats:Preformed sheet goods enable compression molding of complex geometries with reduced scrap rates versus cut-and-place operations.
Established volume flows through woven textile forms. Fastest capacity addition targets non-woven production lines serving automated automotive preforming requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's automotive supply corridor anchors European demand concentration, with Stuttgart and Munich OEMs requalifying bio-composite feedstocks ahead of 2027 platform launches. Processing clusters in France's Champagne-Ardenne and Canada's prairie provinces supply bast fiber raw materials to compounders serving interior panel programs.
Germany
Automotive tier-1 suppliers in Stuttgart and Munich specify hemp-reinforced polypropylene for A-surface interior panels under EU Green Deal circularity mandates. ECHA REACH restrictions on synthetic fiber coatings disqualify incumbent composite suppliers from Bavarian OEM programs. TECNARO GMBH anchors multi-year supply relationships through its Ludwigshafen materials campus.
France
Champagne-Ardenne's hemp processing belt supplies non-woven mat production for construction composites and automotive preforming operations. The EU F-Gas Regulation applies indirect pressure on energy-intensive glass manufacturing, accelerating substitution timelines for natural fiber alternatives. Regional compounders serve facade panel and structural insulated panel specifications under national green building codes.
India
Gujarat's jute processing corridor expands capacity to serve construction composite demand under emerging BIS bio-building standards. The Bureau of Indian Standards certification pathway for bio-based building materials creates infrastructure reinforcement opportunities. Ahmedabad and Surat processors supply non-woven mat forms for flat-pack furniture and upholstery substrate applications.
Japan
METI's carbon neutrality roadmap drives automotive OEM bio-composite programs for interior panels and trunk floors. Toyota and Honda procurement teams consolidate supplier relationships around compounders with captive agricultural fiber partnerships. Nagoya-based tier-1 suppliers requalify kenaf-reinforced thermoplastics for 2028 model cycle integration.
United States
EPA toxicity evaluations under the Toxic Substances Control Act fragment market access protocols for bio-composite suppliers. California and New York state-level procurement mandates for bio-based content create divergent certification requirements. Midwest agricultural processors supply hemp fiber to automotive compounders serving Detroit OEM interior programs.
Natural Fiber Reinforcement Materials Market Competitive Environment
Premium-margin players sit above commodity-margin players across fiber sourcing control and automotive qualification depth. The vendor base stratifies into three tiers: integrated compounders with captive agricultural partnerships, specialized fiber processors serving spot markets, and diversified chemical conglomerates with materials campus R&D infrastructure. Two dominant competitive moves reshape positioning: backward integration into hemp and jute cultivation through multi-year supply agreements, and technology licensing partnerships that transfer biocomposite processing expertise to injection molders lacking natural fiber screw profile optimization.
Among European integrated compounders, TECNARO GMBH and BASF SE exemplify the agricultural partnership archetype, anchoring supply relationships with Bavarian OEM interior programs through Ludwigshafen and regional production footprints. Bcomp occupies a specialist position within the premium motorsport and luxury electric vehicle niche, representing the performance validation channel that transfers credibility to broader automotive adoption.
| Leading Market Players |
|---|
| TECNARO GMBH |
| Trex Company, Inc. |
| BASF SE |
| UPM |
| Bcomp |
| DuPont |
| HempFlax |
| Polyvlies Franz Beyer GmbH |
| Procotex Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fiber processors in France's Champagne-Ardenne and Gujarat's jute belt maintain pricing discipline through multi-year agricultural partnerships that insulate compounders from spot-market volatility. This ownership structure limits speculative inventory buildup while reinforcing contract-based offtake terms with Bavarian automotive tier-1 suppliers.
Pricing Analysis
Value-based pricing anchored to part-mass reduction outcomes dominates procurement negotiations between compounders and Stuttgart OEM interior programs. Three-tier pricing structure across premium, standard, and economy levels separates ampliTex flax prepregs from hemp-reinforced polypropylene and commodity jute compounds. Cost compression in standard-tier bast fiber grades is intensifying because subsidized E-glass from Chinese manufacturers undercuts bio-composite margin structures. Furniture manufacturers under extended producer responsibility mandates exhibit highest price sensitivity, while motorsport and luxury electric vehicle programs demonstrate lowest sensitivity due to performance validation premiums.
Supply Chain Analysis
Regional distribution centers in Ludwigshafen, Stuttgart, and Munich operate hub-and-spoke patterns that consolidate bast fiber shipments from France and Canada before just-in-time delivery to automotive preforming lines. Geographic supply concentration clusters in France's Champagne-Ardenne hemp belt, Canada's prairie provinces, and Gujarat's jute processing corridor. Raw material dependencies include agricultural bast fibers, polypropylene resin matrices, and bio-based sizing chemistry. Single-source vulnerability from weather-driven crop yield swings in concentrated growing regions threatens supply continuity. Distribution runs through compounder-controlled logistics networks serving qualified OEM interior programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH additive restrictions on synthetic fiber coatings construct a barrier-to-entry moat for compounders with validated bio-based feedstock dossiers.
For Market Incumbents: To counter disqualification pressure from German OEM interior programs, TECNARO GMBH and BASF SE should deepen captive agricultural partnerships in Champagne-Ardenne and expand Ludwigshafen materials campus capacity for cellulose-reinforced thermoplastic R&D. Certification investment in India's emerging BIS bio-building standards creates channel control leverage for construction composite expansion. For New Entrants and Emerging Players: Direct-to-compounder digital platforms bypass established distributor markups and enable spot-market access for smaller automotive tier-2 suppliers lacking procurement scale. India's Gujarat jute processing belt represents the most penetrable geography under BIS standardization. Technical partnership with injection molders seeking screw profile optimization for high-loading natural fiber compounds offers the strongest go-to-market angle. For Investors and Strategic Acquirers: Bcomp's motorsport-to-luxury-EV validation channel securing German OEM platform specifications is the leading indicator that premium-margin flax prepreg technology commands acquisition premiums. Five-to-ten year viability favors integrated compounders with backward control over hemp cultivation and multi-year supply agreements. The signal to monitor is requalification timeline compression for A-surface interior panels ahead of model cycle deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hemp Cultivation | TECNARO GMBH secures multi-year supply relationships with Bavarian OEM programs through captive agricultural partnerships. |
| Cellulose Nanofibril R&D Scale-Up | BASF SE's Ludwigshafen campus penetrates premium packaging barrier applications previously closed to conventional bast fibers. |
| Motorsport Validation Channel Expansion | Bcomp transfers ampliTex flax prepreg performance credibility from racing programs to luxury electric vehicle battery enclosures. |
| BIS Certification Pathway Investment | Gujarat processors capture construction composite demand under India's emerging national bio-building material standards. |
| Non-Woven Mat Production Capacity Addition | Automated preforming lines compress cycle times for complex automotive interior geometries and reduce labor content. |
Study Parameters
Independent corroboration across procurement directors at German automotive tier-1 suppliers, plant managers at Champagne-Ardenne hemp processing facilities, and regulatory affairs leads navigating ECHA REACH dossier requirements underwrites the qualitative findings in this study. Primary interviews with compounder technical directors, jute processing belt operators in Gujarat, and furniture manufacturer sustainability officers combined with secondary validation from EU customs trade data, BIS draft standard publications, and SEC filings from diversified chemical conglomerates. Bottom-up fiber volume estimates and top-down polymer matrix consumption patterns were triangulated to anchor segmentation splits.
Rate-of-change decomposition across fiber type, application end-use, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include bast fiber species, reinforcement form architecture, automotive interior versus construction composite application, and captive versus spot-market supply relationships. CAGRs were derived from installed automotive platform forecasts, green building code adoption curves, and extended producer responsibility mandate implementation schedules. Forecast inputs incorporated EU F-Gas Regulation indirect pressure on glass manufacturing energy costs and METI carbon neutrality roadmap procurement specifications.
The model holds under continued ECHA substance restriction tightening and stable agricultural yield patterns in France and Canada; deviation in India's BIS certification timeline acceleration or Chinese E-glass subsidy expansion would shift volume trajectories. Forecasts reflect assumptions regarding OEM requalification cycle timing and bio-based sizing chemistry technical maturation. Periodic stress-testing of base assumptions against regulatory enforcement intensity and alternative fiber crop development is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Drug Integrated Polymer Fibers Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
Asia-Pacific Carbon Fiber Market
Fibers
Global R-Glass Fiber Market
Fibers
Polytetrahydrofuran Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Asia-Pacific Nanofiber Market
Fibers
4-Strand Fan-Shaped Strand Wire Rope Market
Fibers
E-Glass Fiber Market
Fibers
North America Carbon Fiber Market
Fibers
Dry-Molded Fibre Market
Fibers
North America Glass Fiber Reinforced Gypsum Market
Fibers
Global Electronic Fiberglass Market
Fibers
Asia-Pacific Optical Fiber Raw Material Market
Fibers
Carbon Fiber Tapes Market