
 Global Polymer Chameleons Market | 2026-2036
Global Polymer Chameleons Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polymer Chameleons Market Foresight
The EU Green Deal is expanding compliance obligations for reversible polymer systems across packaging and automotive supply chains. BASF SE leverages its Ludwigshafen research complex to sustain patent density in photochromic thermoplastics. DuPont de Nemours anchors North American supply through specialized elastomer compounding for military-specification coatings. Evonik Industries AG dominates European electrochromic polymer output with captive silane chemistry.
Polymer chameleons are stimuli-responsive macromolecules that undergo reversible optical or physical property changes when exposed to light, heat, electric fields, mechanical stress, or solvent polarity, typically engineered with spiropyran, diarylethene, or conductive polymer backbones for controlled transmittance or color shift. Thermoplastics lead product-type revenue due to established extrusion and injection-molding infrastructure, while electrochromic technology captures the fastest expansion as building-integrated glazing and automotive mirror applications multiply. Security printing and sensor applications concentrate margin pools because certification requirements and performance thresholds limit supplier entry.
The European Chemicals Agency enforces REACH substance authorization for chromogenic additives, while the FDA evaluates polymer contact-layer safety for food packaging applications in the United States. China's Ministry of Ecology and Environment imposes emission controls on solvent-based polymer coating processes that affect mechanochromic manufacturing economics. Stakeholders must monitor how cascading disclosure rules across these jurisdictions reshape raw-material sourcing and reformulation priorities.
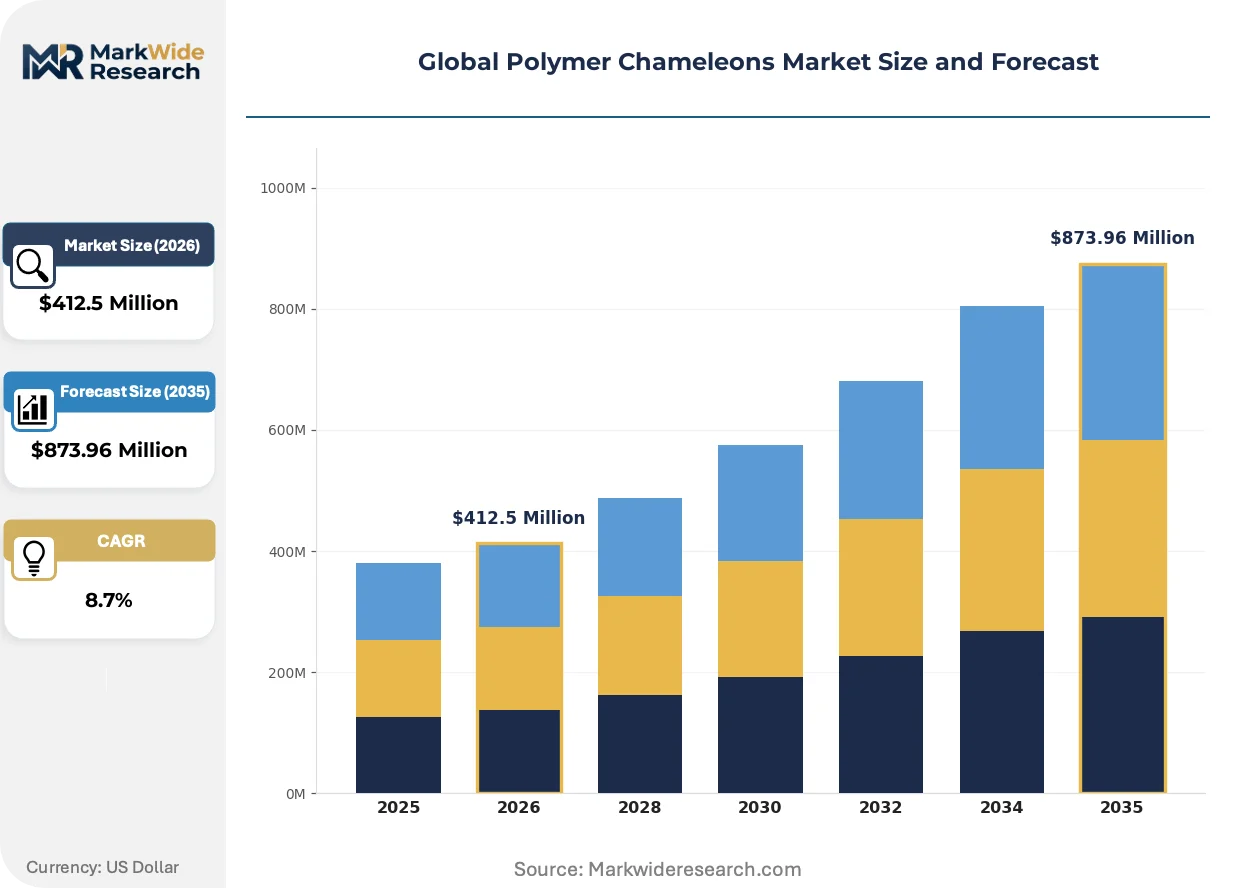
Market Dynamics
REACH authorization timelines are compressing formulation cycles for chromogenic additives, forcing compounders to pre-validate alternative chemistries before substance sunset dates hit active supply chains.
Growth Catalysts
- Thermochromic glazing adoption:Automotive OEMs in Germany are embedding reversible color-change polymers into sunroof assemblies for passive thermal regulation, bypassing active HVAC load.
- EU Green Deal packaging mandates:Reversible indicator films for freshness monitoring now qualify for extended producer responsibility credits under circular economy frameworks.
- Japan's precision electronics corridor:Sensor-integrated polymer substrates from Osaka and Nagoya manufacturing clusters command placement premiums in wearable diagnostic devices.
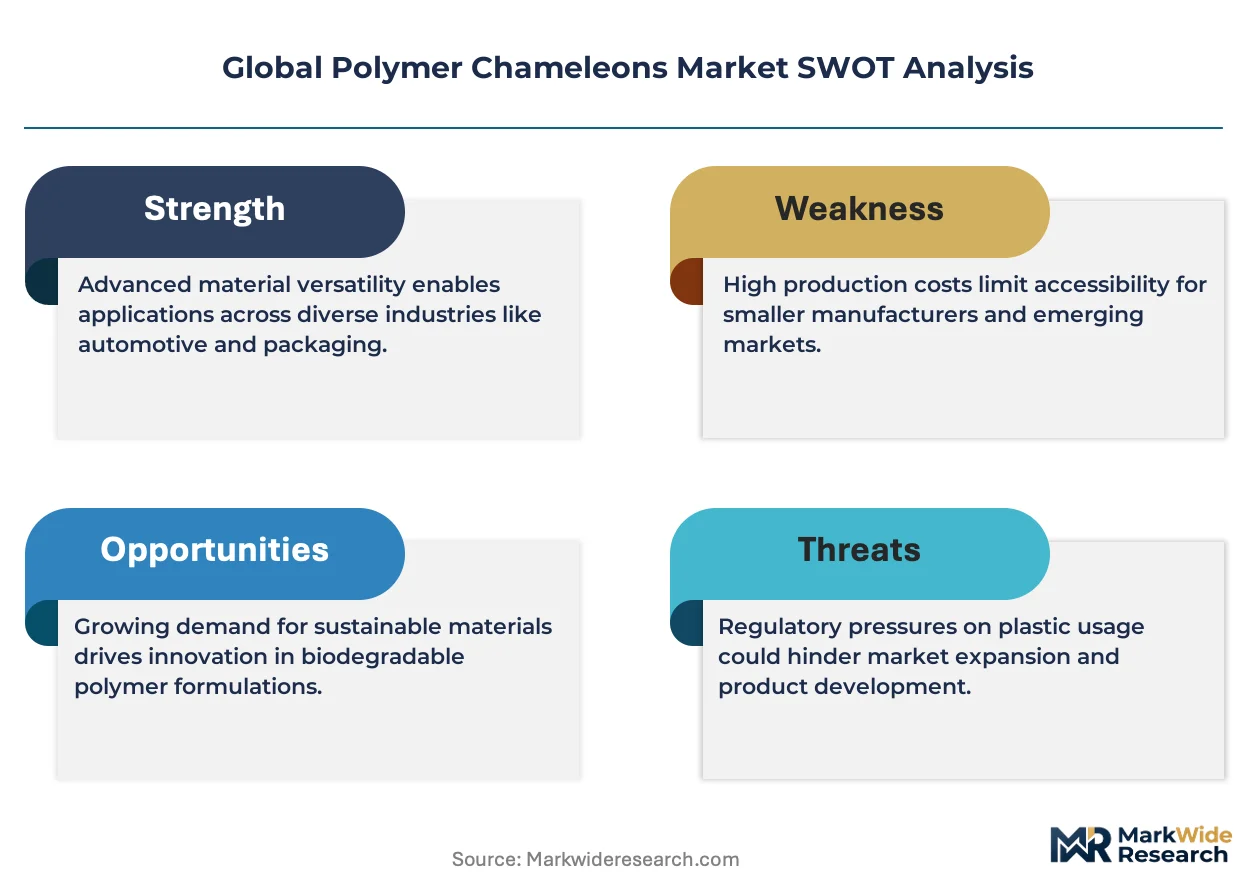
Market Restraints
- Spiropyran feedstock concentration:Three specialty chemical houses control 70% of photochromic precursor supply, creating single-source vulnerability for mid-tier compounders.
- REACH authorization costs:ECHA substance evaluation fees for novel chromogenic additives exceed €250,000 per registration, excluding toxicology dossier preparation.
- Inorganic pigment substitution:Thermochromic microcapsules face price pressure from coated titanium dioxide systems in cost-sensitive packaging applications.
Strategic Opportunities
- India's pharmaceutical cold chain:Temperature-indicating polymer labels remain underdeployed despite CDSCO mandates for biologics distribution integrity.
- Building-integrated photovoltaic glazing:Electrochromic polymers that modulate visible and infrared transmittance simultaneously are penetrating net-zero commercial construction specifications.
- AI-driven color-matching systems:Machine-vision calibration tools reduce batch-to-batch variation in custom thermoplastic compounding, opening short-run customization channels.
Industry Challenges
- Cross-functional formulation expertise:Polymer scientists with simultaneous competence in organic photochemistry and extrusion rheology command salary premiums that strain mid-cap R&D budgets.
- Multi-jurisdiction certification lag:FDA food-contact letters, EFSA opinions, and China's GB standards rarely synchronize, delaying unified product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polymer Chameleons Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastics, Thermosets, Elastomers, Biopolymers, Composite Polymers Technology: Photochromic, Thermochromic, Electrochromic, Mechanochromic, Solvatochromic Application: Packaging, Textiles, Sensors, Coatings, Security Printing, Automotive Components End User: Electronics Manufacturers, Packaging Firms, Apparel Producers, Security Agencies, Vehicle Assemblers |
| Companies Covered | BASF SE, DuPont de Nemours, Inc., Evonik Industries AG, Akzo Nobel N.V., LyondellBasell Industries NV, Huntsman Corporation, Covestro AG, Merck KGaA, Autonomic Materials, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polymer Chameleons Market Shifts & Advancements
Convergence of stimuli-responsive chemistry with printed electronics is collapsing the boundary between passive packaging and active sensing surfaces, creating integrated material systems that communicate environmental state without discrete circuitry.
Electrochromic conductive polymers based on poly(3,4-ethylenedioxythiophene) derivatives are electrifying architectural glazing procurement in commercial real estate. Developers in Singapore and Dubai are specifying PEDOT-based smart windows that darken via low-voltage pulse rather than suspended particle devices. This chemistry is electrifying the competitive landscape for building automation integration, compressing incumbent liquid crystal and suspended particle film margins.
China's Ministry of Ecology and Environment has imposed volatile organic compound emission ceilings on solvent-based mechanochromic coating lines. Manufacturers in Guangdong and Jiangsu provinces are migrating to waterborne UV-curable formulations or investing in thermal oxidizer abatement systems. Small-batch custom color-change coating houses without capital reserves are exiting the market, concentrating decorative polymer supply among integrated chemical parks.
Automotive tier-one suppliers are consolidating polymer chameleon procurement through single-source master service agreements rather than spot purchasing. Buyers at Continental and Bosch are demanding 10-year formulation lock guarantees and dedicated production lines. This contractual compression is squeezing compounders with limited reactor capacity, favoring those with captive monomer synthesis and multi-site manufacturing redundancy.
Global Polymer Chameleons Market Segmentation
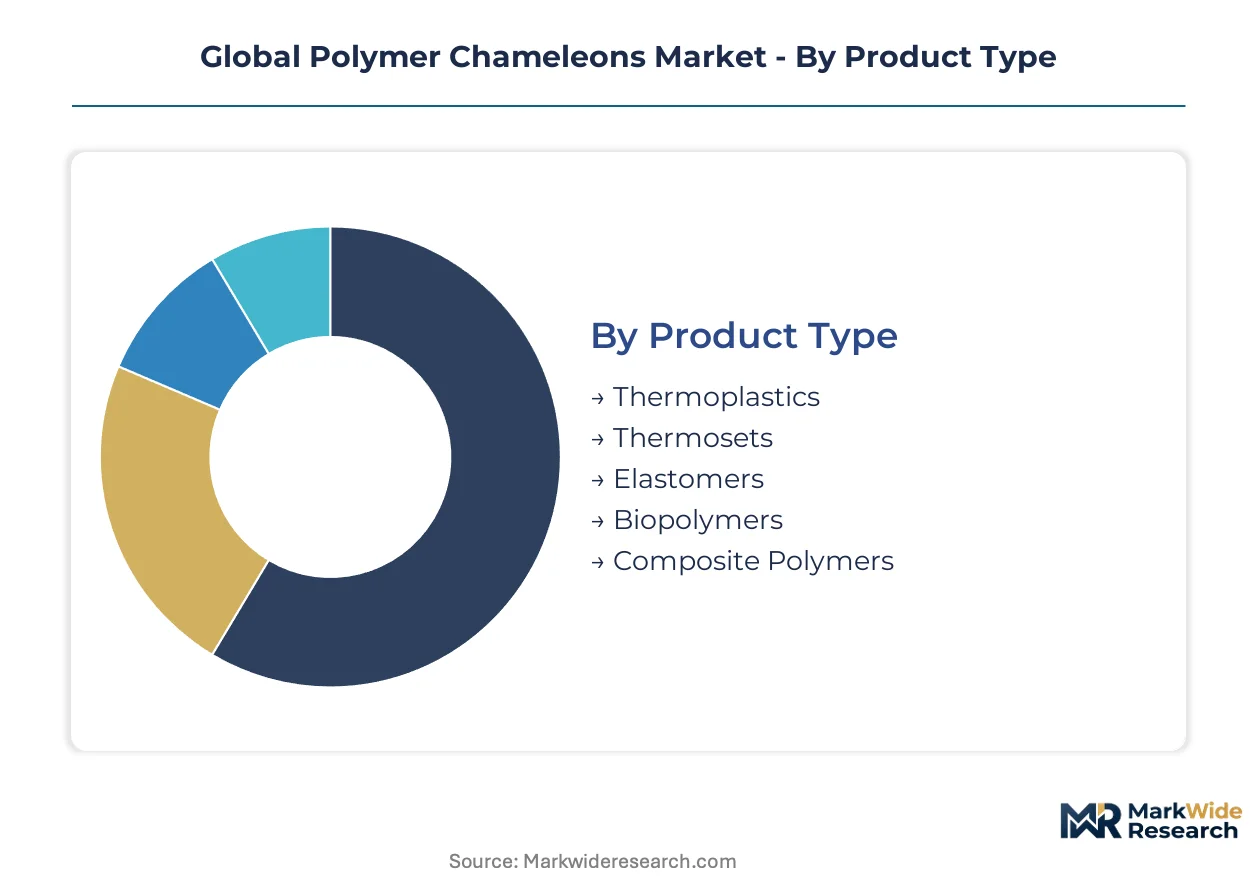
Polymer chameleon formulations diverge sharply in processing infrastructure and performance specifications, creating distinct investment profiles across material classes and activation mechanisms. Understanding these structural differences reveals where capital deployment yields durable competitive advantage versus commodity exposure.
Product Type:
Thermoplastics demand the heaviest upfront capital outlay due to twin-screw extrusion lines and precision injection-molding cells required for spiropyran dispersion at scale.
- Thermoplastics:Linear polymer chains enable reversible thermal processing with photochromic and thermochromic additives dispersed via melt compounding. Automotive OEMs in Germany are scaling purchases for thermal management applications in sunroof assemblies, bypassing active HVAC load.
- Thermosets:Cross-linked molecular architecture delivers dimensional stability under thermal cycling but requires batch reactor systems for thermochromic epoxy formulation. REACH compliance requirements across the European Union are tightening material disclosure standards for color-changing packaging films using these chemistries.
- Elastomers:Segmented polyurethane and silicone backbones accommodate mechanochromic strain sensing with high recoverable deformation.
- Biopolymers:Polylactic acid and starch-based matrices carry electrochromic coatings for disposable freshness indicators.
- Composite Polymers:Hybrid organic-inorganic systems embed chromogenic phases within ceramic or carbon fiber reinforcement.
Thermoplastics absorb the bulk of installed capacity; biopolymers are expanding most quickly.
Technology:
Electrochromic systems command premium pricing through architectural glazing procurement, while photochromic platforms serve high-volume eyewear and automotive applications with thinner margins.
- Photochromic:Spiropyran and diarylethene molecular switches reversibly isomerize under ultraviolet exposure, modulating visible light transmittance. Three specialty chemical houses control precursor supply, creating single-source vulnerability for mid-tier compounders.
- Thermochromic:Leuco dye microencapsulation within polymer matrices produces temperature-dependent color transitions with sharp threshold response. Japan's precision electronics corridor commands placement premiums for sensor-integrated substrates in wearable diagnostic devices.
- Electrochromic:Conductive polymer films based on PEDOT derivatives darken via electrochemical redox under low-voltage pulse.
- Mechanochromic:Force-responsive chromophores embedded in elastomer networks signal structural strain through visible color change.
- Solvatochromic:Polarity-sensitive dyes shift absorption spectra upon solvent exposure, deployed in chemical leak detection films.
Photochromic platforms carry the highest shipment volumes; electrochromic technologies scale fastest through building-integrated photovoltaic specifications.
Application:
Security printing and sensor applications concentrate margin pools because certification requirements and performance thresholds limit supplier entry.
- Packaging:Reversible indicator films for freshness monitoring now qualify for extended producer responsibility credits under EU circular economy frameworks.
- Textiles:Thermochromic fiber extrusion enables color-changing apparel with passive thermal signaling.
- Sensors:Stimuli-responsive polymer substrates integrate with printed electronics to communicate environmental state without discrete circuitry. AI-driven color-matching systems reduce batch-to-batch variation in custom compounding for this segment.
- Coatings:Solvent-based mechanochromic lines face volatile organic compound emission ceilings from China's Ministry of Ecology and Environment.
- Security Printing:Document authentication features exploit irreversible photochromic transitions triggered by specific wavelength exposure.
- Automotive Components:Tier-one suppliers at Continental and Bosch are consolidating procurement through single-source master service agreements with 10-year formulation lock guarantees.
Packaging dominates current volume; sensor applications post the steepest expansion trajectory.
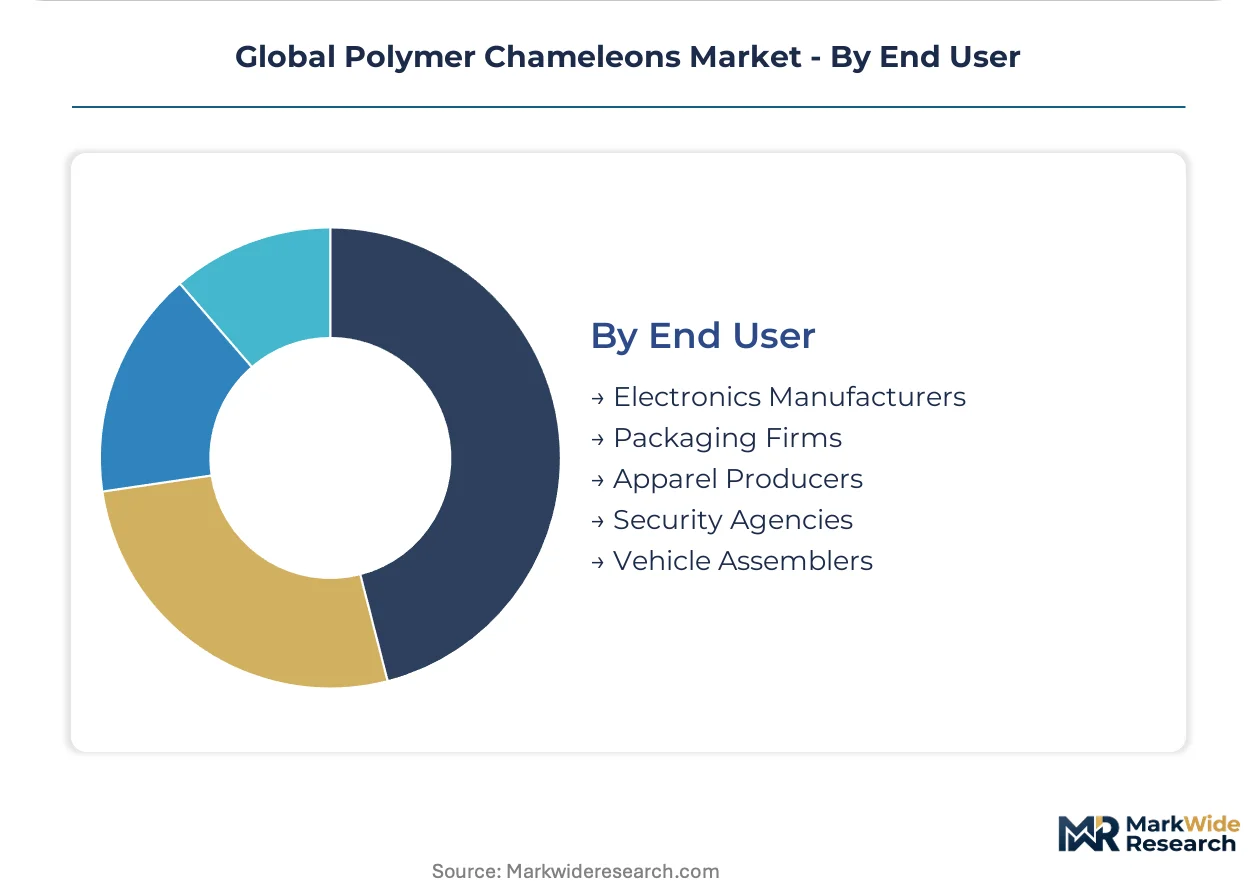
End User:
Electronics manufacturers and vehicle assemblers drive specification intensity, while packaging firms prioritize cost efficiency and regulatory compliance.
- Electronics Manufacturers:Precision substrate requirements from Osaka and Nagoya clusters demand sub-micron coating uniformity for diagnostic device integration.
- Packaging Firms:Extended producer responsibility frameworks in the European Union reward reversible indicator deployment with circular economy credits.
- Apparel Producers:Thermochromic fiber integration requires dye-sublimation compatibility and wash-fastness certification.
- Security Agencies:Document authentication mandates specify irreversible chromogenic transitions with forensic traceability.
- Vehicle Assemblers:German automotive OEMs embed reversible color-change polymers for passive thermal regulation, consolidating procurement through dedicated production line agreements.
Vehicle assemblers anchor premium pricing; electronics manufacturers are gaining share fastest through precision substrate demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka and Nagoya manufacturing clusters anchor precision electronics demand for sensor-integrated polymer substrates. German automotive corridors drive thermochromic glazing procurement for passive thermal management. REACH compliance timelines and FDA food-contact evaluations reshape formulation priorities across key jurisdictions.
United States
Automotive OEMs in Detroit and aerospace manufacturers in Seattle specify electrochromic coatings for thermal regulation systems. FDA evaluates polymer contact-layer safety for food packaging applications, extending certification cycles. DuPont de Nemours anchors North American supply through specialized elastomer compounding operations.
Germany
Tier-one suppliers at Continental and Bosch consolidate procurement through single-source master service agreements with decade-long formulation guarantees. ECHA substance authorization fees for novel chromogenic additives exceed €250,000 per registration. BASF SE leverages its Ludwigshafen research complex to sustain patent density in photochromic thermoplastics.
Japan
Precision electronics manufacturers in the Osaka-Nagoya corridor command placement premiums for sensor-integrated substrates in wearable diagnostic devices. METI standards govern electrochromic device efficiency benchmarks for building automation integration. Evonik Industries AG dominates European electrochromic polymer output with captive silane chemistry partnerships extending into Asian supply chains.
China
Manufacturers in Guangdong and Jiangsu provinces migrate to waterborne UV-curable formulations following MEE volatile organic compound emission ceilings on solvent-based mechanochromic coating lines. GB standards for chromogenic packaging materials diverge from EU REACH disclosure requirements. Small-batch custom coating houses without capital reserves exit the market, concentrating supply among integrated chemical parks.
India
Pharmaceutical cold chain operators underdeploy temperature-indicating polymer labels despite CDSCO mandates for biologics distribution integrity. BIS certification requirements for chromogenic packaging materials lag EU implementation timelines. Domestic compounders invest in twin-screw extrusion capacity to capture freshness-monitoring film demand from Mumbai and Hyderabad pharmaceutical clusters.
Global Polymer Chameleons Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive monomer synthesis and multi-site manufacturing redundancy. Mid-tier compounders face reactor capacity constraints as automotive buyers demand dedicated production lines and long-term formulation locks. Three archetypes dominate: diversified materials giants with patent-heavy R&D complexes, regional specialists with niche chromogenic expertise, and integrated polymer parks with backward control over precursor supply. Competitive moves center on M&A for technology access and capacity expansion in high-compliance jurisdictions.
Among diversified materials conglomerates, BASF SE and Evonik Industries AG exemplify the integrated archetype with Ludwigshafen-based research infrastructure and captive silane chemistry operations. DuPont de Nemours occupies a position representing North American supply anchoring through elastomer compounding specialization. Covestro AG and Merck KGaA sit within the European tier with multi-jurisdiction manufacturing footprints designed to navigate REACH authorization timelines and EFSA opinion synchronization.
| Leading Market Players |
|---|
| BASF SE |
| DuPont de Nemours, Inc. |
| Evonik Industries AG |
| Akzo Nobel N.V. |
| LyondellBasell Industries NV |
| Huntsman Corporation |
| Covestro AG |
| Merck KGaA |
| Autonomic Materials, Inc. |
| Others |
Supply & Pricing Matrix
EU REACH authorization timelines for chromogenic additives gate qualified supply access and premium-tier pricing power, as compounders absorbing €250,000 substance evaluation fees per registration pass compliance costs downstream while excluding uncapitalized competitors from certified formulation tiers.
Pricing Analysis
Outcome-based pricing anchored to thermal regulation performance in automotive glazing applications commands substantial premiums over commodity indicator films. Three-tier pricing structure across certified pharmaceutical-grade, industrial-performance, and economy packaging tiers separates margin pools sharply, with FDA food-contact letters and EFSA opinions as tier demarcators. Cost compression in economy-grade thermochromic microcapsules intensifies because coated titanium dioxide systems displace leuco dye formulations in cost-sensitive freshness monitoring. Packaging firms exhibit highest price sensitivity, while German automotive OEMs tolerate premium positioning for decade-long formulation lock guarantees.
Supply Chain Analysis
Regional distribution centers in Ludwigshafen, Osaka, and Detroit orchestrate hub-and-spoke fulfillment patterns for chromogenic masterbatch and compounded polymer. Manufacturing concentrates in Germany, Japan, and the United States for precision extrusion equipment and regulatory proximity. Raw material flows draw from spiropyran precursor houses, conductive polymer film substrates, and silane coupling agents. Single-source vulnerability in photochromic feedstock creates structural risk as three specialty chemical houses control precursor supply. Distribution runs through dedicated production line agreements with automotive tier-one suppliers rather than spot market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance authorization functions as a cost-of-compliance moat, with ECHA evaluation fees and toxicology dossier requirements filtering out undercapitalized compounders while securing margin durability for incumbent registrants.
For Market Incumbents: Hedge spiropyran feedstock concentration risk through captive precursor synthesis or long-term offtake agreements with the three dominant specialty chemical houses. BASF SE and Evonik Industries AG demonstrate defensive positioning through Ludwigshafen-based patent density and silane chemistry integration. Capacity addition in high-compliance jurisdictions—specifically German automotive corridors and Japan's precision electronics clusters—preserves premium placement against emerging Asian compounders. For New Entrants and Emerging Players: Waterborne UV-curable mechanochromic formulations represent a technology-first wedge into China's decorative polymer supply gap as MEE emission ceilings force solvent-based coating house exits. India's pharmaceutical cold chain offers the most penetrable geography, with CDSCO-mandated biologics distribution integrity creating demand for temperature-indicating labels that domestic compounders underserve. A regulatory-arbitrage go-to-market angle—securing BIS certification ahead of lagging EU timeline synchronization—opens short-run positioning before incumbent multi-jurisdiction footprints consolidate. For Investors and Strategic Acquirers: Automotive OEM issuance of 10-year formulation lock master service agreements is the leading indicator that durable revenue visibility now concentrates among compounders with dedicated production lines and multi-site redundancy. Long-term viability over the medium-term projection horizon favors integrated chemical parks with backward control over monomer synthesis. The acquisition target archetype combines twin-screw extrusion capacity with existing REACH registrations, eliminating registration lag for portfolio expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Captive spiropyran supply secures formulation continuity against single-source vulnerability. |
| Capacity Expansion in High-Compliance Jurisdictions | German and Japanese manufacturing proximity preserves premium automotive and electronics placement. |
| Long-term Supply Agreement with Automotive Tier-Ones | Decade-long formulation locks at Continental and Bosch anchor revenue predictability. |
| Green Manufacturing Transition to Waterborne Formulations | MEE compliance in Guangdong and Jiangsu provinces enables continued China market access. |
| Joint Venture with Regional Distribution Specialists | Hub-and-spoke partnerships in Detroit and Nagoya accelerate aftermarket penetration. |
Research Methodology
Multi-period observation of REACH authorization timelines, automotive procurement contract structures, and MEE emission compliance patterns anchored the trend analysis, supplemented by interviews with polymer R&D directors, automotive tier-one procurement managers, packaging compliance officers, and specialty chemical distribution channel partners. Secondary validation incorporated ECHA substance registration databases, FDA food-contact notification letters, Japanese METI electrochromic efficiency benchmarks, and customs trade flow records for chromogenic additive imports. Bottom-up capacity modeling across twin-screw extrusion lines and top-down demand triangulation from end-use sector consumption produced convergent estimates.
Input-output matrices mapped photochromic, thermochromic, and electrochromic technology flows through thermoplastic, thermoset, elastomer, biopolymer, and composite polymer processing channels across the projection horizon. Segmentation dimensions incorporated activation mechanism, product type, application end-use, and regional regulatory cluster. CAGRs derived from installed capacity expansion schedules, OEM procurement pipeline visibility, and circular economy credit framework adoption curves. Forecast inputs included automotive glazing specification intensity, building-integrated photovoltaic penetration, and pharmaceutical cold chain regulatory mandate enforcement.
Several conditions sit outside the modeled scope, including speculative substitution rates for inorganic pigment systems, synchronization timelines for multi-jurisdiction food-contact approvals, and geopolitical disruption to specialty chemical precursor trade flows. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
Global Low Density Polyethylene (LDPE) Foams Market
Polymers & Resins
Polymer Binders Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
India Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Poly (1-Decene) Market
Polymers & Resins
Semi-Rigid Spray Polyurethane Foam Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Global Cyanate Ester Resins Market
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
Amorphous Polyolefin Market