
 Electromagnetic Shielding Market | 2026-2036
Electromagnetic Shielding Market Size, Share, and Industry Trends Forecast 2026-2036
Electromagnetic Shielding Market Analysis
South Korea's expanding semiconductor packaging capacity is rewriting regional supply dynamics for precision shielding components. Henkel AG & Co. KGaA leverages its adhesive-conductive material portfolio to anchor high-volume electronics assembly lines across Asia-Pacific. Leader Tech Inc specializes in beryllium copper finger stock gaskets, a niche where it competes on thermal cycling reliability rather than price. PPG Industries Inc extends its industrial coatings expertise into spray-applied EMI barriers for aerospace airframes, occupying a margin-rich segment with long qualification cycles.
Electromagnetic shielding encompasses engineered materials and structures that attenuate electromagnetic interference through reflection, absorption, or redirection of radiated energy, typically specified in decibels of attenuation across frequency ranges from kilohertz to gigahertz. Manufacturers achieve protection through conductive fillers dispersed in polymer matrices, woven metal meshes, or solid metal enclosures designed to Faraday-cage specifications for sensitive instrumentation. Metal shielding dominates current procurement volumes in telecommunications infrastructure, where base station housings require rigid barriers against cross-channel interference. Fabric shielding represents the fastest-expanding product category, as wearable medical devices and flexible consumer electronics drive demand for conformable, lightweight EMI solutions. Passive shielding technology retains the largest installed base across military equipment applications, though hybrid architectures combining absorptive and reflective layers are capturing design wins in next-generation radar systems.
The FCC's Part 15 rules on unintentional radiators and the EU's EMC Directive shape product compliance costs, compelling manufacturers to validate shielding effectiveness through accredited test laboratories before market entry. China's GB/T standards for electromagnetic compatibility, administered by SAMR, create additional certification layers for components entering domestic 5G and EV supply chains. Stakeholders must monitor divergence between regional test protocols, as harmonization gaps between FCC, CE, and GB methodologies force redundant engineering cycles and inflate time-to-market for multi-region product families.
Market Dynamics
Automotive electrification is pulling shielding materials into high-voltage architectures faster than suppliers can qualify new chemistries, creating a structural capacity gap between OEM demand and certified material availability.
Growth Catalysts
- Germany's automotive electrification mandates:OEMs in Stuttgart and Munich are specifying nickel-graphite conductive elastomers for 800V battery enclosures, pulling European material capacity toward EV-grade certification.
- FCC Part 15 enforcement tightening:Unintentional radiator rules are forcing consumer electronics manufacturers to redesign housings with integrated shielding, expanding addressable demand for polymer-matrix solutions.
- 5G base station deployment:China's eastern manufacturing corridor is consuming metal shielding for base station housings at volumes that strain copper alloy supply chains.
Market Restraints
- Copper price volatility:Beryllium copper finger stock gaskets face input cost swings that compress margins for precision shielding component specialists.
- South Korean foundry concentration:Semiconductor packaging capacity clustering around Seoul creates single-source risk for wafer-level shielding film supply.
- REACH substance restrictions:Candidate list updates threaten legacy conductive filler chemistries, forcing reformulation cycles that delay qualification timelines.
Strategic Opportunities
- India's PLI scheme for electronics:Manufacturing incentives in Noida and Chennai are attracting shielding component assembly for export-oriented smartphone production.
- Wearable medical devices:Flexible fabric shielding for continuous glucose monitors and cardiac patches represents an underpenetrated application with premium pricing power.
- Hybrid absorptive-reflective architectures:Convergence of ferrite-loaded polymers with metal mesh is enabling next-generation radar cross-section management for defense platforms.
Industry Challenges
- EMC engineer scarcity:Specialized talent for shielding effectiveness testing and compliance documentation commands wage premiums that inflate R&D overhead.
- Multi-region certification redundancy:Divergence between FCC, CE marking, and GB/T test protocols forces parallel validation cycles that extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electromagnetic Shielding Market |
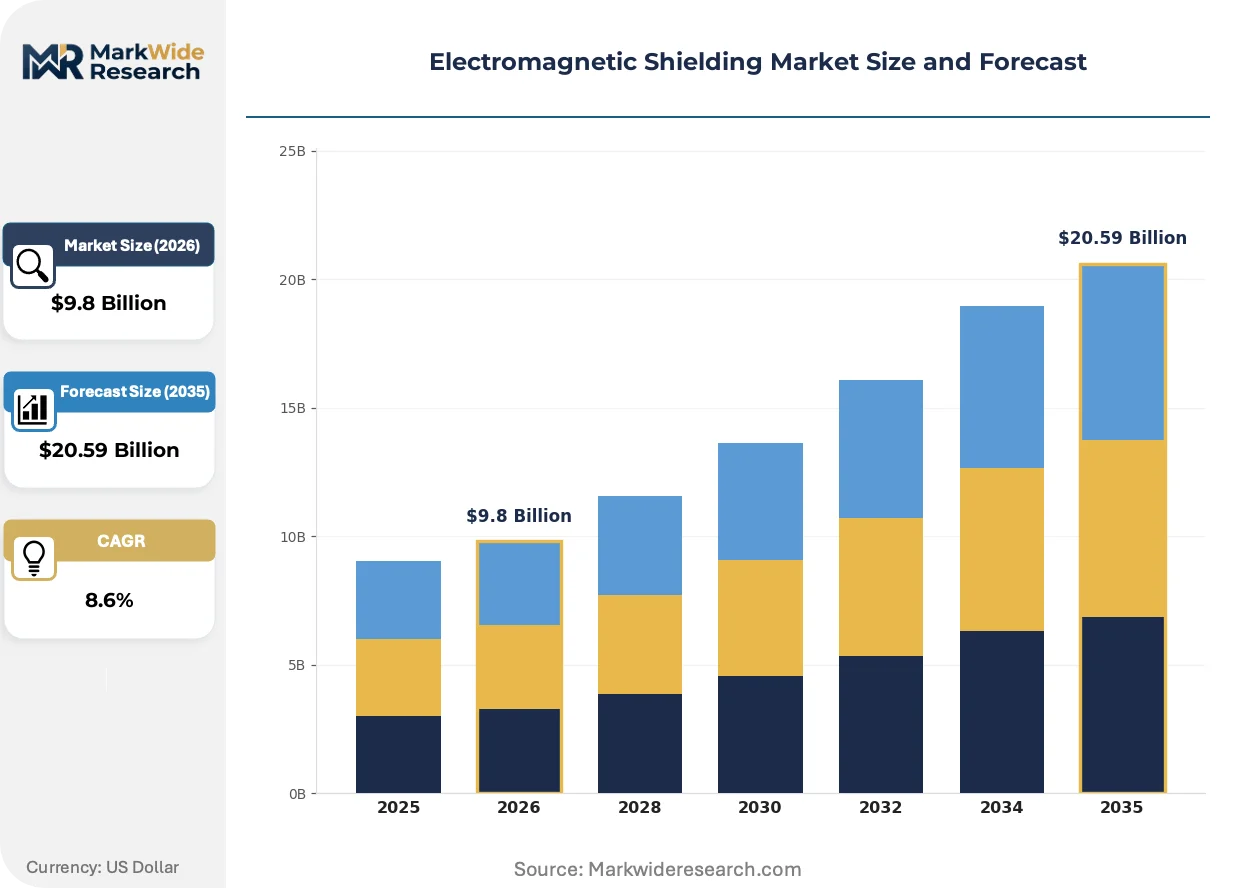
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.59 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Coatings, Metal Shielding, EMI Filters, Fabric Shielding End User: Telecommunications, Automotive, Consumer Electronics, Aerospace Technology: Passive Shielding, Active Shielding, Hybrid Shielding, Frequency Selective Application: Data Processing, Medical Devices, Power Systems, Military Equipment |
| Companies Covered | Henkel AG & Co. KGaA, Leader Tech Inc, Parker Hannifin Corp, TE Connectivity, ETS-Lindgren, PPG Industries Inc, Laird Technologies, Kitagawa Industries, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electromagnetic Shielding Market Emerging Trajectories
Material science breakthroughs are compressing the performance gap between rigid metal enclosures and conformable polymer alternatives, redrawing competitive boundaries across end-use verticals.
Spray-applied EMI barrier coatings are rendering obsolete traditional adhesive-backed shielding tapes in aerospace airframe assembly. Boeing and Airbus tier suppliers in Wichita and Hamburg are qualifying these solutions for lightning strike protection and avionics isolation. The shift is compressing installation labor hours while extending maintenance intervals.
China's GB/T electromagnetic compatibility standards, administered by SAMR, are tightening test protocols for components entering domestic 5G infrastructure. Foreign suppliers must now demonstrate shielding effectiveness across extended frequency ranges before component approval. Domestic EV battery pack manufacturers are responding by specifying fully certified shielding subassemblies rather than raw materials.
Medical device OEMs are consolidating vendor relationships around shielding suppliers with in-house ISO 13485 quality systems and dedicated biocompatibility testing. This preference shift is squeezing undifferentiated commodity producers while rewarding specialists with vertical control over formulation and validation. The pattern is most visible in Minnesota's medical technology cluster and Switzerland's precision device corridor.
Electromagnetic Shielding Market Segmentation
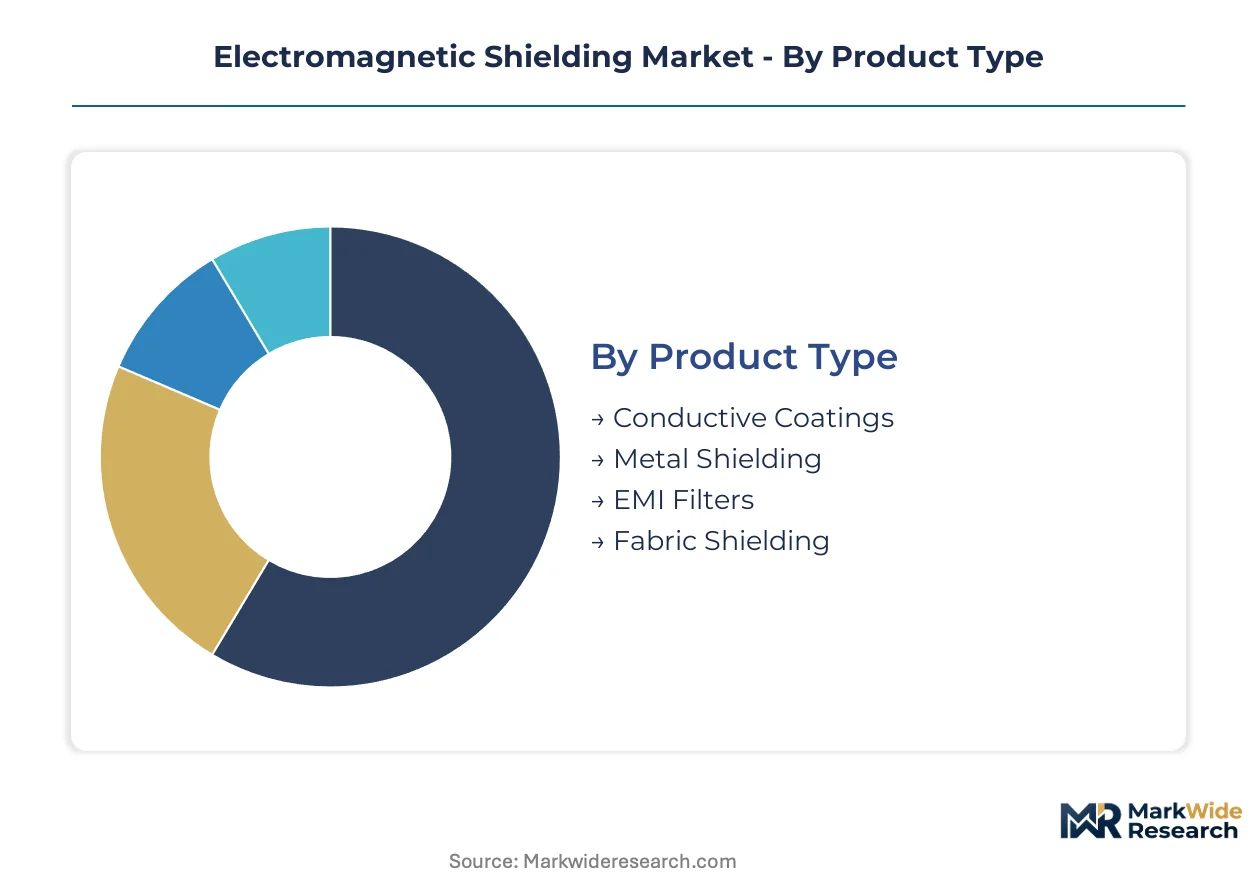
Shielding procurement cycles vary dramatically by segment, with some materials requiring multi-year aerospace qualification while consumer electronics specifications refresh annually. Understanding these velocity differentials helps suppliers calibrate inventory and R&D commitments across their portfolios.
Product Type:
Replacement cycles stretch from weeks for spray-applied coatings to decades for solid metal enclosures, dictating entirely different commercial relationships and margin structures.
- Metal Shielding:Solid aluminum and copper enclosures fabricated to Faraday-cage specifications dominate telecommunications infrastructure. China's eastern manufacturing corridor consumes these rigid barriers for 5G base station housings at volumes that strain copper alloy supply chains.
- Fabric Shielding:Woven conductive textiles and flexible polymer composites enable conformable protection for wearable medical devices. Demand concentrates in Minnesota's medical technology cluster and Switzerland's precision device corridor where ISO 13485-certified suppliers command premium positioning.
- Conductive Coatings:Silver-filled epoxies and nickel-graphite sprays provide thin-film EMI suppression for plastic housings.
- EMI Filters:Pi-circuit and feedthrough configurations suppress conducted interference on power and signal lines.
Metal Shielding anchors the volume base while Fabric Shielding gains share at the steepest rate.
End User:
Margin profiles diverge sharply between price-sensitive consumer electronics and qualification-intensive aerospace, with automotive electrification creating a new middle tier of volume-plus-technical-demands.
- Automotive:800V battery architectures and inverter housings specify nickel-graphite conductive elastomers and precision-formed metal barriers. OEMs in Stuttgart and Munich are pulling European material capacity toward EV-grade certification faster than suppliers can qualify new chemistries.
- Telecommunications:Base station manufacturers require rigid shielding against cross-channel interference in high-density deployments. China's GB/T electromagnetic compatibility standards, administered by SAMR, are tightening test protocols for components entering domestic 5G infrastructure.
- Consumer Electronics:FCC Part 15 enforcement on unintentional radiators forces housing redesigns with integrated polymer-matrix shielding.
- Aerospace:Boeing and Airbus tier suppliers in Wichita and Hamburg qualify spray-applied EMI barriers for lightning strike protection and avionics isolation.
Telecommunications commands the largest installed base while Automotive expands most quickly as electrification mandates multiply.
Technology:
Engineering complexity escalates from single-mechanism approaches to architectures combining multiple attenuation principles, with hybrid systems capturing defense procurement preference.
- Passive Shielding:Reflective metal barriers and absorptive ferrite-loaded polymers operate without external power. This technology retains the largest installed base across military equipment applications where simplicity enhances field reliability.
- Hybrid Shielding:Converged architectures combining absorptive and reflective layers enable next-generation radar cross-section management. Defense platforms in multiple geographies are specifying these solutions for signature control in contested electromagnetic environments.
- Active Shielding:Powered cancellation systems generate opposing fields to nullify interference at specific frequencies.
- Frequency Selective:Patterned apertures and metamaterial structures transmit desired signals while blocking others.
Passive Shielding dominates current procurement volumes while Hybrid Shielding climbs fastest in defense design wins.
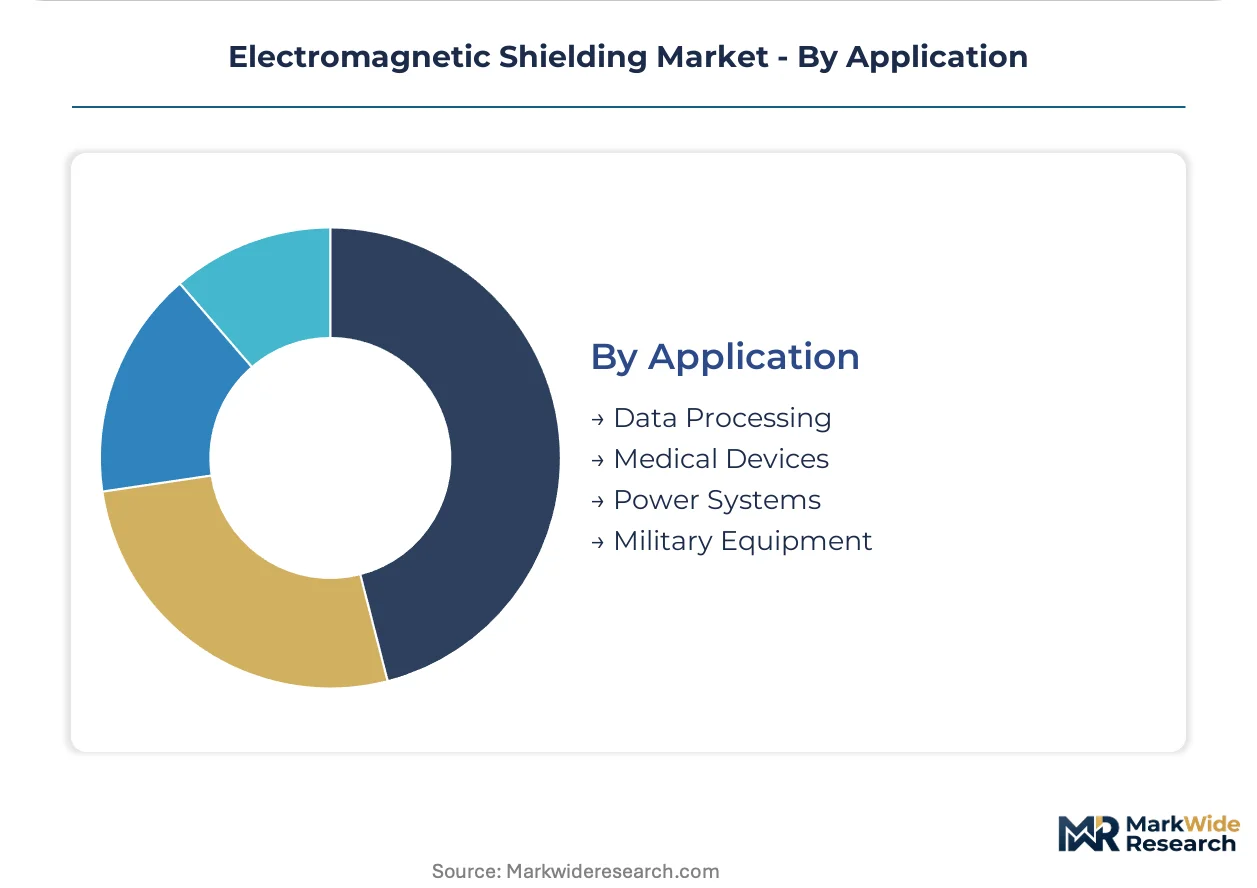
Application:
Regulatory burden intensifies from industrial power systems to implantable medical devices, with certification requirements filtering supplier participation by vertical.
- Medical Devices:Continuous glucose monitors and cardiac patches require flexible, biocompatible shielding that withstands body-fluid exposure. OEMs are consolidating vendor relationships around suppliers with in-house ISO 13485 quality systems and dedicated biocompatibility testing capabilities.
- Military Equipment:Harsh-environment specifications demand shielding effectiveness across extended temperature and humidity ranges. Multi-region defense procurement mandates redundant validation cycles against divergent test protocols.
- Data Processing:Server farms and edge computing nodes require cost-optimized shielding at massive scale.
- Power Systems:Grid infrastructure and renewable energy converters need high-current EMI suppression.
Data Processing generates the highest unit volumes while Medical Devices offers the steepest pricing power premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper alloy supply chains concentrate in China's eastern manufacturing corridor, where 5G base station deployment and domestic EV production are creating dual sourcing pressure for conductive coatings and metal shielding solutions.
China
5G infrastructure rollout and electric vehicle battery manufacturing dominate shielding material demand in Jiangsu and Guangdong provinces. SAMR-administered GB/T electromagnetic compatibility standards tighten test protocols for components entering domestic supply chains. Shanghai and Shenzhen-based OEMs now specify fully certified shielding subassemblies rather than raw materials to accelerate regulatory approval.
Germany
Automotive electrification mandates in Stuttgart and Munich are pulling nickel-graphite conductive elastomers into 800V battery enclosures and inverter housings. REACH candidate list updates threaten legacy conductive filler chemistries, forcing reformulation cycles that delay qualification timelines. Bavarian material suppliers are redirecting capacity toward EV-grade certification faster than new chemistries can complete validation.
United States
FCC Part 15 enforcement on unintentional radiators compels consumer electronics manufacturers to redesign housings with integrated polymer-matrix shielding. Wichita-based Boeing tier suppliers qualify spray-applied EMI barriers for lightning strike protection and avionics isolation. Minnesota's medical technology cluster consolidates vendor relationships around ISO 13485-certified shielding suppliers with dedicated biocompatibility testing.
Japan
Semiconductor packaging capacity expansion around Tokyo and Osaka rewrites regional supply dynamics for precision shielding components. METI industrial policy supports advanced material development for next-generation electronics. Kitagawa Industries anchors domestic supply of precision-formed shielding solutions for automotive and telecommunications applications.
South Korea
Foundry concentration around Seoul creates single-source risk for wafer-level shielding film supply in semiconductor packaging. Domestic battery manufacturers for Hyundai and Kia specify conductive elastomers for high-voltage architectures. Busan-Ulsan industrial corridor houses specialty metal fabricators serving export-oriented electronics assembly.
Electromagnetic Shielding Market Vendor Landscape
Specialized material formulators and diversified industrial conglomerates split the market along application complexity lines. The vendor base organizes into three tiers: adhesive-conductive specialists, precision metal fabricators, and spray-applied coating providers. Consolidation pressure concentrates in the middle tier, where scale advantages in raw material procurement determine margin survival. Dominant competitive moves include backward integration into conductive filler production and captive supply of certified polymer matrices.
Within the diversified industrial tier, Henkel AG & Co. KGaA and PPG Industries Inc exemplify scale-driven players leveraging coatings expertise across multiple end-use verticals. Leader Tech Inc occupies a position among precision metal specialists focused on thermal cycling reliability rather than price competition. These three anchors illustrate how competitive positioning diverges between volume-optimized formulation houses and niche component fabricators serving qualification-intensive applications.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Leader Tech Inc |
| Parker Hannifin Corp |
| TE Connectivity |
| ETS-Lindgren |
| PPG Industries Inc |
| Laird Technologies |
| Kitagawa Industries |
| 3M |
| Others |
Supply Flow & Price Mechanics
Copper price volatility in beryllium copper finger stock gaskets compresses margins for precision shielding component specialists while simultaneously widening spreads between aerospace-grade certified materials and commodity conductive fillers, forcing tiered procurement strategies that concentrate volume buyers on Asian polymer-matrix suppliers and reserve European metal fabricators for qualification-intensive applications.
Pricing Analysis
FCC Part 15 and CE marking requirements dictate the pricing tier structure across electromagnetic shielding materials, separating ISO 13485-certified medical-grade solutions from standard consumer electronics grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with aerospace lightning-strike barriers commanding substantial premiums over telecommunications base station housings. Cost compression in nickel-graphite conductive elastomers is intensifying because automotive OEMs in Stuttgart and Munich are pulling European material capacity toward EV-grade certification faster than suppliers can qualify new chemistries. Consumer electronics manufacturers exhibit the highest price sensitivity due to annual specification refreshes, while medical device OEMs in Minnesota's technology cluster demonstrate the lowest sensitivity given biocompatibility testing requirements and vendor consolidation preferences.
Supply Chain Analysis
Beryllium copper feedstock and silver-filled epoxy resins anchor upstream material flows for electromagnetic shielding production. China's eastern manufacturing corridor, South Korea's Seoul metropolitan foundry cluster, and Germany's Bavarian chemical belt concentrate supply for metal shielding enclosures, wafer-level shielding films, and conductive elastomer formulations respectively. Raw material dependencies rest on Chilean copper concentrates, Japanese precision metal foils, and German specialty polymer additives. Single-source vulnerability concentrates around Seoul's semiconductor packaging capacity for precision shielding components. Distribution runs through Tier 1 automotive suppliers in Stuttgart, telecommunications infrastructure integrators in Shenzhen, and aerospace tier suppliers in Wichita and Hamburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification mandates across multiple geographies fragment the electromagnetic shielding market into application-specific niches, creating entry points for specialists who can navigate divergent regional certification protocols faster than diversified incumbents.
For Market Incumbents: Build certification moats by securing parallel FCC, CE marking, and GB/T validations for shielding subassemblies before competitors complete redundant engineering cycles. Capture backward integration into conductive filler production to defend margin position against REACH substance restrictions threatening legacy chemistries. Add dedicated capacity in Noida and Chennai to serve India's PLI scheme for export-oriented electronics assembly. For New Entrants and Emerging Players: Pursue wearable medical device applications in Minnesota's technology cluster and Switzerland's precision device corridor, where ISO 13485 quality systems and biocompatibility testing capabilities filter out undifferentiated commodity producers. Target flexible fabric shielding for continuous glucose monitors and cardiac patches, the fastest-expanding product category with premium pricing power. Establish go-to-market partnerships with medical device OEMs consolidating vendor relationships around vertically integrated formulation-and-validation specialists. For Investors and Strategic Acquirers: REACH candidate list updates reshaping the acquisition landscape favor targets with in-house reformulation capabilities and accelerated qualification timelines for EV-grade conductive elastomers. Mid-cap specialists with captive polymer matrix production and established aerospace qualification cycles present the strongest long-term viability profile. Monitor divergence between FCC, CE, and GB/T test protocols as the signal indicating which shielding suppliers will capture multi-region product family contracts versus those trapped in single-market dependency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Filler Production | Henkel and PPG anchor margin control by capturing upstream nickel-graphite and silver-epoxy supply. |
| Multi-Region Certification Parallelization | Simultaneous FCC, CE, and SAMR validation compresses time-to-market for 5G base station shielding suppliers. |
| ISO 13485 Quality System Investment | Medical device OEMs in Minnesota consolidate procurement around shielding suppliers with dedicated biocompatibility testing. |
| Hybrid Shielding Architecture Development | Convergence of ferrite-loaded polymers with metal mesh captures defense procurement preference for radar signature control. |
| Spray-Applied EMI Barrier Qualification | Boeing and Airbus tier suppliers in Wichita and Hamburg adopt PPG's aerospace coatings for lightning strike protection. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, SAMR GB/T certification databases, aerospace supplier qualification records, and trade flow data from China's eastern manufacturing corridor. EMC engineers at telecommunications infrastructure deployers, procurement leads at Stuttgart automotive OEMs, shielding effectiveness test laboratory directors, and conductive materials R&D heads provided structured input. Bottom-up demand modeling across automotive 800V architectures, 5G base station deployments, and medical wearable devices triangulates against top-down market sizing from polymer-matrix and metal enclosure production volumes.
Forecast inputs include shielding effectiveness specifications across kilohertz to gigahertz frequency ranges, qualification cycle durations by application vertical, and regional regulatory divergence indices. Segmentation dimensions span product type, end user industry, technology mechanism, and application requirements across the analysis window. CAGRs derive from installed base erosion rates for passive shielding versus adoption curves for hybrid absorptive-reflective architectures. Copper alloy supply constraints, REACH substance restriction timelines, and semiconductor packaging capacity expansion in South Korea inform industry-specific trajectory adjustments.
Sensitivities concentrate around copper price volatility, harmonization gaps between FCC and GB/T test protocols, and REACH candidate list expansion affecting legacy conductive filler chemistries. Cross-checking against aerospace supplier qualification databases and SAMR component approval registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Lab-Grown Rough Diamond Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Transparent Wood Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Superconducting Materials Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
APAC Advanced Building Materials Market
Advanced Materials
North America Advanced Phase Change Materials Market
Advanced Materials
US Graphene Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
Synthetic Graphite Market
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
Global Thermal Interface Materials Market
Advanced Materials
Global Advanced Materials Market
Advanced Materials
Cathode Materials Market