
 Tank Car Market | 2026-2036
Tank Car Market Size, Share, and Industry Trends Forecast 2026-2036
Tank Car Market Analysis
The PHMSA Hazardous Materials Regulations is realigning capital deployment across the North American tank car supply base. Trinity Industries leverages backward integration into railcar leasing to sustain recurring revenue streams. Union Tank Car dominates specialized pressure vessel fabrication with proprietary weld inspection protocols. Greenbrier Companies anchors its position through high-volume stainless steel tank car production for chemical shippers.
A tank car is a cylindrical rail vehicle engineered to transport liquids, gases, and pressurized commodities, typically constructed with carbon steel or stainless steel shells ranging from 7/16-inch to 1-inch thickness and equipped with pressure relief devices, thermal protection, and head shields. Chemical tank cars command the largest installed base due to diversified hazardous cargo flows, while pressure tank cars represent the fastest-expanding category as liquefied natural gas and industrial gas volumes climb. Stainless steel material grades capture premium margin pools owing to corrosion resistance mandates for food-grade and aggressive chemical service.
The US DOT Pipeline and Hazardous Materials Safety Administration enforces construction standards through 49 CFR Part 179, while Transport Canada's Transport of Dangerous Goods Regulations imposes parallel certification requirements for cross-border movements. The Association of American Railroads Tank Car Committee further shapes design approvals through its construction and interchange rules. Stakeholders must monitor regulatory harmonization pressures between US and Canadian regimes as retrofit deadlines for legacy DOT-111 fleets approach.
Market Dynamics
The US DOT's retrofit mandate for DOT-111 tank cars is compressing fleet replacement timelines and redistributing manufacturing capacity toward thicker-shell constructions. Chemical shippers are accelerating dedicated fleet commitments to lock in transport capacity ahead of regulatory deadlines.
Growth Catalysts
- PHMSA Safety Mandates:Enhanced 49 CFR Part 179 standards for head shields and thermal protection are forcing premature retirement of legacy rolling stock, generating replacement demand across North American chemical corridors.
- Permian Basin NGL Expansion:Fractionation capacity additions in West Texas and New Mexico are pulling specialized pressure vessel orders for liquefied petroleum gas service.
- Stainless Steel Corrosion Resistance:Food-grade and aggressive chemical shippers specify 316L and duplex grades to extend service intervals and reduce inspection frequency.
Market Restraints
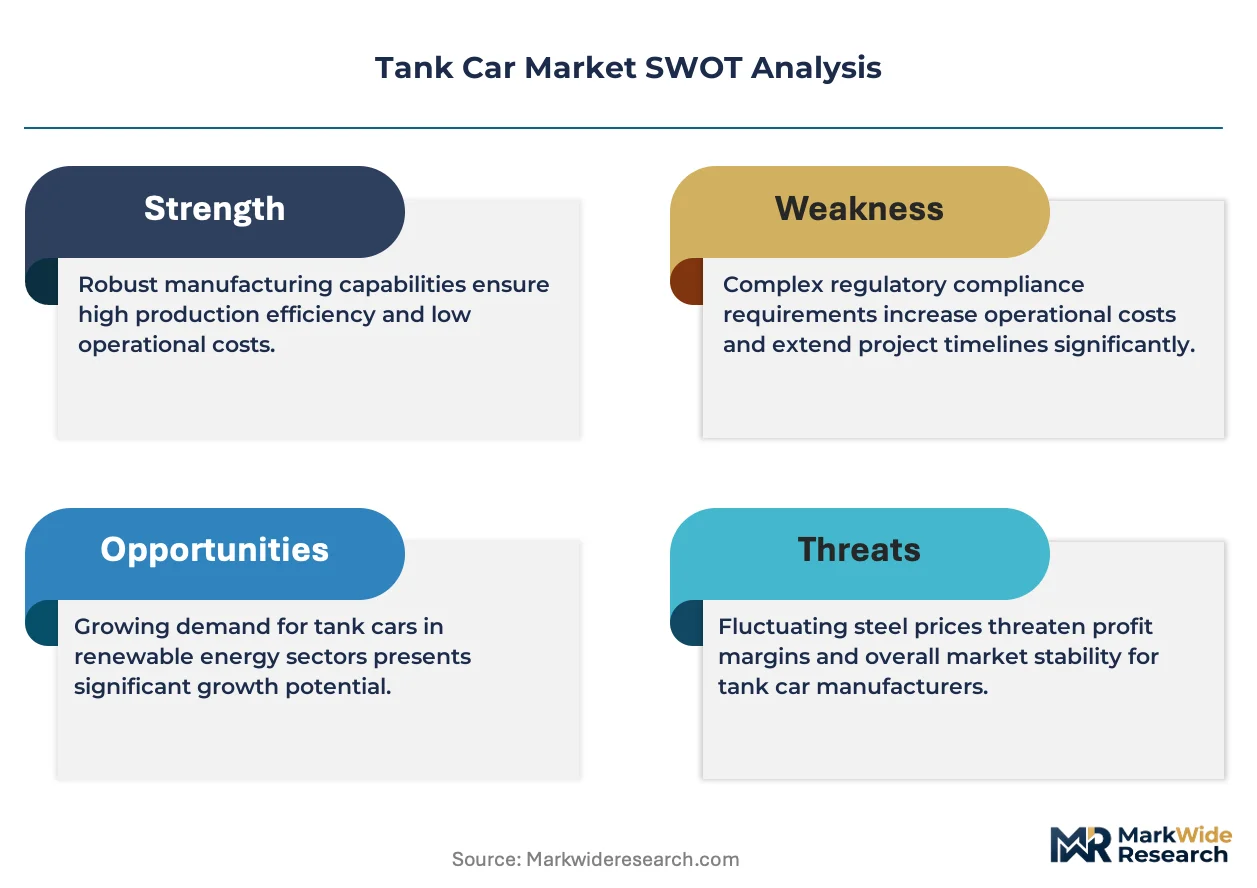
- Specialized Steel Input Volatility:Nickel and molybdenum price swings directly compress margin pools on stainless tank car contracts, forcing fixed-price risk onto fabricators.
- Fabrication Concentration:Pressure vessel welding capacity clusters in the US Gulf Coast and Ontario, creating bottlenecks during fleet replacement surges.
- Cross-Border Regulatory Friction:Divergent Transport Canada and US DOT certification timelines delay interchange eligibility for new-build cars.
Strategic Opportunities
- Alberta Oil Sands Diluent Service:Underpenetrated demand for specialized coil-heated tank cars exists in Cold Lake and Athabasca production zones.
- Carbon Capture Transport:Supercritical CO2 pipeline bridging projects in Louisiana and Texas require mobile storage solutions during infrastructure gaps.
- Leasing-Plus-Maintenance Convergence:Integrated service contracts bundling railcar provision with certified inspection and repair are displacing pure operating leases.
Industry Challenges
- Certified Welder Scarcity:ASME Section IX-qualified pressure vessel welders command premium wages, constraining throughput at fabrication yards.
- Retrofit Coordination Complexity:Synchronizing shop time with active fleet utilization requires advance scheduling with chemical shippers operating on tight turnarounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tank Car Market |
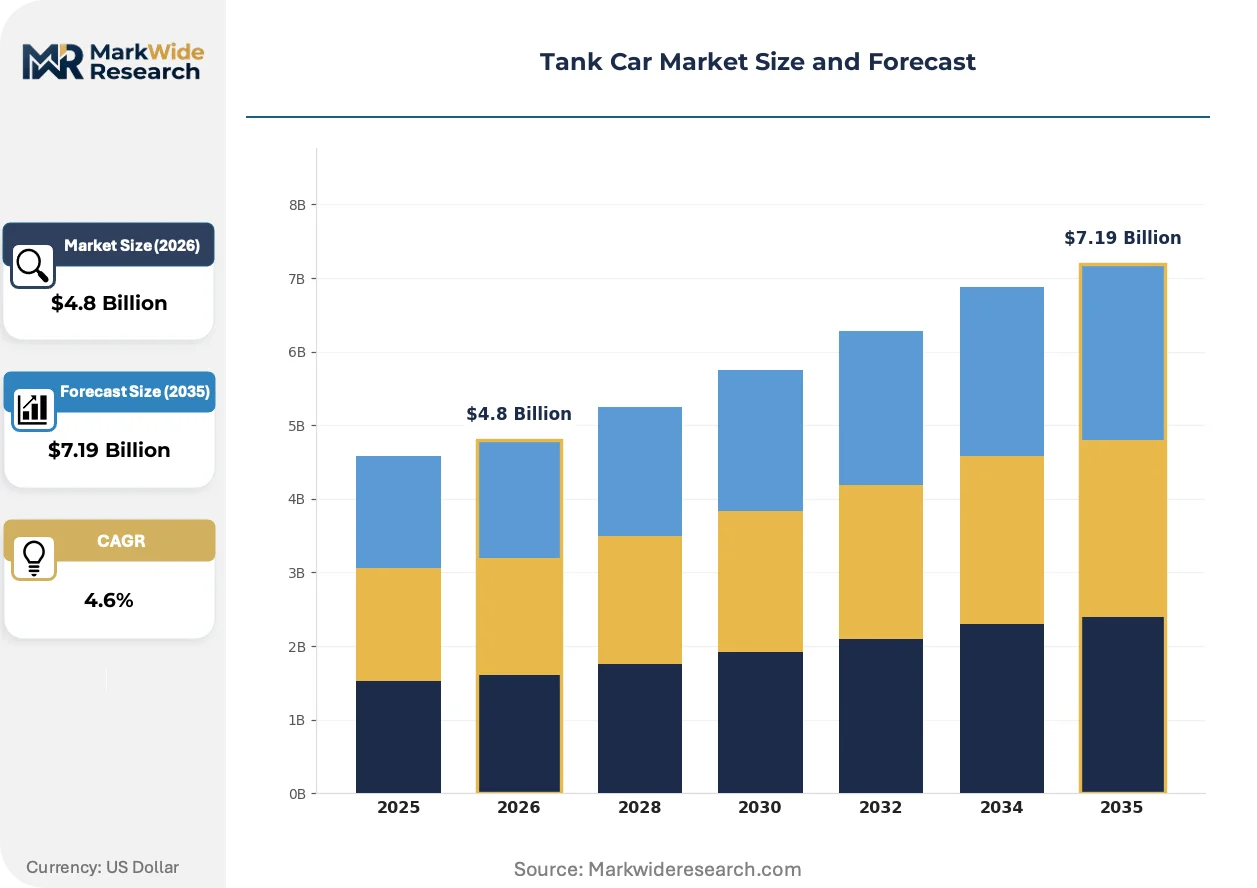
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Car Type: Chemical Tank Cars, Crude Oil Tank Cars, Food Grade Tank Cars, Pressure Tank Cars Material: Steel, Stainless Steel, Aluminum, Composite End User: Refineries, Chemical Manufacturers, Food Processing Industries, Logistics Providers Capacity: 20000 gallons, 30000 gallons, 40000 gallons, 50000 gallons |
| Companies Covered | American Railcar Industries, Union Tank Car, Trinity Industries, Evonik Industries, Procor, GATX Corporation, National Steel Car, CLNX Holdings, Greenbrier Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tank Car Market Emerging Trajectories
Digital inspection protocols and advanced material specifications are compressing maintenance cycles and extending service life. Regulatory pressure on legacy fleet safety is accelerating capital deployment toward next-generation designs.
Electron beam welding is consolidating fabrication quality control in pressure tank car production. Specialty gas and cryogenic liquid shippers specify full-penetration single-pass welds to eliminate inspection rework. The technology is consolidating supplier tiers by disqualifying yards lacking vacuum chamber capacity.
Transport Canada's updated Transport of Dangerous Goods Regulations impose parallel thermal protection standards to US DOT mandates. Cross-border operators must certify to both regimes, doubling compliance documentation. Pressure car builders in Ontario and Quebec are front-loading dual-certification engineering to capture US Gulf Coast orders.
Fleet operators are unbundling maintenance from pure lease agreements and contracting directly with certified repair shops. Chemical shippers in the Houston Ship Channel and Baton Rouge corridor prefer control over inspection timing to minimize cargo scheduling conflicts. The shift is most visible among large-volume sulfuric acid and caustic soda handlers seeking ISO 9001-traceable repair records.
Tank Car Market Segmentation
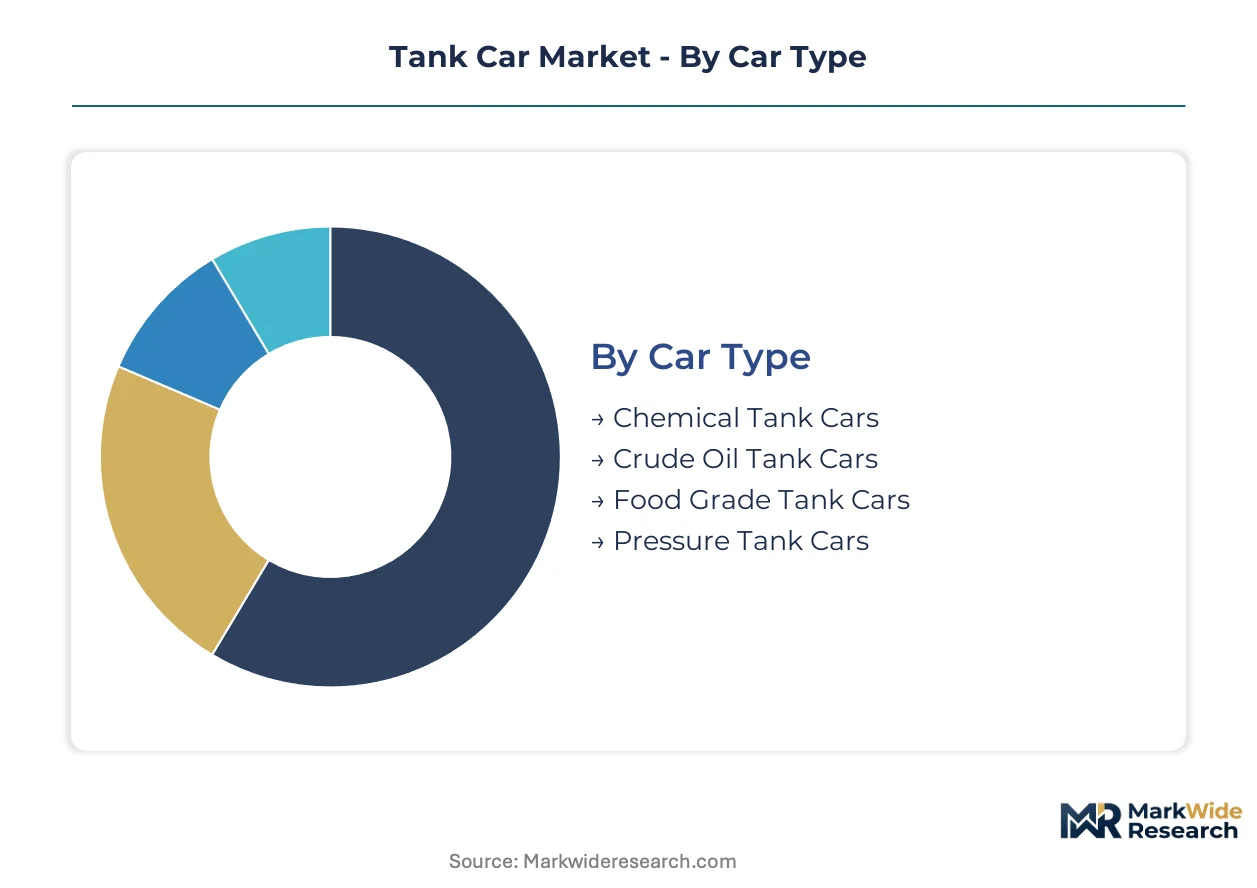
Tank car procurement hinges on matching shell specifications to cargo chemistry, pressure requirements, and regulatory classifications. Shippers optimize fleet economics by balancing acquisition cost against corrosion tolerance, inspection intervals, and residual resale value.
Car Type:
Customization intensity varies sharply across this category, from standardized crude oil designs to highly engineered pressure vessels requiring ASME certification.
- Chemical Tank Cars:These carbon steel or stainless steel shells transport acids, caustics, and solvents in non-pressurized service. Demand concentrates along the US Gulf Coast petrochemical corridor as Dow Chemical and BASF expand dedicated fleets to secure transport capacity under tightening PHMSA safety mandates.
- Pressure Tank Cars:ASME-coded cylindrical vessels handle liquefied petroleum gas, anhydrous ammonia, and industrial gases at pressures exceeding 100 psi. Permian Basin NGL fractionation capacity additions are pulling specialized orders for 33,000-gallon pressure designs with enhanced thermal protection.
- Crude Oil Tank Cars:DOT-117 specification cars dominate Bakken and Permian crude movements with thicker 9/16-inch shells and full-height head shields.
- Food Grade Tank Cars:316L stainless steel construction with sanitary fittings serves edible oils, sweeteners, and liquid food additives under FDA and USDA inspection protocols.
Leading the category by volume: Chemical Tank Cars. Growing fastest: Pressure Tank Cars.
Material:
Cost tier structures procurement decisions, with base carbon steel anchoring fleet economics and specialty alloys commanding premium positioning.
- Stainless Steel:304 and 316L grades deliver corrosion resistance for aggressive chemicals and food-grade service. Nickel and molybdenum input volatility compresses fabricator margins on fixed-price contracts, forcing risk-sharing clauses into long-term supply agreements.
- Steel:Carbon steel shells dominate crude oil and basic chemical service with 7/16-inch to 9/16-inch thickness specifications. DOT-111 retrofit deadlines are accelerating replacement demand for thicker DOT-117 carbon steel constructions.
- Aluminum:Lightweight alloys reduce tare weight for high-value chemical movements where payload optimization offsets higher acquisition cost.
- Composite:Fiberglass-reinforced and polymer-lined designs serve niche corrosive chemical applications requiring extreme pH tolerance.
Stainless steel captures the highest margin pool. Carbon steel moves the greatest unit volume.
End User:
Customer type determines lease-versus-buy calculus and maintenance integration preferences.
- Chemical Manufacturers:Dow, BASF, and LyondellBasell operate captive fleets exceeding 10,000 cars with integrated maintenance contracts. These shippers prioritize stainless steel specifications to extend inspection intervals and minimize cargo contamination risk.
- Refineries:Integrated oil companies deploy crude oil tank cars for gathering and midstream movements from Permian and Bakken production zones.
- Logistics Providers:Trinity Industries and GATX lease fleets to smaller shippers lacking capital for dedicated rolling stock.
- Food Processing Industries:Cargill and ADM specify 316L sanitary designs with CIP (clean-in-place) compatibility for edible oil and liquid sweetener transport.
Chemical manufacturers deploy the largest owned fleets. Logistics providers are expanding fastest as leasing penetration rises.
Capacity:
Volume segmentation tracks weight restrictions and loading infrastructure constraints across the North American rail network.
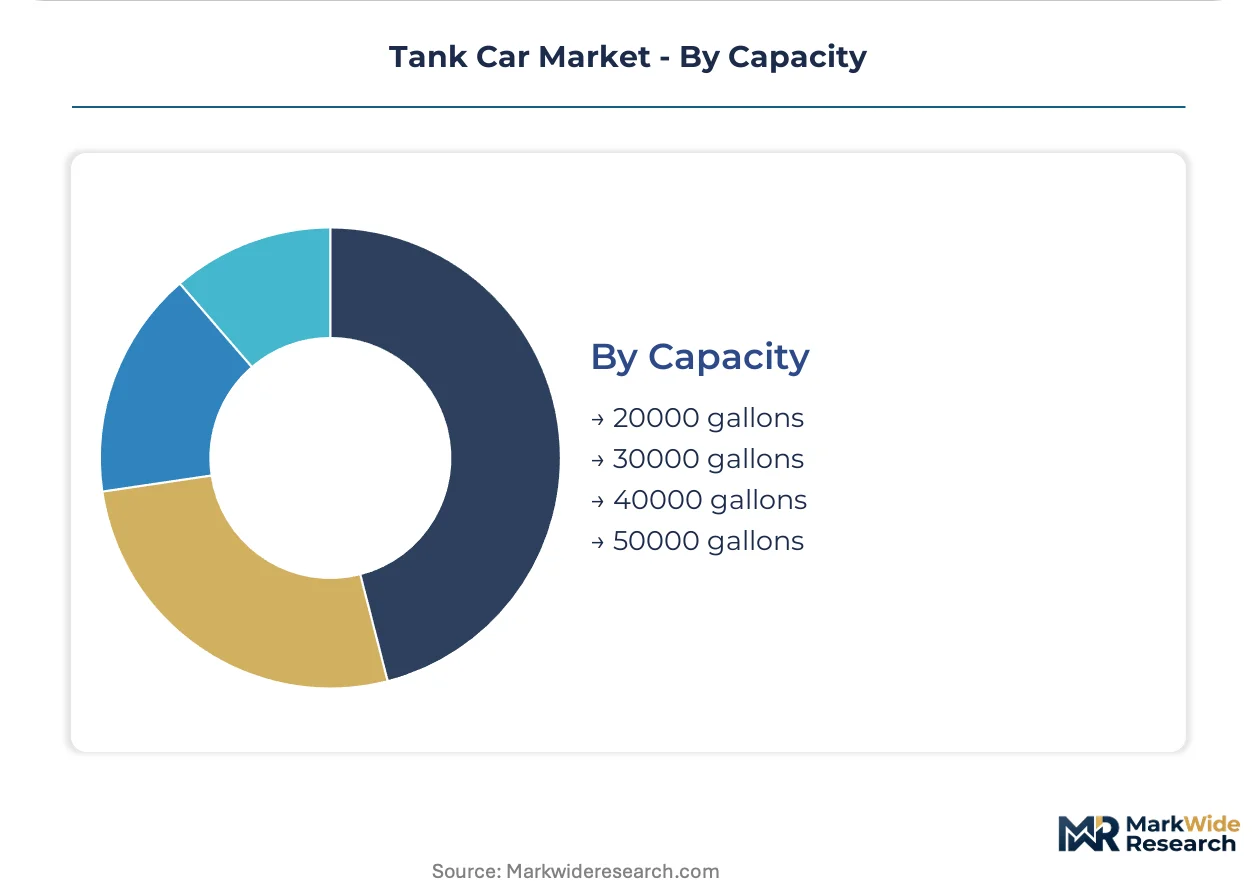
- 30000 gallons:This intermediate specification balances payload optimization with axle load limits on Class I railroads. Chemical shippers in the Houston Ship Channel and Baton Rouge corridor prefer this capacity for sulfuric acid and caustic soda movements.
- 20000 gallons:Smaller cars serve high-density chemicals and restricted-clearance routes with 263,000-pound gross rail load compliance.
- 40000 gallons:Extended tank designs maximize ethanol and crude oil movements on heavy-haul routes.
- 50000 gallons:Maximum-capacity cars concentrate in unit train crude oil service and select low-density chemical applications.
Thirty-thousand-gallon designs dominate chemical service. Forty-thousand-gallon configurations are climbing fastest in crude oil unit train deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor functions as the dominant demand concentration zone, with tax-advantaged infrastructure zones pulling fleet investment toward Texas and Louisiana chemical clusters.
United States
PHMSA's enhanced 49 CFR Part 179 standards are compressing replacement timelines for legacy DOT-111 fleets. The Permian Basin NGL fractionation expansion is pulling specialized pressure vessel orders toward West Texas fabrication yards. Houston Ship Channel chemical shippers are accelerating dedicated fleet commitments to secure transport capacity ahead of regulatory deadlines.
Canada
Transport Canada's updated Transport of Dangerous Goods Regulations impose thermal protection standards matching US DOT mandates. Alberta oil sands diluent service is generating underpenetrated demand for specialized coil-heated tank cars in Cold Lake production zones. Ontario and Quebec pressure car builders are front-loading dual-certification engineering to capture cross-border interchange eligibility.
Mexico
Pemex refining capacity expansions in Tula and Salamanca are pulling chemical tank car orders for sulfuric acid and caustic soda movements. The Secretariat of Communications and Transportation coordinates rail safety standards with US and Canadian regulators. Monterrey industrial corridor is emerging as a maintenance hub for cross-border fleet operators seeking certified repair capacity.
Germany
BASF and Evonik operate captive chemical fleets exceeding European averages for stainless steel specifications. The Federal Railway Authority enforces tank car construction standards through EBA guidelines harmonized with RID regulations. Ludwigshafen chemical cluster demands corrosion-resistant 316L grades to extend inspection intervals for aggressive cargo service.
China
NMPA and MIIT are tightening pressure vessel certification standards for liquefied natural gas transport. Yangtze River Delta petrochemical complexes in Ningbo and Shanghai are expanding dedicated fleet orders to secure rail logistics capacity. Shandong Province fabrication yards are scaling electron beam welding capacity for specialty gas and cryogenic liquid shippers.
Tank Car Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The supplier base clusters around three strategic archetypes: integrated railcar-leasing operators, captive fabrication subsidiaries of chemical majors, and independent pressure vessel specialists. Dominant competitive moves include backward integration into railcar leasing to capture recurring revenue, and capacity expansion in electron beam welding to qualify for specialty gas contracts.
Among North American fabricators, Trinity Industries, Union Tank Car, and Greenbrier Companies exemplify distinct positioning strategies. Trinity Industries represents the diversified conglomerate archetype with integrated leasing operations. Union Tank Car occupies the specialist tier with proprietary pressure vessel fabrication protocols. Greenbrier Companies anchors high-volume stainless steel production for chemical shippers seeking standardized fleet economics.
| Leading Market Players |
|---|
| American Railcar Industries |
| Union Tank Car |
| Trinity Industries |
| Evonik Industries |
| Procor |
| GATX Corporation |
| National Steel Car |
| CLNX Holdings |
| Greenbrier Companies |
| Others |
Supply Flow & Price Mechanics
PHMSA thermal protection mandates gate qualified supply and premium-tier pricing access for fabricators capable of dual-certification engineering. Buyers without pre-qualified supplier relationships face extended lead times and cost premiums as retrofit deadlines compress available shop capacity across North American fabrication yards.
Pricing Analysis
Short lead-time premiums of 15-25% apply to spot orders from chemical shippers facing unplanned fleet replacement, while contracted volume commitments secure standard-tier pricing with fixed escalation clauses. Three-tier pricing structure across premium, standard, and economy levels separates ASME-coded pressure vessels from DOT-117 carbon steel constructions and basic non-pressurized chemical service cars. Pricing pressure stems from nickel and molybdenum volatility on stainless steel contracts, forcing fabricators to absorb margin compression or renegotiate fixed-price agreements. Small-volume chemical shippers exhibit highest price sensitivity due to limited fleet scale, while integrated majors like Dow Chemical leverage volume commitments for preferential terms.
Supply Chain Analysis
Dual-sourcing requirements from Class I railroads and large chemical shippers mandate multi-supplier qualification, preventing single-fabricator dependence for critical fleet replacements. Manufacturing concentrates in the United States, Canada, and China, with US Gulf Coast and Ontario yards dominating pressure vessel welding capacity. Raw material dependencies center on specialty steel plate, nickel alloys, and ASME-certified pressure relief devices. Single-source vulnerability exists in electron beam welding equipment, where vacuum chamber capacity limits qualify only select fabrication yards. Distribution runs through integrated leasing operators, direct manufacturer sales to captive fleets, and third-party railcar lessors serving fragmented chemical shipper demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tank car market sits in a technology-transition phase as electron beam welding displaces conventional multi-pass fabrication for pressure vessel construction. Legacy fleet retirement timelines compress the window for competitive repositioning around next-generation manufacturing capabilities.
For Market Incumbents: Acquire electron beam welding capacity and vacuum chamber infrastructure to qualify for specialty gas and cryogenic liquid contracts that disqualify conventional fabrication yards. Expand backward integration into certified repair networks to capture maintenance revenue streams unbundling from pure lease agreements. Defend against emerging Chinese fabricators scaling Shandong Province capacity by front-loading dual US-Canada certification engineering.
For New Entrants and Emerging Players: Technology-first electron beam welding specialization offers entry into premium pressure vessel segments where incumbent capacity constraints create supply gaps. Target Alberta oil sands diluent service for coil-heated tank cars, an underpenetrated segment lacking dedicated fabrication capacity. Pursue carbon capture transport mobility solutions in Louisiana and Texas as supercritical CO2 infrastructure gaps create interim storage demand.
For Investors and Strategic Acquirers: Transport Canada-US DOT regulatory harmonization announcements are the leading indicator that cross-border certification capabilities will command acquisition premiums. Five-to-ten-year viability favors fabricators with dual-certification engineering and integrated leasing operations over pure manufacturing plays. Monitor ASME Section IX welder wage inflation as signal of throughput constraints at qualified yards.
| Strategic Initiative | Industry Significance |
|---|---|
| Electron Beam Welding Capacity Expansion | Qualifies fabricators for specialty gas contracts requiring single-pass full-penetration welds. |
| Dual-Certification Engineering Investment | Captures cross-border interchange eligibility as US-Canada regulatory timelines converge. |
| Integrated Leasing-Plus-Maintenance Contracts | Bundles railcar provision with certified inspection to displace pure operating leases. |
| Stainless Steel Grade Specialization | Extends service intervals for aggressive chemical shippers under FDA and USDA protocols. |
| Alberta Oil Sands Diluent Service Entry | Addresses underpenetrated demand for coil-heated designs in Cold Lake production zones. |
Methodological Framework
Multi-period observation of fleet replacement timelines, regulatory certification deadlines, and specialty steel input pricing anchored the trend analysis, supplemented by interviews with railcar leasing executives, chemical manufacturer fleet managers, ASME-certified fabrication yard operators, and PHMSA regulatory affairs specialists. Secondary validation drew from AAR Tank Car Committee construction filings, US DOT incident databases, SEC 10-K disclosures from listed lessors, and Transport Canada dangerous goods transport records. Bottom-up triangulation across fabrication capacity surveys and top-down demand modeling from chemical production forecasts ensured cross-verified outputs.
Input-output matrix framing connected pressure vessel welding throughput, specialty alloy cost indices, and regulatory compliance timelines to fleet replacement volume projections across the analysis window. Segmentation dimensions modeled included car type, material grade, end-user category, and geographic production cluster. CAGRs derived from regression analysis of historical fleet growth against chemical production capacity additions and NGL fractionation expansion schedules. Industry-specific forecast inputs incorporated PHMSA retrofit deadline phasing and Permian Basin infrastructure completion timelines.
Several conditions sit outside the modeled scope, including sudden tariff reconfigurations affecting Canadian-US cross-border movements, accelerated electrification of chemical process heat reducing diluent demand, and breakthrough composite material certifications displacing steel constructions. Forecasts reflect documented assumptions regarding regulatory harmonization progress and specialty steel supply elasticity. Deviation in nickel-molybdenum price volatility or ASME welder labor availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
Automated Truck Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
Electric Truck Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Industrial Vehicles Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
United States Vans Market
Commercial Vehicles
Asia Three Wheeler Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Asia-Pacific Commercial Vehicles Market
Commercial Vehicles
Chile Commercial Vehicle Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market