
 Europe LCV Rental Market | 2026-2036
Europe LCV Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Europe LCV Rental Market Foresight
CE marking under the EU Vehicle Type Approval framework is rotating competitive eligibility toward OEMs with certified electric light commercial platforms. FRAIKIN SAS leverages its refrigerated van specialization to anchor fleet share in temperature-controlled logistics across Southern Europe. Enterprise Holdings, Inc. sustains density advantages through corporate account relationships and airport-adjacent service infrastructure. Sixt SE differentiates via premium self-drive positioning and digital-first booking interfaces that reduce friction for SME users.
Europe LCV rental encompasses the short- to medium-term provision of commercial vehicles under 3.5 tonnes gross vehicle weight, including vans configured for payload capacities between 600 kg and 1,500 kg and box trucks with cube volumes up to 20 cubic metres, serving fleet operators seeking asset-light logistics capacity without ownership risk. Short-term rental contracts command premium per-day rates but exhibit volatile utilization, while flexi-rental structures capture expanding margin pools as corporate customers demand term flexibility without surrendering maintenance inclusion. Vans dominate transaction volume across urban last-mile applications, though refrigerated vans extract higher per-unit economics from pharmaceutical and fresh-food verticals with strict cold-chain requirements.
Euro 7 standards from the European Commission, CE marking under EU Vehicle Type Approval, and national low-emission zones enforced by municipal authorities in London, Paris, and Berlin are reshaping fleet composition toward battery-electric and hydrogen fuel cell platforms. These regulatory layers elevate compliance costs for non-compliant diesel inventory and create procurement urgency among rental operators facing residual value compression. Stakeholders must monitor subsidy phase-out schedules and charging infrastructure build-out rates to time electrification capex against rental rate recovery trajectories.
Market Dynamics
Euro 7 emission standards from the European Commission are compressing diesel residual values and forcing rental operators to accelerate electrification capex cycles ahead of fleet refresh schedules. This regulatory compression is reshaping asset-liability structures across the European rental base.
Growth Catalysts
- CE marking under EU Vehicle Type Approval:Certified electric light commercial platforms are rotating competitive eligibility toward OEMs with compliant architectures, expanding eligible supply for rental procurement.
- Last-mile delivery fleet expansion:German logistics operators are extending rental contracts to avoid capital commitment on depreciating diesel assets while testing electric van economics.
- Low-emission zone proliferation:Municipal authorities in London, Paris, and Berlin are enforcing access restrictions that elevate demand for zero-emission rental substitutes among urban operators.
Market Restraints
- Battery supply concentration:European cell manufacturing capacity lags procurement needs, exposing rental operators to input cost volatility and delivery timeline uncertainty.
- Charging infrastructure gaps:Depot and public fast-charging networks remain underbuilt relative to fleet electrification targets, constraining operational radius for battery-electric rentals.
- Residual value compression on diesel inventory:Euro 7 compliance costs are accelerating depreciation curves for legacy internal combustion assets still held on rental balance sheets.
Strategic Opportunities
- Refrigerated van specialization:Temperature-controlled logistics in Southern Europe offers premium per-unit economics for rental operators with cold-chain certified electric platforms.
- Corporate flexi-rental expansion:France and the United Kingdom are concentrating demand for term-flexible structures that bundle maintenance without ownership risk.
- Hydrogen fuel cell pilot programs:EU Green Deal funding streams are enabling early deployment of fuel cell light commercials for long-haul routes beyond battery range.
Industry Challenges
- Technician certification gaps:High-voltage system maintenance requires specialized training that rental fleet service networks are racing to scale across multiple jurisdictions.
- Telematics integration complexity:Legacy fleet management platforms require reconfiguration to capture battery state-of-charge data and optimize electric vehicle utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe LCV Rental Market |
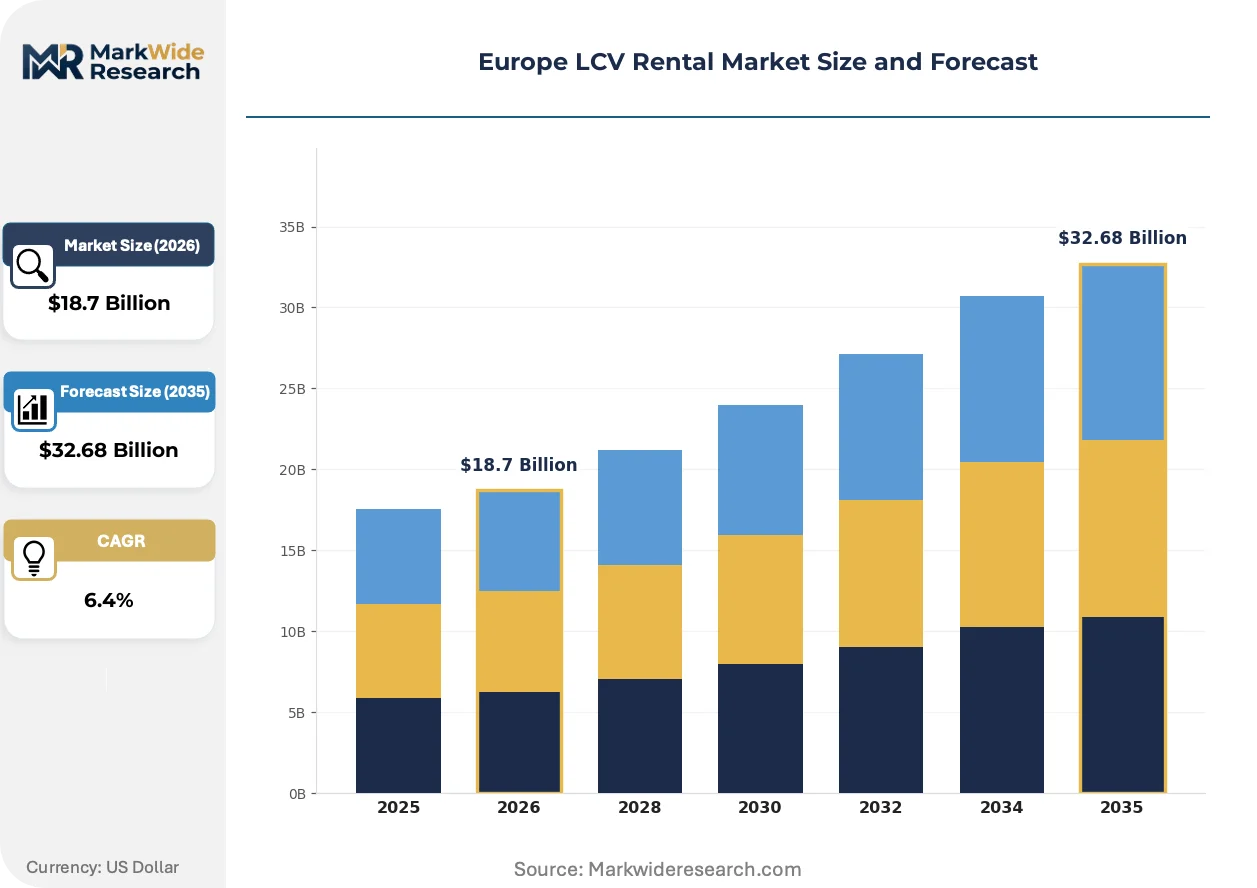
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Vans, Pickups, Box Trucks, Refrigerated Vans Rental Duration: Short-term, Long-term, Monthly, Daily Customer Type: Corporate, Individual, Government, NGO Service Type: Self-drive, Chauffeur-driven, Lease, Flexi-rental |
| Companies Covered | Avis Budget Group, FRAIKIN SAS, Enterprise Holdings, Inc., ALD Automotive, LeasePlan Corp NV, Europcar Mobility Group, The Hertz Corporation, Northgate plc, Sixt SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe LCV Rental Market Shifts & Advancements
Digital booking interfaces and connected fleet management systems are compressing transaction friction for SME users while enabling rental operators to optimize asset utilization through real-time demand matching. These capabilities are redefining service differentiation beyond vehicle specification alone.
Battery-electric van platforms with modular payload configurations are supplanting fixed-body diesel equivalents in urban last-mile applications. Pharmaceutical distributors and fresh-food logistics operators in the Netherlands and Belgium are adopting these architectures fastest. This transition is compressing maintenance cost structures and enabling overnight depot charging that eliminates fuel station downtime.
CSRD disclosure requirements are mandating Scope 3 emissions reporting across corporate supply chains. Rental operators must now provide granular carbon accounting for every leased vehicle-day to enterprise customers. Fleet procurement teams in Germany and Scandinavia are prioritizing rental partners with certified lifecycle data transparency.
SME logistics operators are consolidating vendor relationships toward single-source rental agreements that bundle short-term, flexi-rental, and maintenance services under unified rate structures. Traditional spot-rental brokers in Spain and Italy are losing share to integrated fleet management providers. This concentration is most visible among e-commerce fulfillment contractors seeking operational simplicity over rate shopping.
Europe LCV Rental Market Segmentation
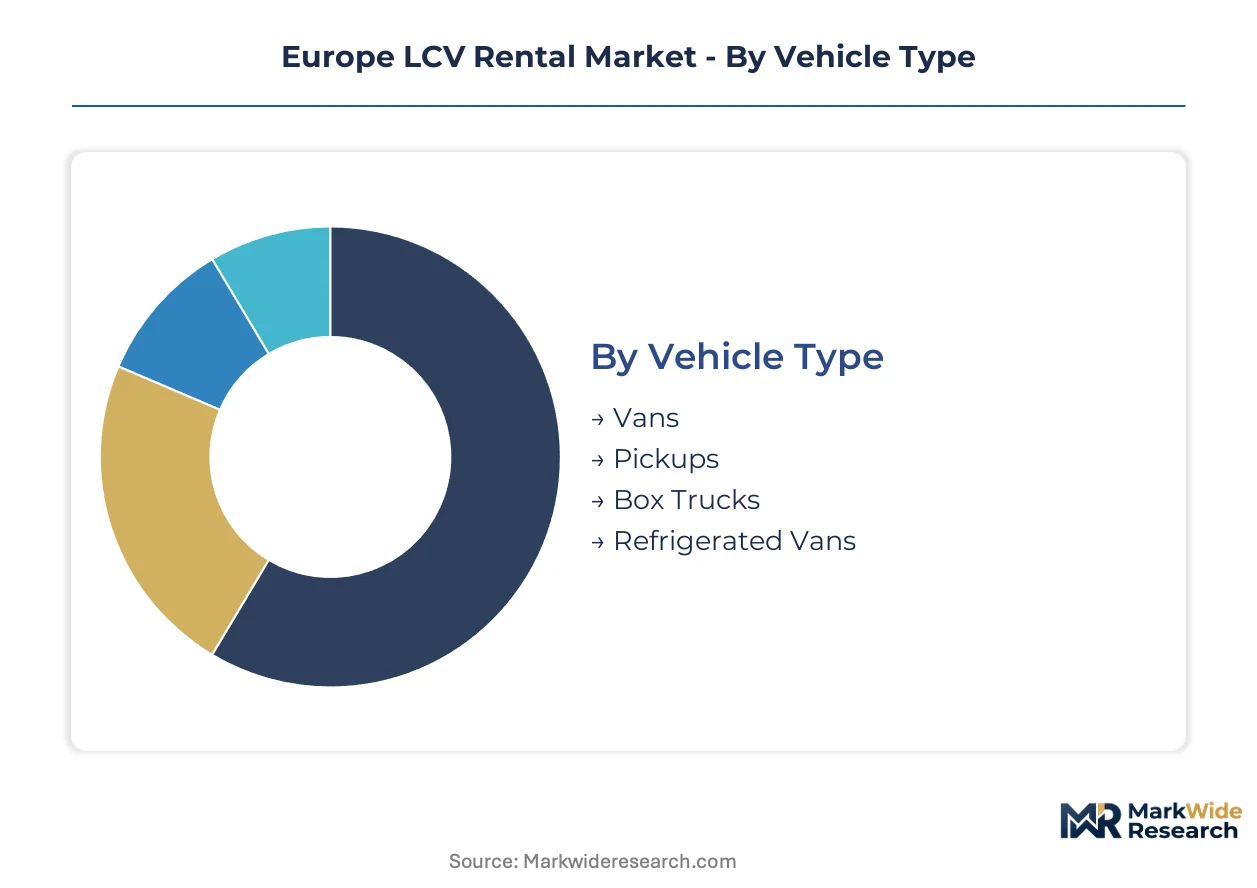
Segmentation in Europe LCV rental reveals how regulatory pressure and fleet economics fragment procurement behavior. CE marking requirements and Euro 7 compliance timelines create divergent asset strategies across vehicle configurations and contract structures.
Vehicle Type:
CE marking under EU Vehicle Type Approval rotates competitive eligibility toward certified electric architectures, elevating procurement complexity for diesel-dependent categories.
- Vans:Configured for payload capacities between 600 kg and 1,500 kg, these vehicles dominate urban last-mile delivery across German and French logistics networks. E-commerce fulfillment contractors in the Netherlands concentrate demand here, prioritizing battery-electric platforms to access municipal low-emission zones in Amsterdam and Rotterdam.
- Refrigerated Vans:Cold-chain certified platforms with integrated temperature control systems serve pharmaceutical distributors and fresh-food operators. Southern European logistics corridors from Barcelona to Milan extract premium per-unit economics from these assets due to strict pharmaceutical GDP compliance and shorter replacement cycles.
- Pickups:Open-bed configurations appeal to construction trades and agricultural contractors across rural Spain and Eastern Europe where payload flexibility outweighs urban access restrictions.
- Box Trucks:Cube volumes up to 20 cubic metres accommodate palletized freight and bulky goods distribution, with demand clustering around industrial zones in Northern Italy and the Rhine-Ruhr region.
Established volume favors vans; emerging adoption favors refrigerated vans.
Rental Duration:
Cost tier differentiation separates premium daily rates from volume-driven long-term structures that bundle maintenance and residual value risk transfer.
- Short-term:Premium per-day pricing captures spot demand from seasonal peaks and vehicle downtime coverage, though utilization volatility compresses margin stability for fleet operators.
- Long-term:Corporate contracts spanning 12-36 months dominate fleet replacement cycles, with German logistics operators extending these structures to avoid capital commitment on depreciating diesel assets.
- Monthly:Mid-tier pricing attracts SME contractors seeking operational flexibility without full lease obligations, particularly visible among UK construction trades.
- Daily:Transaction-heavy spot rentals serve emergency replacement and peak season overflow, with airport-adjacent service infrastructure capturing premium positioning.
Volume concentration sits with long-term; rate expansion sits with short-term.
Customer Type:
Procurement sophistication separates enterprise fleet managers with unified vendor strategies from fragmented individual demand.
- Corporate:Fleet procurement teams in Germany and Scandinavia prioritize rental partners with certified lifecycle data transparency for CSRD Scope 3 reporting, consolidating vendor relationships toward single-source agreements.
- Individual:SME logistics operators and sole traders drive spot-rental transaction volume, though digital booking interfaces are compressing their friction toward integrated platform adoption.
- Government:Municipal fleet procurement in France and the United Kingdom specifies zero-emission mandates for urban service vehicles, accelerating electric van deployment timelines.
- NGO:Humanitarian and development organizations require flexible cross-border mobility with rapid deployment capability, favoring rental structures over owned fleet complexity.
Contract value concentrates with corporate; policy influence concentrates with government.
Service Type:
Margin structure separates asset-light flexi-rental from capital-intensive lease arrangements with residual value exposure.
- Self-drive:Digital-first booking interfaces reduce transaction friction for SME users, with Sixt SE and Enterprise Holdings sustaining density advantages through corporate account relationships and app-based fleet access.
- Chauffeur-driven:Premium positioning serves executive transport and specialized cargo security requirements, extracting rate premiums in London and Paris financial districts.
- Lease:Full-service structures transfer residual value risk to lessors, though Euro 7 compliance costs are accelerating depreciation curves and compressing lease rate competitiveness for diesel inventory.
- Flexi-rental:Term-flexible structures bundle maintenance without ownership risk, with demand concentrating in France and the United Kingdom as logistics operators seek fleet elasticity against demand volatility.
Volume scale favors self-drive; margin expansion favors flexi-rental.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate fleet procurement teams concentrate demand in Germany, France, and the United Kingdom, while temperature-controlled logistics operators anchor volume in Southern Europe. Municipal low-emission zones and national subsidy programs are fragmenting electrification timelines across national borders.
Germany
Last-mile delivery contractors extend rental contracts to avoid capital commitment on depreciating diesel assets. KBA enforces Euro 7 pre-compliance timelines that accelerate fleet refresh cycles. Logistics clusters in the Rhine-Ruhr region concentrate electric van pilot programs as charging infrastructure scales around Cologne and Düsseldorf industrial zones.
France
Corporate flexi-rental demand concentrates among logistics operators seeking fleet elasticity against demand volatility. ANSM-aligned municipal authorities in Paris enforce strict low-emission zone access restrictions that elevate zero-emission rental substitutes. The Île-de-France logistics corridor extracts premium economics from refrigerated van deployments serving pharmaceutical distribution networks.
United Kingdom
SME construction trades and e-commerce fulfillment contractors drive mid-tier monthly rental structures. London's Ultra Low Emission Zone compresses diesel vehicle residual values and accelerates electric van procurement urgency. Midlands industrial zones concentrate integrated fleet management providers capturing share from traditional spot-rental brokers.
Netherlands
E-commerce fulfillment contractors prioritize battery-electric platforms to access municipal low-emission zones in Amsterdam and Rotterdam. The country's national charging infrastructure program enables overnight depot charging that eliminates fuel station downtime. Pharmaceutical distributors in the Randstad region adopt modular payload configurations fastest among Benelux logistics operators.
Italy
Fresh-food logistics operators across the Po Valley extract premium per-unit economics from cold-chain certified rental platforms. Municipal authorities in Milan enforce urban access restrictions that displace non-compliant diesel inventory. Southern European logistics corridors from Milan to Rome concentrate refrigerated van specialization among rental operators with GDP-compliant electric architectures.
Europe LCV Rental Market Competitive Landscape
Player mix skews toward integrated fleet management providers with multi-service bundling capabilities and specialized temperature-control operators with certified cold-chain platforms. Strategic archetypes separate airport-adjacent service infrastructure operators from digital-first booking interface providers and refrigerated van specialists. Competitive moves concentrate on corporate account relationship consolidation and electric platform procurement acceleration ahead of regulatory deadlines.
Within the specialized cold-chain tier, FRAIKIN SAS anchors fleet share in temperature-controlled logistics across Southern Europe. Enterprise Holdings, Inc. and Sixt SE occupy positions on the digital-first and premium self-drive vectors respectively, with the former sustaining density advantages through corporate account relationships and the latter reducing transaction friction for SME users through app-based fleet access.
| Leading Market Players |
|---|
| Avis Budget Group |
| FRAIKIN SAS |
| Enterprise Holdings, Inc. |
| ALD Automotive |
| LeasePlan Corp NV |
| Europcar Mobility Group |
| The Hertz Corporation |
| Northgate plc |
| Sixt SE |
| Others |
Supply & Pricing Matrix
Battery-electric van platforms substituting diesel equivalents simultaneously relocate procurement gravity toward cell manufacturing clusters and compress maintenance-inclusive rate structures across German and French rental markets. This substitution dynamic elevates lithium-ion cell costs as the dominant pricing variable while depot charging infrastructure investments reshape regional fleet economics.
Pricing Analysis
Cost-plus contracts indexed to lithium carbonate futures dominate long-term fleet procurement agreements between rental operators and German logistics contractors. Three-tier pricing structure across premium refrigerated, standard panel van, and economy compact categories reflects CE certification tiers and cold-chain GDP compliance levels. Pricing pressure stems from Euro 7 compliance costs accelerating diesel residual value compression, with SME construction trades exhibiting highest price sensitivity and pharmaceutical distributors showing lowest due to regulatory mandate pass-through.
Supply Chain Analysis
Just-in-time vehicle delivery from OEM assembly plants in Germany, France, and Spain contrasts with strategic stockpiling of high-voltage battery modules by major rental operators facing cell supply volatility. The supply chain draws from South Korean and Chinese cell manufacturers, European electric motor specialists, and domestic chassis fabricators. Single-source vulnerability concentrates in battery cell procurement, with distribution running through OEM-certified dealer networks and direct fleet allocation channels to rental balance sheets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe LCV rental represents a high-growth disruption anchored to Euro 7 regulatory compression forcing electrification capex cycles ahead of traditional fleet refresh timelines.
For Market Incumbents: Fortify residual value risk management through accelerated electric platform procurement and captive maintenance network certification for high-voltage systems. Diesel inventory depreciation curves threaten balance sheet stability, while backward integration into depot charging infrastructure offers margin protection against energy cost volatility. For New Entrants and Emerging Players: CE marking fast-track for refrigerated electric van architectures opens white-space penetration in Southern European pharmaceutical logistics corridors. Target underpenetrated mid-tier flexi-rental demand among UK SME contractors through digital-first booking interfaces bundling maintenance and roadside assistance. For Investors and Strategic Acquirers: The market sits at a regulatory inflection phase that favors specialized cold-chain operators with certified electric platforms and integrated fleet management providers with multi-service bundling capabilities. Acquisition targets should demonstrate CSRD-compliant carbon accounting infrastructure. The signal to watch is municipal low-emission zone expansion timelines accelerating zero-emission rental substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Platform Procurement Acceleration | Locks in CE-certified van supply ahead of Euro 7 residual value compression affecting diesel inventory. |
| Depot Charging Infrastructure Partnership | Secures overnight charging capacity eliminating fuel station downtime for battery-electric fleet deployments. |
| Refrigerated Van Specialization Investment | Captures premium per-unit economics from pharmaceutical GDP compliance requirements across Southern Europe. |
| Corporate Flexi-Rental Service Launch | Bundles maintenance and term flexibility to consolidate vendor relationships among German logistics operators. |
| CSRD-Compliant Carbon Accounting Integration | Enables Scope 3 emissions reporting for enterprise fleet procurement teams in Germany and Scandinavia. |
Research Methodology
Initial hypotheses were tested against primary input from fleet procurement managers, rental operator executives, OEM platform engineers, and municipal transport planners and refined through secondary validation across EU Vehicle Type Approval databases, KBA registration statistics, national low-emission zone enforcement records, and corporate sustainability disclosure filings. Bottom-up demand modeling from logistics operator fleet refresh schedules triangulated against top-down market sizing from rental fleet capacity data.
Variance decomposition across vehicle type, rental duration, customer segment, and service tier dimensions structured the analytical framework over the projection horizon. CAGRs derived from regression analysis against electrification capex cycles and regulatory compliance timelines incorporated charging infrastructure build-out rates and subsidy phase-out schedules as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of Euro 7 enforcement continuity and lithium cell supply normalization; material deviation would warrant model refresh. Revision becomes warranted when municipal low-emission zone proliferation or battery supply concentration crosses thresholds altering fleet procurement urgency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Chile Commercial Vehicle Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Heavy Haulage Trucks Market
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
Robotic Haul Trucks Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Global Commercial Vehicles Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Asia Three Wheeler Market
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
Industrial Truck Market
Commercial Vehicles
Compact Utility Vehicles Market