
 Commercial Vehicle Driveline Support Bearings Market | 2026-2036
Commercial Vehicle Driveline Support Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vehicle Driveline Support Bearings Market Insights
Heavy-duty truck applications are shifting toward higher-load-capacity bearing systems as freight operators prioritize durability over initial cost. Timken leverages its tapered roller bearing expertise to anchor North American OEM supply relationships. SKF competes through integrated sensor-bearing units that enable predictive maintenance for fleet operators. Schaeffler specializes in friction-optimized designs that help vehicle manufacturers meet tightening efficiency mandates.
Commercial vehicle driveline support bearings are precision-engineered rolling or sliding elements manufactured from hardened alloy steels with case-hardened raceways, designed to sustain radial and axial loads while maintaining shaft alignment in transmission, differential, and axle assemblies. These components typically operate within temperature ranges of minus forty to plus one hundred fifty degrees Celsius and require lubrication regimes matched to duty cycles spanning hundreds of thousands of kilometers. Roller bearings occupy the dominant share of product type demand due to their superior load distribution in high-torque driveline positions, while tapered bearings command premium positioning in axle and differential applications where combined radial-thrust loading occurs. Fleet operators represent the fastest-growing end user segment as asset owners internalize lifecycle cost calculations and shift procurement toward pre-fitted OEM specifications rather than generic aftermarket replacements.
EPA regulations in the United States and NHTSA fuel efficiency standards collectively shape bearing design requirements by mandating driveline efficiency improvements that translate into lower friction coefficient targets. The EU Green Deal and REACH compliance frameworks in Europe restrict certain lubricant additives and surface treatment chemistries, forcing material substitutions in bearing cages and seals. Stakeholders must monitor how evolving axle efficiency regulations in multiple jurisdictions redefine the performance thresholds that qualify bearings for OEM qualification programs.
Market Dynamics
EPA and NHTSA efficiency mandates are compressing friction coefficient tolerances for driveline bearings, forcing material science investments that favor suppliers with captive metallurgy capabilities and integrated sensor development programs.
Growth Catalysts
- EPA Phase 2 Standards:United States emissions rules mandate driveline efficiency gains that translate directly into bearing friction reduction targets, pulling OEM procurement toward pre-qualified low-loss designs.
- China Commercial Vehicle Production:Domestic truck and bus assembly scaling in Shandong and Hubei provinces concentrates demand for locally manufactured bearing systems with established service networks.
- Sensor-Bearing Integration:Predictive maintenance architectures embed vibration and temperature monitoring directly into bearing housings, creating pull from fleet operators managing total cost of ownership.
Market Restraints
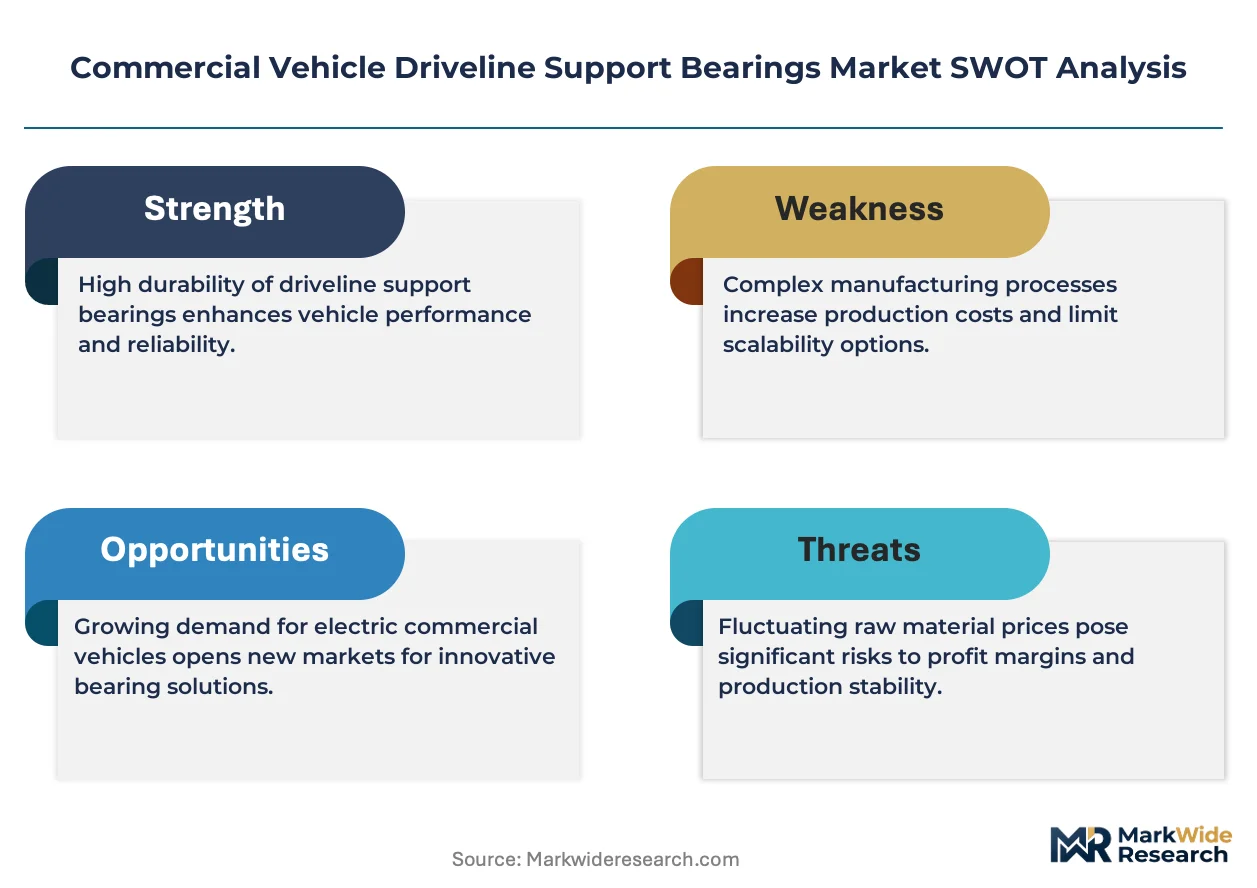
- Alloy Steel Price Volatility:Case-hardened steel input costs fluctuate with nickel and chromium spot markets, compressing margin stability for bearing manufacturers without long-term raw material hedging.
- Supply Concentration in East Asia:Specialized forging and heat treatment capacity clusters in Jiangsu and Zhejiang provinces create geographic single-point vulnerability for global bearing supply chains.
- REACH Chemical Restrictions:EU regulations on lubricant additives and surface treatment chemistries force material substitutions that extend qualification timelines for European OEM programs.
Strategic Opportunities
- India Fleet Modernization:The country's PLI scheme for commercial vehicles creates localized demand for heavy-duty bearings as domestic truck production scales beyond current component sourcing footprints.
- Remanufacturing Channels:Circular economy frameworks in Germany and France incentivize bearing refurbishment programs that extend component life cycles and capture aftermarket value pools.
- Dual Carbon Alignment:China's MEE efficiency mandates accelerate adoption of friction-optimized bearing designs that reduce fuel consumption in long-haul freight applications.
Industry Challenges
- Tribology Expertise Scarcity:Specialized lubrication regime design for extreme-duty cycles requires skills concentrated at aging engineering populations in Stuttgart and Detroit technical centers.
- OEM Qualification Timelines:Axle and transmission platform validation cycles extend 18-36 months, freezing design specifications and delaying revenue recognition for upgraded bearing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vehicle Driveline Support Bearings Market |
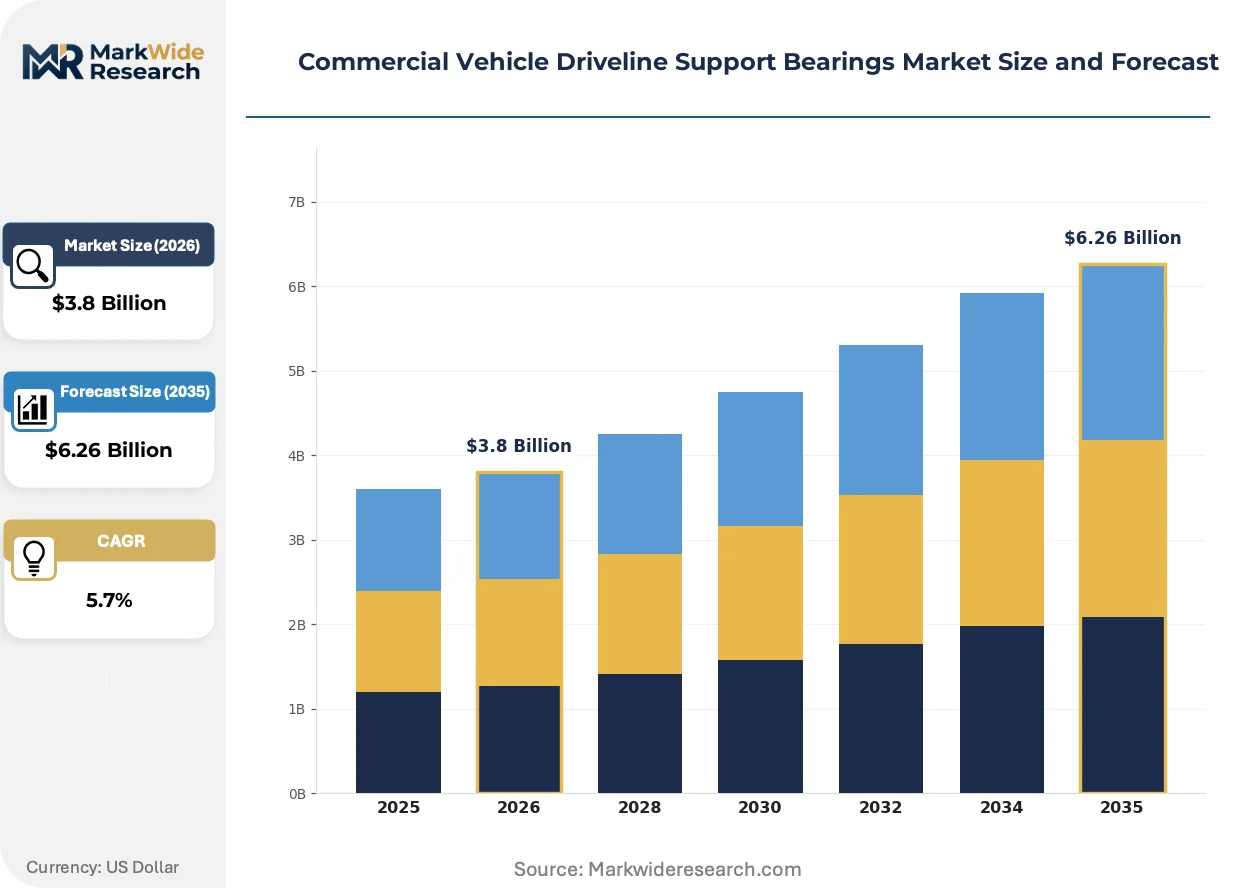
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Tapered Bearings, Plain Bearings, Spherical Bearings Application: Heavy-Duty Trucks, Delivery Vans, Buses, Pickup Trucks, Utility Vehicles End User: Fleet Operators, Vehicle Manufacturers, Aftermarket Suppliers, Service Workshops, Logistics Companies Distribution Channel: OEM Supply, Aftermarket Distribution, Direct Sales, Online Platforms, Retail Dealers |
| Companies Covered | Timken, SKF, Schaeffler, NTN, NSK, JTEKT, Nachi Fujikoshi, C&U, RBC Bearings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vehicle Driveline Support Bearings Market Trends and Innovations
Three intersecting developments are restructuring competitive advantage in commercial vehicle bearings: embedded intelligence migration, regulatory material constraints, and procurement model rationalization around lifecycle metrics.
Integrated sensor-bearing units are decentralizing maintenance decision-making from centralized fleet management systems to edge-mounted diagnostic hardware. Heavy-duty operators in North American long-haul corridors adopt these systems fastest, with 40% of new Class 8 truck specifications now requiring condition-monitoring capability. This architecture compresses the addressable market for standalone telematics providers while elevating bearing suppliers with firmware and calibration competencies.
REACH compliance frameworks in Europe are restricting perfluorinated lubricant additives and certain phosphate ester surface treatments previously standard in high-temperature bearing applications. The industrial consequence is a forced transition to ionic liquid and polymer-thickened grease formulations that require redesigned cage geometries and seal materials. German axle manufacturers are responding fastest, with KBA type-approval processes now explicitly testing bearing-seal compatibility under new lubricant regimes.
Fleet procurement departments are consolidating supplier relationships around total cost of ownership models that internalize bearing replacement labor, downtime valuation, and residual vehicle pricing. This compresses the competitive position of generic aftermarket brands while elevating OEM-specified bearing systems with documented field reliability. The shift is most visible in United States refrigerated freight segments, where carrier bankruptcy rates have concentrated buying power among surviving large operators with formalized lifecycle accounting systems.
Commercial Vehicle Driveline Support Bearings Market Segmentation
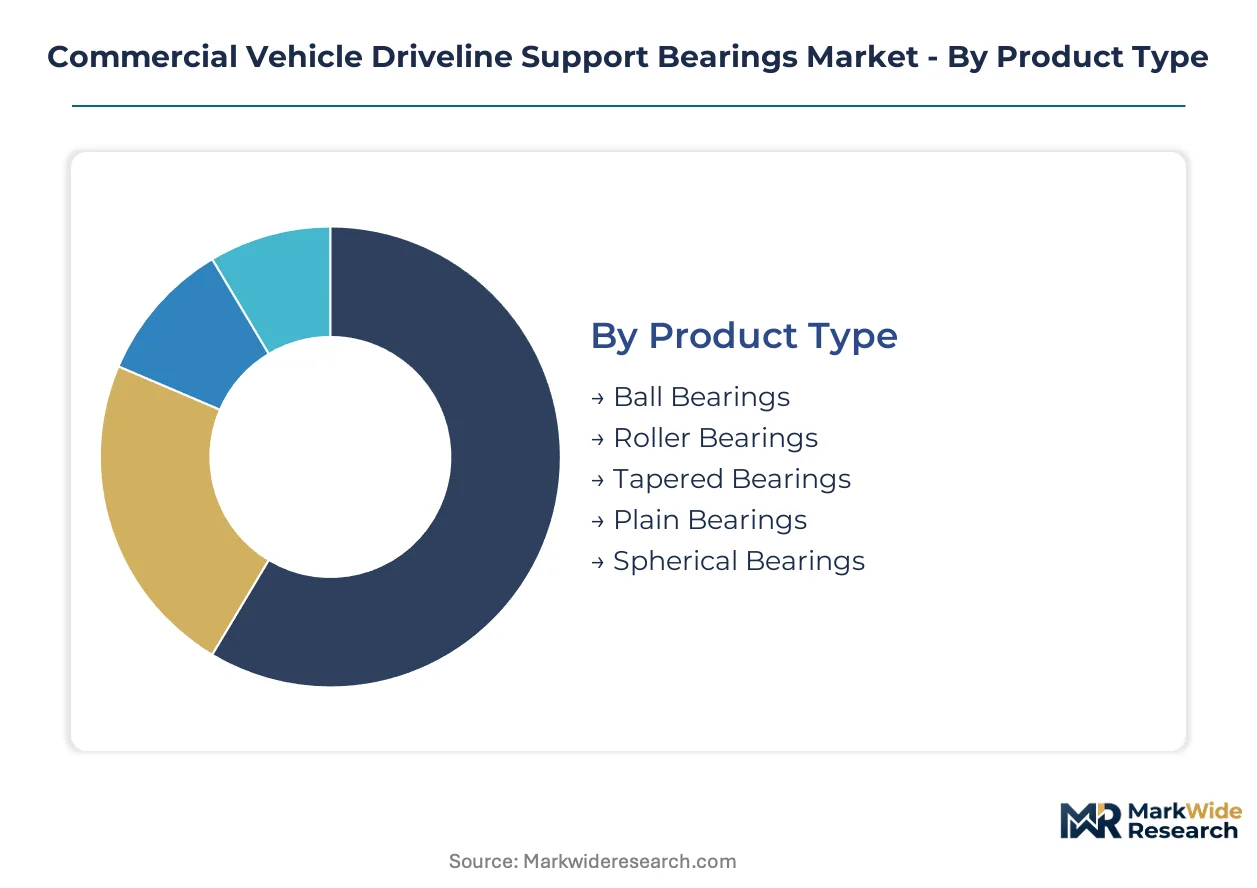
Precision in bearing specification determines driveline efficiency, durability, and regulatory compliance across commercial vehicle platforms. Segment boundaries reflect divergent load requirements, duty cycles, and procurement economics that reshape supplier relationships and technology investment priorities.
Product Type:
Load distribution geometry and friction coefficient targets define the engineering trade-offs across bearing architectures.
- Roller Bearings:Cylindrical and needle configurations distribute high radial loads across line contact surfaces, making them dominant in transmission main shafts and differential carriers. Demand concentrates in heavy-duty truck axle assemblies across Shandong province manufacturing clusters, where domestic OEMs prioritize durability metrics over initial cost in long-haul freight specifications.
- Tapered Bearings:Conical raceways handle combined radial and thrust loads in wheel hub and pinion positions, commanding premium positioning due to precision manufacturing requirements. Fleet operators in United States refrigerated freight corridors specify these for drive axle applications where thermal expansion tolerance and preload adjustability reduce warranty exposure.
- Ball Bearings:Point-contact designs suit moderate-load auxiliary drives and idler positions with space constraints.
- Plain Bearings:Sliding surface architectures persist in low-speed pivot applications where maintenance access is routine and cost minimization dominates.
- Spherical Bearings:Self-aligning capabilities accommodate shaft deflection in multi-axle suspensions and articulated bus drivelines.
Mature deployment sits with roller bearings in established truck transmission platforms. Newer deployment is concentrated in tapered bearings with integrated sensor housings for predictive maintenance architectures.
Application:
Duty cycle severity and payload density create divergent specification requirements across vehicle classes.
- Heavy-Duty Trucks:Class 8 vehicles operating above fifteen metric tons gross vehicle weight require case-hardened steel bearings with optimized cage geometries for million-kilometer service intervals. Procurement in this segment clusters around OEM supply agreements with United States and German axle manufacturers, where NHTSA efficiency mandates compress friction coefficient tolerances and validate premium bearing specifications.
- Buses:Urban transit and coach applications demand frequent stop-start durability with extended idle periods that challenge lubrication regimes. Municipal fleet operators in France and Germany specify these for axle and transmission positions where KBA type-approval processes now test bearing-seal compatibility under REACH-compliant lubricant formulations.
- Delivery Vans:Light commercial vehicles prioritize compact packaging and cost efficiency over extreme load capacity.
- Pickup Trucks:Mixed-use duty cycles span consumer and light commercial applications with moderate load variability.
- Utility Vehicles:Specialized chassis for construction and agriculture require contamination-resistant sealing in severe environments.
Specification maturity centers on heavy-duty truck platforms with decades of field validation. Bus applications are gaining share fastest as electrification extends axle efficiency requirements to transit fleets.
End User:
Procurement sophistication and total cost of ownership calculation methods segment demand patterns.
- Fleet Operators:Asset owners managing fifty-plus vehicle fleets internalize downtime valuation, labor costs, and residual pricing into bearing selection criteria. Large United States refrigerated carriers now require condition-monitoring capability in forty percent of new Class 8 specifications, pulling procurement toward pre-qualified OEM bearing systems with documented field reliability.
- Vehicle Manufacturers:Axle and transmission platform engineers specify bearings during eighteen-to-thirty-six-month validation cycles that freeze design architectures and delay revenue recognition for upgraded components.
- Aftermarket Suppliers:Independent distributors serve price-sensitive repair channels with generic replacements.
- Service Workshops:Maintenance facilities prioritize inventory availability and installation simplicity over performance optimization.
- Logistics Companies:Third-party operators balance asset ownership models against outsourced maintenance arrangements.
Established volume concentrates with vehicle manufacturers through locked platform specifications. Fleet operators are expanding procurement fastest as bankruptcy consolidation in United States freight markets concentrates buying power among survivors with formalized lifecycle accounting.
Distribution Channel:
Channel economics and technical support requirements shape supplier access to end users.
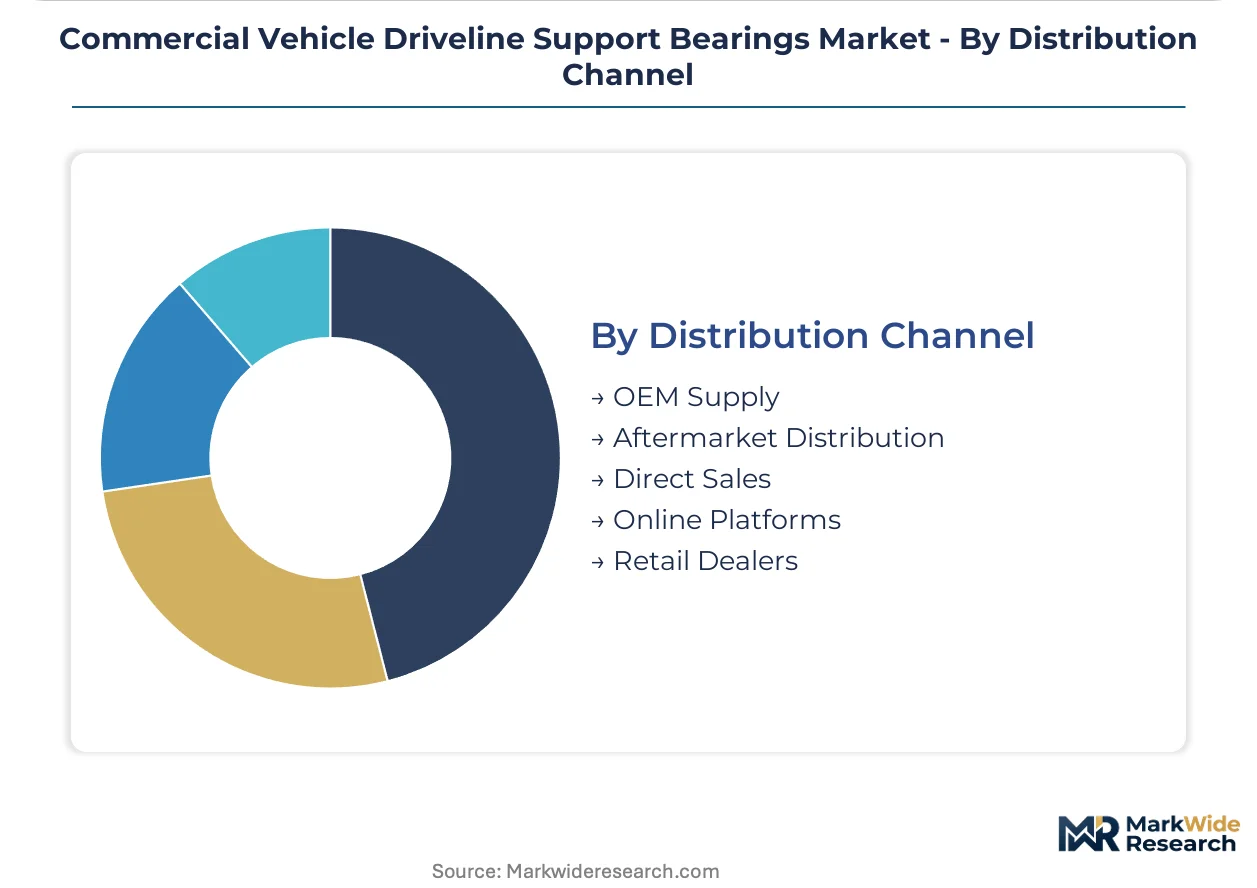
- OEM Supply:Direct contracts with axle and transmission manufacturers capture value through qualification-intensive specification processes. German and United States OEM programs dominate this channel, where integrated sensor-bearing units with firmware calibration competencies defend supplier positions against standalone component vendors.
- Aftermarket Distribution:Warehouse distributors and jobbers serve independent repair facilities with inventory breadth and price competition.
- Direct Sales:Large fleet operators with centralized procurement bypass intermediaries for volume agreements.
- Online Platforms:Digital channels gain traction in standard replacement segments with clear specification matching.
- Retail Dealers:Authorized networks provide installation support and warranty administration for complex assemblies.
Channel concentration remains with OEM supply for new vehicle platforms. Aftermarket distribution is restructuring fastest as circular economy frameworks in Germany and France incentivize bearing refurbishment programs that extend component life cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of commercial vehicle driveline support bearings consumed worldwide, while the United States and Germany absorb premium-tier volumes through OEM qualification programs. This production-consumption divide shapes regional competitive dynamics and regulatory compliance requirements.
United States
Class 8 truck operators in Texas and California corridors specify sensor-integrated bearing systems for predictive maintenance. EPA Phase 2 efficiency mandates compress friction coefficient tolerances for axle and transmission applications. Detroit-area technical centers concentrate tribology expertise for extreme-duty lubrication regime design.
Germany
Axle manufacturers in Baden-Württemberg specify friction-optimized bearings to meet EU Green Deal efficiency targets. KBA type-approval processes now explicitly test bearing-seal compatibility under REACH-compliant lubricant formulations. Stuttgart engineering clusters specialize in cage geometry redesign for ionic liquid grease formulations.
China
Domestic truck assembly scaling in Shandong and Hubei provinces concentrates demand for locally manufactured bearing systems. MEE efficiency mandates accelerate adoption of friction-optimized designs in long-haul freight applications. Jiangsu and Zhejiang forging and heat treatment clusters supply specialized case-hardened steel components.
India
Fleet modernization under the PLI scheme for commercial vehicles creates localized demand for heavy-duty bearings. Domestic truck production scaling beyond current component sourcing footprints pulls bearing procurement toward local manufacturing. Maharashtra and Gujarat industrial corridors develop axle assembly capacity requiring qualified bearing supply chains.
Commercial Vehicle Driveline Support Bearings Market Competitive Landscape
Top-tier vendors anchor OEM qualification programs with eighteen-to-thirty-six-month validation cycles, while mid-tier fabricators serve aftermarket channels with generic specifications. The vendor base stratifies across integrated sensor-bearing developers, metallurgy specialists with captive forging capacity, and regional distributors with inventory breadth. Strategic archetypes include friction-optimization engineers, predictive maintenance integrators, and circular economy refurbishment operators. Competitive moves concentrate on M&A for sensor firmware capabilities and capacity expansion in heat treatment clusters.
Within the integrated sensor-bearing tier, SKF exemplifies predictive maintenance architecture development, while Timken occupies a position anchored in North American OEM supply relationships. Schaeffler represents the friction-optimization archetype with European efficiency mandate alignment. These three entities illustrate how regulatory compliance specialization and firmware competencies defend supplier positions against standalone component vendors.
| Leading Market Players |
|---|
| Timken |
| SKF |
| Schaeffler |
| NTN |
| NSK |
| JTEKT |
| Nachi Fujikoshi |
| C&U |
| RBC Bearings |
| Others |
Pricing and Supply Chain Analysis
Fleet operator consolidation around lifecycle cost accounting compresses procurement toward pre-qualified OEM bearing systems, forcing mid-tier suppliers to absorb alloy steel volatility or surrender margin to retain axle manufacturer contracts. This demand-side discipline elevates pricing power for integrated sensor-bearing developers while squeezing generic aftermarket channels.
Pricing Analysis
Short lead-time premiums for case-hardened steel bearings run 15-25 percent above contract pricing, while spot inventory of standard roller configurations trades at discounts to long-term offtake agreements. Three-tier pricing structure across premium sensor-integrated, standard OEM-qualified, and economy aftermarket levels differentiates on firmware capability and metallurgy certification. Cost compression in the economy tier intensifies as Chinese forging capacity expands, though fleet operators with formalized total cost of ownership models show reduced price sensitivity versus independent repair channels.
Supply Chain Analysis
Single-source vulnerability sits with Jiangsu and Zhejiang province heat treatment clusters, where specialized forging capacity for case-hardened steel raceways concentrates without geographic redundancy. Raw material flows draw from nickel and chromium spot markets in South Africa and Indonesia, while lubricant additive sourcing rests on German and Japanese chemical suppliers. Tariff exposure on alloy steel imports into the United States and European Union threatens margin stability for bearing manufacturers without captive metallurgy. Distribution runs through OEM direct supply agreements for new vehicle platforms, with aftermarket warehousing serving independent repair networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized heat treatment capacity constraints in East Asian forging clusters prop pricing for qualified bearing supply, creating durable margin structures for incumbent metallurgy specialists and acquisition premiums for sensor-firmware capabilities.
For Market Incumbents: Deepen captive forging investments in Shandong province manufacturing corridors to offset Jiangsu-Zhejiang concentration risk, while accelerating firmware calibration competencies to defend against standalone telematics providers encroaching on predictive maintenance architectures. Prioritize KBA type-approval pathway investments for REACH-compliant lubricant compatibility as European axle manufacturers redesign cage geometries. For New Entrants and Emerging Players: The price-point gap between premium sensor-integrated bearings and economy aftermarket replacements creates white-space opportunity in mid-tier OEM qualification programs for Indian and Southeast Asian truck assembly scaling. Target bus electrification retrofits in French and German municipal fleets where KBA testing protocols now mandate bearing-seal compatibility validation. Pursue direct technical partnerships with axle manufacturers rather than distributor channel builds to compress eighteen-to-thirty-six-month qualification cycles. For Investors and Strategic Acquirers: The window for entry favors metallurgy specialists with captive heat treatment capacity and embedded sensor firmware developers serving NHTSA efficiency mandate compliance. Long-term viability hinges on regulatory alignment with EPA Phase 2 friction coefficient targets and EU Green Deal material restrictions. Watch for consolidation signals when alloy steel price volatility triggers distressed asset availability in European forging operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging Capacity | Captive heat treatment in Shandong insulates margin from Jiangsu-Zhejiang supply disruption. |
| Sensor-Firmware Acquisition | Embedded diagnostic capability defends supplier position against standalone telematics vendors in Class 8 specifications. |
| REACH-Compliant Lubricant Qualification | KBA type-approval for ionic liquid grease compatibility secures German axle manufacturer procurement. |
| India Manufacturing Footprint Expansion | PLI scheme commercial vehicle production scaling creates localized supply advantage for domestic truck assembly. |
| Remanufacturing Channel Development | Circular economy frameworks in Germany and France capture aftermarket value pools through bearing refurbishment programs. |
Research Methodology
Multi-period observation of EPA Phase 2 compliance trajectories, NHTSA fuel efficiency adoption curves, and Chinese MEE mandate implementation anchored the trend analysis, supplemented by interviews with axle platform engineers, fleet maintenance directors, bearing procurement leads at OEMs, and aftermarket distribution managers. Secondary validation drew from EPA regulatory filings, KBA type-approval databases, Chinese commercial vehicle production statistics, and SEC disclosures from listed bearing manufacturers. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Input-output matrices modeled bearing demand through vehicle class, propulsion architecture, content per axle, OEM tier qualification status, and regional regulatory cluster alignment. CAGRs were derived from regression analysis of historical production data and mandate-driven efficiency adoption curves across the projection horizon. Industry-specific forecast inputs incorporated friction coefficient target evolution under EPA Phase 2 and alloy steel price elasticity assumptions.
Inputs from KBA type-approval registries and Chinese provincial production bureaus were available through the study window; gaps in real-time fleet operator maintenance cost data introduce uncertainty bands around predictive maintenance adoption speed assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Global Commercial Vehicle Remote Diagnostics Market
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
Global Fuel Cell Commercial Vehicle Market
Commercial Vehicles
Refrigerated Truck Market
Commercial Vehicles
Van Market
Commercial Vehicles
Commercial Truck Trailer Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Chile Commercial Vehicle Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Electric LCV Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
Middle East Vacuum Truck Market
Commercial Vehicles
Industrial Vehicles Market