
 Used Truck Market | 2026-2036
Used Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Used Truck Market Analysis
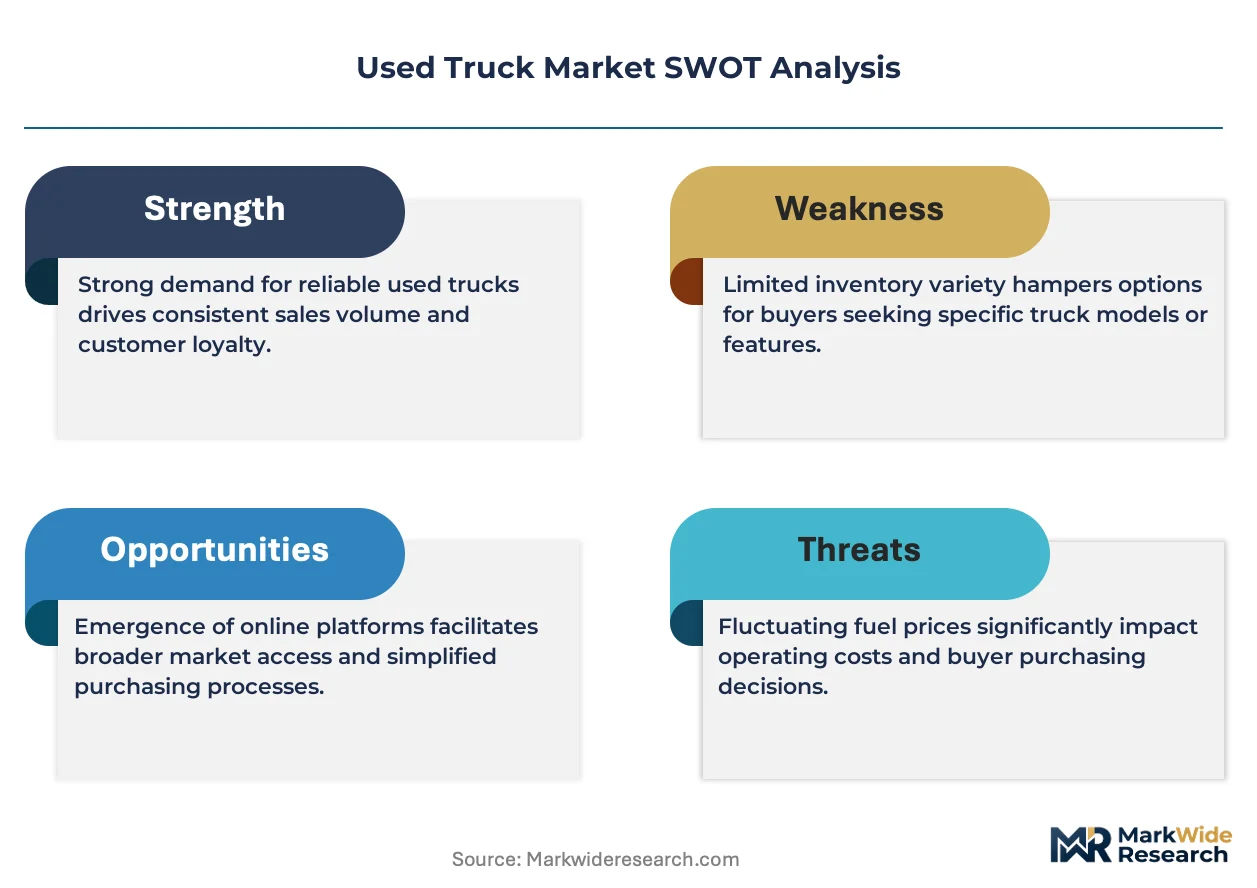
E-commerce fulfillment is restructuring fleet replacement cycles across North America. Daimler Truck AG leverages its certified pre-owned network to capture fleet turnover demand. PACCAR Inc. sustains resale premiums through proprietary powertrain warranties. Volvo Group anchors secondary market liquidity with factory-backed refurbishment programs in the Midwest and Southeastern states.
A used truck denotes a previously operated commercial vehicle with a gross vehicle weight rating exceeding 10,000 pounds, retaining structural utility for freight hauling, construction, or municipal service after initial ownership. Diesel powertrains dominate transaction volume due to torque requirements and established service infrastructure, though electric drivetrains are gaining share in last-mile and urban delivery applications. Certified pre-owned units command margin concentration because dealer inspection protocols reduce buyer uncertainty and financing access improves. Online platforms represent the fastest-growing sales channel as digital remarketing tools compress transaction timelines and expand geographic matching between sellers and fleet buyers.
EPA emissions enforcement and CARB compliance deadlines shape vehicle eligibility for interstate registration and resale value retention. NHTSA safety recall tracking and FMCSA hours-of-service rules indirectly steer fleet preferences toward newer used models with integrated telematics. Stakeholders must monitor how zero-emission zone expansions in California and pending federal GHG standards reshape which model years retain operational utility across state lines.
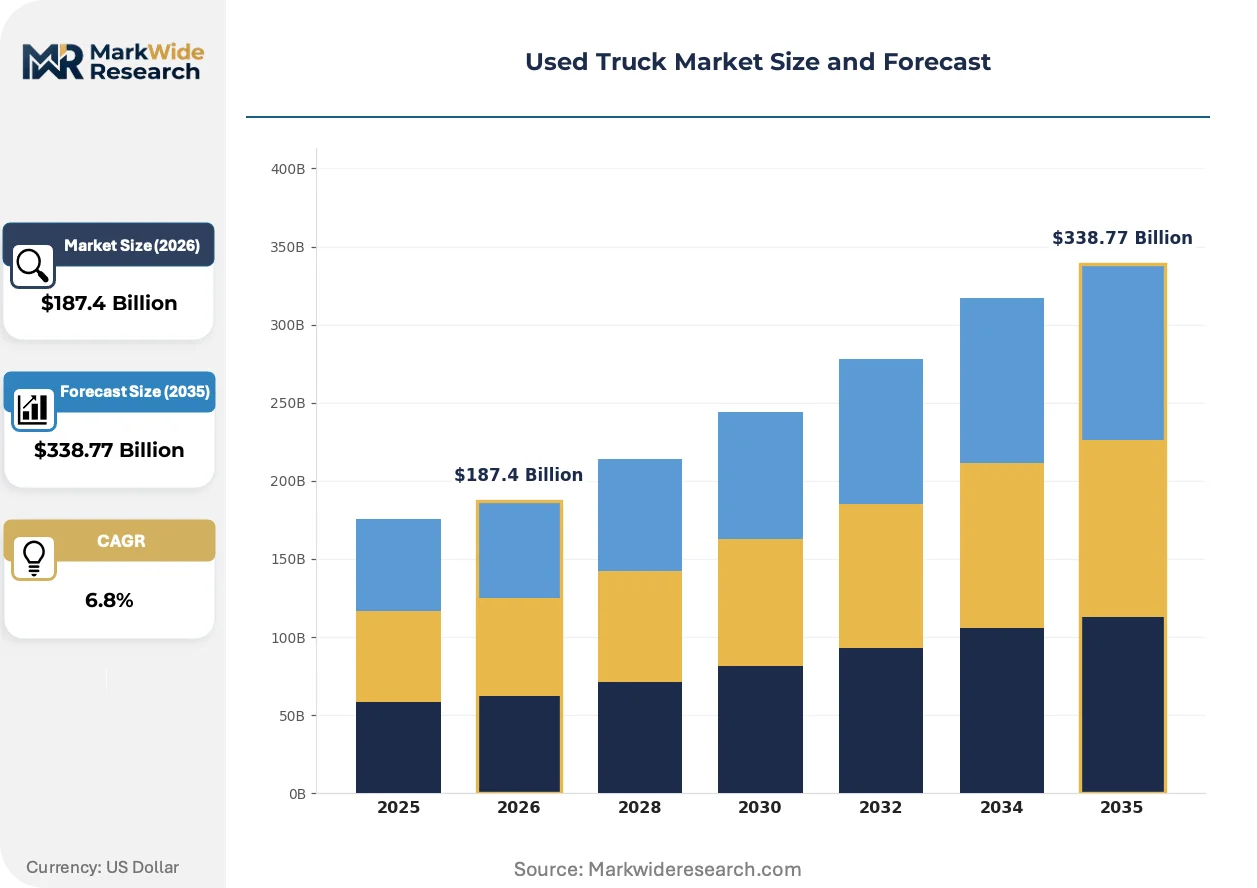
Market Dynamics
EPA Phase 3 emissions standards and CARB mandates are compressing fleet replacement timelines as operators accelerate procurement ahead of compliance deadlines. This regulatory pressure is restructuring capital allocation across logistics networks.
Growth Catalysts
- E-commerce fulfillment density:Parcel volume concentration in urban corridors is forcing expedited fleet turnover. Last-mile operators require additional tractor units to maintain service-level agreements.
- IRA commercial vehicle incentives:Federal tax credits for clean-fuel retrofits are improving total cost of ownership calculations for certified pre-owned diesel-electric hybrids.
- Texas-I-35 manufacturing corridor:Heavy freight volume between Dallas-Fort Worth and Laredo is sustaining above-average transaction velocity for sleeper cab configurations.
Market Restraints
- Steel and aluminum input volatility:Cab and chassis fabrication costs fluctuate with commodity indexes, squeezing refurbishment margins for independent dealers.
- California zero-emission zone expansion:CARB's Advanced Clean Trucks rule is rendering certain model years ineligible for interstate registration, fragmenting resale liquidity.
- Telematics integration gaps:Older ECM architectures lack over-the-air update capability, limiting FMCSA hours-of-service compliance automation.
Strategic Opportunities
- Midwest factory refurbishment programs:Ohio and Indiana service centers can anchor regional certified pre-owned distribution networks.
- Digital remarketing platform penetration:Auction aggregators are compressing transaction timelines from 45 days to under 14 days.
- IRA alternative fuel infrastructure grants:CNG and hydrogen fueling investments along I-10 and I-40 corridors enable used natural gas truck deployment.
Industry Challenges
- Diesel technician shortage:Aftertreatment system diagnostics require specialized training that vocational programs have not scaled to match fleet demand.
- Multi-state registration complexity:Varying EPA enforcement interpretations create compliance documentation burdens for interstate operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used Truck Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Truck Type: Pickup, Box Truck, Flatbed, Dump Truck Fuel Type: Diesel, Gasoline, Electric, Hybrid Condition: Refurbished, Certified Pre-Owned, As-Is, Salvage Sales Channel: Dealerships, Auctions, Private Sales, Online Platforms |
| Companies Covered | Volvo Group, Daimler Truck AG, PACCAR Inc., Navistar International Corporation, Scania AB, MAN Truck & Bus SE, Isuzu Motors Limited, Hino Motors, Ltd., Penske Used Trucks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used Truck Market Emerging Trajectories
Telematics integration and powertrain electrification are compressing traditional replacement cycles. Fleet managers now prioritize data-enabled asset visibility over nominal equipment age.
Remanufactured battery-electric drivetrains are modularizing secondary market entry points for zero-emission vehicles. Regional grocery and beverage distributors in California are piloting refurbished Class 6 electric trucks for urban delivery routes. This technology is modularizing total cost of ownership calculations by separating battery asset ownership from chassis procurement.
EPA's pending GHG Phase 3 standards for heavy-duty vehicles are forcing pre-buy activity ahead of 2027 implementation. Fleet operators are advancing replacement schedules to secure compliant model years. Sleeper cab configurations for long-haul routes face the most acute inventory pressure.
Subscription-based maintenance bundling is displacing traditional per-incident service relationships. Large fleet buyers now demand predictable operating cost structures from used truck vendors. This shift is most visible among pharmaceutical and cold-chain logistics operators in the Northeast corridor.
Used Truck Market Segmentation
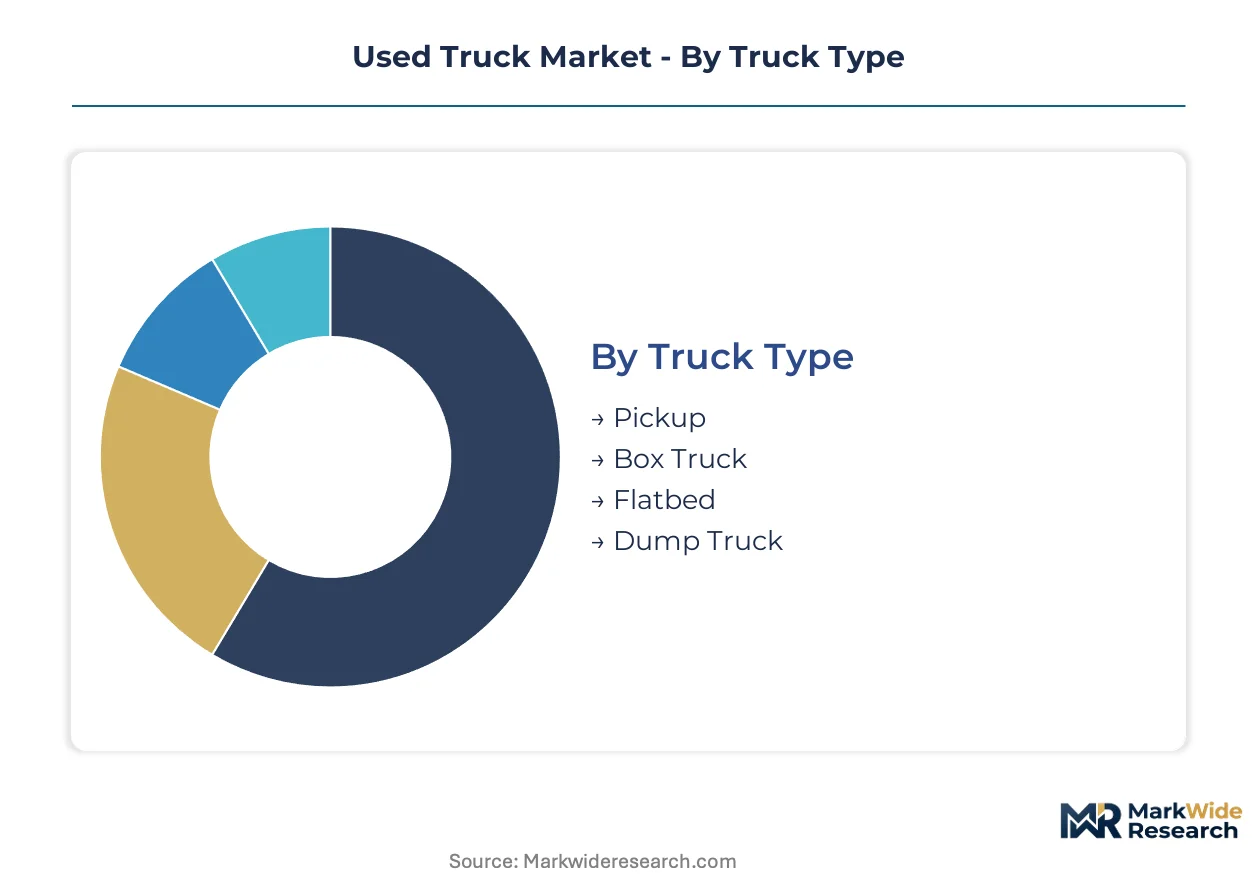
Used truck procurement patterns diverge sharply across operational requirements, regulatory exposure, and capital constraints. Fleet buyers segment their searches by payload specifications, emissions compliance windows, and residual value predictability.
Truck Type:
Operational duty cycles determine which configurations dominate procurement volumes across freight corridors and construction zones.
- Pickup:Light-duty chassis rated between 10,001 and 14,000 pounds GVWR serve contractor fleets and last-mile operators. Texas and Florida construction markets sustain above-average transaction velocity for crew cab configurations with towing packages.
- Box Truck:Enclosed cargo bodies from 14 to 26 feet dominate urban delivery and moving services. E-commerce fulfillment density in California and New York metro areas is compressing replacement cycles for Class 5 and Class 6 straight trucks.
- Flatbed:Open-deck configurations accommodate irregular loads in agriculture and equipment hauling.
- Dump Truck:Hydraulic lift mechanisms serve aggregate and demolition sectors with severe-duty chassis requirements.
Box trucks lead volumes today; electric drivetrain variants are gaining share fastest in urban delivery corridors.
Fuel Type:
Powertrain selection reflects torque demands, fuel infrastructure access, and compliance deadlines for state-level emissions zones.
- Diesel:Compression-ignition engines deliver sustained torque for long-haul and heavy-haul applications. Sleeper cab configurations along the I-35 corridor from Dallas-Fort Worth to Laredo sustain premium pricing for EPA-compliant model years.
- Gasoline:Spark-ignition powertrains dominate light-duty segments where acquisition cost sensitivity outweighs fuel economy.
- Electric:Battery-electric drivetrains are modularizing secondary market entry through remanufactured pack programs. California grocery distributors pilot refurbished Class 6 electrics for zero-emission zone compliance.
- Hybrid:Diesel-electric architectures qualify for IRA commercial vehicle incentives, improving total cost of ownership in stop-and-go urban routes.
Diesel retains dominant share; electric configurations show steepest expansion trajectory in last-mile and municipal fleet conversions.
Condition:
Buyer risk tolerance and financing access separate procurement tiers across fleet and independent operator segments.
- Certified Pre-Owned:Dealer inspection protocols with extended warranties reduce buyer uncertainty and unlock preferred financing terms. PACCAR and Volvo factory programs concentrate margin capture in the Midwest and Southeast.
- Refurbished:Factory-backed overhaul programs in Ohio and Indiana restore major components to specification. These units anchor regional distribution networks for fleet buyers demanding predictable operating cost structures.
- As-Is:Unwarranted transactions appeal to cash buyers with in-house maintenance capabilities.
- Salvage:Insurance-totaled chassis supply parts harvesting and export markets.
Certified Pre-Owned commands pricing premiums; Refurbished is climbing the fastest as factory programs expand geographic coverage.
Sales Channel:
Transaction velocity and geographic matching efficiency vary sharply across procurement modalities.
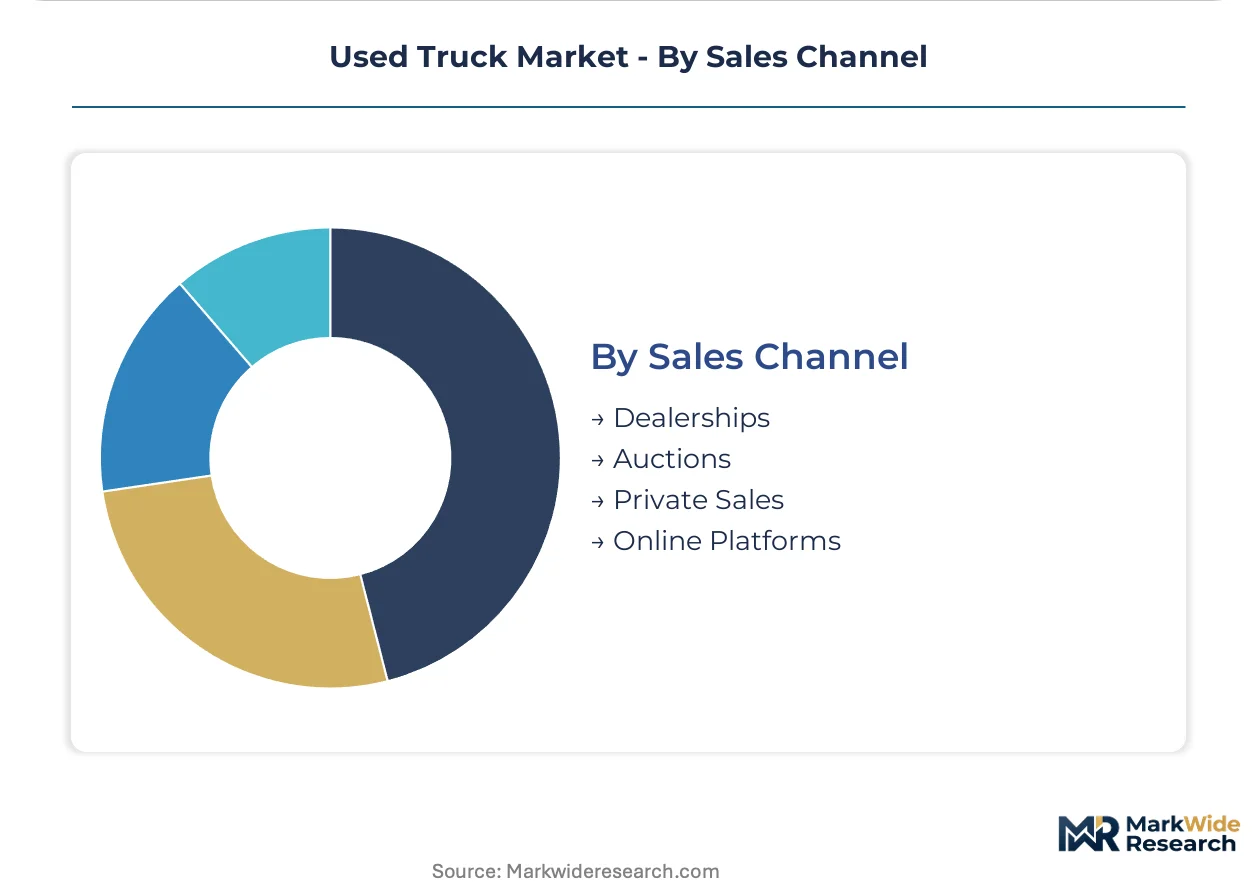
- Online Platforms:Digital remarketing tools compress transaction timelines from 45 days to under 14 days. Auction aggregators expand geographic matching between dispersed sellers and fleet buyers.
- Dealerships:Brick-and-mortar networks provide inspection access and financing facilitation for risk-averse buyers.
- Auctions:Physical and simulcast events concentrate liquidity for fleet turnover volumes.
- Private Sales:Direct transactions between operators bypass intermediary fees but carry documentation and title risk.
Dealerships retain volume leadership; Online Platforms are expanding most quickly as fleet buyers prioritize transaction speed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing used truck procurement across jurisdictions with divergent emissions compliance costs. Fleet operators migrate asset deployment toward states and countries with extended grandfathering provisions for pre-Phase 3 powertrains. This geographic sorting intensifies price dispersion for identical model years across border markets.
United States
Texas and the Great Lakes manufacturing corridor sustain the densest transaction velocity for sleeper cab configurations. EPA Phase 3 pre-buy activity concentrates in Dallas-Fort Worth and Laredo along the I-35 freight spine. Ohio and Indiana refurbishment centers anchor factory-backed distribution networks serving fleet buyers demanding predictable operating cost structures.
Germany
Commercial vehicle remarketing in Bavaria and Baden-Württemberg benefits from KBA type-approval harmonization across EU member states. The country's national transport regulator maintains strict periodic technical inspection protocols that elevate certified pre-owned pricing premiums. Stuttgart industrial clusters concentrate powertrain remanufacturing capacity for export to Eastern European logistics networks.
China
Dual carbon goals enforced by MEE are compressing residual value retention for pre-国六 diesel trucks in coastal provinces. Yangtze River Delta logistics operators accelerate procurement of used natural gas configurations ahead of stricter port emissions zones. Shandong Province heavy-duty assembly plants supply refurbished chassis to inland freight corridors with delayed compliance deadlines.
Mexico
Nuevo León and the Northern Border States absorb surplus US Class 8 inventory ineligible for California CARB registration. Cross-border fleet operators exploit EPA enforcement gaps to deploy pre-2010 powertrains on maquiladora supply routes. Mexico City Metro operators face accelerating replacement cycles as municipal zero-emission zone pilots expand.
Canada
Ontario and Quebec fleet buyers leverage currency differentials to source EPA-compliant used trucks from US auction channels. Transport Canada vehicle import regulations create documentation friction that independent dealers navigate for cross-border transactions. Alberta oilfield service demand sustains premium pricing for severe-duty chassis configurations.
Used Truck Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with OEM-certified programs commanding margin concentration in fleet procurement while independent dealers capture price-sensitive owner-operator volume. Market structure tilts toward consolidation at the premium tier, where factory-backed inspection protocols and extended warranty terms create switching costs. Three archetypes dominate: vertically integrated OEM remarketing divisions, regional refurbishment specialists with captive service networks, and digital auction aggregators compressing transaction timelines. Competitive dynamics center on geographic expansion of certified pre-owned coverage and technology licensing for telematics-enabled residual value forecasting.
Among European-based OEM remarketing operations, Volvo Group, Daimler Truck AG, and Scania AB exemplify the integrated archetype, each anchoring factory refurbishment programs that reduce buyer uncertainty through standardized inspection protocols and preferred financing access. These entities occupy positions where proprietary powertrain warranties and dealer network density create defensive moats against independent channel competition. Their geographic footprints concentrate in markets with stringent regulatory compliance windows, where certified pre-owned eligibility determines operational utility.
| Leading Market Players |
|---|
| Volvo Group |
| Daimler Truck AG |
| PACCAR Inc. |
| Navistar International Corporation |
| Scania AB |
| MAN Truck & Bus SE |
| Isuzu Motors Limited |
| Hino Motors, Ltd. |
| Penske Used Trucks |
| Others |
Supply Flow & Price Mechanics
Fleet procurement officers at large logistics networks command volume-based discounts that compress dealer margins while sustaining factory-certified premiums. This buyer concentration rewards tiered pricing structures that separate warranty-backed units from as-is transactions.
Pricing Analysis
Dealer markup layers rest on inspection protocol intensity and financing facilitation. Pricing stratifies across certified pre-owned, refurbished, and as-is tiers, with EPA compliance windows and telematics integration driving differentiation. Cost compression in independent refurbishment channels is intensifying because steel and aluminum input volatility squeezes margin buffers. Owner-operators exhibit acute price sensitivity, while pharmaceutical and cold-chain fleet buyers prioritize predictable operating cost structures over acquisition discounts.
Supply Chain Analysis
Steel and aluminum feedstock supply rests on mills concentrated in the United States, China, and Germany. Remanufactured powertrain components and battery-electric drivetrain modules draw from specialized facilities in Ohio, Indiana, and Michigan. Single-source vulnerability persists for advanced aftertreatment systems sourced from limited Tier 1 suppliers. Distribution runs through OEM-certified dealer networks, independent refurbishment centers, and digital auction aggregators serving dispersed fleet buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in used trucks stems from factory refurbishment programs capturing premium pricing through standardized warranty terms and reduced buyer uncertainty.
For Market Incumbents: Hedge regulatory fragmentation by diversifying certified pre-owned inventory across EPA Phase 3 and pre-Phase 3 compliance windows. Deepen backward integration into remanufactured powertrain production in Ohio and Indiana to defend against independent refurbishment margin erosion. Prioritize telematics-enabled residual value forecasting as a differentiation lever against digital auction aggregators. For New Entrants and Emerging Players: Digital remarketing platforms with AI-driven condition assessment represent the most penetrable technology wedge. Target last-mile electric truck refurbishment in California zero-emission zones where grocery and beverage distributors pilot Class 6 electrics. Pursue subscription-based maintenance bundling as the go-to-market angle for pharmaceutical and cold-chain operators in the Northeast corridor. For Investors and Strategic Acquirers: OEM remarketing divisions are the most active acquirer in this space, consolidating regional refurbishment specialists to extend geographic coverage. Long-term viability centers on factory-backed certification programs that create switching costs through proprietary powertrain warranties. Monitor EPA Phase 3 implementation velocity and CARB zero-emission zone expansion as the primary inflection signal for asset valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Factory Refurbishment Program Expansion | Volvo Group and PACCAR anchor Midwest distribution networks with standardized inspection protocols. |
| Digital Remarketing Platform Integration | Auction aggregators compress transaction timelines from 45 days to under 14 days for fleet turnover. |
| Telematics-Enabled Residual Value Forecasting | Data-driven asset visibility displaces nominal equipment age in fleet procurement decisions. |
| Subscription-Based Maintenance Bundling | Predictable operating cost structures attract pharmaceutical and cold-chain logistics operators. |
| Alternative Fuel Infrastructure Partnership | IRA grants enable CNG and hydrogen fueling investments along I-10 and I-40 corridors. |
Methodological Framework
Direct dialogue with fleet procurement managers, independent dealer principals, OEM remarketing executives, and aftermarket service directors grounded qualitative insights. Secondary validation drew from EPA enforcement records, NHTSA safety recall databases, FMCSA hours-of-service filings, and commercial vehicle registration data. Bottom-up transaction volume estimates and top-down market sizing triangulated through cross-reference with auction aggregator disclosures and OEM financial segment reporting.
Segment-level projections across truck type, fuel architecture, condition tier, and sales channel fed into analytical framework spanning the projection horizon. CAGRs were derived from regression against freight volume indices, fleet replacement cycle surveys, and regulatory compliance deadline clustering. Model inputs incorporated e-commerce fulfillment density metrics, IRA incentive uptake rates, and zero-emission zone expansion schedules.
The model holds under stable regulatory enforcement timelines and commodity input assumptions; deviation in EPA Phase 3 implementation velocity or steel price volatility would shift refurbishment margin and transaction velocity forecasts. Material deviation in CARB zero-emission zone geography or IRA incentive continuity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Commercial Truck Trailer Market
Commercial Vehicles
Middle East Vacuum Truck Market
Commercial Vehicles
Truck Market
Commercial Vehicles
United States Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Semi-Tractor Trailer Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Asia-Pacific Commercial Vehicles Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
Mini Truck Market