
 Spain Light Commercial Vehicles Market | 2026-2036
Spain Light Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Light Commercial Vehicles Market Analytics
The EU Green Deal is broadening the addressable market for zero-emission light commercial vehicles in Spain. Ford Motor Company leverages its Transit Electric lineup to anchor fleet contracts with municipal logistics operators. Volkswagen AG sustains engineering investment in modular electric platforms that span van and pickup derivatives. Stellantis competes across multiple price bands through its integrated Peugeot, Fiat, and Citroën brand architecture.
Spain light commercial vehicles span rigid-body and cab-chassis configurations with gross vehicle weights below 3.5 tonnes, purpose-built for urban freight distribution, tradesman mobility, and passenger shuttle services. Panel vans dominate unit volume due to standardized cargo volumes that align with European pallet dimensions and last-mile routing software. Electric powertrains represent the fastest-expanding fuel type segment as total cost of ownership parity approaches for high-utilization fleets. Diesel retains residual strength among construction firms and rural utility services where charging infrastructure remains sparse.
Spain's Dirección General de Tráfico enforces EURO 7 readiness timelines while the Instituto para la Diversificación y Ahorro de la Energía administers purchase incentives tied to domestic assembly content. The Ministry for the Ecological Transition coordinates low-emission zone mandates that now cover fifteen Spanish municipalities. Fleet operators and OEMs must monitor regulatory fragmentation between autonomous community enforcement standards and national homologation requirements.
Market Dynamics
Spain's Movilidad Sostenible framework is compressing diesel van residual values while accelerating fleet electrification timelines. Municipal low-emission zones now cover fifteen Spanish cities, forcing operators to front-load zero-emission procurement decisions ahead of total cost of ownership parity.
Growth Catalysts
- EURO 7 readiness timelines:The Dirección General de Tráfico enforces stricter emissions thresholds that push fleet operators toward electric powertrains earlier than depreciation cycles would otherwise allow.
- Last-mile delivery densification:E-commerce fulfillment networks in Madrid, Barcelona, and Valencia metropolitan corridors are standardizing on compact panel vans with standardized European pallet dimensions.
- IDAE purchase incentives:The Instituto para la Diversificación y Ahorro de la Energía ties subsidies to domestic assembly content, accelerating localized production commitments from multinational OEMs.
Market Restraints
- Charging infrastructure gaps:Rural utility services and construction firms in Extremadura and Castilla-La Mancha face sparse fast-charging networks that extend diesel dependency.
- Battery mineral supply concentration:Lithium and cobalt processing capacity concentrates in China, exposing Spanish fleet operators to input cost volatility and geopolitical supply interruptions.
- Grid capacity constraints:Distribution network operators in dense urban cores limit simultaneous fast-charging deployment, throttling depot electrification for large fleet operators.
Strategic Opportunities
- Andalusian logistics corridor:The Algeciras-Cádiz-Seville freight axis remains underpenetrated by electric van leasing networks, offering first-mover positioning for regional fleet-as-a-service providers.
- Vehicle-to-grid integration:Bidirectional charging technology convergence with smart meter infrastructure creates new revenue streams for fleet operators participating in demand-response markets.
- Autonomous community incentive stacking:Catalonia's complementary subsidies for zero-emission commercial vehicles layer atop national IDAE programs, improving payback periods for Barcelona-based operators.
Industry Challenges
- Homologation fragmentation:Autonomous community enforcement standards for low-emission zone access permits vary between Madrid's Distrito Central and Barcelona's ZBE, forcing OEMs to maintain multiple certification pathways.
- Technician skill gaps:High-voltage battery diagnostics and electric drivetrain repair require specialized training that Spain's vocational education system has not yet scaled to match fleet electrification velocity.
Report Scope
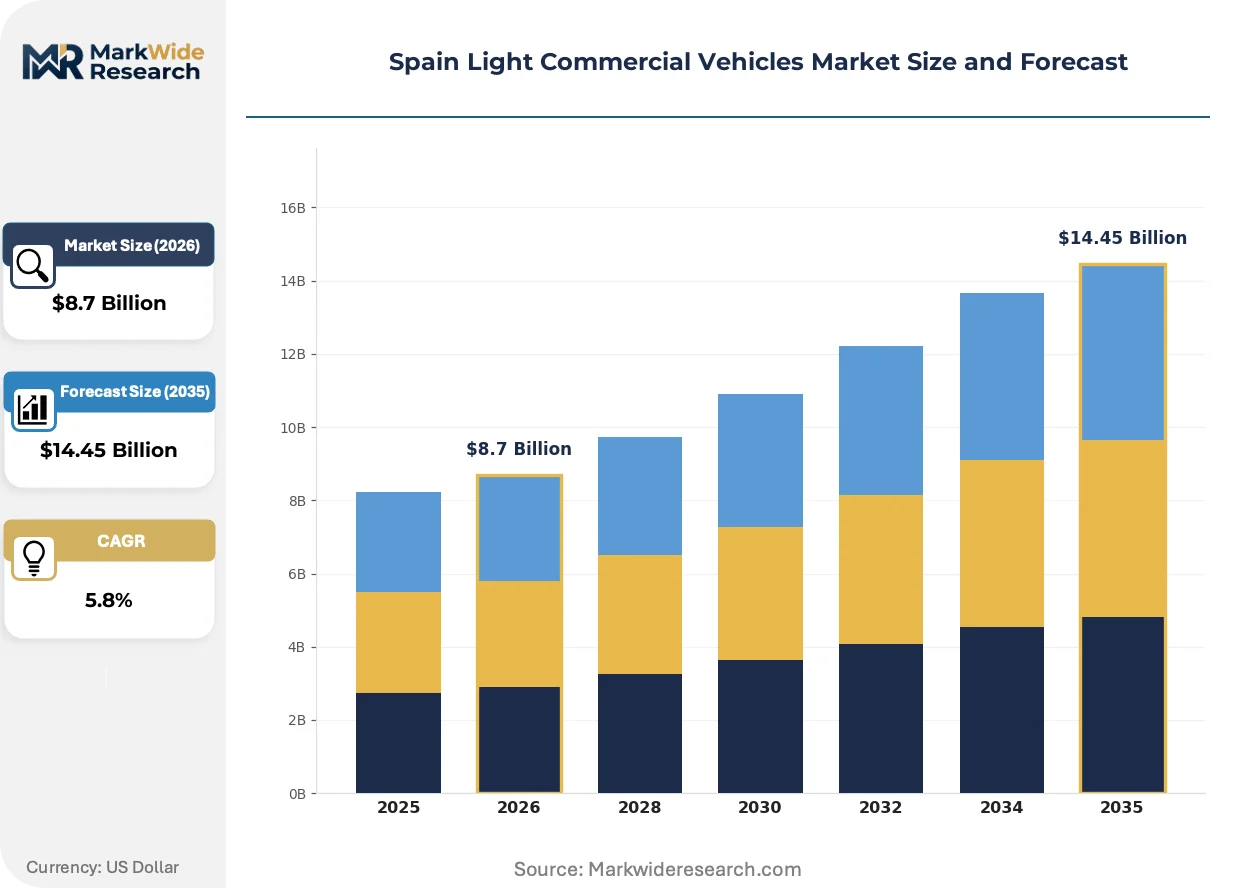
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Light Commercial Vehicles Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Panel Vans, Pickup Trucks, Minibuses, Chassis Cabs Fuel Type: Diesel, Petrol, Electric, Hybrid End User: Logistics Companies, Construction Firms, Delivery Services, Retail Businesses Application: Goods Transport, Passenger Transport, Utility Services, Emergency Services |
| Companies Covered | Ford Motor Company, Peugeot S.A., Volkswagen AG, IVECO S.p.A., Toyota Motor Corporation, Stellantis, Groupe Renault, Fiat Chrysler Automobiles N.V., Mercedes-Benz, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Light Commercial Vehicles Market Evolving Landscape
Powertrain electrification is rewriting fleet economics while modular platform architectures compress model development cycles. Regulatory mandates and buyer behavior are converging to accelerate technology substitution beyond historical automotive replacement patterns.
High-voltage battery packs with silicon-anode chemistries are extending electric van range toward diesel parity. Logistics operators running high-utilization routes in Madrid's metropolitan freight belt are piloting these configurations ahead of widespread availability. This energy density improvement is rewriting total cost of ownership calculations for urban delivery fleets previously constrained by range anxiety and mid-route charging downtime.
Spain's Ministry for the Ecological Transition coordinates low-emission zone mandates that now cover fifteen municipalities. Fleet operators must secure ZBE access permits that differentiate between temporary exemptions and permanent compliance pathways. Municipal logistics contracts in Valencia and Zaragoza now specify zero-emission vehicle percentages that exceed national averages, forcing accelerated procurement timelines.
Leasing structures are displacing outright purchase for electric van acquisition among small and mid-sized fleet operators. Traditional ownership models carry residual value risk that finance houses now absorb through guaranteed buyback programs. This shift concentrates most visibly among Barcelona-based tradesman fleets and last-mile delivery subcontractors serving Mercadona and Amazon fulfillment networks.
Spain Light Commercial Vehicles Market Segmentation
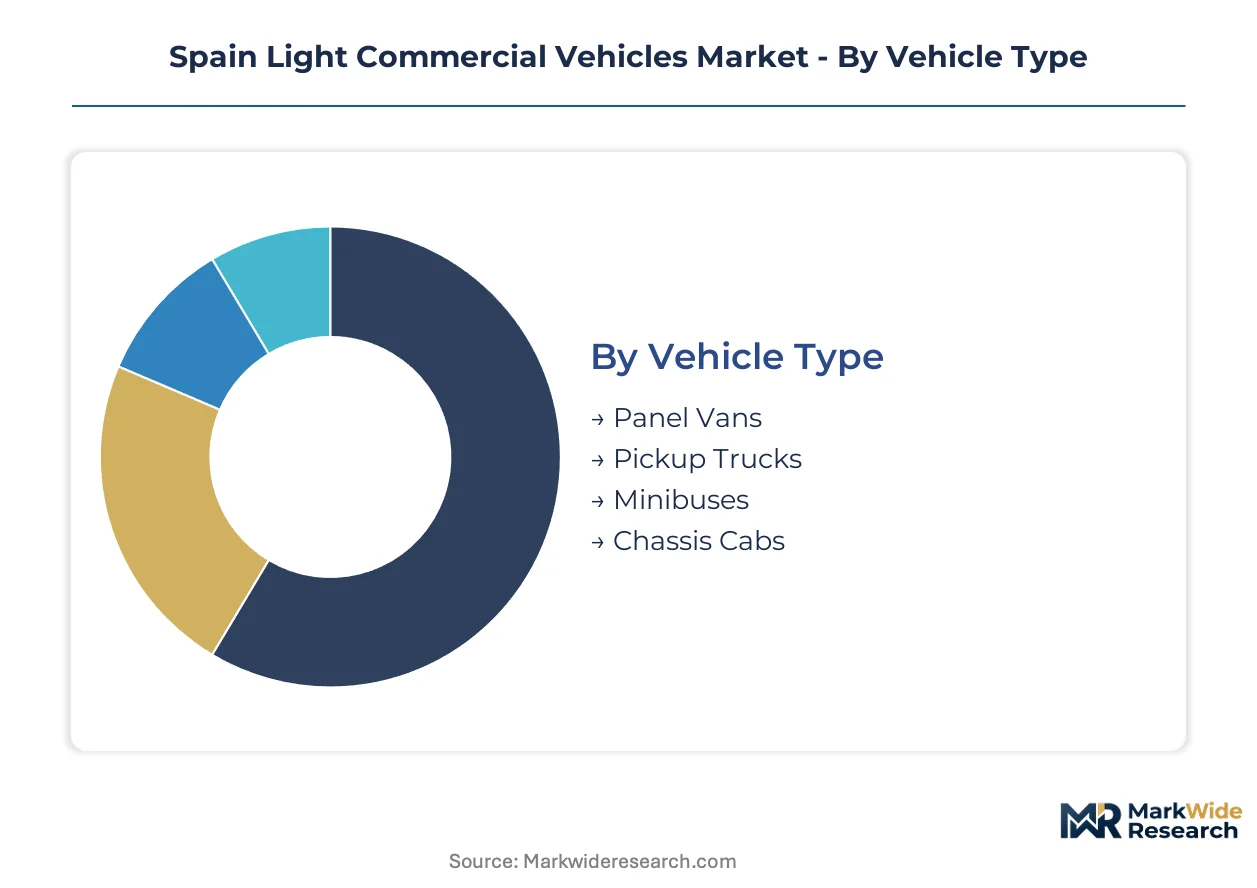
Light commercial vehicle procurement in Spain diverges sharply across buyer types, with fleet operators prioritizing total cost of ownership while tradesmen emphasize payload flexibility. Understanding these segment-specific decision criteria reveals where electrification timelines compress and where diesel dependency persists.
Vehicle Type:
Payload configuration and cargo accessibility separate buyers in this category, with urban logistics operators favoring enclosed bodies and rural contractors requiring open-bed versatility.
- Panel Vans:Enclosed rigid-body designs with standardized European pallet dimensions dominate Madrid and Barcelona last-mile fleets. E-commerce fulfillment networks in these metropolitan corridors are standardizing procurement around compact and medium variants to optimize routing software compatibility.
- Pickup Trucks:Open-bed configurations with cab-chassis flexibility serve construction firms and agricultural cooperatives across Extremadura and Castilla-La Mancha. Sparse charging infrastructure in these regions extends diesel powertrain dominance for this segment.
- Minibuses:Passenger-carrying derivatives with 9-16 seat configurations support corporate shuttle services and rural school transport contracts.
- Chassis Cabs:Incomplete vehicle platforms allow aftermarket bodybuilder customization for specialized utility applications including refrigerated distribution and mobile workshops.
Panel vans lead volumes today; electric variants in this segment are gaining share fastest as low-emission zone mandates tighten.
Fuel Type:
Operating cost structures and regulatory compliance timelines create distinct buyer segments, with high-utilization fleets calculating total cost of ownership differently than low-mileage operators.
- Electric:Battery-electric powertrains with lithium-ion packs are approaching parity for urban delivery routes exceeding 150 kilometers daily. IDAE purchase incentives tied to domestic assembly content accelerate procurement among Barcelona-based fleet operators serving Mercadona and Amazon networks.
- Diesel:Compression-ignition engines retain residual strength among construction firms and rural utility services where charging infrastructure remains sparse. EURO 7 readiness timelines enforced by Dirección General de Tráfico are compressing residual values and shortening replacement cycles.
- Hybrid:Mild and full-hybrid configurations bridge urban access requirements and range anxiety for mixed-route operators.
- Petrol:Spark-ignition engines serve low-mileage tradesman applications and secondary vehicle roles where capital constraints limit electric premium absorption.
Diesel retains the largest installed base; electric powertrains are climbing the fastest as total cost of ownership parity approaches for high-utilization fleets.
End User:
Fleet scale and contract visibility determine procurement financing structures, with large operators leveraging leasing instruments while small businesses absorb residual value risk.
- Logistics Companies:National and regional parcel carriers with centralized fleet management are front-loading zero-emission procurement ahead of Movilidad Sostenible compliance deadlines. These operators pilot silicon-anode battery configurations in Madrid's metropolitan freight belt to extend range toward diesel parity.
- Delivery Services:Last-mile subcontractors and food delivery platforms prioritize compact panel vans with rapid turnaround requirements.
- Construction Firms:Site-based contractors in Andalusia and Galicia emphasize payload capacity and all-terrain capability over emissions compliance.
- Retail Businesses:Independent merchants and franchise operators balance brand image requirements with capital constraints in vehicle selection.
Logistics companies lead procurement volumes today; delivery services are expanding most quickly as e-commerce densification accelerates.
Application:
Regulatory access privileges and duty cycle intensity shape technology selection, with urban applications facing stricter low-emission zone requirements than rural counterparts.
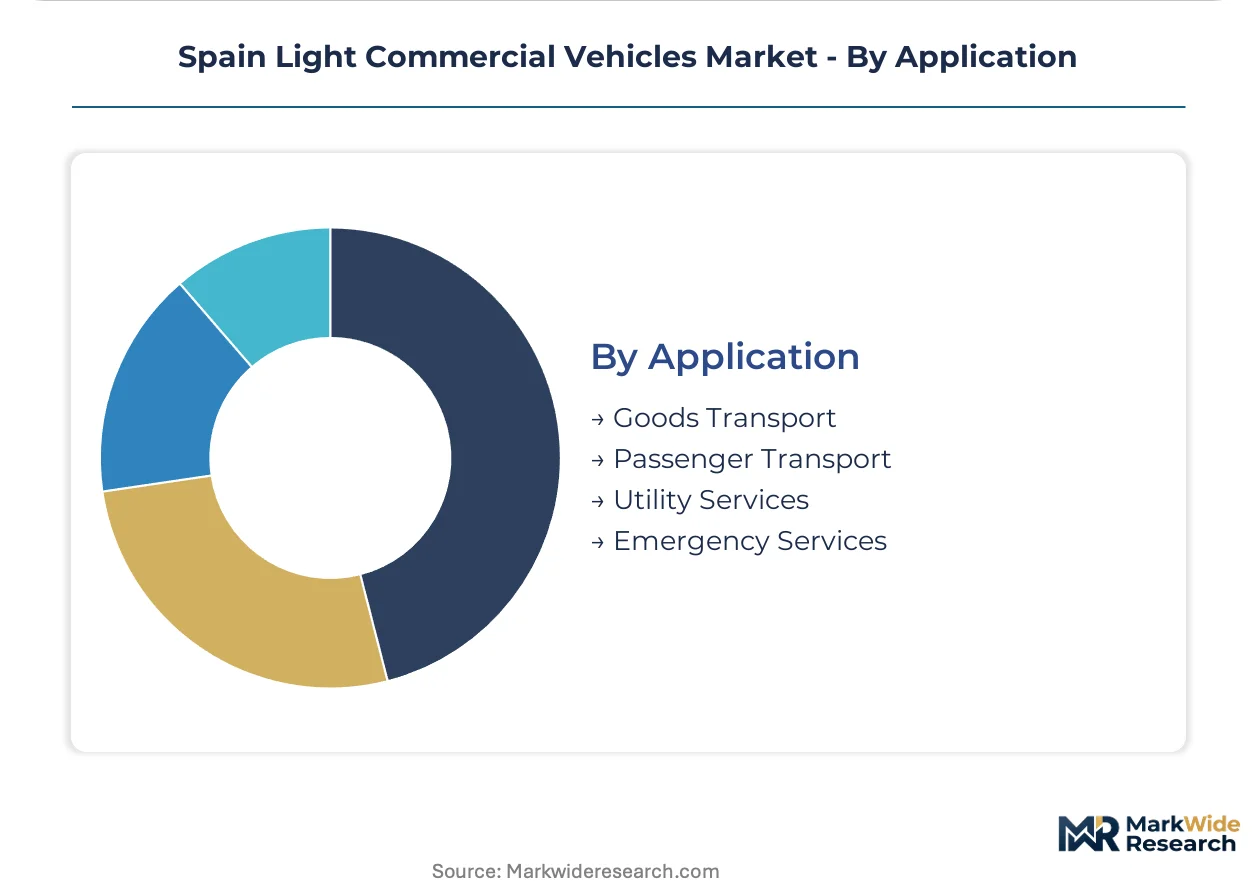
- Goods Transport:Freight distribution across Madrid, Barcelona, and Valencia metropolitan corridors now faces congestion charging and ZBE permit requirements. Municipal logistics contracts in these cities specify zero-emission vehicle percentages that exceed national averages.
- Passenger Transport:Shuttle services and accessible transport providers must comply with autonomous community accessibility standards that vary between Catalonia and Madrid.
- Utility Services:Grid maintenance and telecommunications fleets operate across urban-rural boundaries, creating mixed-route electrification challenges.
- Emergency Services:Police, fire, and medical response vehicles require guaranteed availability that currently favors proven powertrain technologies.
Goods transport dominates unit demand today; utility services are seeing the steepest expansion trajectory as infrastructure maintenance contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's light commercial vehicle industry traces its modern foundations to the 1950s-1970s when SEAT and foreign assembly operations established manufacturing corridors around Barcelona and Madrid. These industrial clusters matured into today's electrification battlegrounds where regional policy fragmentation shapes fleet procurement decisions.
Madrid
Last-mile delivery densification and municipal logistics contracts drive panel van demand in Spain's capital. The Distrito Central low-emission zone enforces permanent compliance pathways that exclude most diesel vehicles from 2025. Ford's Transit Electric anchors fleet contracts with municipal operators in the metropolitan freight belt.
Catalonia
Barcelona-based tradesman fleets and Amazon fulfillment subcontractors prioritize compact electric vans with rapid turnaround specifications. Catalonia's complementary subsidies layer atop national IDAE programs, improving payback periods for zero-emission procurement. The ZBE low-emission zone mandates exceed national averages, forcing accelerated replacement timelines.
Andalusia
The Algeciras-Cádiz-Seville freight axis remains underpenetrated by electric van leasing networks despite expanding port logistics activity. Construction firms and agricultural cooperatives across Extremadura and Castilla-La Mancha extend diesel dependency due to sparse fast-charging infrastructure. Regional fleet-as-a-service providers see first-mover positioning opportunities.
Basque Country
Industrial component suppliers and machine tool logistics operators concentrate in Bilbao-San Sebastián corridors with high-utilization route profiles. The regional government coordinates vocational training programs for high-voltage battery diagnostics to address technician skill gaps. Silicon-anode battery pilots are rewriting total cost of ownership calculations for urban delivery fleets.
Valencia
Municipal logistics contracts specify zero-emission vehicle percentages exceeding national regulatory minimums. E-commerce fulfillment networks standardize procurement around medium panel vans optimized for European pallet dimensions. The port city's freight belt serves as a testbed for vehicle-to-grid integration with smart meter infrastructure.
Spain Light Commercial Vehicles Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Spain's light commercial vehicle market. The vendor base concentrates around integrated automotive groups with modular electric platforms and specialized van divisions with regional distribution partnerships. Three archetypes dominate: legacy OEMs with full-line electrification strategies, commercial-vehicle specialists with vocational bodybuilder networks, and Asian manufacturers with cost-optimized compact van offerings. Competitive moves center on strategic partnerships for charging infrastructure deployment and portfolio diversification into leasing services.
Within the legacy OEM tier, Ford Motor Company and Volkswagen AG exemplify divergent electrification approaches. Ford leverages its Transit Electric lineup to anchor municipal fleet contracts, while Volkswagen sustains engineering investment in modular electric platforms spanning van derivatives. Stellantis occupies a position across multiple price bands through its integrated brand architecture. Peugeot S.A. and Mercedes-Benz sit within the premium-commercial segment where leasing structures displace outright purchase among mid-sized fleet operators.
| Leading Market Players |
|---|
| Ford Motor Company |
| Peugeot S.A. |
| Volkswagen AG |
| IVECO S.p.A. |
| Toyota Motor Corporation |
| Stellantis |
| Groupe Renault |
| Fiat Chrysler Automobiles N.V. |
| Mercedes-Benz |
| Others |
Value Network & Pricing Analysis
High-voltage battery technician concentrations in the Basque Country feed labor-cost differentials that widen pricing spreads between premium electric van tiers and economy diesel alternatives. Catalonia's denser vocational training infrastructure compresses service-labor premiums for Barcelona-based fleet operators, while Extremadura's technician scarcity extends after-sales cost advantages to Madrid-proximate service networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Spain's light commercial vehicle procurement, with Ford, Mercedes-Benz, and Stellantis brands occupying distinct rungs. Price differentiation hinges on battery energy density certification and domestic assembly content qualifying for IDAE subsidies. Cost compression in economy diesel tiers is intensifying because EURO 7 readiness timelines compress residual values ahead of depreciation cycles. Small tradesman fleets in rural Castilla-La Mancha exhibit highest price sensitivity, while municipal logistics operators in Madrid's Distrito Central absorb premiums for zero-emission compliance.
Supply Chain Analysis
Lithium-ion cell supply rests on Chinese, South Korean, and Japanese cathode and electrolyte specialists, with Spanish pack assembly concentrated in Vitoria-Gasteiz and Martorell facilities. Raw material dependencies span lithium carbonate from Chilean salares, cobalt hydroxide from the DRC, and copper foil from German rolling mills. Single-source vulnerability concentrates in Chinese graphite anode processing, exposing Spanish OEMs to geopolitical supply interruptions. Distribution runs through Madrid and Barcelona hub-and-spoke networks serving regional fleet leasing partners and municipal procurement offices.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's light commercial vehicle market functions as a geographic-arbitrage play between Catalonia's stacked incentive regimes and Andalusia's underpenetrated leasing infrastructure. The cost differential between Barcelona's ZBE-mandated accelerated procurement and Seville's diesel-extended replacement cycles creates divergent margin profiles across the Iberian Peninsula.
For Market Incumbents: Anchor fleet-as-a-service offerings in Madrid and Barcelona metropolitan corridors where municipal logistics contracts specify zero-emission percentages. Secure backward integration into battery pack assembly through partnerships with Basque Country vocational training pipelines. Defend against Asian manufacturer cost-optimized compact van entrants by locking multi-year leasing structures with Mercadona and Amazon fulfillment subcontractors.
For New Entrants and Emerging Players: Enter via the Algeciras-Cádiz-Seville freight axis, where electric van leasing networks remain sparse despite expanding port logistics activity. Target agricultural cooperatives and construction firms across Extremadura with hybrid bridge products addressing charging infrastructure gaps. Pursue fleet-as-a-service partnerships with regional distributors rather than direct OEM competition.
For Investors and Strategic Acquirers: Charging infrastructure operators are the most active acquirer in this space, consolidating depot electrification and public fast-charging assets ahead of grid capacity constraints. Long-term viability hinges on vehicle-to-grid revenue stream maturation and silicon-anode battery cost curves. Watch IDAE incentive renewal trajectories and autonomous community subsidy stacking permissibility as inflection indicators for fleet electrification velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell volumes from South Korean producers for Vitoria-Gasteiz assembly. |
| Charging Infrastructure Partnership | Deploys depot fast-charging with Iberdrola grid operators in Madrid's metropolitan freight belt. |
| Platform Standardization | Consolidates Ford Transit Electric variants across municipal and commercial fleet specifications. |
| Geographic Manufacturing Footprint | Expands Martorell electric van output to satisfy IDAE domestic content requirements. |
| Software-Defined Vehicle Investment | Integrates routing optimization with Barcelona low-emission zone permit compliance systems. |
Research Methodology
Multiple input streams — OEM platform engineering disclosures, fleet operator procurement records, and IDAE incentive administration data — were reconciled through bottom-up and top-down triangulation. Primary interviews with municipal logistics contract managers, aftermarket service technicians, and leasing company portfolio directors informed utilization assumptions and replacement cycle compression factors. Secondary validation drew from Dirección General de Tráfico registration databases, EURO 7 regulatory filings, and autonomous community low-emission zone permit issuance records.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeling spanning vehicle type, fuel architecture, end-user scale, and metropolitan corridor regulatory intensity. CAGRs were derived from fleet penetration curves calibrated to Movilidad Sostenible compliance deadlines and total cost of ownership parity trajectories. Forecast inputs incorporated silicon-anode battery energy density improvements and grid capacity constraint timelines from distribution network operator disclosures.
The model holds under sustained IDAE incentive levels and EURO 7 enforcement consistency; deviation in battery mineral supply interruptions or autonomous community regulatory fragmentation would shift electrification velocity assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Compact Utility Vehicles Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Van Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Automated Truck Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
Service Truck Market
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
Electric Truck Chassis Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Global Timber Trailer Market
Commercial Vehicles
France Light Commercial Vehicles Market