
 Three-Wheeler Market | 2026-2036
Three-Wheeler Market Size, Share, and Industry Trends Forecast 2026-2036
Three-Wheeler Market Intelligence
India is tilting toward expanded electric three-wheeler capacity with state-level EV policies supporting domestic manufacturing scale. Bajaj Auto Limited leverages its petrol-engine heritage while building out electric platforms for urban passenger routes. TVS Motor Company Limited anchors its position through integrated powertrain R&D and southern India dealership density. Mahindra & Mahindra Limited dominates the cargo segment with rugged chassis designs purpose-built for rural logistics.
A three-wheeler is a motorized vehicle with one front steering wheel and two rear drive wheels, typically powered by internal combustion engines up to 600cc or electric motors ranging 3-10 kW, designed for low-speed urban and semi-urban transport of passengers or goods. Its primary commercial purpose centers on affordable last-mile connectivity and small-load logistics where four-wheel vehicle economics prove excessive. Passenger and cargo vehicle types command the volume base, though electric fuel type variants are capturing disproportionate investment attention as battery costs decline and charging infrastructure spreads. E-commerce end users now represent the fastest-growing demand pool, with dedicated delivery segments pulling specialized load-deck configurations and telematics integration from manufacturers.
India's Ministry of Road Transport and Highways enforces AIS-145 safety standards for electric three-wheelers, while the Central Electricity Authority regulates battery-swapping station grid integration under EV charging guidelines. Europe's REACH and RoHS frameworks constrain material composition for any export-oriented Indian or Chinese manufacturer targeting EU-adjacent markets. Stakeholders must monitor how India's BIS certification evolution for lithium-ion packs intersects with state-level EV subsidy durability to calibrate capacity commitments and supplier qualification timelines.
Market Dynamics
India's PLI scheme for automotive manufacturing is collapsing the cost gap between imported and domestically produced battery cells, forcing fleet operators to accelerate electrification timelines and reshaping supplier qualification criteria across South Asian manufacturing corridors.
Growth Catalysts
- India's Production-Linked Incentive scheme:The PLI scheme accelerates localized lithium-ion cell and motor production, reducing import dependency for electric powertrain components.
- E-commerce logistics fleets:Dedicated delivery segments in Indian urban corridors are pulling specialized load-deck configurations with integrated telematics from original equipment manufacturers.
- Last-mile connectivity gaps:Persistent infrastructure deficits in South Asian semi-urban zones sustain demand for affordable passenger three-wheelers as primary mobility solutions.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings compress margin visibility for battery pack assemblers and deter long-term fleet procurement commitments.
- Charging infrastructure concentration:Grid integration bottlenecks in secondary Indian cities limit operational radius for electric cargo variants serving rural logistics routes.
- Internal combustion engine substitution pressure:Compressed natural gas retrofits and two-wheeler delivery expansion threaten petrol three-wheeler demand in cost-sensitive segments.
Strategic Opportunities
- Battery-swapping station networks:India's Central Electricity Authority grid integration guidelines enable asset-light fleet models that eliminate overnight charging downtime.
- Rural logistics specialization:Rugged chassis designs purpose-built for unpaved road conditions address cargo transport gaps in India's hinterland districts.
- Telematics-integrated fleet management:Convergence of GPS tracking with load sensors creates subscription revenue streams from e-commerce logistics operators.
Industry Challenges
- Power electronics engineering talent scarcity:Motor controller and battery management system design capabilities concentrate in southern Indian technology clusters, constraining nationwide manufacturing scale.
- AIS-145 certification timelines:India's Ministry of Road Transport and Highways safety testing protocols create six-to-nine month approval delays for new electric platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Three-Wheeler Market |
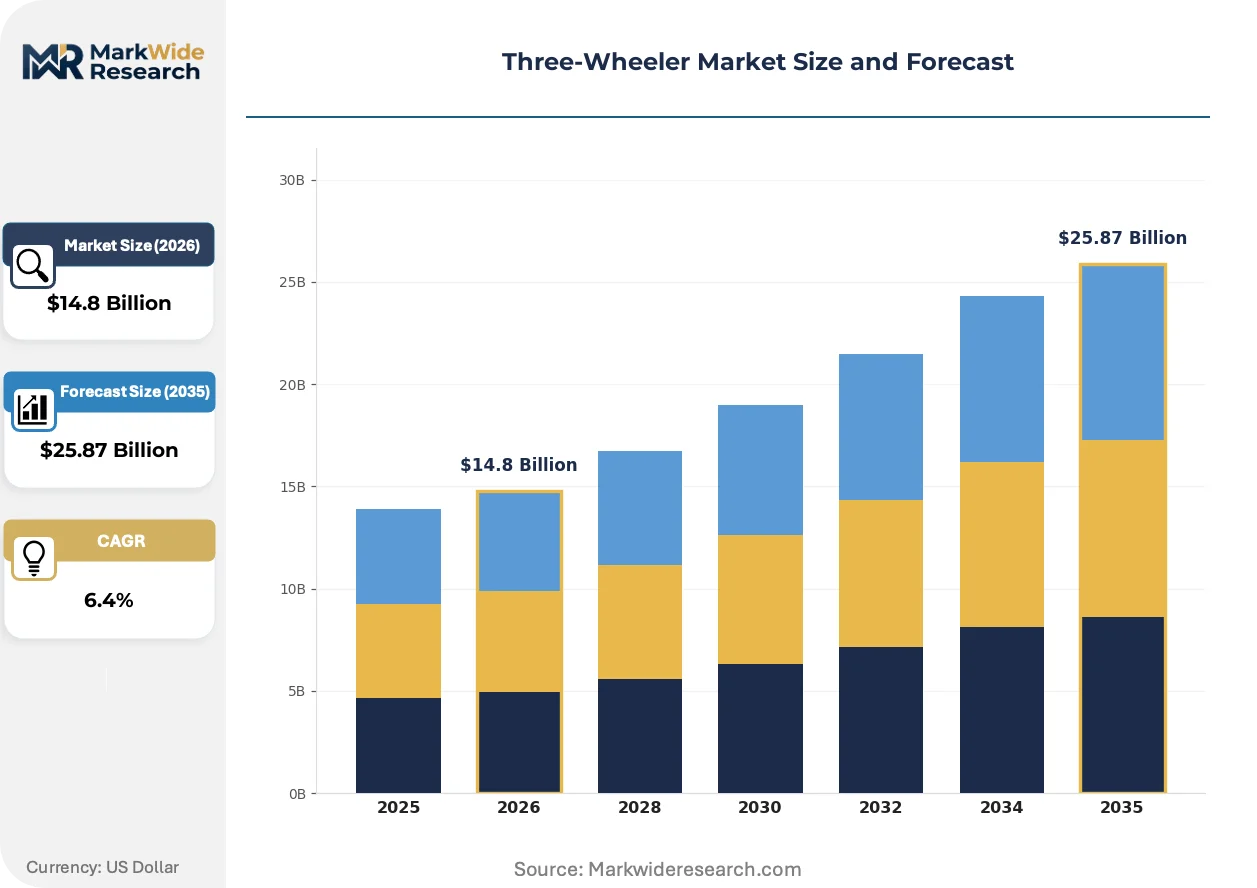
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger, Cargo, Auto Rickshaw, Delivery Fuel Type: Petrol, Diesel, Electric, LPG End User: Logistics, Personal Transport, Public Transport, E-commerce Usage Purpose: Goods Transportation, Passenger Transport, Utility Services, Tourism |
| Companies Covered | Mahindra & Mahindra Limited, Chongqing Zongshen Vehicle Co., Ltd., Bajaj Auto Limited, Lohia Auto Industries, Terra Motors Corporation, Piaggio & C. S.p.A., Atul Auto Limited, Yadea Group Holdings Ltd, TVS Motor Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Three-Wheeler Market Strategic Shifts & Innovations
Powertrain electrification is compressing product development cycles while digital integration redefines fleet ownership economics. Three concurrent shifts are restructuring competitive capabilities and procurement criteria.
Lithium iron phosphate battery chemistry is collapsing the total cost of ownership differential against lead-acid alternatives in Indian cargo applications. E-commerce logistics operators are specifying LFP packs for their thermal stability and cycle life advantages. This chemistry migration is enabling longer warranty terms that reshape fleet financing structures.
India's BIS certification evolution for lithium-ion packs is tightening cell-to-pack traceability requirements. The standard mandates thermal runaway propagation testing that eliminates uncertified imports from supplier shortlists. Domestic pack assemblers with in-house testing facilities are capturing preferred vendor status from national fleet operators.
Fleet procurement is consolidating around operating lease models that bundle vehicles, batteries, and maintenance into per-kilometer contracts. This shift transfers residual value risk from logistics operators to manufacturers and their captive finance arms. The model is spreading fastest in Maharashtra and Karnataka where state EV policies subsidize commercial electrification.
Three-Wheeler Market Segmentation
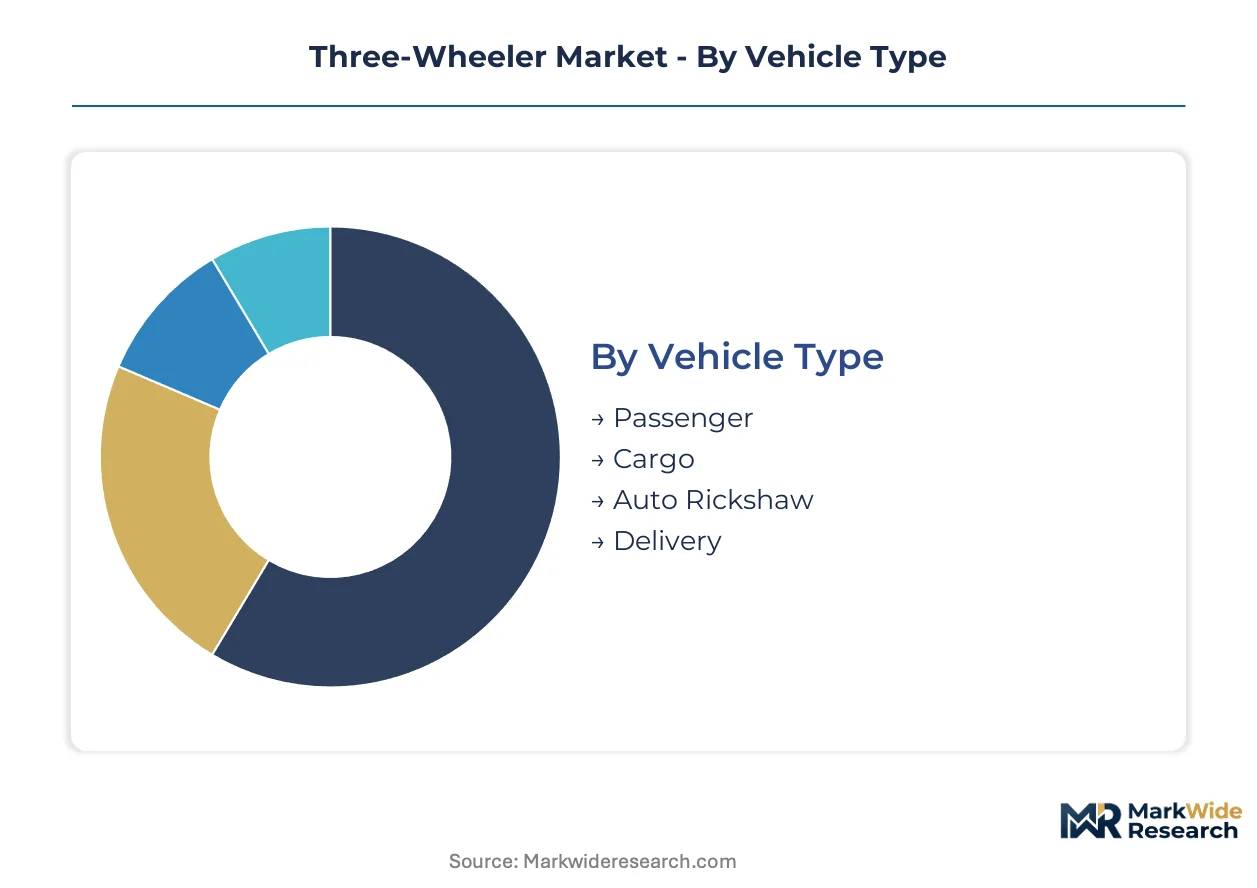
Segmentation in the three-wheeler market dictates powertrain specifications, chassis durability requirements, and service network density. Fleet operators and individual buyers diverge sharply on total cost of ownership calculations, forcing manufacturers to maintain parallel product architectures.
Vehicle Type:
After-sales service intensity varies dramatically across vehicle types, with commercial cargo units requiring three times the maintenance touchpoints of passenger variants over their operational lifespan.
- Passenger:Configured with bench seating for 3-4 occupants and weather protection canopies. Urban corridors in Maharashtra and Karnataka concentrate demand as state EV policies subsidize commercial electrification of shared mobility fleets.
- Cargo:Open or enclosed load decks rated for 300-600 kg payloads with reinforced ladder-frame chassis. E-commerce logistics operators in Delhi-NCR and Bengaluru specify integrated telematics and LFP battery packs for thermal stability during intensive duty cycles.
- Auto Rickshaw:Compact wheelbase design optimized for narrow urban lanes with side-entry passenger doors. Mumbai and Chennai municipal regulations mandate CNG or electric powertrains for new registrations.
- Delivery:Purpose-built variants with modular load-deck configurations and GPS tracking integration. Last-mile operators from Flipkart and Amazon India are pulling specialized specifications with rapid battery-swapping compatibility.
Passenger vehicles hold the largest share; momentum sits with Delivery variants as e-commerce fulfillment networks expand into secondary cities.
Fuel Type:
Cost tier stratification separates premium electric platforms from economy petrol models, with diesel occupying a narrowing commercial niche as CNG retrofits capture cost-sensitive operators.
- Petrol:Carbureted or fuel-injected engines up to 600cc displacement dominating rural markets with limited charging infrastructure. Bajaj Auto maintains production scale for hinterland districts where upfront electric premiums deter adoption.
- Diesel:Compression-ignition variants above 400cc for heavy cargo applications requiring sustained torque. Declining share in Delhi and Mumbai as air quality regulations tighten commercial vehicle emissions standards.
- Electric:Hub-mounted or mid-drive motors ranging 3-10 kW with lithium-ion battery packs. PLI scheme incentives are collapsing cell import costs, enabling Mahindra & Mahindra to localize powertrain assembly at its Bengaluru facility.
- LPG:Bi-fuel conversions and factory-fitted systems offering operating cost advantages over petrol. Gujarat and Rajasthan fleet operators favor LPG for inter-city cargo routes where electric range remains insufficient.
Petrol retains volume leadership; electric platforms are gaining share fastest as battery costs decline and swapping infrastructure spreads.
End User:
Application-specific durability requirements separate logistics fleets demanding 150,000 km warranties from personal transport buyers prioritizing low acquisition cost over service intervals.
- Logistics:Fleet operators managing 50+ unit deployments with centralized maintenance contracts. Delhivery and Shadowfax are consolidating procurement around operating lease models that bundle vehicles, batteries, and telematics subscriptions.
- Personal Transport:Individual owner-operators in semi-urban towns using vehicles for mixed passenger and light cargo duties. Uttar Pradesh and Bihar concentrate demand for affordable petrol variants with minimal electronic complexity.
- Public Transport:Municipal permits and route associations governing shared auto services. Chennai and Hyderabad transport corporations are piloting electric fleet conversions with dedicated charging depots.
- E-commerce:Dedicated delivery segments with SLA-driven performance requirements. Amazon India's I Have Space program is pulling standardized load-deck dimensions and real-time tracking integration from OEM specification sheets.
Logistics commands the largest end-user segment; e-commerce represents the steepest expansion trajectory as fulfillment networks penetrate Tier-3 towns.
Usage Purpose:
Supply concentration in chassis manufacturing clusters near Pune and Chennai shapes regional specialization, with goods transportation variants demanding heavier gauge steel fabrication than passenger configurations.
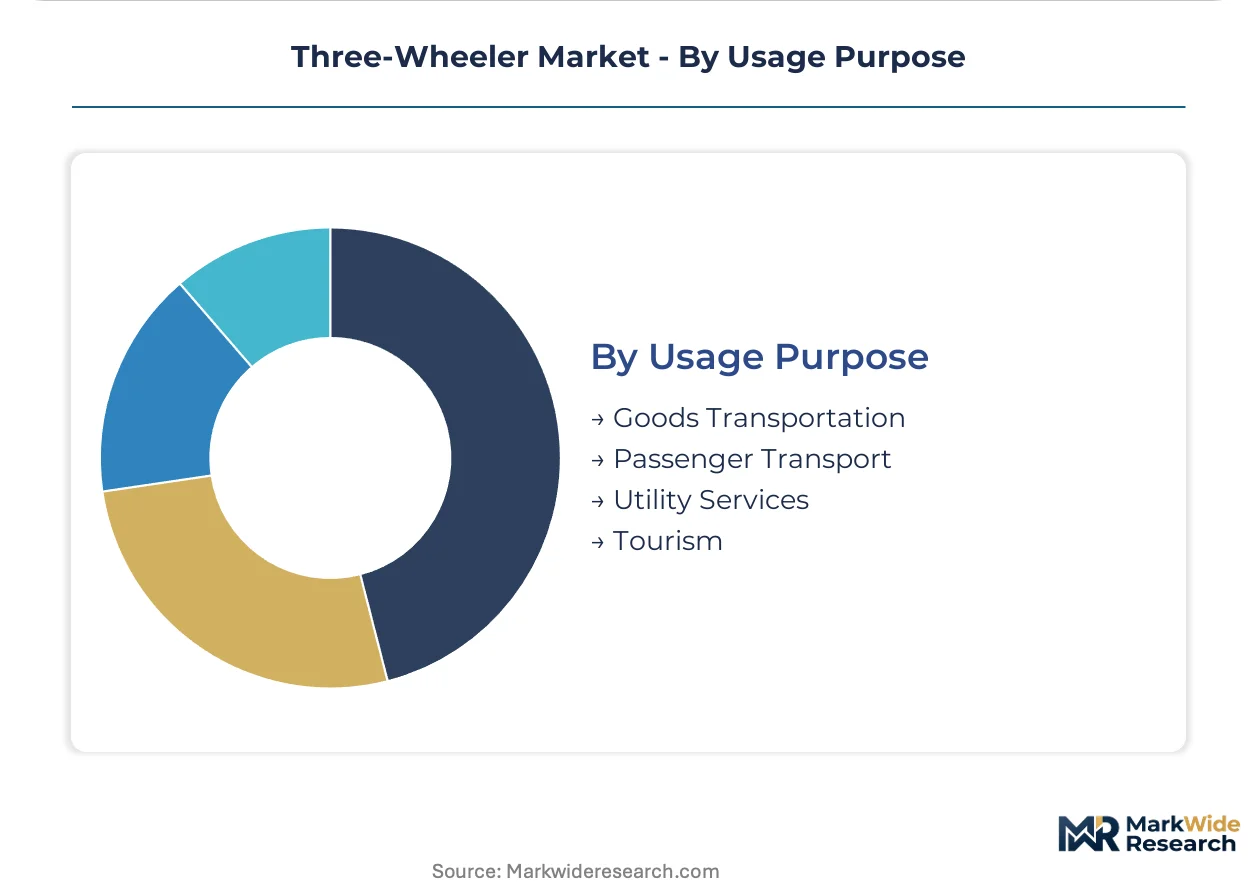
- Goods Transportation:Reinforced suspension systems and high-torque powertrains for unpaved road conditions. Rural logistics corridors in Madhya Pradesh and Odisha sustain demand for ruggedized cargo platforms with extended warranty terms.
- Passenger Transport:Optimized seating ergonomics and noise dampening for urban shared mobility. Bengaluru and Hyderabad metro feeder routes are electrifying three-wheeler connections to address last-mile gaps.
- Utility Services:Mobile workshop and vending configurations with auxiliary power take-offs. Municipal corporations in Ahmedabad and Surat procure specialized variants for street maintenance and waste collection fleets.
- Tourism:Open-body designs with aesthetic customization for heritage city circuits. Jaipur and Udaipur operators specify enhanced comfort features for foreign visitor segments.
Goods Transportation dominates by volume; Utility Services are climbing the fastest as smart city infrastructure investments expand municipal fleet procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Ministry of Road Transport and Highways anchors the regulatory framework governing three-wheeler safety standards and electrification mandates across the world's largest market for these vehicles. PLI scheme incentives and state-level EV policies are redrawing manufacturing investment patterns. Geographic concentration varies sharply by powertrain type and end-use application.
India
E-commerce logistics fleets in Delhi-NCR and Bengaluru are pulling specialized electric cargo configurations with integrated telematics from original equipment manufacturers. The PLI scheme for automotive manufacturing accelerates localized lithium-ion cell and motor production, collapsing import dependency for powertrain components. Maharashtra and Karnataka state EV policies subsidize commercial electrification, concentrating fleet procurement in these corridors.
China
Domestic demand for electric three-wheelers in last-mile delivery and rural goods transport sustains massive production scale. MIIT regulations govern vehicle certification and new energy vehicle quotas that shape manufacturer portfolio decisions. Chongqing and Zhengzhou manufacturing clusters supply both domestic operators and export markets across Southeast Asia and Africa.
Indonesia
Urban passenger transport in Jakarta and Surabaya relies heavily on auto rickshaw variants for informal mobility services. The national government's electric vehicle roadmap sets conversion targets for public transport fleets without binding mandates. Manufacturing investment concentrates in Java-based assembly operations serving domestic demand and regional re-export.
Bangladesh
Compressed natural gas and electric three-wheelers compete for dominance in Dhaka's dense urban passenger corridors. The country's national energy regulator oversees CNG station licensing that indirectly shapes powertrain economics for fleet operators. Local assembly operations in Gazipur and Narayanganj supply cost-optimized variants for price-sensitive owner-operators.
Thailand
Tourism-driven demand for open-body passenger three-wheelers in Bangkok and Chiang Mai sustains a specialized manufacturing niche. The Board of Investment promotes EV production through tax incentives that attract regional headquarters functions. Eastern Economic Corridor industrial zones host component suppliers serving ASEAN-wide distribution networks.
Three-Wheeler Market Key Industry Players
Legacy two-wheeler manufacturers and dedicated three-wheeler specialists split the market between integrated powertrain platforms and purpose-built chassis architectures. Consolidation pressure concentrates among electric entrants seeking manufacturing scale against established internal combustion engine incumbents. Domestic champions and multinational subsidiaries represent the dominant archetypes, with regional specialists occupying niche export positions. Capacity expansion in battery pack assembly and strategic partnerships for swapping infrastructure constitute the primary competitive moves reshaping supplier relationships.
Among India-based conglomerates, Mahindra & Mahindra Limited and Bajaj Auto Limited exemplify the integrated automotive group archetype, leveraging existing dealership networks and captive finance operations to anchor fleet procurement decisions. TVS Motor Company Limited occupies a position within the southern India-focused specialist tier, while Chongqing Zongshen Vehicle Co., Ltd. represents the China-based scale manufacturer archetype serving export markets through cost-optimized production configurations.
| Leading Market Players |
|---|
| Mahindra & Mahindra Limited |
| Chongqing Zongshen Vehicle Co., Ltd. |
| Bajaj Auto Limited |
| Lohia Auto Industries |
| Terra Motors Corporation |
| Piaggio & C. S.p.A. |
| Atul Auto Limited |
| Yadea Group Holdings Ltd |
| TVS Motor Company Limited |
| Others |
Cost & Logistics Intelligence
Lithium carbonate price volatility compresses margin visibility for battery pack assemblers and forces tiered pricing spreads between certified domestic LFP packs and uncertified imported alternatives, while simultaneously concentrating supply chain investment around in-house cell testing facilities in southern Indian manufacturing corridors.
Pricing Analysis
Price spreads between Maharashtra-Karnataka fleet procurement corridors and Uttar Pradesh-Bihar owner-operator markets reach three-tier stratification across premium electric platforms with telematics bundling, standard CNG retrofits with warranty coverage, and economy petrol variants with minimal electronic complexity. Price differentiation rests on BIS certification grade for lithium-ion packs and volume scale of fleet lease contracts. Cost compression in economy petrol tiers intensifies as two-wheeler delivery expansion threatens substitution. E-commerce logistics operators exhibit lowest price sensitivity due to SLA-driven performance requirements; individual rural owner-operators remain most price-sensitive.
Supply Chain Analysis
Upstream lithium feedstock draws from Chilean and Australian extraction operations before concentrating in Chinese and South Korean cell manufacturing, with India's PLI scheme accelerating domestic pack assembly localization. Power electronics engineering talent scarcity constrains motor controller and battery management system production scale. Single-source vulnerability sits with concentrated lithium carbonate processing capacity. Distribution runs through captive finance arms of legacy OEMs and emerging battery-swapping station networks serving fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compressed natural gas retrofits and two-wheeler delivery expansion threaten petrol three-wheeler incumbents with substitution pressure that demands defensive capability building in electrified platforms and swapping infrastructure.
For Market Incumbents: Build switching-cost moats through captive battery-swapping station networks that lock fleet operators into per-kilometer lease ecosystems. Anchor procurement decisions by integrating telematics subscriptions with vehicle financing. Defend against emerging electric entrants by accelerating PLI-linked cell localization at southern Indian manufacturing clusters. Prioritize AIS-145 certification pipeline expansion to compress new platform approval timelines. For New Entrants and Emerging Players: Rural logistics corridors in Madhya Pradesh and Odisha with unpaved road conditions and limited charging infrastructure represent the most penetrable entry point for ruggedized cargo platforms with extended warranty terms. Battery-swapping compatibility specifications pulled by Delhivery and Shadowfax procurement teams create specification gaps that specialized chassis designers can exploit. Partner with state-level EV policy implementation cells in Maharashtra and Karnataka to secure fleet pilot allocations. For Investors and Strategic Acquirers: India's BIS certification evolution for lithium-ion packs reshapes the acquisition landscape toward domestic pack assemblers with in-house thermal runaway propagation testing facilities. Long-term viability over the projection horizon hinges on powertrain electrification scale and swapping infrastructure network effects. Target acquisition archetypes include southern Indian technology clusters with motor controller engineering capabilities. Monitor state EV subsidy durability announcements as the critical inflection signal for capacity commitment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures LFP cell volumes from PLI-qualified domestic assemblers for fleet scale deployment. |
| Charging Infrastructure Partnership | Enables grid-integrated swapping station networks under CEA guidelines for asset-light fleet models. |
| Platform Standardization | Reduces SKU complexity across passenger and cargo variants while accelerating AIS-145 certification cycles. |
| Software-Defined Vehicle Investment | Integrates GPS tracking with load sensors for subscription revenue from e-commerce logistics operators. |
| Geographic Manufacturing Footprint | Localizes powertrain assembly in Bengaluru and Pune corridors to capture state EV policy subsidies. |
Research Approach
Cross-validation between OEM platform engineering directors and e-commerce logistics fleet procurement managers anchors the qualitative findings on specification evolution and lease model adoption. Primary interviews with battery pack assembly technical leads, swapping station network operators, and state transport department EV policy cells combined with secondary validation against AIS-145 certification records, PLI scheme beneficiary disclosures, and CEA grid integration guidelines. Bottom-up triangulation across vehicle type and fuel type segmentation converged with top-down demand modeling from e-commerce fulfillment network expansion patterns.
Calibration against historical electrification adoption curves in comparable last-mile logistics markets refined the analytical framework across the analysis window. Segmentation dimensions modeled include vehicle type, fuel type, end user category, and usage purpose, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derived from production volume trajectories and fleet procurement pipeline disclosures. Industry-specific forecast inputs incorporated lithium carbonate price volatility scenarios and state EV subsidy durability assumptions.
Practitioners should monitor lithium carbonate spot price movements and state-level EV policy renewal announcements for early signals of margin compression or procurement acceleration. Forecasts reflect assumptions on PLI scheme continuation and swapping infrastructure rollout pace. Cross-checking against IHS Markit vehicle registration data and Delhivery public fleet disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Semi-Tractor Trailer Market
Commercial Vehicles
Europe Light Commercial Vehicle (LCV) Market
Commercial Vehicles
Van Market
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Tank Car Market
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Electric Truck Chassis Market
Commercial Vehicles
Iraq Trailer Market
Commercial Vehicles
India Commercial Vehicle (CV) Market