
 Commercial Vehicle Calibration Market | 2026-2036
Commercial Vehicle Calibration Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vehicle Calibration Market Analytics
Euro VI emission standards is pivoting the cost-of-entry calculus for calibration service providers across Europe. Robert Bosch GmbH leverages its embedded diagnostics ecosystem to anchor laboratory calibration workflows for heavy-duty fleets. Continental AG sustains R&D intensity in optical sensor alignment for autonomous commercial platforms. MAHLE GmbH competes through specialized dynamic calibration protocols that address thermal management in hybrid powertrains.
Commercial vehicle calibration encompasses the precise adjustment of sensor arrays, control modules, and propulsion management systems against manufacturer specifications using standardized reference equipment. The process requires sub-millimeter optical alignment tolerances and validated inertial measurement unit drift compensation to ensure safe operation of advanced driver-assistance systems on freight corridors. GPS technology leads current deployment volumes due to fleet telematics mandates, while acoustic calibration segments are expanding fastest as noise-emission enforcement tightens for urban delivery vehicles. OEM end users command the largest margin pools through captive service networks, though independent repair shops are capturing volume growth from aging commercial parc maintenance.
EMA's MDR framework and ECHA's REACH chemical restrictions shape material choices in calibration consumables and sensor housings across European markets. Germany's KBA enforces type-approval protocols that directly determine which calibration procedures qualify for regulatory compliance documentation. Stakeholders must monitor divergence between EU Green Deal decarbonization timelines and national enforcement capacities to anticipate where compliance investment will concentrate.
Market Dynamics
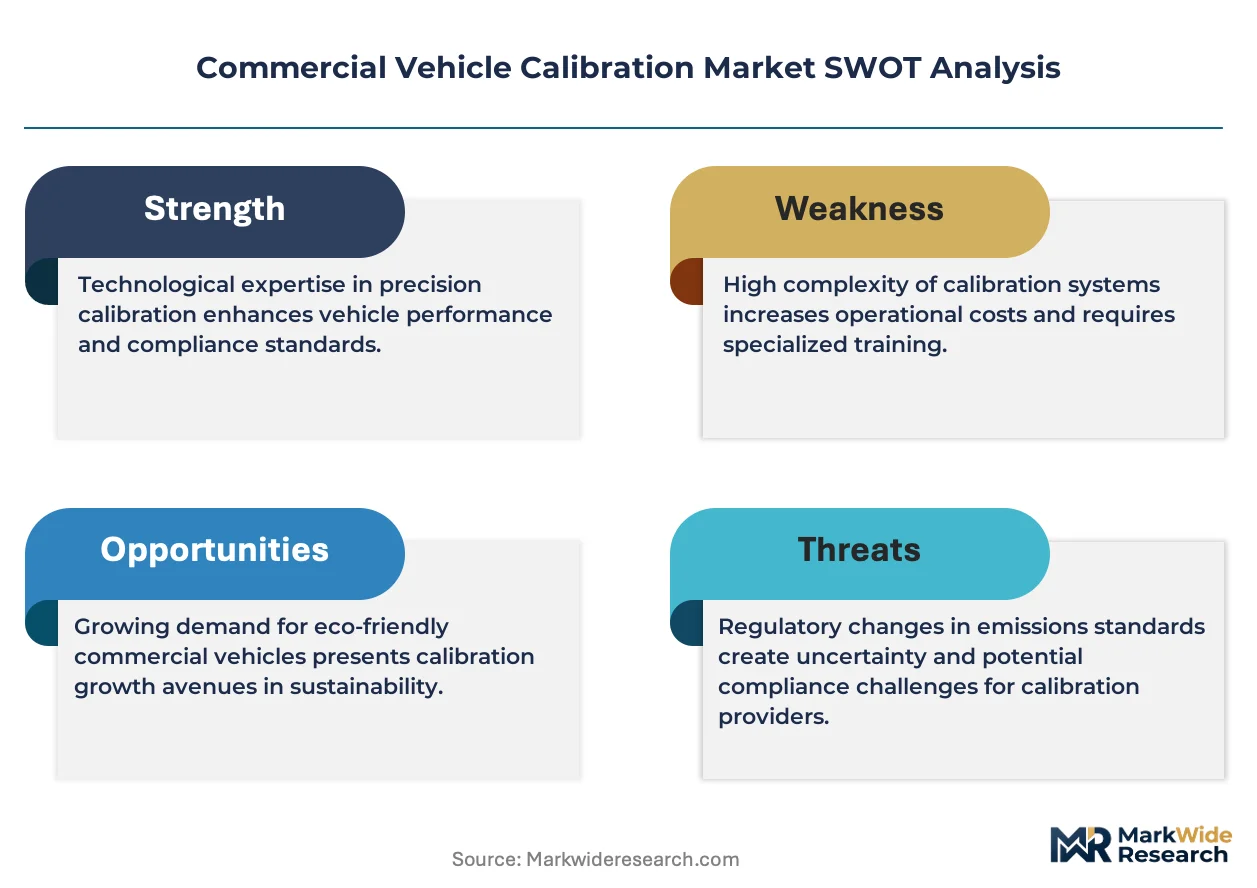
Fleet telematics mandates and autonomous freight corridor deployments are compressing calibration cycle times while multiplying sensor count per vehicle, forcing service networks to absorb capital-intensive optical alignment capabilities.
Growth Catalysts
- Euro VI emission norms:Germany's KBA enforces type-approval protocols that mandate periodic recalibration of NOx sensors and particulate matter monitors across heavy-duty parcs.
- Remote diagnostics mandates:European Commission regulations require real-time powertrain monitoring, embedding calibration validation within connected vehicle platforms.
- Autonomous freight corridors:Lidar and camera array deployments on Rotterdam-Genoa and Hamburg-Milan routes demand sub-millimeter optical alignment services.
Market Restraints
- Reference equipment concentration:German and Swiss metrology equipment suppliers control precision turntable and inertial platform supply, exposing calibration chains to single-source risk.
- Specialized technician scarcity:Optical sensor alignment requires certified expertise that vocational pipelines across Europe fail to replenish at replacement rates.
- Consumables cost volatility:ECHA REACH restrictions on rare-earth dopants in fiber-optic reference standards inflate consumable expenditures for acoustic calibration protocols.
Strategic Opportunities
- Poland and Czechia fleet expansion:Central European logistics hubs are densifying commercial vehicle parcs faster than calibration service coverage, creating white-space for mobile diagnostic units.
- Hydrogen powertrain calibration:Fuel cell thermal management sensors require dynamic calibration protocols that incumbent service networks have not yet standardized.
- EMA MDR framework alignment:Medical-device-grade calibration documentation is transferable to commercial vehicle safety-critical systems, opening premium service tiers.
Industry Challenges
- Multi-protocol integration complexity:SAE J1939, ISO 11783, and manufacturer-specific CAN bus implementations fragment diagnostic tool compatibility across mixed fleets.
- Certification timeline compression:EU AI Act safety documentation requirements for automated driving systems extend calibration validation cycles beyond current service bay throughput capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vehicle Calibration Market |
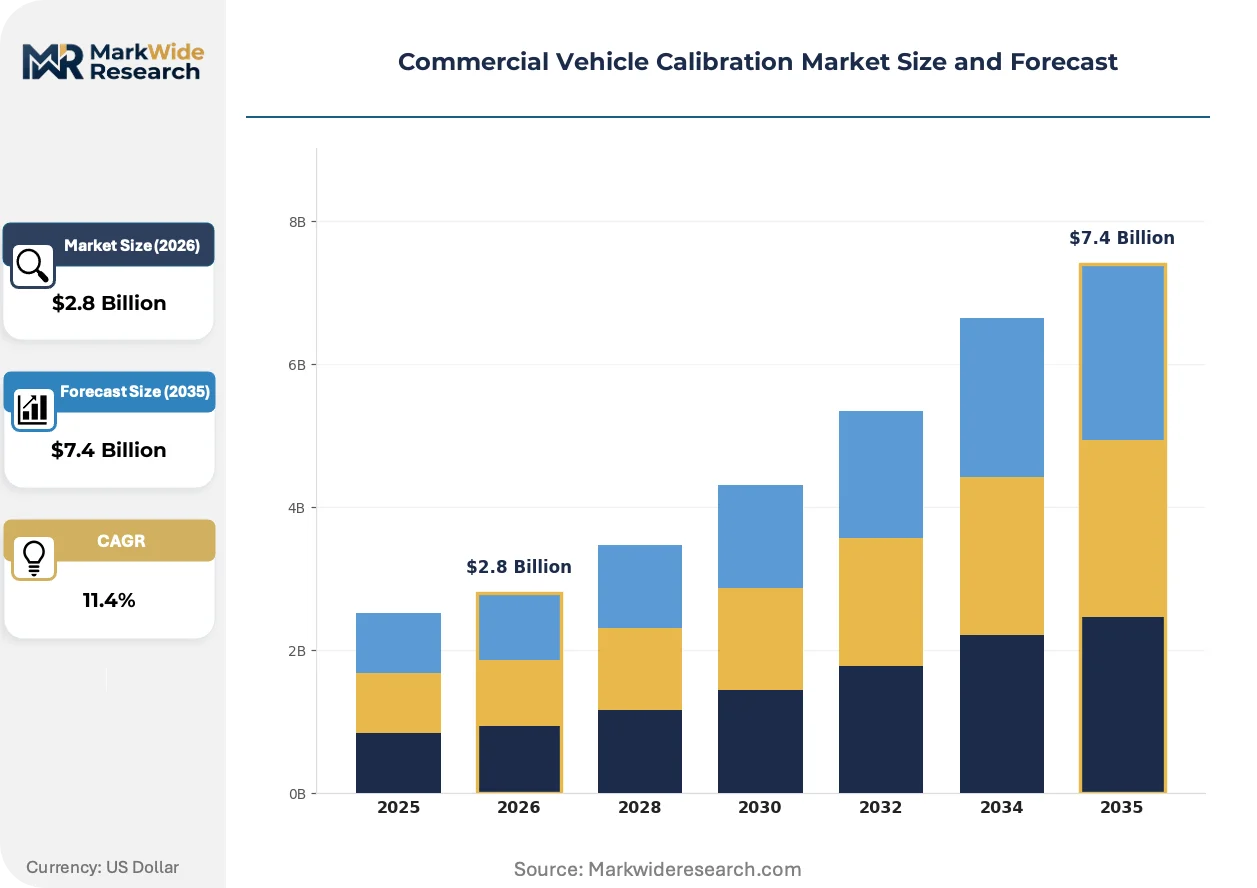
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, Optical, Acoustic, Inertial Calibration Type: Static, Dynamic, On-Road, Laboratory End User: OEMs, Fleet Operators, Repair Shops, Government Agencies Vehicle Type: Heavy-Duty, Light-Duty, Electric, Hybrid |
| Companies Covered | Robert Bosch GmbH, Continental AG, MAHLE GmbH, HELLA GmbH & Co. KGaA, Cojali S.L., MAHA Maschinenbau Haldenwang GmbH & Co. KG, Autel Intelligent Technology Corp., Ltd., AVL List GmbH, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vehicle Calibration Market Evolving Landscape
Calibration workflows are migrating from static laboratory environments to dynamic, in-field execution models. Three convergent developments are compressing equipment form factors while expanding sensor coverage requirements.
Over-the-air calibration platforms are consolidating control module parameter updates into centralized fleet management systems. Heavy-duty operators in Germany and the Netherlands are adopting cloud-based validation tools that eliminate depot visits for software-aligned sensors. This architecture is consolidating vendor relationships around telematics providers with embedded diagnostics ecosystems.
EU Green Deal decarbonization timelines are tightening enforcement windows for emission-related calibration documentation. France's ANSM and Germany's KBA are harmonizing type-approval test sequences that compress recertification intervals for hybrid powertrains. Urban delivery segments face the steepest compliance cost escalation as noise-emission protocols layer onto existing exhaust monitoring mandates.
Service unbundling is fragmenting procurement patterns across European fleet operators. Large logistics groups are separating diagnostic hardware ownership from calibration labor contracts, pressuring independent workshops to absorb capital risk on reference equipment. This bifurcation is most pronounced in Italy and Spain, where captive OEM networks have historically dominated safety-critical system maintenance.
Commercial Vehicle Calibration Market Segmentation
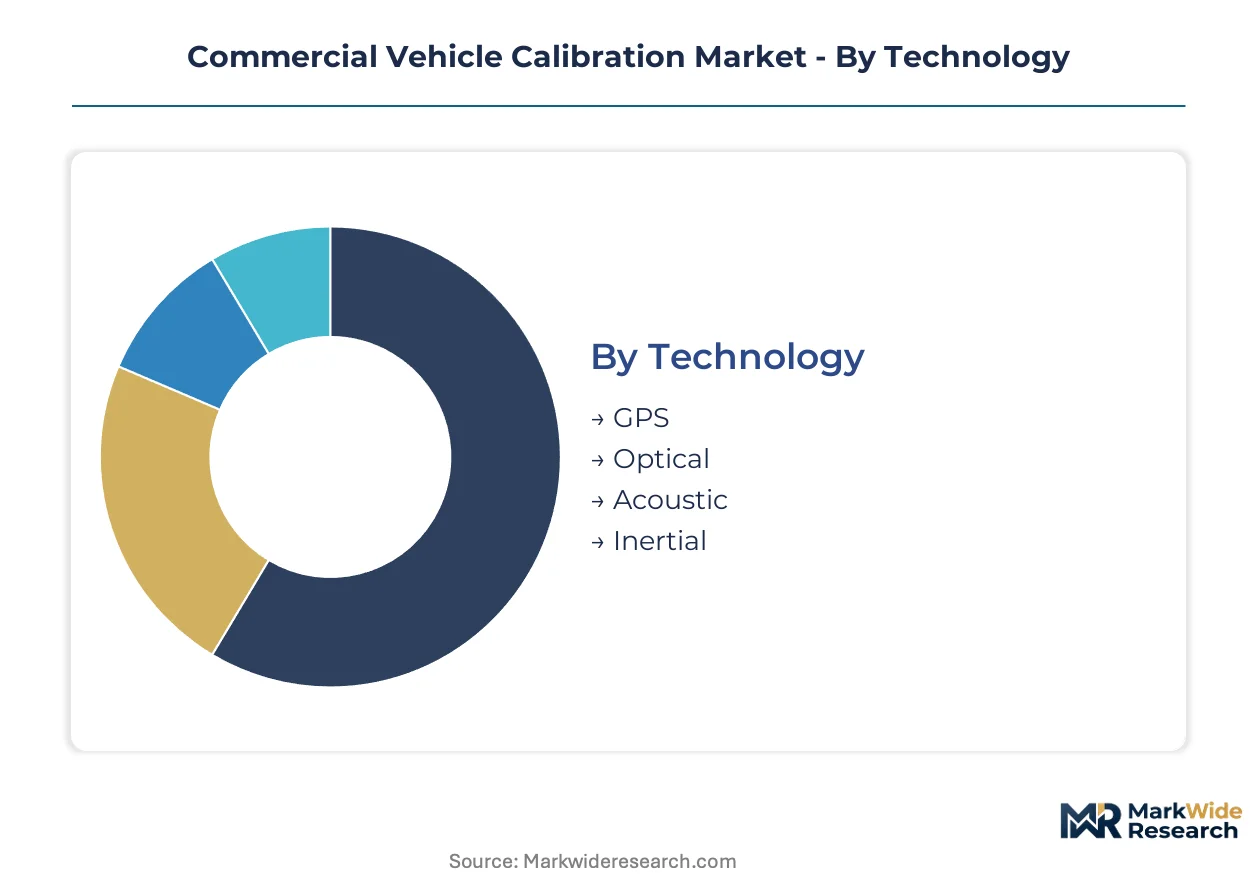
Calibration procurement patterns diverge sharply across technology platforms and service delivery models. Fleet operators prioritize mobile-capable solutions while OEMs anchor volume in laboratory protocols, creating distinct margin architectures within each segment cluster.
Technology:
Technology selection determines capital intensity and technician certification requirements for service providers.
- GPS:Satellite-based positioning calibration validates antenna alignment and signal processing against reference coordinates. Fleet telematics mandates in Germany and the Netherlands concentrate demand here, though commoditization pressure intensifies as receiver modules standardize.
- Optical:Lidar and camera array alignment demands sub-millimeter precision using calibrated target boards and structured light projection. Autonomous freight corridor deployments on Rotterdam-Genoa routes are accelerating optical service capacity expansion.
- Acoustic:Noise emission sensor validation for urban delivery compliance.
- Inertial:IMU drift compensation for stability control systems.
GPS leads volumes today; optical is gaining share fastest.
Calibration Type:
Service delivery location shapes equipment depreciation schedules and labor utilization rates.
- Static:Controlled-environment calibration using precision turntables and climate chambers. Heavy-duty OEMs in Stuttgart's engineering corridor maintain captive static facilities for type-approval documentation.
- Dynamic:Road-load simulation with parameterized vibration and thermal cycling. Hybrid powertrain thermal management validation is concentrating demand in Munich's test-engineering ecosystem.
- On-Road:Mobile execution eliminates depot downtime for distributed fleets.
- Laboratory:Reference-standard traceability for regulatory submission.
Static protocols dominate revenue today; dynamic methods are expanding most quickly.
End User:
Procurement authority and compliance liability split differently across buyer categories.
- OEMs:Captive service networks integrate calibration into manufacturing and warranty fulfillment. Type-approval liability under Germany's KBA protocols locks OEMs into documented traceability chains.
- Fleet Operators:Direct contracting for uptime-critical assets. Dutch and Belgian logistics groups are unbundling diagnostic hardware ownership from labor contracts.
- Repair Shops:Independent workshops absorb capital risk on reference equipment to capture aging parc maintenance.
- Government Agencies:Enforcement and roadside inspection calibration for regulatory verification.
OEMs command the largest margin pools; repair shops are capturing volume growth fastest.
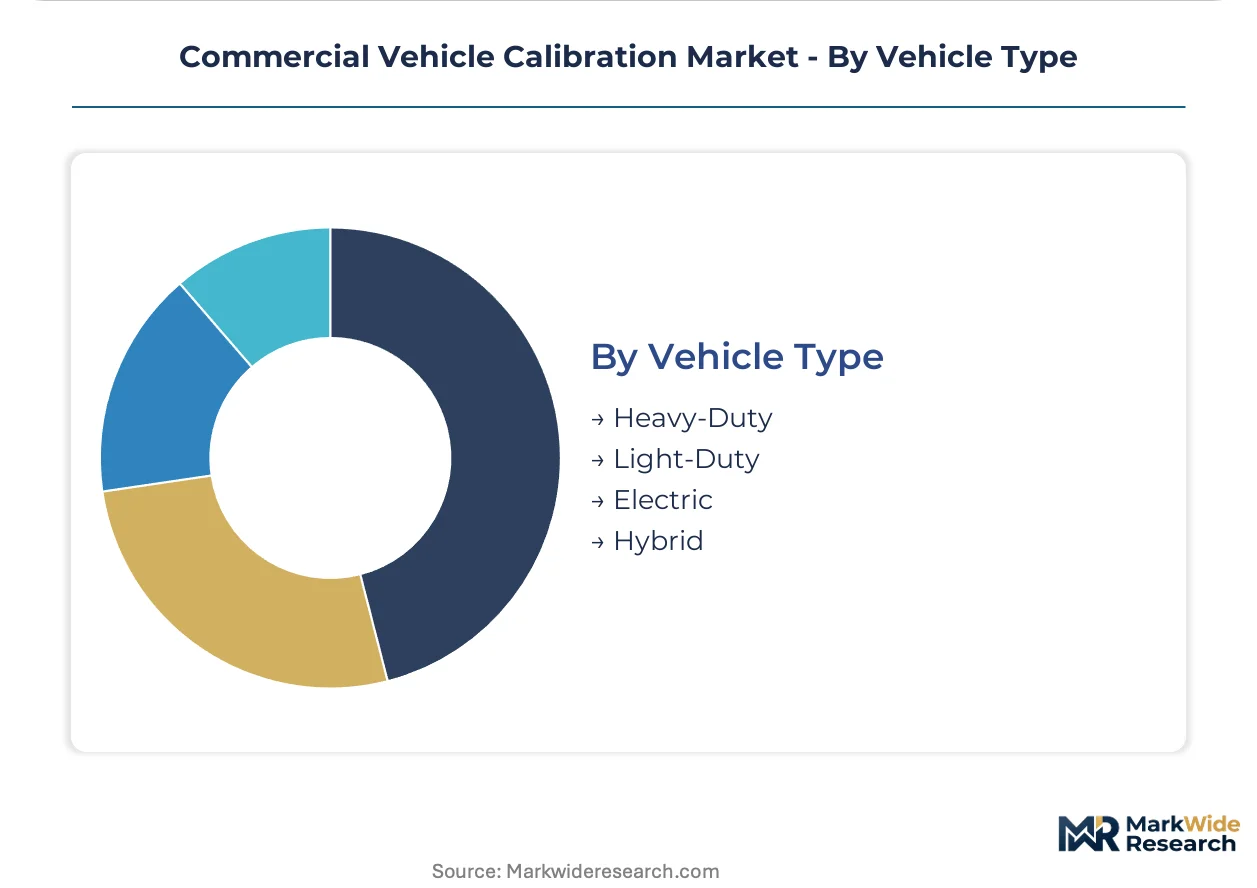
Vehicle Type:
Powertrain electrification is fragmenting calibration protocols across thermal and electrical domains.
- Heavy-Duty:NOx sensor and particulate monitor recalibration under Euro VI enforcement. Germany's long-haul corridors generate concentrated demand for depot-based service networks.
- Electric:Battery management system voltage sensing and thermal runaway detection validation. Urban delivery electrification in France and the Netherlands is accelerating electric-specific protocol development.
- Light-Duty:Compact sensor arrays for last-mile distribution vehicles.
- Hybrid:Dual-powertrain thermal management sensor coordination.
Heavy-duty vehicles anchor revenue today; electric platforms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive engineering corridor around Stuttgart and Munich established the foundational calibration infrastructure for European commercial vehicles. This legacy concentration continues to shape regulatory standards and service network architectures across the continent.
Germany
Heavy-duty fleet operators in the Stuttgart engineering corridor drive sustained demand for NOx sensor and particulate monitor recalibration. Germany's KBA enforces type-approval protocols that mandate documented traceability chains for all safety-critical calibrations. Munich's test-engineering ecosystem anchors dynamic calibration development for hybrid powertrain thermal management validation.
France
Urban delivery electrification in Paris and Lyon accelerates electric-specific protocol development for battery management systems. ANSM harmonizes type-approval test sequences with Germany's KBA, compressing recertification intervals for hybrid platforms. The Île-de-France logistics hub concentrates depot-based service network demand for last-mile fleet compliance.
Netherlands
Dutch logistics groups pioneer unbundled procurement, separating diagnostic hardware ownership from labor contracts. Remote diagnostics mandates from the European Commission embed calibration validation within Rotterdam's connected freight platforms. The Rotterdam-Genoa corridor deployment demands sub-millimeter optical alignment services for autonomous freight trials.
Italy
Service unbundling fragments procurement patterns most acutely in Italy, where captive OEM networks historically dominated safety-critical maintenance. EU Green Deal decarbonization timelines tighten enforcement windows for emission-related calibration documentation in Milan's urban delivery segments. The Hamburg-Milan freight route accelerates lidar and camera array deployment requiring mobile calibration capacity.
Poland
Central European logistics hubs in Warsaw and Kraków densify commercial vehicle parcs faster than calibration service coverage expands. Euro VI emission norms extend compliance requirements to Poland's rapidly growing heavy-duty fleet. White-space opportunities emerge for mobile diagnostic units serving cross-border freight operators.
Commercial Vehicle Calibration Market Competitive Landscape
The competitive structure tilts toward diversified automotive suppliers with embedded diagnostics ecosystems. Laboratory calibration workflows and optical sensor alignment capabilities concentrate among component manufacturers with captive R&D infrastructure. Three archetypes dominate: integrated automotive suppliers, specialized metrology equipment fabricators, and telematics-embedded diagnostics platforms. Strategic moves center on cloud-based validation tool consolidation and mobile service capacity expansion.
Within the integrated supplier tier, Robert Bosch GmbH and Continental AG occupy anchor positions exemplifying embedded diagnostics ecosystems. MAHLE GmbH represents specialized dynamic calibration protocol development. Among metrology-focused fabricators, MAHA Maschinenbau Haldenwang GmbH & Co. KG sits within the precision equipment archetype. AVL List GmbH exemplifies test-engineering service providers with captive calibration capabilities. Autel Intelligent Technology Corp., Ltd. represents the diagnostics platform segment with telematics integration potential.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| MAHLE GmbH |
| HELLA GmbH & Co. KGaA |
| Cojali S.L. |
| MAHA Maschinenbau Haldenwang GmbH & Co. KG |
| Autel Intelligent Technology Corp., Ltd. |
| AVL List GmbH |
| Denso Corporation |
| Others |
Value Network & Pricing Analysis
Rare-earth dopant costs in fiber-optic reference standards cascade through acoustic calibration tiers, with ECHA REACH restrictions amplifying consumable expenditures for independent repair shops serving Poland's expanding heavy-duty fleets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM captive networks from independent workshops and mobile diagnostic operators. Certification grade under Germany's KBA type-approval protocols and volume scale through fleet telematics mandates drive price differentiation. Cost compression in the economy tier intensifies as standardized GPS receiver modules commoditize. Fleet operators exhibit highest price sensitivity due to unbundled procurement patterns, while OEM captive networks maintain lowest sensitivity through warranty cost absorption.
Supply Chain Analysis
Refurbishment flows for precision turntables and inertial platforms concentrate in Germany and Switzerland, with secondary calibration equipment redeployment extending asset lifecycles for Central European entrants. German metrology fabricators and Swiss precision equipment suppliers anchor upstream manufacturing, drawing from rare-earth mineral feedstocks and specialized optical component foundries. Single-source vulnerability persists in precision turntable supply. Distribution runs through OEM captive service networks, independent workshop consortia, and emerging mobile diagnostic platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial vehicle calibration functions as a stable compounder, with Euro VI emission enforcement and autonomous freight corridor deployment generating recurring compliance expenditure across European fleet operators.
For Market Incumbents: Anchor laboratory calibration workflows through embedded diagnostics ecosystems to defend against telematics-embedded platform consolidation. Deepen backward integration into precision metrology equipment supply to mitigate single-source risk from German and Swiss fabricators. Invest in KBA-aligned certification documentation to maintain type-approval liability coverage.
For New Entrants and Emerging Players: Cross-border freight operators in Poland and Czechia represent the most penetrable buyer archetype, with calibration service coverage lagging fleet parc expansion. Mobile diagnostic units targeting hydrogen powertrain thermal management sensors offer white-space entry before incumbent protocol standardization. Pursue cloud-based validation tool partnerships to bypass capital-intensive static facility requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized optical sensor alignment expertise concentrates among aging technician cohorts. The five-to-ten-year viability window favors acquisition of metrology-capable test-engineering service providers with documented KBA traceability chains. Monitor EU AI Act safety documentation requirements as inflection signal for automated driving system calibration validation cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Diagnostic Platform Deployment | Rotterdam-Genoa corridor operators demand sub-millimeter optical alignment without depot downtime. |
| Hydrogen Powertrain Protocol Development | Fuel cell thermal management sensors require dynamic calibration methods absent from incumbent networks. |
| Cloud-Based Validation Tool Consolidation | Dutch logistics groups unbundle hardware ownership, concentrating vendor relationships around telematics ecosystems. |
| EMA MDR Framework Alignment | Medical-device-grade documentation transfers to commercial vehicle safety-critical premium service tiers. |
| Central European Service Network Expansion | Warsaw and Kraków logistics hubs densify parcs faster than calibration coverage expands. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, calibration service technicians, OEM platform engineers, and aftermarket distribution managers alongside secondary validation. KBA type-approval documentation, ECHA REACH restriction filings, EU Green Deal implementation timelines, and vehicle production registration databases anchored data triangulation. Bottom-up segment sizing and top-down market reconciliation cross-verified outputs.
Comparable-period anchoring linked projection horizons to historical reference intervals across the analysis window. Segmentation modeling incorporated technology platform, calibration type, end-user category, and vehicle powertrain architecture dimensions. CAGRs derived from trend extrapolation against enforcement milestone pacing, with hybrid powertrain thermal management validation and autonomous freight corridor deployment schedules informing trajectory assumptions.
Underlying measurement precision varies by segment; GPS and static laboratory protocols carry tighter precision than emerging acoustic and hydrogen powertrain categories. Forecasts incorporate assumptions regarding Euro VI enforcement consistency and EMA MDR framework adoption velocity. Practitioners should monitor EU AI Act safety documentation finalization and Poland fleet telematics mandate timing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Tank Car Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market
Commercial Vehicles
Commercial Truck Trailer Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Asia Three Wheeler Market
Commercial Vehicles
Cryogenic Liquid Transport Vehicle Market
Commercial Vehicles
Electric LCV Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
Compact Utility Vehicles Market