
 Europe Vacuum Truck Market | 2026-2036
Europe Vacuum Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vacuum Truck Market Analytics
Aluminum is hardening its position as the preferred tank material for European vacuum truck builders seeking payload optimization and corrosion resistance. Cappellotto Spa leverages its Italian manufacturing base to dominate Mediterranean municipal contracts with specialized combination units. KOKS Group BV anchors its competitive stance through advanced vacuum system engineering for hazardous industrial applications. Federal Signal Corporation extends its transatlantic reach by adapting North American chassis designs to EU emission standards.
A vacuum truck integrates a high-capacity tank vessel, vacuum pump or blower system, and suction hose assembly mounted on a commercial chassis, typically achieving vacuum levels of 85-95% and tank capacities from 3,000 to 20,000 liters for liquid, sludge, or dry material recovery. The technology dimension shows pump and vacuum system configurations commanding the premium tier where industrial cleaning and oil and gas applications require explosion-proof specifications and continuous-duty cycles. Combination type units represent the fastest-growing configuration as municipal services consolidate fleet assets to handle diverse waste streams with single-vehicle deployment.
The EU Green Deal and REACH framework mandate cleaner extraction processes and material traceability, pushing manufacturers toward stainless steel tank materials and closed-loop filtration systems that reduce environmental discharge. CE marking under the EU's machinery directive governs market access and safety compliance for all vacuum truck deployments across member states. ECHA chemical restriction lists influence hose and seal material selections, directly impacting component sourcing decisions. Stakeholders must monitor evolving F-Gas Regulation amendments that could restrict refrigerant-based cooling systems in certain vacuum pump technologies.
Market Dynamics
The EU Green Deal's waste hierarchy directives are compressing fleet replacement cycles as municipal operators face mandatory efficiency upgrades for liquid recovery systems.
Growth Catalysts
- REACH framework mandates:Chemical processing plants across the Rhine-Ruhr corridor must deploy closed-loop extraction systems, forcing vacuum truck procurement for compliant sludge handling.
- Aluminum tank adoption:Payload optimization requirements from German municipal fleets are accelerating corrosion-resistant tank configurations.
- Combination unit consolidation:French sewer maintenance services are retiring single-purpose vehicles in favor of multi-stream recovery platforms.
Market Restraints
- Stainless steel input costs:Tank material price volatility constrains margin flexibility for builders serving ECHA-compliant specifications.
- Pump technology concentration:Explosion-proof vacuum system engineering remains concentrated among specialized Dutch and German suppliers.
- F-Gas Regulation friction:Pending amendments threaten refrigerant-based cooling architectures in certain vacuum pump designs.
Strategic Opportunities
- Portuguese municipal underpenetration:Aging Iberian sewer infrastructure lacks modern combination fleets, creating fleet modernization whitespace.
- Hydrogen refueling station maintenance:Emerging high-pressure liquid extraction protocols require specialized vacuum configurations for fuel cell infrastructure.
- CSRD-aligned service bundling:Sustainability reporting mandates enable outcome-based maintenance contracts with material traceability guarantees.
Industry Challenges
- Vacuum system technician scarcity:Specialized pump maintenance skills lag fleet expansion rates across Central European service networks.
- CE marking timeline compression:Machinery directive compliance documentation delays chassis-tank integration schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vacuum Truck Market |
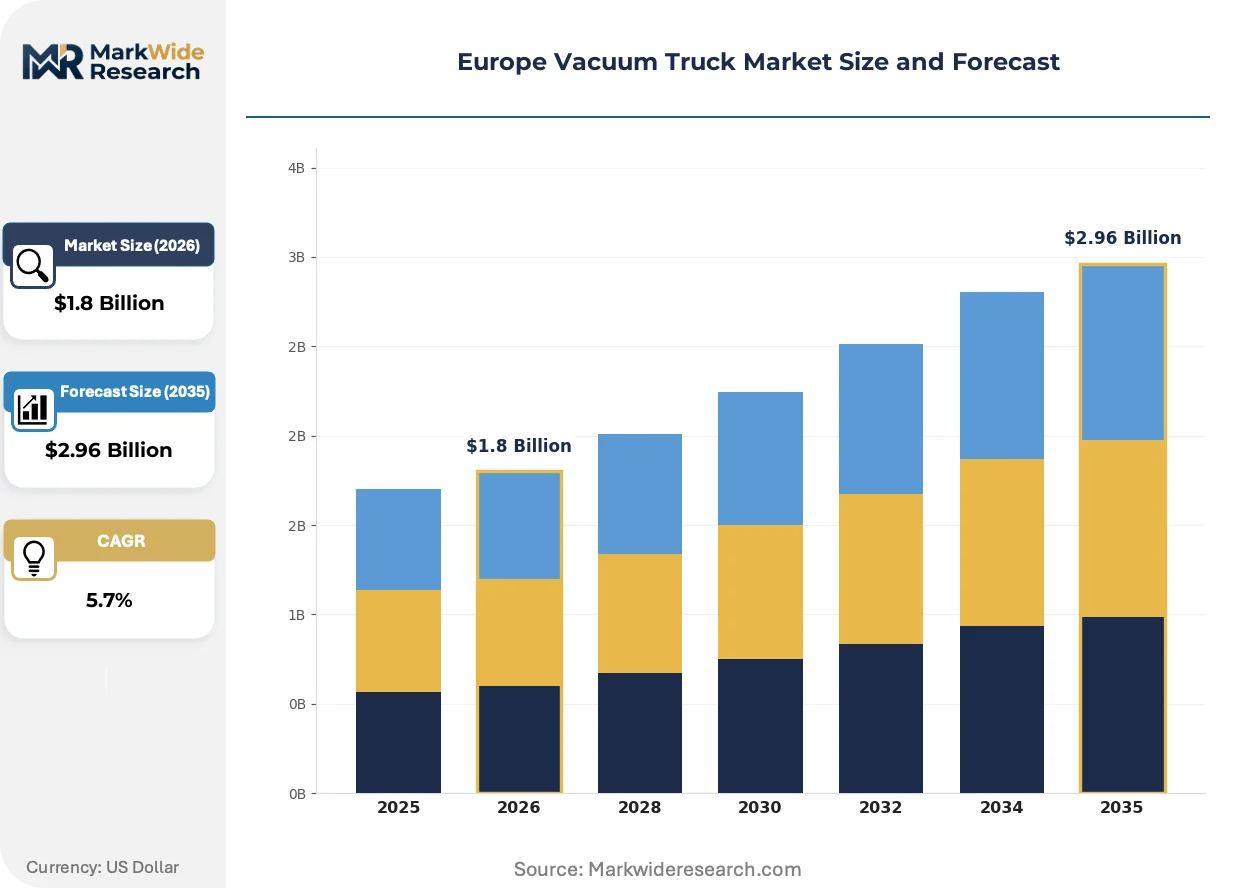
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Liquid, Sludge, Waste, Combination Application: Municipal Services, Industrial Cleaning, Construction, Oil & Gas Tank Material: Stainless Steel, Carbon Steel, Aluminum, Composite Technology: Pump, Vacuum System, Filtration, High-Pressure Jetting |
| Companies Covered | Cappellotto Spa, KOKS Group BV, Federal Signal Corporation, Alamo Group Inc. (Rivard), Vac-Con, Inc., GapVax, Inc., FULONGMA Group Co., Ltd., Keith Huber Corporation, DISAB Vacuum Technology AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vacuum Truck Market Evolving Landscape
European vacuum truck architecture is fragmenting into application-specific configurations as operators reject one-size-fits-all platforms for targeted extraction protocols.
Electric auxiliary power units for vacuum pump drives are modularizing fleet electrification strategies. German chemical processors are piloting battery-supported blower systems for indoor hazardous zone operations. This architecture is modularizing chassis-powertrain separation, enabling retrofit pathways without full vehicle replacement.
ECHA chemical restriction lists are forcing seal and hose material substitutions across the supply base. Industrial cleaning operators must recertify component traceability for REACH-compliant polymers. Hazardous waste segments face the steepest reformulation costs as legacy elastomers exit approved substance inventories.
Performance-based maintenance contracts are displacing traditional equipment ownership across Dutch municipal fleets. Service providers now guarantee extraction volumes and uptime metrics rather than delivering capital assets. This shift concentrates most visibly in Randstad urban agglomerations where fleet utilization rates determine contract renewal.
Europe Vacuum Truck Market Segmentation
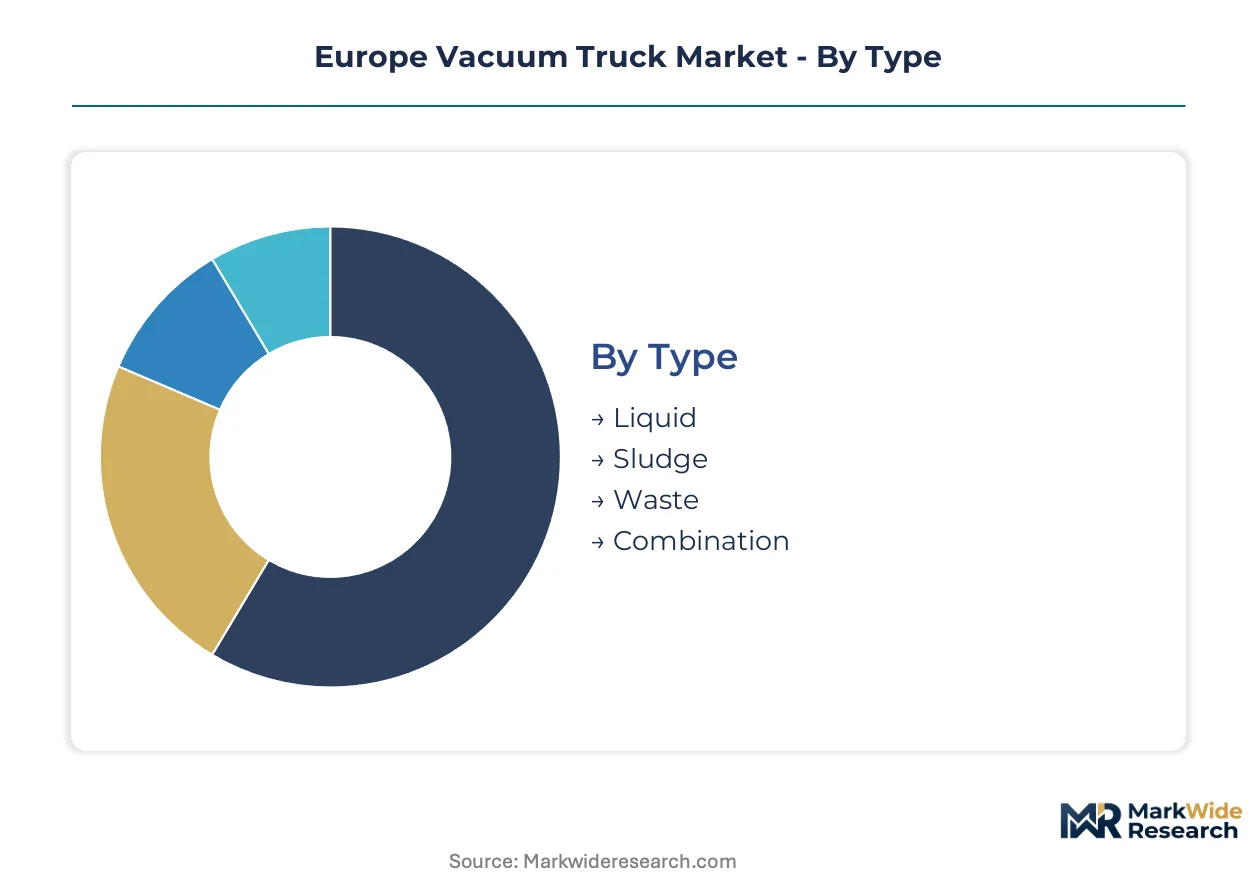
European vacuum truck procurement patterns fragment sharply across material handling requirements, regulatory exposure, and fleet utilization economics. Tank material selection and technology configuration now determine competitive positioning more than chassis brand or geographic origin.
Type:
Supply concentration in combination units has compressed single-purpose manufacturing capacity across German and Dutch builders.
- Liquid:Dedicated liquid recovery systems employ cylindrical tank geometries optimized for low-viscosity fluids and rapid discharge cycles. Rhine-Ruhr chemical processors specify these units for solvent recovery operations where cross-contamination protocols prohibit multi-stream deployment.
- Sludge:High-solids handling configurations integrate reinforced tank baffles and abrasion-resistant suction systems. French municipal sewer maintenance fleets are standardizing on sludge-specific platforms for primary sediment extraction before secondary treatment.
- Waste:General waste recovery units balance tank capacity with maneuverability constraints for urban collection routes.
- Combination:Multi-stream platforms consolidate liquid, sludge, and dry material recovery within modular tank architectures. Randstad municipal operators are retiring single-purpose fleets in favor of these flexible configurations.
Combination units absorb the bulk of installed capacity; sludge configurations are expanding most quickly.
Application:
Cost tier differentiation separates municipal procurement from industrial specifications where explosion-proof engineering commands substantial premiums.
- Municipal Services:Sewer maintenance and stormwater management fleets prioritize standardized tank volumes and rapid hose deployment systems. German municipal associations are consolidating specifications to reduce spare parts complexity across Länder procurement pools.
- Industrial Cleaning:Hazardous zone operations require ATEX-certified vacuum systems and stainless steel tank materials. Rotterdam petrochemical terminals specify these units for tank cleaning protocols under REACH discharge monitoring.
- Construction:Excavation support and dewatering applications favor high-capacity blower systems mounted on all-terrain chassis.
- Oil & Gas:Upstream extraction sites demand continuous-duty pump configurations with remote monitoring capabilities for offshore platform logistics.
Municipal services anchor volume demand; industrial cleaning configurations generate the steepest margin expansion.
Tank Material:
Volume concentration in aluminum has forced stainless steel suppliers toward specialized corrosion-resistant alloys for ECHA-regulated applications.
- Stainless Steel:Austenitic grades 304 and 316L provide chemical resistance for aggressive effluent handling. Dutch hazardous waste operators are mandating full stainless construction under CSRD-aligned material traceability requirements.
- Carbon Steel:Standard mild steel tanks with epoxy coatings serve cost-sensitive municipal fleets where neutral pH effluent predominates. Eastern European operators favor these configurations for budget-constrained replacement cycles.
- Aluminum:5083-H321 marine-grade aluminum delivers payload optimization with natural corrosion resistance. Bavarian municipal fleets have standardized on aluminum tanks to maximize legal axle loading within German road weight regulations.
- Composite:Fiberglass-reinforced polymer tanks offer extreme chemical resistance for niche acid recovery applications.
Aluminum tanks absorb the bulk of new orders; stainless steel specifications are gaining share fastest in regulated industrial segments.
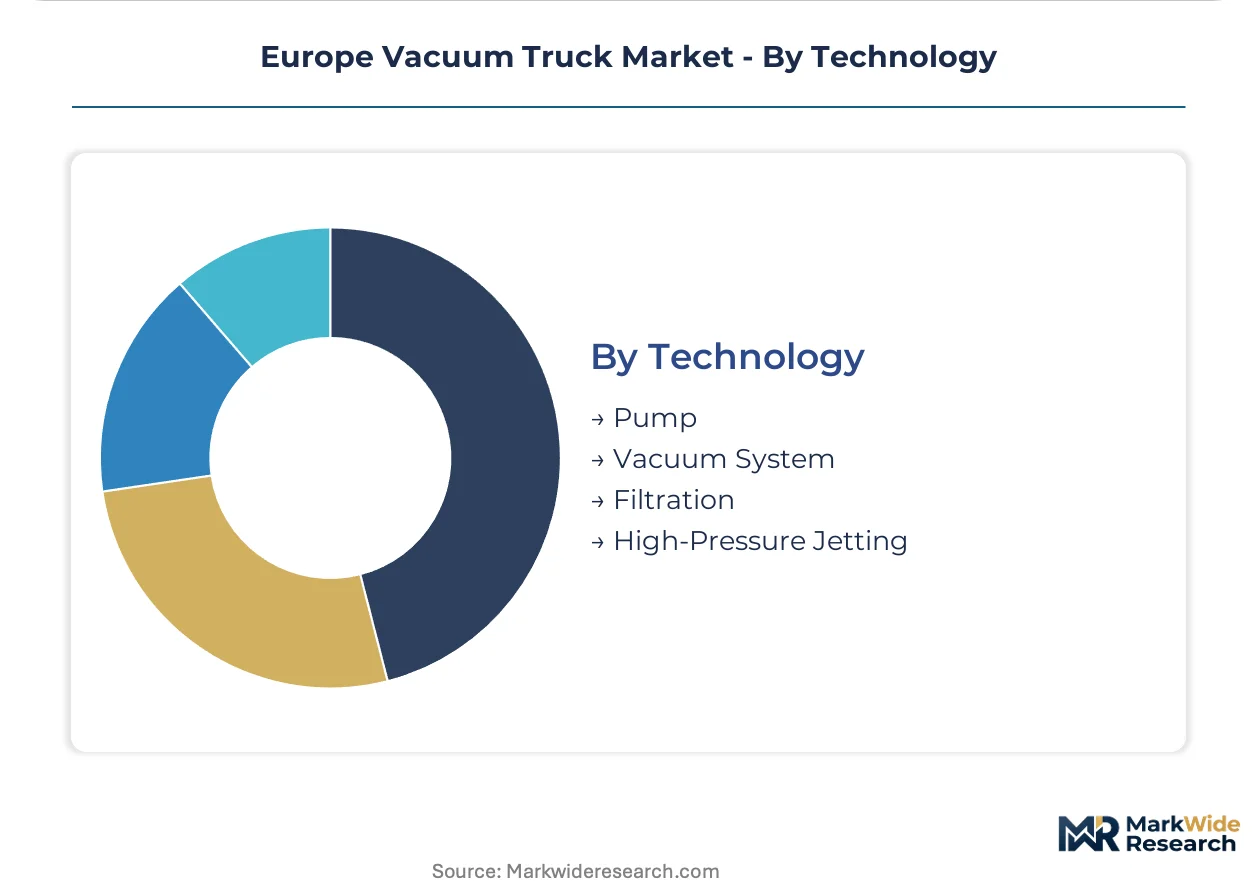
Technology:
Customer type segmentation separates municipal buyers seeking standardized maintenance protocols from industrial operators demanding custom vacuum system engineering.
- Pump:Rotary vane and liquid ring vacuum pumps achieve 85-95% vacuum levels for continuous material transfer. German pump specialists dominate this tier through proprietary sealing technologies.
- Vacuum System:Integrated blower and filtration architectures optimize airflow dynamics for high-volume recovery. French industrial cleaning contractors are specifying these systems for pharmaceutical manufacturing cleanouts.
- Filtration:Closed-loop filtration modules separate solids from liquid streams to reduce disposal volumes. REACH compliance is forcing adoption across Rhine-Ruhr chemical processing corridors.
- High-Pressure Jetting:Integrated water jetting systems combine excavation with immediate debris recovery for trenchless pipeline rehabilitation.
Pump technologies absorb the bulk of installed base; vacuum system configurations are climbing the fastest as industrial specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates along the Rhine-Ruhr industrial corridor where chemical processors and municipal operators drive procurement of specialized extraction vehicles. German municipal associations and French sewer maintenance services anchor volume procurement across the region.
Germany
Bavarian municipal fleets are standardizing on aluminum tank configurations to maximize legal axle loading under federal road weight regulations. The EU Green Deal's waste hierarchy directives are compressing fleet replacement cycles for liquid recovery systems. The Rhine-Ruhr corridor hosts chemical processing plants requiring REACH-compliant closed-loop sludge extraction vehicles.
France
Paris and the Île-de-France region are retiring single-purpose sewer maintenance vehicles in favor of multi-stream combination units. ECHA chemical restriction lists are forcing seal and hose material substitutions across municipal procurement specifications. The Randstad urban agglomerations are piloting performance-based maintenance contracts with guaranteed uptime metrics.
Netherlands
Rotterdam petrochemical terminals specify ATEX-certified vacuum systems for tank cleaning protocols under REACH discharge monitoring. The F-Gas Regulation is threatening refrigerant-based cooling architectures in certain vacuum pump technologies deployed across Dutch industrial zones. Specialized Dutch pump engineering firms dominate explosion-proof system supply for hazardous zone operations.
Italy
Mediterranean municipal contracts are consolidating around combination units for diverse waste stream handling. CE marking under the EU machinery directive governs safety compliance for chassis-tank integration schedules. Italian manufacturing bases serve specialized unit demand across Southern European procurement pools.
United Kingdom
Industrial cleaning contractors are specifying integrated blower and filtration architectures for pharmaceutical manufacturing cleanouts. The CSRD framework is enabling outcome-based maintenance contracts with material traceability guarantees. London and Southeast England concentrate demand for high-specification hazardous waste extraction platforms.
Europe Vacuum Truck Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers expand from single-purpose platforms toward modular multi-stream configurations. The vendor base organizes around three tiers: chassis-integrated builders, specialized tank fabricators, and component engineering specialists. Strategic archetypes include aluminum tank optimization specialists, explosion-proof system engineers, and municipal fleet consolidators. M&A activity and geographic licensing agreements represent the primary competitive vectors for market position expansion.
Within the specialized engineering tier, KOKS Group BV and Cappellotto Spa exemplify contrasting geographic anchoring strategies. KOKS Group BV occupies a position among Dutch-based explosion-proof system specialists serving hazardous industrial applications. Cappellotto Spa represents Italian manufacturing concentration for Mediterranean municipal contract capture. Federal Signal Corporation sits within the transatlantic adaptation archetype, bridging North American chassis expertise with EU emission compliance requirements.
| Leading Market Players |
|---|
| Cappellotto Spa |
| KOKS Group BV |
| Federal Signal Corporation |
| Alamo Group Inc. (Rivard) |
| Vac-Con, Inc. |
| GapVax, Inc. |
| FULONGMA Group Co., Ltd. |
| Keith Huber Corporation |
| DISAB Vacuum Technology AB |
| Others |
Value Network & Pricing Analysis
German municipal fleet standardization on aluminum tank specifications is compressing supplier margins as builders absorb material cost volatility to retain Länder procurement contracts. This buyer-driven specification tightening forces tank fabricators toward backward integration into aluminum processing while pump specialists exploit concentration in explosion-proof engineering to defend premium pricing.
Pricing Analysis
Volume procurement by municipal associations anchors the economy tier while REACH-compliant industrial configurations command substantial premiums. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified hazardous zone units from municipal sewer maintenance fleets and Eastern European budget replacements. Cost compression in the stainless steel tier is intensifying because ECHA-compliant alloy specifications constrain supplier flexibility. Eastern European municipal operators exhibit highest price sensitivity; Rotterdam petrochemical terminals show least sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German municipal associations and French sewer services, while specialized distributors serve fragmented industrial cleaning contractors. Manufacturing concentrates in Germany, the Netherlands, and Italy, with German pump engineering drawing from specialized sealing technology suppliers. Raw material dependencies span marine-grade aluminum, austenitic stainless steel grades, and REACH-compliant elastomer formulations. Single-source vulnerability in explosion-proof vacuum system engineering creates supply chain risk. Distribution runs through OEM-integrated builders for municipal volume and component specialists for hazardous industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as tank fabricators pursue captive aluminum processing capabilities to escape material cost volatility and pump specialists defend proprietary engineering moats.
For Market Incumbents: Lock in aluminum supply agreements with Nordic smelters to neutralize input cost volatility threatening Bavarian municipal contract profitability. Secure ATEX certification maintenance through in-house explosion-proof engineering talent retention, as Dutch pump specialist scarcity intensifies competitive poaching. Prioritize chassis-tank integration scheduling compression to preempt CE marking timeline delays eroding delivery commitments. For New Entrants and Emerging Players: Digital spare parts platforms offer the lowest-friction entry vector for aftermarket service capture in Portuguese municipal markets lacking modern combination fleet maintenance infrastructure. Target Iberian sewer infrastructure modernization whitespace through refurbishment-focused value propositions rather than new-build competition. Pursue outcome-based contracting pilots with Randstad municipal operators seeking guaranteed uptime metrics over capital ownership. For Investors and Strategic Acquirers: The window for entry favors component engineering specialists with proprietary vacuum system IP over chassis-integrated assemblers facing margin compression. Long-term viability centers on explosion-proof certification capabilities and CSRD-aligned material traceability infrastructure. Watch for F-Gas Regulation amendment finalization as inflection indicator for refrigerant-dependent pump technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Processing | Captive supply of 5083-H321 marine-grade aluminum secures Bavarian municipal contract margins against LME volatility. |
| ATEX Certification Expansion | Explosion-proof system engineering accreditation opens Rotterdam petrochemical terminal procurement pools. |
| Outcome-Based Service Contracting | Guaranteed uptime metrics align with Randstad municipal fleet utilization optimization mandates. |
| Portuguese Market Entry Partnership | Iberian infrastructure modernization whitespace enables combination unit fleet conversion without incumbent displacement. |
| Hydrogen Infrastructure Vacuum Configuration Development | High-pressure liquid extraction protocols for fuel cell stations create first-mover positioning in emerging maintenance demand. |
Research Methodology
Trade association filings, EU machinery directive compliance databases, and municipal procurement registry extracts formed the secondary backbone for market sizing validation. Primary interviews with fleet maintenance directors at German municipal associations, technical procurement leads at Rotterdam petrochemical terminals, and aftermarket service heads at Dutch industrial cleaning contractors combined with secondary validation through bottom-up and top-down triangulation.
Bottom-up unit economics across tank material grades, pump technology tiers, and application segments reconciled against top-down regional demand aggregation. Segmentation dimensions modeled include tank material type, vacuum system configuration, end-use application intensity, and regulatory compliance tier. CAGRs were derived from replacement cycle compression analysis and fleet modernization trajectory assessment, with EU Green Deal implementation pacing and REACH enforcement intensity as industry-specific forecast inputs.
The model holds under steady regulatory enforcement and aluminum price stability; deviation in F-Gas Regulation amendment severity or Nordic aluminum supply disruption would shift replacement cycle assumptions. Forecasts reflect documented base conditions with acknowledged sensitivity to ECHA chemical restriction list expansion and municipal budget allocation volatility. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Malaysia Box Truck Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market
Commercial Vehicles
Van Market
Commercial Vehicles
Asia Three Wheeler Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
United States Vans Market
Commercial Vehicles
Refrigerated Truck Market
Commercial Vehicles
Commercial Vehicle Steering Column Market