
 Compact Utility Vehicles Market | 2026-2036
Compact Utility Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Compact Utility Vehicles Market Intelligence
EPA Tier 4 Final is repositioning the engineering cost structure for diesel-powered compact utility vehicles, compelling manufacturers to invest in after-treatment systems or pivot to alternative powertrains. Kubota Corporation leverages its engine manufacturing depth to manage compliance costs internally. John Deere anchors its position through integrated drivetrain control systems that optimize fuel efficiency under load. Mahindra & Mahindra competes on cost-engineered diesel platforms tailored to price-sensitive agricultural buyers.
Compact utility vehicles are self-propelled work machines with gross vehicle weights typically below 8,500 pounds, designed for material transport, towing, and attachment-driven tasks across unpaved and semi-improved surfaces. Steel-reinforced cargo decks and hydrostatic transmissions define their functional architecture for repetitive stop-start duty cycles in confined spaces. Electric power source configurations are capturing disproportionate engineering investment as battery energy density improvements enable viable all-day runtime for municipal and landscaping applications. Compact crossovers within the vehicle type category remain the highest-volume segment, though mini trucks command premium pricing in specialized agricultural vineyard and orchard configurations where maneuverability constraints dominate equipment selection.
FAA regulations on airport ground support equipment influence compact utility vehicle specifications for baggage handling and tarmac maintenance fleets, while EPA emission tiers and OSHA workplace noise standards shape product certification requirements for domestic sales. NHTSA safety standards for low-speed vehicles create additional compliance layers for street-legal configurations sold through dealership channels. Stakeholders must monitor battery supply chain localization requirements and charging infrastructure deployment timelines as electrification transitions from pilot procurement to mainstream fleet replacement cycles.
Market Dynamics
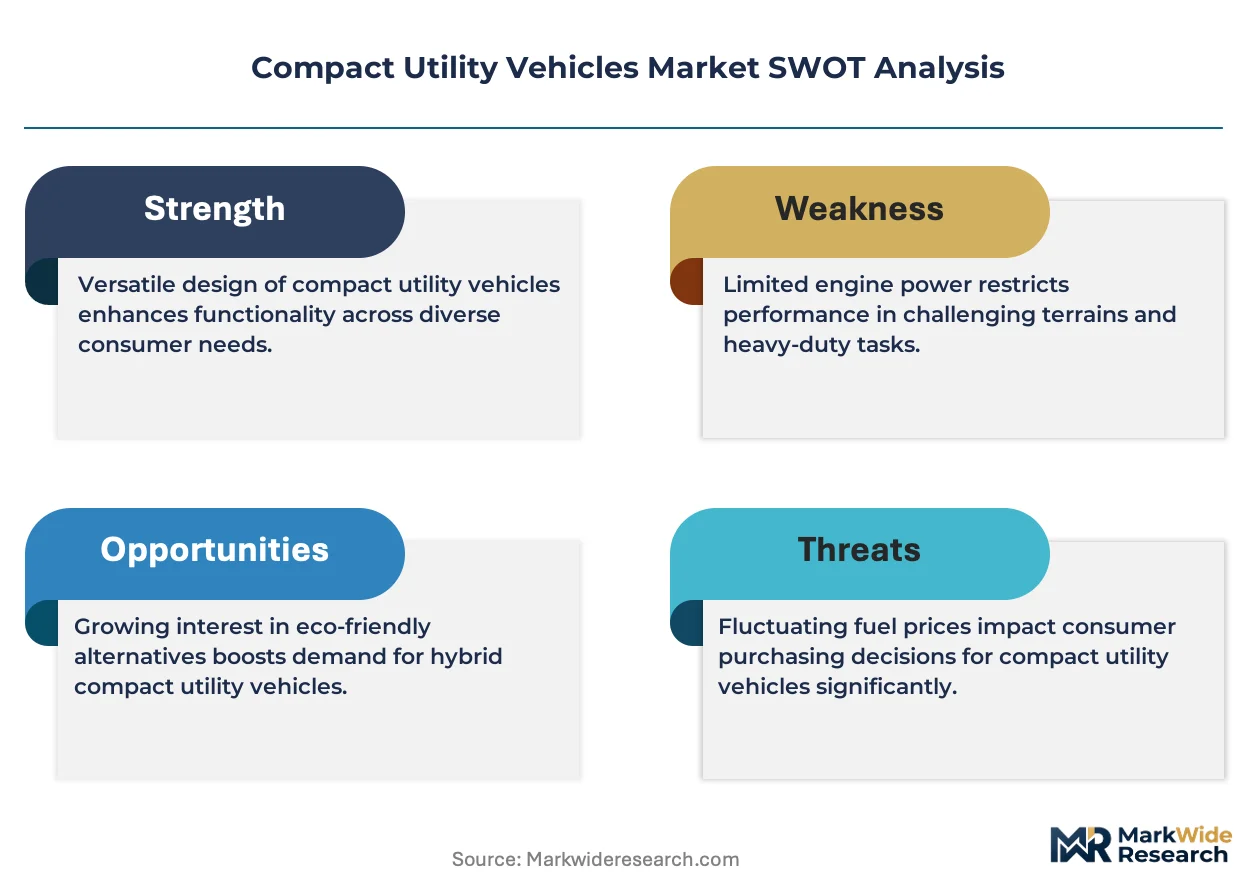
EPA Tier 4 Final emission standards are compressing diesel powertrain economics across municipal and agricultural fleets, forcing manufacturers to absorb after-treatment costs or accelerate electrification roadmaps. Battery energy density gains now enable viable all-electric configurations for stop-start duty cycles previously dominated by internal combustion.
Growth Catalysts
- US federal infrastructure spending:Public works departments in the United States are modernizing fleets with dedicated funding streams for electric vehicle procurement, accelerating replacement cycles for aging diesel units.
- FAA ground support mandates:Airport baggage handling and tarmac maintenance specifications are standardizing compact utility vehicle platforms for aviation applications, creating certified demand pools.
- Lithium-ion battery chemistry advances:Improved energy density and thermal management are extending runtime for landscaping and municipal applications into full-shift territory.
Market Restraints
- Steel and semiconductor input volatility:Hydrostatic transmission manufacturing and chassis fabrication face margin pressure from commodity price swings and chip allocation constraints.
- After-treatment system complexity:EPA Tier 4 Final compliance requires diesel particulate filters and selective catalytic reduction, adding cost and maintenance burden to legacy powertrain sales.
- Lead-acid battery substitution in price-sensitive segments:Agricultural buyers in emerging markets continue specifying flooded lead-acid configurations, limiting lithium-ion penetration.
Strategic Opportunities
- Vineyard and orchard mini truck specialization:Narrow-gauge configurations with tight turning radii command premium pricing in California and European wine regions where maneuverability constraints dominate.
- OSHA workplace noise standard alignment:Electric powertrains open indoor facility maintenance contracts where diesel noise and emissions previously excluded compact utility vehicles.
- Telematics and attachment integration:CAN-bus control systems enabling precision agriculture and smart fleet management represent unbundled software revenue streams.
Industry Challenges
- High-voltage technician certification gaps:Dealership service departments lack trained personnel for battery pack diagnostics and thermal management system repair.
- NHTSA low-speed vehicle homologation timelines:Street-legal configuration approval processes extend product launch schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact Utility Vehicles Market |
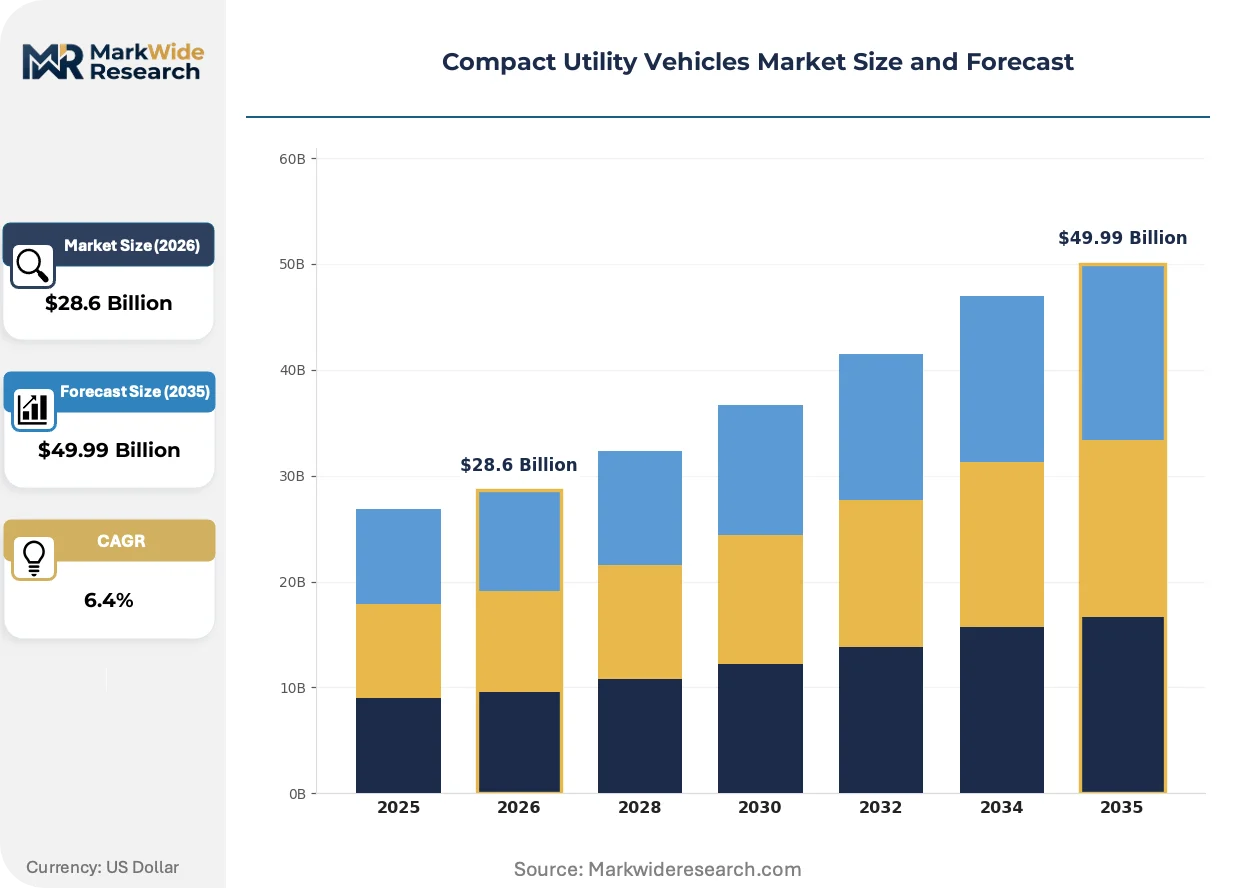
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Mini Trucks, Subcompact SUVs, Compact Crossovers, Light Buses Power Source: Gasoline, Diesel, Hybrid, Electric End User: Agriculture, Construction, Landscaping, Municipal Services Distribution Channel: Direct Sales, Dealerships, Online Platforms, Rental Services |
| Companies Covered | John Deere, Kubota Corporation, Bobcat Company, Caterpillar Inc., Mahindra & Mahindra, Komatsu Ltd., Hitachi Construction Machinery Co. Ltd., Hyundai Construction Equipment Co Ltd, Volvo Construction Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact Utility Vehicles Market Strategic Shifts & Innovations
Electrification is rewriting powertrain architecture decisions across compact utility vehicle segments, with battery-electric configurations capturing disproportionate engineering investment relative to current sales mix. Manufacturers are repositioning around energy storage and thermal management capabilities rather than engine displacement hierarchies.
Lithium iron phosphate battery packs are expanding into municipal fleet applications where safety and cycle life outweigh energy density priorities. Public works departments in the United States are piloting these configurations for snow removal and park maintenance duty cycles. The technology is expanding into price points previously reserved for lead-acid alternatives, compressing the premium gap for electrified entry-level units.
EPA Tier 4 Final implementation is eliminating non-compliant diesel engine imports for the US market. Manufacturers without captive engine production face sourcing constraints or partnership dependencies for after-treatment integration. Agricultural buyers are responding by accelerating trade-up timelines to secure pre-compliant inventory or transitioning to gasoline and electric alternatives.
Rental and short-term leasing channels are displacing traditional equipment financing for landscaping contractors and seasonal municipal operations. Equipment-as-a-service models bundle attachments, maintenance, and telematics into per-hour or per-season contracts. This shift is most visible in the United States where municipal budget volatility favors operational expenditure treatment over capital appropriations.
Compact Utility Vehicles Market Segmentation
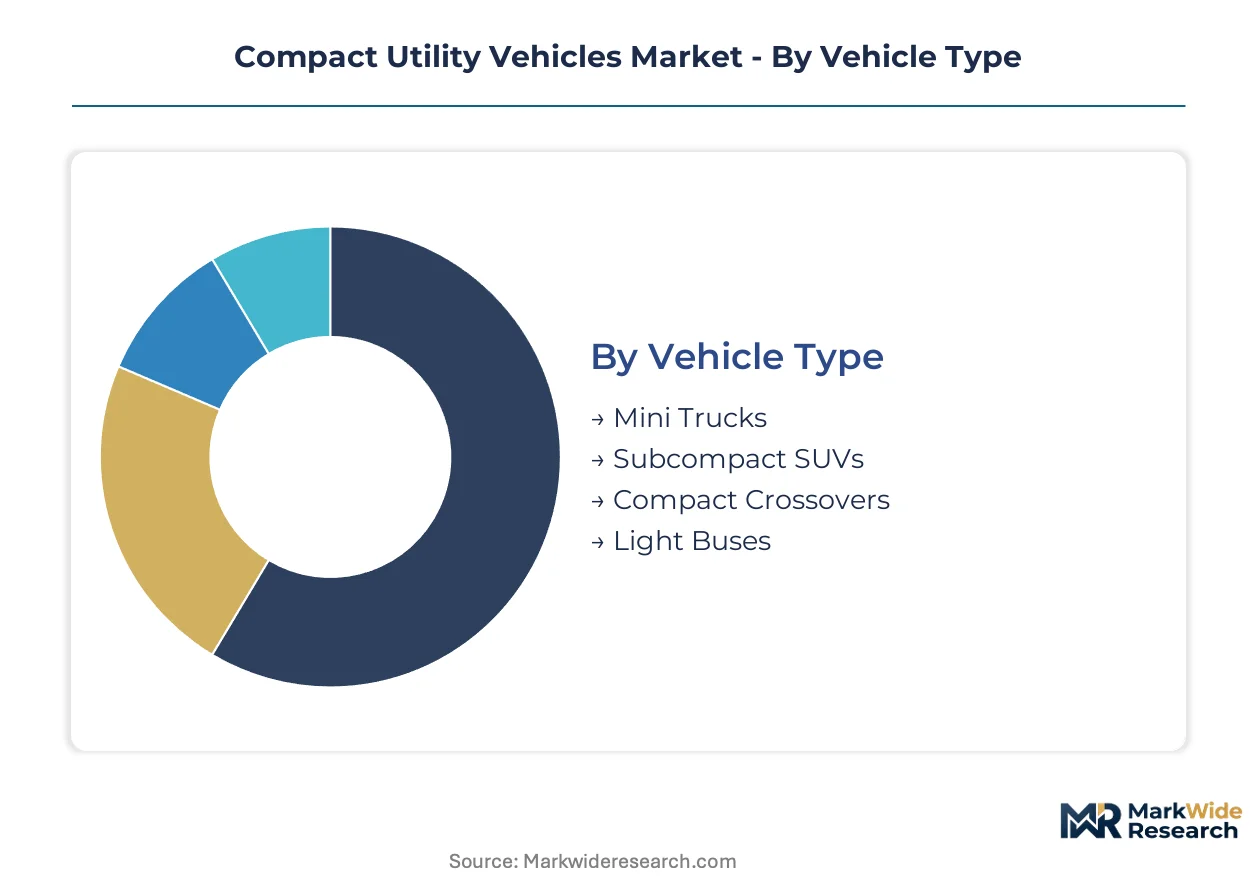
Segmentation in compact utility vehicles reveals divergent capital requirements across powertrain architectures and distribution models. Equipment buyers face fundamentally different ownership economics depending on duty cycle intensity and procurement channel selection.
Vehicle Type:
Capital intensity peaks with specialized narrow-gauge configurations requiring dedicated tooling and low-volume production lines.
- Mini Trucks:Narrow-gauge chassis with sub-48-inch widths and reinforced cargo decks dominate vineyard and orchard applications. California wine regions and European viticulture clusters absorb premium pricing for tight-turning-radius configurations where maneuverability constraints override payload capacity.
- Compact Crossovers:Highest-volume segment with standardized unibody construction and modular attachment interfaces. Municipal fleets in the United States concentrate procurement here for park maintenance and snow removal duty cycles where versatility across seasons drives replacement decisions.
- Subcompact SUVs:Bridge configurations blending passenger comfort with light-duty cargo capacity. Landscaping contractors favor these for crew transport between job sites.
- Light Buses:Extended wheelbase variants with bench seating configurations. Airport ground support operations specify these for tarmac crew movement under FAA equipment mandates.
Most installed capacity flows through Compact Crossovers. Expansion is steepest in Mini Trucks.
Power Source:
Engineering investment concentrates where emission compliance costs and battery energy density curves intersect.
- Electric:Lithium iron phosphate packs with thermal management systems now deliver full-shift runtime for stop-start municipal duty cycles. Public works departments in the United States pilot these for park maintenance where EPA Tier 4 Final compliance costs erode diesel economics.
- Diesel:EPA Tier 4 Final after-treatment systems—diesel particulate filters plus selective catalytic reduction—add cost and maintenance burden. Agricultural buyers accelerate trade-up timelines to secure pre-compliant inventory or pivot to alternatives.
- Gasoline:Lower upfront cost suits price-sensitive landscaping contractors with intermittent usage patterns. Carbureted configurations persist in emerging markets without stringent emission enforcement.
- Hybrid:Parallel architectures capturing regenerative braking energy for repetitive stop-start operations. Limited penetration outside premium municipal fleet specifications.
Production volumes concentrate in Diesel configurations. Gaining share fastest are Electric powertrains.
End User:
Customer type determines attachment specification, financing preference, and service interval tolerance.
- Municipal Services:Equipment-as-a-service contracts with bundled maintenance and telematics. Budget volatility in the United States favors operational expenditure treatment over capital appropriations.
- Agriculture:Cost-engineered diesel platforms with flooded lead-acid battery alternatives for price-sensitive buyers. Seasonal cash flow dictates financing structure.
- Landscaping:Rental and short-term leasing channels displacing traditional equipment financing for seasonal operations.
- Construction:Steel-reinforced cargo decks and hydrostatic transmissions for material transport across unpaved surfaces.
Procurement volume concentrates in Municipal Services. Climbing the fastest are Landscaping applications.
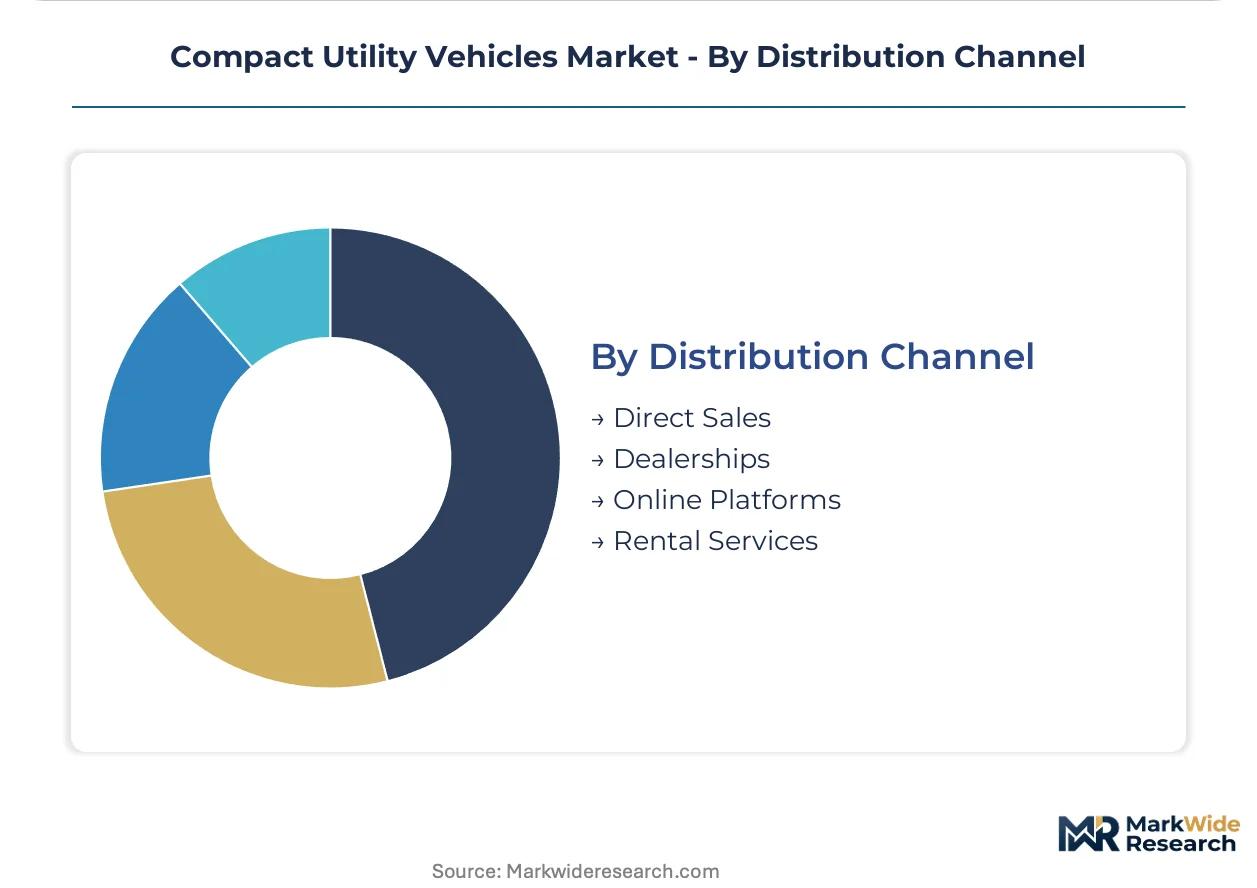
Distribution Channel:
Channel selection shapes margin structure and customer relationship depth.
- Direct Sales:Fleet procurement contracts with volume pricing and customized attachment packages. Large municipal aggregators negotiate directly with manufacturers.
- Dealerships:Service revenue attachment and NHTSA low-speed vehicle homologation support for street-legal configurations.
- Rental Services:Hourly and seasonal contracts bundling attachments, maintenance, and telematics for budget-constrained contractors.
- Online Platforms:Specification comparison and lead generation for rural buyers with limited dealer proximity.
Transaction volume concentrates in Dealerships. Steepest expansion trajectory belongs to Rental Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in agricultural machinery and powertrain development anchor geographic demand concentration. EPA Tier 4 Final compliance costs and municipal fleet electrification programs reshape procurement patterns across developed markets. Battery supply chain localization and charging infrastructure deployment timelines determine regional adoption velocity.
United States
Federal infrastructure spending accelerates municipal fleet replacement cycles for public works departments. EPA Tier 4 Final emission standards compress diesel powertrain economics, pushing procurement toward electric configurations. California wine regions absorb premium-priced narrow-gauge mini trucks for vineyard applications where maneuverability constraints dominate equipment selection.
Germany
Precision agriculture engineering clusters concentrate in Baden-Württemberg and Bavaria, driving demand for telematics-integrated platforms. REACH chemical regulations and EU Green Deal carbon pricing influence material selection and end-of-life recycling requirements. Stuttgart-based automotive suppliers extend into compact utility vehicle component systems for electrified drivetrains.
China
Dual carbon goals and MIIT new energy vehicle mandates redirect manufacturing investment toward battery-electric platforms. Yangtze River Delta industrial clusters integrate lithium iron phosphate cell production with compact utility vehicle assembly. GB standards for low-speed electric vehicles create regulatory pathways for municipal fleet procurement in tier-two cities.
Japan
METI energy efficiency regulations and JIS standards for industrial machinery shape product certification requirements. Kanto region engineering centers develop hybrid powertrain architectures for repetitive stop-start duty cycles. Osaka-based component suppliers specialize in hydrostatic transmission systems for confined-space material handling applications.
India
Cost-engineered diesel platforms dominate agricultural procurement in Punjab and Haryana, where seasonal cash flow dictates financing structure. BIS certification requirements and PLI scheme incentives for advanced chemistry cell manufacturing accelerate lithium-ion penetration. Maharashtra industrial corridors concentrate assembly capacity for price-sensitive emerging market exports.
Compact Utility Vehicles Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressure intensifies as EPA Tier 4 Final compliance costs and electrification R&D demands strain mid-scale engineering budgets. Three archetypes dominate: integrated engine manufacturers with captive after-treatment capabilities, attachment-driven platform specialists, and emerging electric-native entrants. Strategic moves concentrate on M&A for battery supply chain access and geographic expansion through localized assembly partnerships.
Among diversified industrial conglomerates, John Deere exemplifies integrated drivetrain control capabilities, while Kubota Corporation anchors the engine-manufacturing archetype with internal compliance cost management. Mahindra & Mahindra occupies a position within cost-engineered diesel platforms for price-sensitive agricultural segments. These three represent distinct strategic responses to emission regulation compression and electrification transition timelines.
| Leading Market Players |
|---|
| John Deere |
| Kubota Corporation |
| Bobcat Company |
| Caterpillar Inc. |
| Mahindra & Mahindra |
| Komatsu Ltd. |
| Hitachi Construction Machinery Co. Ltd. |
| Hyundai Construction Equipment Co Ltd |
| Volvo Construction Equipment |
| Others |
Cost & Logistics Intelligence
Steel and lithium-ion cell costs cascade through compact utility vehicle pricing tiers, with hydrostatic transmission foundries in Japan and battery pack integrators in China determining margin allocation across municipal fleet contracts and agricultural dealer networks.
Pricing Analysis
Bundled equipment-as-a-service contracts now capture premium municipal procurement, while unbundled transactional sales dominate agricultural dealership channels. Price differentiation rests on EPA Tier 4 Final certification status and telematics integration depth, with electric configurations commanding upfront premiums that compress against lithium iron phosphate cost curves. Pricing pressure stems from semiconductor allocation constraints in hydrostatic transmission controllers, squeezing margins on mid-tier diesel units. Agricultural buyers in India and price-sensitive emerging markets exhibit highest price sensitivity, while US public works departments with federal infrastructure allocations show lowest sensitivity to capital expenditure differentials.
Supply Chain Analysis
Reverse logistics flows for battery pack refurbishment and hydrostatic transmission remanufacturing concentrate service revenue in dealer networks across the United States, Germany, and Japan. Manufacturing draws from Yangtze River Delta lithium iron phosphate cell production, Baden-Württemberg precision machining clusters, and Osaka-based hydrostatic component specialists. Single-source vulnerability in semiconductor allocation for transmission controllers creates supply chain risk. Distribution runs through manufacturer-owned dealerships for fleet homologation support, with rental services capturing seasonal landscaping demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final compliance cost differentials between US and Indian manufacturing bases create geographic-arbitrage opportunities for engine sourcing and after-treatment system integration.
For Market Incumbents: To counter electric-native entrants with direct battery supply agreements, Kubota Corporation and John Deere should deepen backward integration into lithium iron phosphate cell partnerships and expand captive thermal management system production in domestic engineering centers. Certification investment in NHTSA low-speed vehicle homologation accelerates street-legal configuration launches. For New Entrants and Emerging Players: IRA clean vehicle procurement incentives in the United States open a window for municipal fleet-focused electric-native platforms to capture equipment-as-a-service contracts before incumbent electrification roadmaps mature. Vineyard and orchard mini truck specialization in California and European wine regions offers the most penetrable white-space target, with telematics-integrated attachment packages as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional dealership networks with service department high-voltage technician certification gaps because consolidation enables shared training infrastructure and captive battery refurbishment revenue streams. Target acquisition archetypes include municipal fleet telematics specialists and lithium iron phosphate pack integrators with JIS or UL certification. Monitor battery supply chain localization requirements and charging infrastructure deployment timelines as inflection indicators for electric configuration adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Lithium iron phosphate cell contracts with Yangtze River Delta producers secure cost-competitive electrified platform economics. |
| Telematics Platform Integration | CAN-bus control systems enabling precision agriculture and smart fleet management unlock recurring software revenue streams. |
| High-Voltage Technician Certification Program | Dealership service department training infrastructure addresses repair capacity constraints for electric powertrain maintenance. |
| Vineyard Mini Truck Specialization | Narrow-gauge configurations with sub-48-inch widths command premium pricing in California and European viticulture clusters. |
| Equipment-as-a-Service Launch | Per-hour and per-season contracts bundling attachments and maintenance capture municipal budget volatility favoring operational expenditure treatment. |
Research Approach
Direct dialogue with municipal fleet procurement managers, agricultural equipment dealership principals, hydrostatic transmission engineering directors, and battery pack integration specialists grounded qualitative findings. Secondary validation drew from EPA emission certification databases, FAA ground support equipment specifications, NHTSA low-speed vehicle registration data, and SEC filings from diversified industrial conglomerates. Bottom-up and top-down triangulation reconciled unit shipment estimates with revenue aggregation across powertrain configurations.
Bottom-up modeling segmented volume and value across vehicle type, power source, end user, and distribution channel dimensions, with cross-validation against top-down macroeconomic indicators and infrastructure spending flows. CAGR derivation incorporated battery energy density improvement curves, EPA Tier 4 Final compliance cost trajectories, and municipal fleet replacement cycle acceleration from federal funding allocations. Industry-specific forecast inputs included lithium iron phosphate cost decline rates and charging infrastructure deployment timelines.
Revisions become necessary when battery supply chain localization mandates, semiconductor allocation disruptions, or NHTSA regulatory timeline extensions materialize. Forecasts reflect assumptions about electrification adoption velocity and after-treatment system cost stabilization. Practitioners should monitor IRA procurement incentive renewal debates and MIIT new energy vehicle mandate enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
Electric LCV Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Cryogenic Liquid Transport Vehicle Market
Commercial Vehicles
Modular Trailer Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Spain Light Commercial Vehicles Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
Heavy Haulage Trucks Market
Commercial Vehicles
Heavy-Duty Trucks Market