
 Asia Pacific Non Passenger Vehicle Market | 2026-2036
Asia Pacific Non Passenger Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Non Passenger Vehicle Market Outlook
Chinese heavy-duty truck manufacturing clusters is recalibrating output mixes toward new energy platforms under national dual carbon mandates. FAW leverages its Jiefang brand scale to dominate domestic electric truck trials across northern corridor routes. Tata Motors anchors India's medium and heavy commercial vehicle segment through its Pune and Jamshedpur production bases. BYD sustains battery-electric bus leadership with municipal fleet deployments in Shenzhen and Jakarta.
Asia Pacific non passenger vehicles encompass commercial and industrial motor vehicles engineered for freight, construction, agriculture, and public transit operations rather than personal transport, typically featuring gross vehicle weight ratings exceeding 3.5 tonnes and powertrains optimized for torque durability over passenger comfort. Diesel configurations retain installed-base dominance across long-haul trucking and mining applications, though electric powertrains are penetrating urban bus and last-mile van segments where battery swap infrastructure reduces downtime. Construction and logistics applications generate the steepest volume growth as e-commerce fulfillment networks and megaproject pipelines across Indonesia and Vietnam expand fleet renewals. Government end users represent a concentrated margin pool given tender specifications requiring domestic content thresholds and multi-year service contracts.
China's MIIT enforces new energy vehicle production quotas that bind domestic manufacturers to escalating electric commercial vehicle output shares. India's BIS certification and CEA grid-integration standards shape charging infrastructure compatibility for electric bus and truck deployments. Japan's METI fuel-efficiency benchmarks for heavy vehicles redirect Isuzu and Mitsubishi Fuso R&D spending toward hybrid architectures. Stakeholders must monitor how ASEAN harmonization of commercial vehicle emission protocols alters cross-border fleet procurement criteria.
Market Dynamics
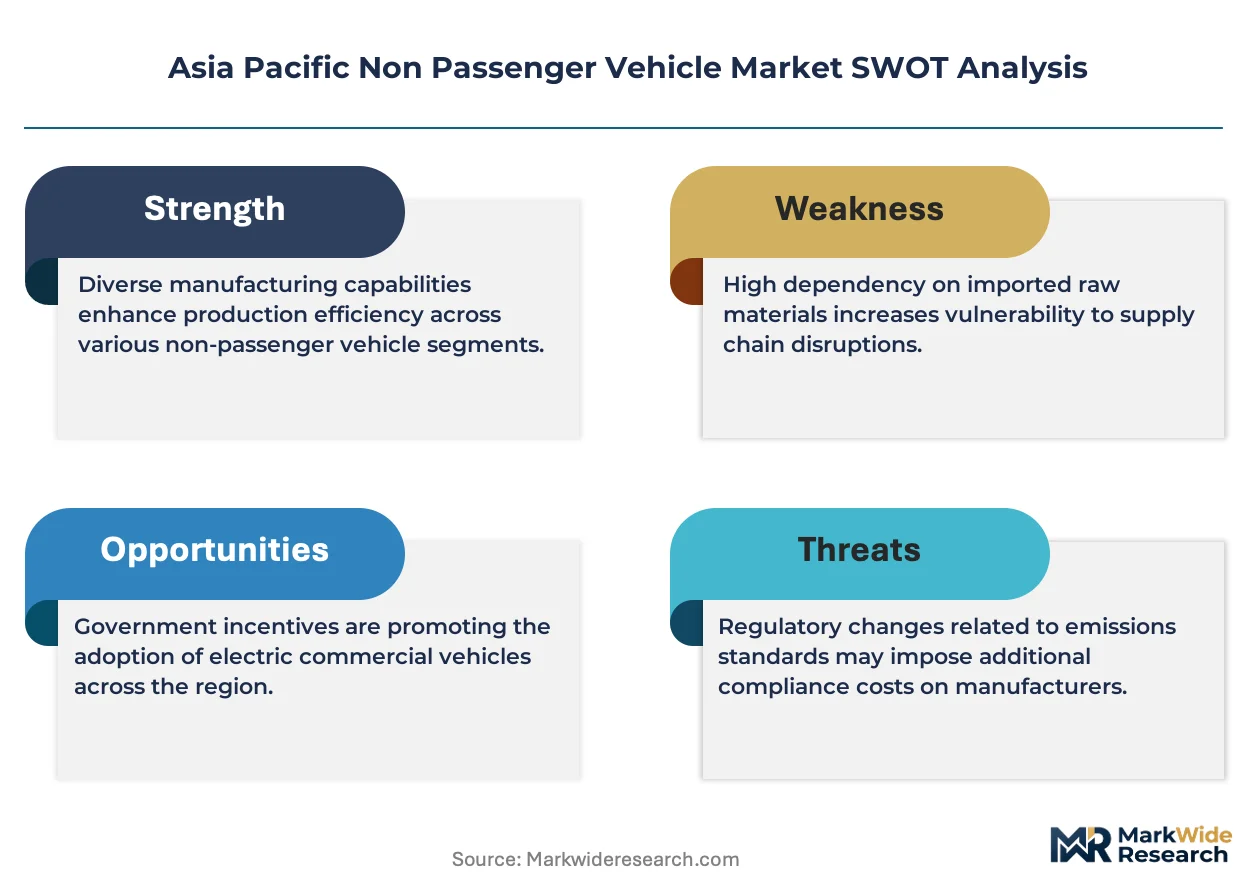
China's dual carbon mandates and India's PLI scheme are forcing manufacturers to reconfigure powertrain portfolios at unprecedented speed, converting regulatory pressure into capital allocation decisions that reshape supplier obligations across the entire regional value chain.
Growth Catalysts
- Battery swap infrastructure:Station networks along Indonesia's Java corridor and Vietnam's Hanoi-Ho Chi Minh route are eliminating range anxiety for electric truck operators. Municipal procurement guidelines in Shenzhen and Jakarta now mandate swap-compatible architectures.
- Construction and logistics applications:E-commerce fulfillment networks across Southeast Asia are accelerating fleet renewal cycles. Megaproject pipelines in Indonesia and Vietnam are generating concentrated demand for heavy-duty equipment with emission-compliant powertrains.
- CEA grid-integration standards:India's Central Electricity Authority protocols are standardizing charging infrastructure for electric bus and truck deployments. This regulatory clarity is unlocking utility-scale investment in depot electrification.
Market Restraints
- Lithium-ion cell supply concentration:Cathode precursor processing clusters in specific East Asian geographies create input vulnerability for regional battery pack assembly. Any disruption propagates through commercial vehicle production schedules.
- Diesel installed-base dominance:Long-haul trucking and mining applications retain entrenched fossil fuel infrastructure. Conversion economics remain unfavorable for assets with residual operational life exceeding five years.
- BIS certification timelines:India's Bureau of Indian Standards testing protocols for electric commercial vehicles extend product launch windows. Certification bottlenecks delay fleet operator procurement decisions.
Strategic Opportunities
- Vietnam's central coast industrial zones:Underpenetrated heavy vehicle markets between Da Nang and Quy Nhon present first-mover advantages for electric truck distributors. Port modernization projects are creating anchor demand.
- Hybrid architecture development:Japan's METI fuel-efficiency benchmarks are redirecting Isuzu and Mitsubishi Fuso R&D spending. Technology convergence between diesel range-extenders and electric traction motors offers interim compliance pathways.
- Government tender specifications:Domestic content thresholds and multi-year service contracts in Indian and Indonesian public procurement create margin pools. Channel innovation through fleet-as-a-service models captures recurring revenue streams.
Industry Challenges
- High-voltage systems engineering talent:Shortages of power electronics specialists and battery thermal management engineers constrain electric commercial vehicle program scaling. Technical workforce development lags behind production targets.
- Legacy fleet integration complexity:Depot charging infrastructure must coexist with existing diesel maintenance workflows. Operational retraining and software interoperability create execution friction for mixed-fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Non Passenger Vehicle Market |
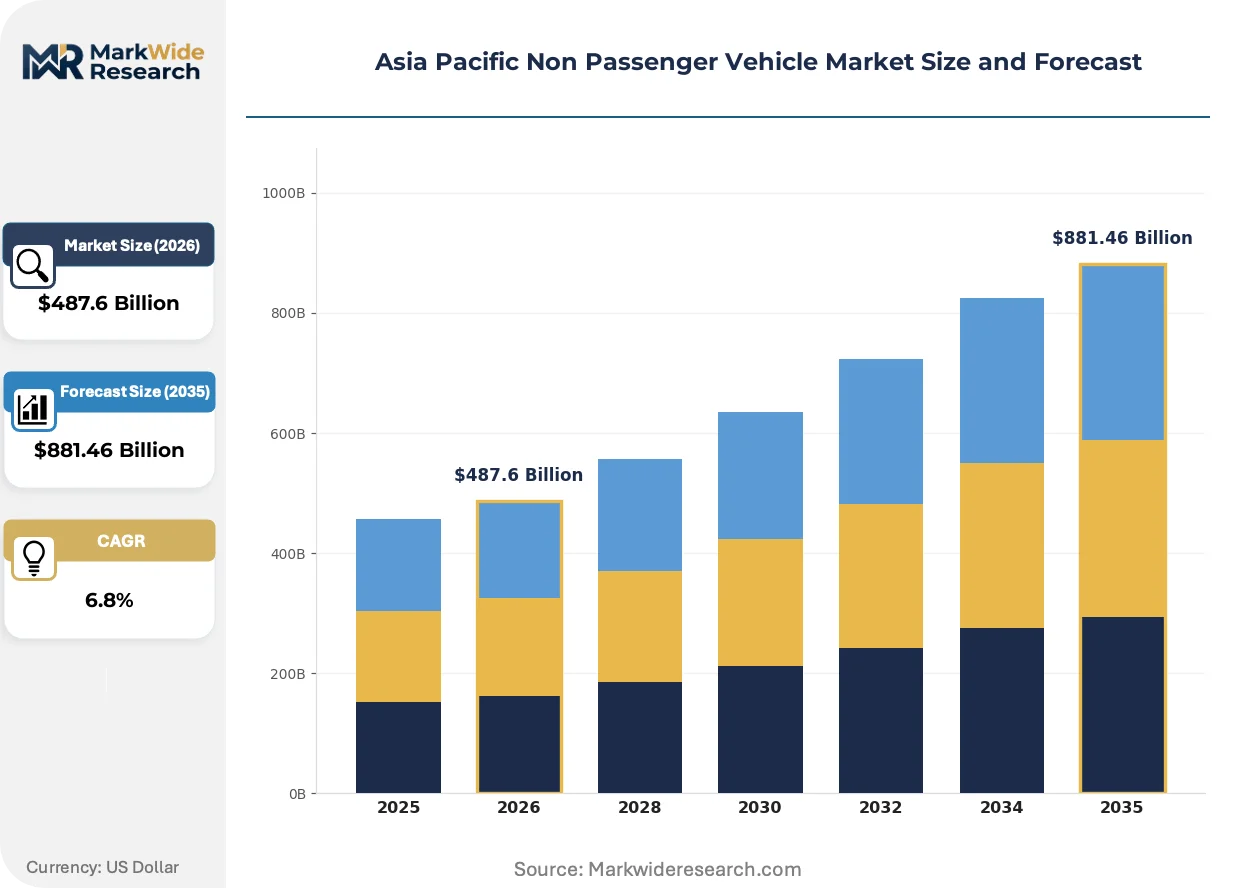
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Trucks, Buses, Vans, Trailers Fuel Type: Diesel, Electric, CNG, LPG Application: Construction, Agriculture, Logistics, Public Transport End User: Government, Enterprises, Freight Companies, Leasing Firms |
| Companies Covered | FAW, Dongfeng, SAIC, Foton, BYD, Toyota (Hino), Isuzu, Mitsubishi Fuso, Tata Motors, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Non Passenger Vehicle Market Strategic Shifts
Powertrain electrification is penetrating commercial vehicle segments where duty cycles and infrastructure economics finally align, while regulatory mandates compress transition timelines beyond what pure market signals would dictate.
Solid-state battery prototyping is expanding into medium-duty delivery van applications where energy density requirements are less extreme than long-haul trucking. Logistics operators in South Korea and Japan are piloting these cells for urban routes with predictable stop-and-go patterns. The technology is expanding into segments previously reserved for conventional lithium-ion, compressing the performance gap between passenger and commercial vehicle battery specifications.
China's MIIT new energy vehicle production quotas bind domestic manufacturers to escalating electric commercial vehicle output shares. The policy mechanism creates compliance-driven demand that outpaces organic fleet economics. Heavy-duty truck assemblers in Shandong and Hubei provinces are responding by accelerating platform conversions ahead of schedule.
Fleet procurement committees are consolidating vendor relationships around integrated powertrain and charging infrastructure providers. Single-source accountability is displacing fragmented supplier management for electric bus and truck acquisitions. This concentration is most visible in Indian state transport undertakings negotiating statewide electrification contracts.
Asia Pacific Non Passenger Vehicle Market Segmentation
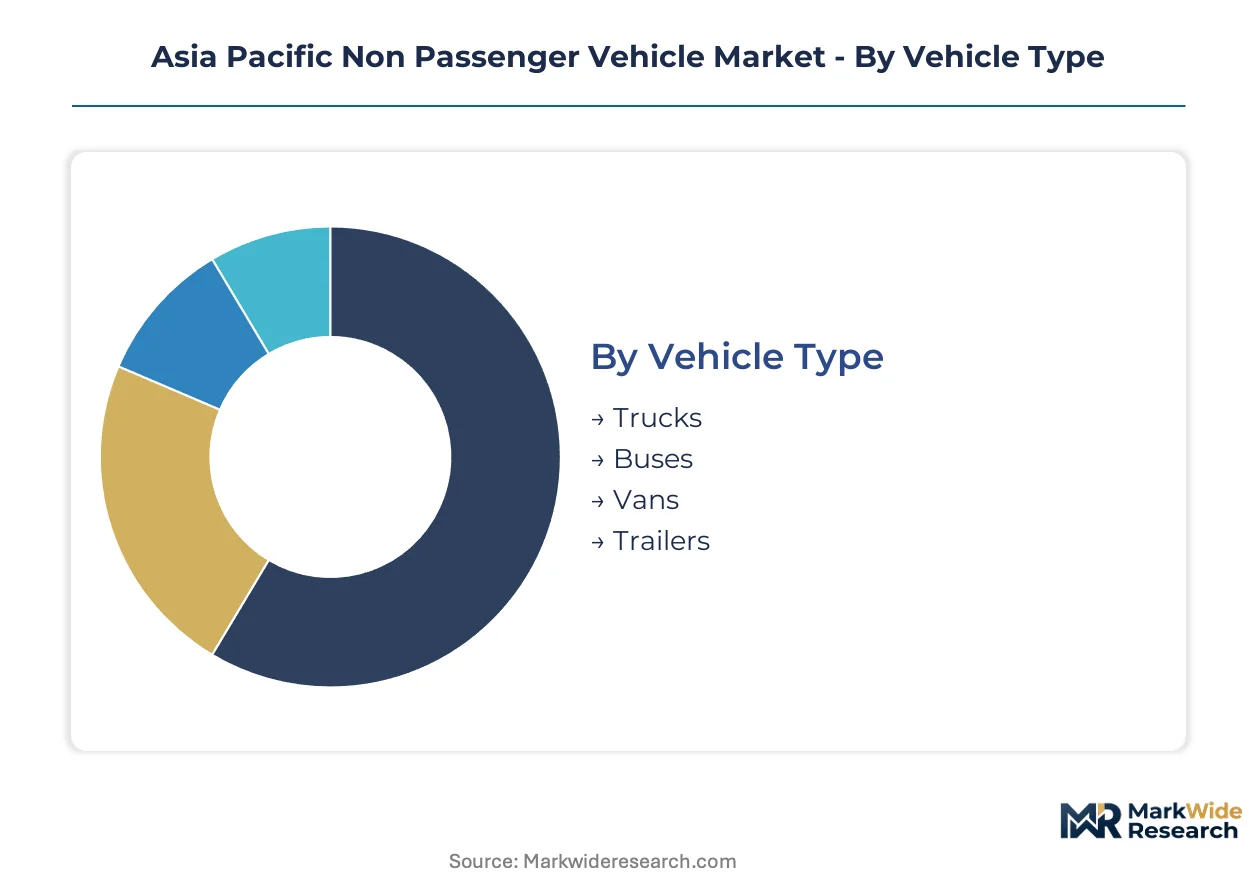
Segmentation in the Asia Pacific non passenger vehicle market reveals how regulatory frameworks and duty-cycle economics fragment procurement patterns. Certification requirements from India's BIS, China's MIIT, and Japan's METI create divergent compliance pathways that reshape competitive positioning across vehicle categories and fuel technologies.
Vehicle Type:
Certification burdens vary sharply: trucks face China's MIIT new energy production quotas, buses trigger municipal tender specifications with domestic content thresholds, vans navigate India's BIS extended testing timelines, and trailers encounter ASEAN cross-border harmonization protocols.
- Trucks:Heavy and medium-duty configurations dominate freight corridors from Maharashtra to Gujarat and China's northern logistics routes. MIIT quotas are forcing Shandong and Hubei assemblers toward accelerated platform conversions ahead of schedule.
- Buses:Battery-electric and hybrid architectures serve municipal fleet deployments in Shenzhen and Jakarta. Swap-compatible designs are now mandatory under procurement guidelines in both cities, eliminating range anxiety for high-frequency urban routes.
- Vans:Last-mile delivery applications across Southeast Asian e-commerce networks drive compact electric variants. Indonesia's Java corridor battery swap infrastructure reduces operational downtime for fleet operators.
- Trailers:Intermodal freight equipment connects port modernization projects along Vietnam's central coast. Cross-border ASEAN emission protocol harmonization is altering fleet procurement criteria for regional logistics operators.
Leading the category by volume: Trucks. Growing fastest: Buses.
Fuel Type:
Cost tier stratification separates established diesel infrastructure from emerging electric platforms, with transitional fuels occupying intermediate investment horizons.
- Diesel:Retains installed-base dominance across long-haul trucking and mining applications where conversion economics remain unfavorable for assets with residual operational life exceeding five years.
- Electric:Penetrating urban bus and last-mile van segments where battery swap infrastructure reduces downtime. China's dual carbon mandates and India's CEA grid-integration standards are unlocking utility-scale depot electrification investment.
- CNG:Serves municipal refuse collection and urban distribution fleets in Indian cities with established pipeline distribution networks. Lower capital cost than electric alternatives attracts budget-constrained fleet operators.
- LPG:Propane configurations persist in specific Southeast Asian markets with mature refueling infrastructure. Limited growth trajectory as electric alternatives achieve cost parity in light commercial applications.
Highest certification burden: Electric. Lowest total cost of ownership trajectory: Electric.
Application:
Volume concentration and margin structure diverge between project-driven construction demand and recurring logistics fleet renewals.
- Construction:Heavy-duty equipment demand concentrates in Indonesia and Vietnam megaproject pipelines. Emission-compliant powertrains are becoming mandatory for government-contracted infrastructure development.
- Agriculture:Tractor and harvester configurations serve plantation operations across Malaysia and Thailand. Diesel retention is strongest here due to remote operational locations and limited charging infrastructure.
- Logistics:E-commerce fulfillment networks across Southeast Asia are accelerating fleet renewal cycles. Battery-electric vans and medium-duty trucks are penetrating urban distribution routes first.
- Public Transport:State transport undertakings in India are consolidating vendor relationships around integrated powertrain and charging infrastructure providers. Single-source accountability is displacing fragmented supplier management.
Steepest volume expansion: Logistics. Highest margin concentration: Public Transport.
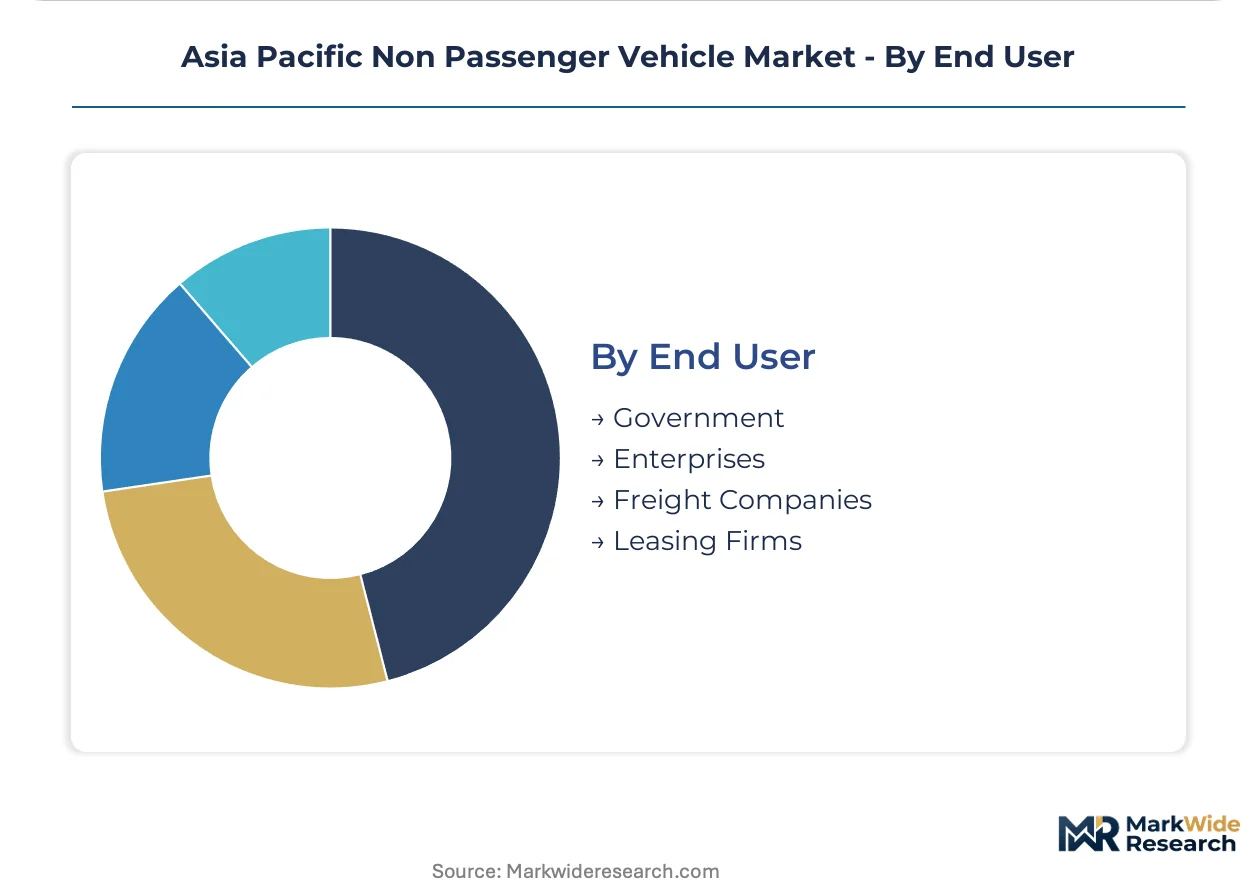
End User:
Procurement authority and contract structure create distinct commercial dynamics across public and private fleet operators.
- Government:Tender specifications requiring domestic content thresholds and multi-year service contracts generate concentrated margin pools. Indian and Indonesian public procurement channels are prioritizing fleet-as-a-service models.
- Enterprises:Corporate fleet operators in manufacturing and retail sectors are consolidating vendor relationships. Total cost of ownership calculations are displacing upfront capital cost as primary decision criteria.
- Freight Companies:Asset-heavy logistics operators face legacy fleet integration complexity as depot charging infrastructure must coexist with existing diesel maintenance workflows.
- Leasing Firms:Fleet-as-a-service providers are capturing recurring revenue streams through channel innovation. Residual value risk for electric commercial vehicles remains a constraint on balance sheet expansion.
Longest contract duration: Government. Fastest procurement cycle acceleration: Leasing Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate processing clusters in Qinghai and Sichuan provinces anchor China's battery supply chain dominance across the Asia Pacific non passenger vehicle ecosystem.
China
MIIT production quotas bind Shandong and Hubei heavy-duty truck assemblers to accelerated electric platform conversions. The dual carbon mandate forces state-owned enterprises to reconfigure output mixes ahead of organic fleet economics. Shenzhen anchors municipal bus electrification with swap-compatible procurement mandates.
India
The western industrial corridor from Maharashtra to Gujarat concentrates logistics fleet procurement of electric commercial vehicles under PLI scheme incentives. BIS certification timelines extend product launch windows for domestic manufacturers. Pune and Jamshedpur production bases anchor Tata Motors' medium and heavy commercial vehicle segment presence.
Japan
METI fuel-efficiency benchmarks redirect Isuzu and Mitsubishi Fuso R&D spending toward hybrid architectures for heavy vehicle compliance. Kanto region engineering centers develop range-extender systems bridging diesel retention and electric transition. Nagoya-area suppliers concentrate power electronics manufacturing for regional OEM integration.
Indonesia
Battery swap station networks along the Java corridor eliminate range anxiety for electric truck operators serving Jakarta-Surabaya logistics routes. Municipal procurement guidelines now mandate swap-compatible architectures for public fleet renewals. Port modernization projects in Surabaya generate anchor demand for emission-compliant heavy equipment.
Vietnam
Underpenetrated heavy vehicle markets between Da Nang and Quy Nhon present first-mover advantages for electric truck distributors targeting central coast industrial zones. Hanoi-Ho Chi Minh route infrastructure investments reduce operational downtime through depot electrification. Megaproject pipelines across northern provinces accelerate construction equipment fleet renewals.
Asia Pacific Non Passenger Vehicle Market Competitive Environment
Global majors compete with regional champions across powertrain technology and fleet service integration, producing a tiered structure where scale advantages in battery manufacturing clash with localized aftermarket capabilities. Market concentration varies by segment: bus electrification favors integrated platform providers, while trucking retains fragmented supplier relationships. Two strategic archetypes dominate—state-backed conglomerates with captive cell supply and independent assemblers relying on external battery procurement. Competitive moves center on vertical integration into cathode processing and strategic partnerships for swap infrastructure deployment.
Among Chinese state-owned vehicle manufacturers, FAW, Dongfeng, and BYD occupy positions that exemplify the integrated conglomerate archetype, leveraging domestic battery supply chains and MIIT quota compliance to anchor regional competitive positioning. These entities represent the scale-driven tier where platform conversion timelines and fleet-as-a-service model development determine market access.
| Leading Market Players |
|---|
| FAW |
| Dongfeng |
| SAIC |
| Foton |
| BYD |
| Toyota (Hino) |
| Isuzu |
| Mitsubishi Fuso |
| Tata Motors |
| Others |
Value Chain & Pricing Dynamics
Battery-electric platform conversions across China's Shandong and Hubei manufacturing clusters are compressing powertrain cost curves while redistributing margin capture toward cathode precursor processors in Qinghai and Sichuan provinces. This simultaneous cost reduction and supply concentration is creating divergent pricing power between integrated state-owned assemblers and independent manufacturers dependent on external cell procurement.
Pricing Analysis
Warranty and service bundling separates state transport undertaking contracts from unbundled enterprise fleet transactions. Three-tier pricing structure across premium, standard, and economy levels reflects MIIT quota compliance tiers, battery swap compatibility, and domestic content thresholds. Price compression runs through light commercial van segments as BYD and Foton scale production. Government tender participants show lowest price sensitivity due to multi-year service contract security, while freight companies face acute capital constraint pressure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Indian state transport undertakings and Chinese municipal fleet operators, while independent distributors serve fragmented Southeast Asian logistics buyers. Cathode precursor processing concentrates in China, South Korea, and Japan, with lithium carbonate refining anchored in Qinghai and Sichuan. Supply chains draw from nickel laterite deposits in Indonesia and cobalt hydroxide from the DRC. Single-source vulnerability in high-voltage power electronics creates procurement risk for medium-duty electric truck programs. Distribution runs through captive OEM networks and third-party fleet-as-a-service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT production quotas and India's PLI scheme compliance costs are constructing barrier-to-entry moats that favor incumbent manufacturers with established certification pathways and captive battery supply arrangements.
For Market Incumbents: Extend platform standardization across medium and heavy-duty segments to amortize R&D costs against MIIT quota volumes. Deepen backward integration into cathode processing to secure margin capture against lithium price volatility. Consolidate aftermarket service networks before independent swap infrastructure operators fragment customer relationships. For New Entrants and Emerging Players: Underserved central coast industrial zones between Da Nang and Quy Nhon offer anchor demand from Vietnam's port modernization projects with limited incumbent presence. Hybrid architecture development for Japanese METI compliance creates technology licensing opportunities without full platform investment. Pursue fleet-as-a-service partnerships with Indonesian logistics operators to bypass upfront capital barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in state-backed conglomerate acquisition of independent swap infrastructure operators and technology licensing platforms. Long-term viability favors entities with captive cell supply and multi-year government service contracts. Watch CEA grid-integration standard adoption rates across Indian states as inflection indicator for utility-scale depot electrification investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cathode precursor allocation from Qinghai processors for MIIT quota compliance. |
| Swap Infrastructure Partnership | Deploys station networks along Indonesia's Java corridor per Jakarta procurement mandates. |
| Platform Standardization | Unifies medium-duty architectures across Shandong and Hubei assembly plants. |
| Backward Integration | Captures lithium carbonate refining margin in Sichuan province cell manufacturing. |
| Software-Defined Vehicle Investment | Enables fleet telematics integration for Indian state transport undertaking contracts. |
Study Parameters
Document review covered MIIT production quota filings, India's BIS certification registries, and ASEAN commercial vehicle emission protocols, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, state transport undertaking fleet managers, and battery swap infrastructure operators. Secondary sources included vehicle production databases, IHS Markit registration data, customs trade records, and utility-scale charging infrastructure investment disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Unit shipment and value estimates were generated through multi-dimensional segmentation modeling across vehicle class, propulsion architecture, gross vehicle weight rating, and regional production cluster. CAGRs were derived from regression analysis of historical fleet renewal cycles against regulatory mandate implementation timelines. Key inputs incorporated PLI scheme incentive phase-out schedules, lithium carbonate price trajectories, and municipal tender award patterns.
Revisions become necessary when MIIT quota enforcement intensity shifts, BIS certification timelines extend unexpectedly, or ASEAN emission protocol harmonization accelerates beyond modeled assumptions. Forecasts reflect documented assumptions regarding battery cost decline curves and swap infrastructure deployment rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Commercial Vehicle Foundation Brakes Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Cryogenic Liquid Transport Vehicle Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market
Commercial Vehicles
North America Van Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Industrial Vehicles Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
Chile Commercial Vehicle Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
United States Commercial Vehicles Market