
 Truck Market | 2026-2036
Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Market Outlook
A capital-intensity divergence between integrated powertrain manufacturers and assembly-focused builders is redrawing competitive boundaries in the truck industry. Freightliner Trucks leverages captive engine and axle production to sustain margin control across North American highway segments. Volvo Trucks anchors its position through proprietary safety systems and connected fleet services. DONGFENG Commercial Vehicle competes on state-backed manufacturing scale and domestic distribution density within China.
A truck is a motorized commercial vehicle engineered with a chassis-cab architecture, designed to carry payloads exceeding one ton through dedicated cargo bodies or fifth-wheel coupling systems, with power ratings spanning 150 to 600+ horsepower depending on duty classification. Its primary commercial purpose is the overland movement of goods, raw materials, and specialized equipment across supply chain nodes. Heavy-duty trucks command the dominant share of industry revenue due to long-haul freight economics and replacement cycles, while electric powertrains represent the fastest-expanding fuel category as battery energy density improves and charging corridor networks mature. Logistics providers constitute the most concentrated end-user segment, driven by contracted fleet turnover and last-mile expansion requirements.
EPA greenhouse gas standards for medium and heavy-duty vehicles, Euro VII emission limits under ECHA frameworks, and China's MIIT new energy vehicle mandates are collectively accelerating powertrain diversification and compliance R&D spending. NHTSA safety regulations and ISO 26262 functional safety standards further shape product design priorities and supplier qualification barriers. Stakeholders must monitor regulatory phase-in calendars against battery supply chain readiness and charging infrastructure deployment timelines.
Market Dynamics
EPA greenhouse gas standards and Euro VII emission limits are compressing diesel engine development cycles while battery-electric powertrains scale manufacturing capacity. Fleet operators face simultaneous pressure to decarbonize and maintain total cost of ownership parity.
Growth Catalysts
- E-commerce fulfillment networks:Logistics providers are accelerating fleet renewals as last-mile delivery density intensifies in urban corridors. Warehouse-to-doorstep velocity requirements favor newer truck specifications.
- China MIIT new energy vehicle mandates:Domestic production quotas for zero-emission commercial vehicles are channeling state-backed capital into battery supply chain expansion. Local OEMs capture preferential procurement positioning.
- Battery energy density improvements:Cell chemistry advances are extending electric truck range thresholds toward heavy-duty highway viability. Charging corridor investments along interstate freight routes follow.
Market Restraints
- Lithium and cobalt price volatility:Raw material input costs for battery packs create margin compression for electric powertrain assemblers. Long-term supply agreements remain scarce.
- European foundry capacity concentration:Precision casting for engine blocks and axle housings clusters in Germany and Poland. Geopolitical disruption risks propagate through component lead times.
- Charging infrastructure deployment lag:Grid interconnection timelines and utility upgrade approvals delay depot electrification for fleet operators. Federal permitting processes extend project horizons.
Strategic Opportunities
- India commercial vehicle electrification:PLI scheme incentives for domestic manufacturing of electric trucks and buses attract joint venture capital. State transport corporation tenders signal volume commitment.
- Vehicle-to-grid integration:Bidirectional charging protocols enable fleet batteries to participate in grid stabilization services. Utility rate structures in California and Texas reward dispatchable capacity.
- Autonomous convoying on designated corridors:Platooning technology reduces aerodynamic drag and driver hour constraints. Arizona and Nevada regulatory frameworks permit supervised multi-truck formations.
Industry Challenges
- High-voltage technician certification gaps:Electric powertrain maintenance requires specialized training beyond conventional diesel mechanic credentials. Vocational program expansion lags fleet electrification timelines.
- ISO 26262 functional safety compliance:Software validation for autonomous and connected systems extends development cycles. Third-party audit backlogs delay product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Market |
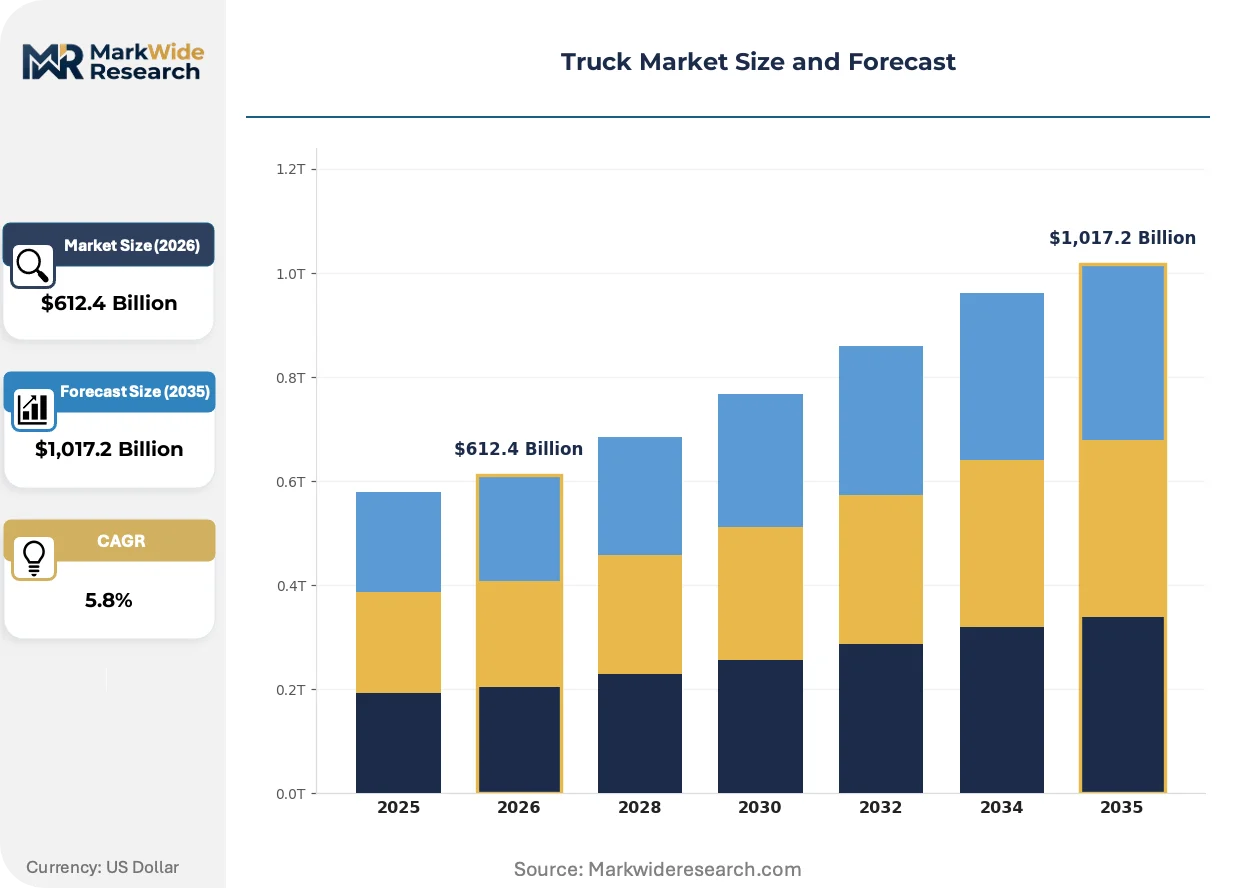
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,017.2 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light-Duty Trucks, Heavy-Duty Trucks, Medium-Duty Trucks, Pickup Trucks Fuel Type: Diesel, Gasoline, Electric, Hybrid End User: Construction Companies, Logistics Providers, Agricultural Sector, Government Body Style: Flatbed, Box Truck, Dump Truck, Tow Truck |
| Companies Covered | Kenworth, Western Star, Freightliner Trucks, Caterpillar, DONGFENG Commercial Vehicle, Mack Trucks, Volvo Trucks, BELAZ, Peterbilt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Market Strategic Shifts
Powertrain diversification is fragmenting established supplier relationships while digital fleet services create new revenue pools. Regulatory phase-in calendars are forcing synchronized investments across battery manufacturing, charging infrastructure, and vehicle platforms.
Modular battery pack architectures are fragmenting the traditional integrated powertrain supplier landscape. Logistics providers with mixed-duty fleets now specify swappable energy storage configurations rather than fixed-capacity systems. This standardization push enables third-party battery leasing models and separates vehicle asset ownership from energy storage capital.
Euro VII emission limits under ECHA frameworks are mandating real-world emissions monitoring through onboard sensors and telematics transmission. Engine manufacturers must redesign after-treatment systems for urban low-emission zone compliance. Heavy-duty urban delivery segments in Germany and the Netherlands face the most compressed retrofit timelines.
Fleet procurement committees now weight total cost of ownership metrics above upfront vehicle capital, compressing traditional dealer sales cycles. Subscription-based maintenance and energy-inclusive operating leases displace outright purchase in large logistics accounts. This preference shift is most pronounced among United States-based e-commerce fulfillment operators with predictable route density.
Truck Market Segmentation
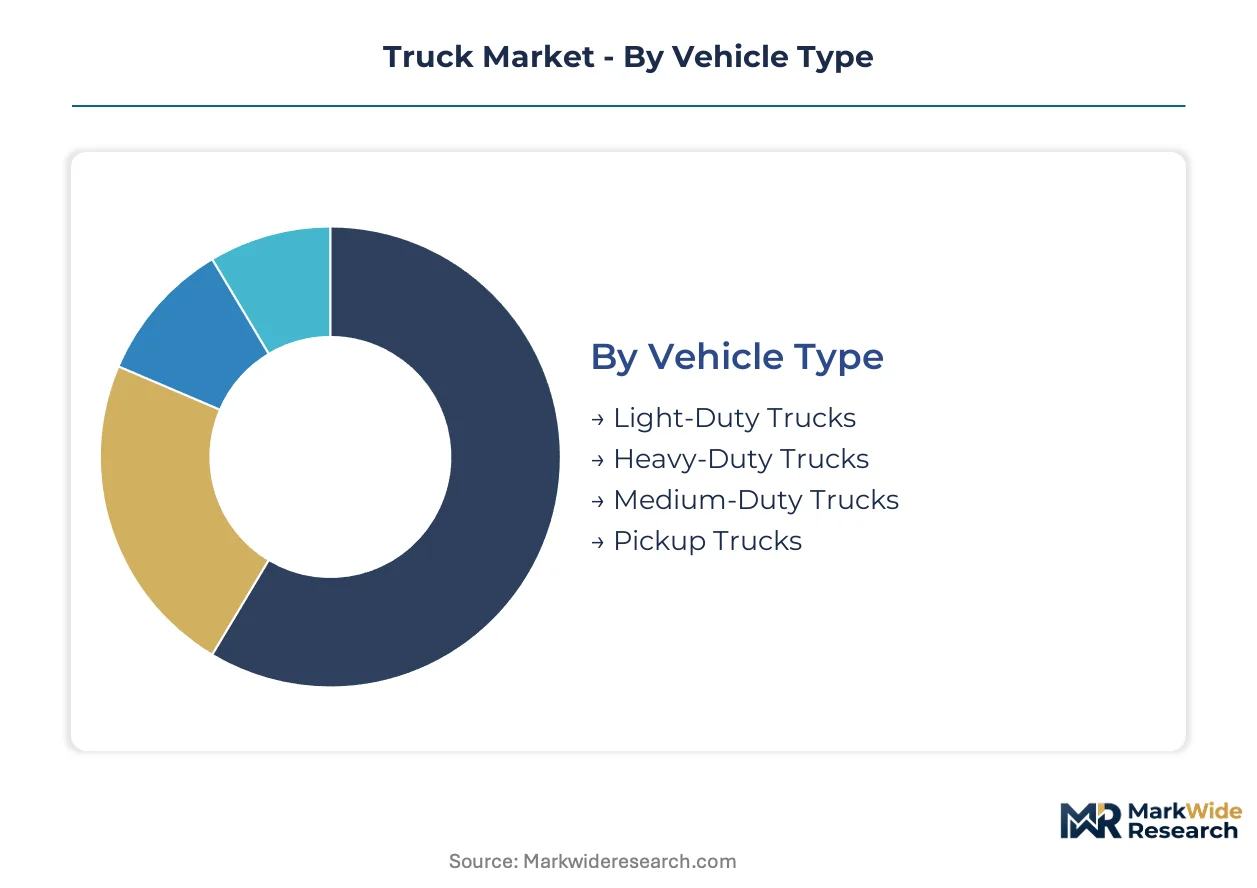
Truck market segmentation reveals how regulatory pressure and duty-cycle economics concentrate investment across vehicle architectures. Fleet procurement committees now weight compliance timelines and total cost of ownership parity when specifying segment requirements.
Vehicle Type:
EPA greenhouse gas standards and Euro VII emission limits apply differential stringency based on gross vehicle weight rating, compressing development cycles unevenly across classes.
- Heavy-Duty Trucks:These vehicles exceed 26,000 pounds gross vehicle weight rating with power ratings spanning 300 to 600+ horsepower for long-haul freight corridors. Demand concentrates among United States logistics providers facing EPA Phase 3 compliance deadlines and replacement cycle pressures from e-commerce fulfillment networks. Diesel powertrains still dominate this segment though battery-electric prototypes now demonstrate highway viability.
- Light-Duty Trucks:Vehicles under 8,500 pounds GVWR serve last-mile delivery and urban service applications with lower regulatory thresholds than heavy-duty classes. China MIIT new energy vehicle mandates channel state-backed capital into electric variants for domestic urban freight. Battery energy density improvements are extending range thresholds toward commercial viability in this weight class.
- Medium-Duty Trucks:Class 4-6 vehicles bridge urban delivery and regional distribution with 14,000 to 26,000 pound GVWR ratings. Vocational applications dominate procurement.
- Pickup Trucks:Light commercial variants serve contractor and fleet utility roles with open cargo beds and four-wheel-drive configurations. North American personal use volumes remain substantial.
Heavy-Duty Trucks handle the majority of throughput; Light-Duty Trucks are climbing the fastest on share as urban electrification accelerates.
Fuel Type:
Cost tier stratification separates incumbent diesel infrastructure from emerging electric capital requirements and hybrid transitional economics.
- Diesel:Compression-ignition engines with after-treatment systems for NOx and particulate compliance remain the baseline for long-haul freight economics. Euro VII mandates from ECHA are forcing redesign of exhaust after-treatment for real-world emissions monitoring. European foundry capacity concentration in Germany and Poland creates supply vulnerability for engine block castings.
- Electric:Battery-electric powertrains with 150-500+ kWh pack configurations are scaling manufacturing capacity alongside charging corridor investments. Lithium and cobalt price volatility creates margin compression for assemblers lacking long-term supply agreements. Grid interconnection timelines delay depot electrification for fleet operators in the United States.
- Gasoline:Spark-ignition engines dominate light-duty and pickup applications with lower upfront capital than diesel alternatives. Urban delivery fleets are gradually displacing this fuel category.
- Hybrid:Parallel and series-hybrid architectures bridge range anxiety and emissions compliance for medium-duty vocational cycles. Technology costs remain above diesel parity.
Diesel still moves the most ton-miles; Electric is gaining share fastest as battery chemistry advances and charging infrastructure matures.
End User:
Application-specific duty cycles determine powertrain specifications and replacement timing across concentrated buyer segments.
- Logistics Providers:Contracted fleet operators with predictable route density and warehouse-to-doorstep velocity requirements. E-commerce fulfillment networks in the United States are accelerating renewal cycles for last-mile specifications. Subscription-based maintenance and energy-inclusive operating leases now displace outright purchase in large accounts.
- Construction Companies:Vocational buyers specifying dump bodies and chassis-cab architectures for material movement. Project-based procurement creates lumpy demand patterns tied to infrastructure investment cycles.
- Agricultural Sector:Seasonal duty cycles with grain transport and equipment hauling requirements. Rural charging infrastructure gaps constrain electric adoption.
- Government:Municipal and state procurement with domestic content preferences and emissions mandates. California Air Resources Board regulations influence specification requirements.
Logistics Providers account for the dominant procurement volume; Construction Companies are expanding fastest as infrastructure stimulus channels through.
Body Style:
Customer type and cargo security requirements segment the market between open-deck versatility and enclosed protection.
- Box Truck:Enclosed cargo bodies with roll-up or swing doors protect freight from weather and theft in urban delivery applications. Last-mile density requirements from e-commerce operators favor this configuration for parcel and appliance delivery. Refrigerated variants serve foodservice distribution with specialized insulation and compressor systems.
- Flatbed:Open deck configurations with stake pockets and tie-down points accommodate oversized and irregular loads. Construction and specialized freight applications dominate demand.
- Dump Truck:Hydraulic lift mechanisms with reinforced bodies for aggregate and demolition material movement. Vocational cycles concentrate in infrastructure-heavy geographies.
- Tow Truck:Wrecker and carrier configurations for vehicle recovery and transport services. Accident frequency and fleet age drive replacement demand.
Box Truck handles the majority of parcel throughput; Flatbed is expanding most quickly as construction activity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freight corridors in the United States, China, and Germany concentrate the heaviest truck deployment, while emerging markets favor lighter configurations for last-mile density.
United States
EPA Phase 3 greenhouse gas standards compress heavy-duty diesel development cycles while logistics providers renew fleets for e-commerce fulfillment velocity. The Inflation Reduction Act channels investment into domestic battery supply chains and charging corridor buildout. The I-80 freight corridor linking Chicago to California anchors electrification pilot programs.
China
MIIT new energy vehicle mandates drive state-backed capital into zero-emission commercial vehicle production quotas. Domestic OEMs capture preferential procurement positioning through manufacturing scale and distribution density. The Yangtze River Delta manufacturing cluster around Shanghai concentrates battery-electric truck assembly capacity.
Germany
Euro VII emission limits under ECHA frameworks mandate real-world emissions monitoring through onboard sensors and telematics transmission. Foundry capacity concentration in Germany and Poland creates supply vulnerability for precision engine castings. The Rhine-Ruhr logistics corridor faces compressed retrofit timelines for urban low-emission zone compliance.
India
PLI scheme incentives attract joint venture capital for domestic electric truck and bus manufacturing. State transport corporation tenders signal volume commitment for fleet electrification. The Delhi-Mumbai Industrial Corridor infrastructure investment intensifies demand for heavy-duty vocational configurations.
Japan
METI regulations shape fuel efficiency standards and hydrogen infrastructure deployment for commercial vehicle applications. Domestic OEMs prioritize hybrid architectures bridging range requirements and emissions compliance. The Chubu region around Nagoya concentrates powertrain component manufacturing and testing facilities.
Truck Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive engine production separating margin-sustainable players from assembly-dependent competitors. Consolidation pressure concentrates around powertrain control and connected fleet service platforms. Three archetypes dominate: vertically integrated highway specialists, state-scaled domestic champions, and safety-system differentiation leaders. Competitive moves center on backward integration into battery supply and strategic partnerships for charging infrastructure access.
Among North American highway specialists, Kenworth, Peterbilt, and Freightliner Trucks exemplify the integrated archetype through captive powertrain and axle production. These manufacturers anchor positions across long-haul freight segments where total cost of ownership metrics drive procurement committee decisions. DONGFENG Commercial Vehicle occupies the state-scaled champion position within China's domestic market, leveraging manufacturing scale and distribution density under MIIT mandate alignment. Volvo Trucks represents the safety-system differentiation vector, with proprietary connected fleet services creating recurring revenue streams beyond vehicle capital sales.
| Leading Market Players |
|---|
| Kenworth |
| Western Star |
| Freightliner Trucks |
| Caterpillar |
| DONGFENG Commercial Vehicle |
| Mack Trucks |
| Volvo Trucks |
| BELAZ |
| Peterbilt |
| Others |
Value Chain & Pricing Dynamics
Battery cell chemistry substitution from nickel-cobalt-manganese to lithium-iron-phosphate formulations simultaneously redraws raw material sourcing geography toward China and compresses pack-level pricing economics for electric truck assemblers lacking long-term cathode supply agreements.
Pricing Analysis
After-sales service contracts and energy-inclusive operating leases now generate the majority of lifetime value capture across heavy-duty truck procurement. Three-tier pricing structure across premium, standard, and economy levels separates integrated powertrain manufacturers with captive engine production from assembly-dependent builders sourcing from Tier 1 suppliers. Price differentiation hinges on EPA Phase 3 compliance certification tier and fleet-scale volume commitments. Cost compression in battery-electric powertrains is intensifying because lithium and cobalt price volatility propagates through pack assembly margins. Logistics providers with predictable route density demonstrate lowest price sensitivity, while vocational construction buyers exhibit highest capital-outlay responsiveness.
Supply Chain Analysis
Inventory lead times for precision engine block castings and axle housings have extended due to European foundry capacity concentration in Germany and Poland. Geographic supply concentration centers on China for battery cell manufacturing, South Korea for cathode active materials, and Germany for precision powertrain components. Raw material dependencies draw from lithium carbonate, cobalt sulfate, and high-grade aluminum alloy feedstocks. Single-source vulnerability in cathode precursor processing creates systemic exposure to geopolitical disruption. Distribution runs through captive OEM dealer networks for heavy-duty highway segments and independent commercial vehicle distributors for vocational applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Phase 3 greenhouse gas standards and Euro VII emission limits constitute a simultaneous regulatory inflection compressing diesel development cycles while accelerating battery-electric powertrain disruption across freight corridors.
For Market Incumbents: Shield margin sustainability through backward integration into battery cell supply and captive charging infrastructure partnerships. Consolidate dealer network control to prevent disintermediation by subscription-based fleet service platforms. Prioritize ISO 26262 functional safety certification investment to maintain qualification barriers against emerging electric powertrain specialists. For New Entrants and Emerging Players: Anchor in medium-duty urban delivery segments where charging depot density and predictable route profiles minimize range anxiety barriers. Target India PLI scheme incentives for domestic electric truck manufacturing joint ventures. Pursue state transport corporation tender participation as the most penetrable volume channel. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed logistics technology platforms seeking fleet electrification exposure through vehicle-as-a-service integration. Long-term viability over the next decade hinges on powertrain control and charging corridor access rather than assembly scale alone. Monitor battery supply agreement announcement velocity as the critical inflection signal for OEM competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode procurement from Chinese or South Korean suppliers secures pack cost parity against diesel alternatives. |
| Charging Infrastructure Partnership | Depot electrification alliances with utility operators in California and Texas accelerate fleet conversion timelines. |
| Platform Standardization | Modular battery architectures enable third-party leasing models and separate vehicle ownership from energy storage capital. |
| Software-Defined Vehicle Investment | Proprietary connected fleet services generate recurring revenue streams beyond upfront vehicle capital sales. |
| Geographic Manufacturing Footprint | Domestic production alignment with MIIT mandates captures preferential procurement positioning within China. |
Study Parameters
A standing panel of fleet procurement directors, OEM platform engineers, Tier 1 supplier account managers, and charging infrastructure developers provided ongoing calibration throughout the study period. Primary interview findings triangulated against vehicle production databases, EPA regulatory filing records, MIIT new energy vehicle quota disclosures, and customs trade flow data. Bottom-up segment sizing and top-down macroeconomic anchoring ensured consistency across the analysis window.
Consistency checks validated volume and value outputs against IHS Markit registration data and OEM revenue disclosures across the projection horizon. The analytical framework modeled segmentation across vehicle class, propulsion architecture, duty cycle intensity, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for electric powertrain penetration and replacement cycle elasticity against freight demand indicators.
Decision-makers should treat outputs as directional under assumptions of battery energy density improvement continuity and charging corridor deployment schedules; material deviation in lithium supply constraints or grid interconnection timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Middle East Vacuum Truck Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Electric LCV Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Global Commercial Vehicles Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Electric Garbage Van Market