
 High-End Instant Noodles Market | 2026-2036
High-End Instant Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
High-End Instant Noodles Market Analysis
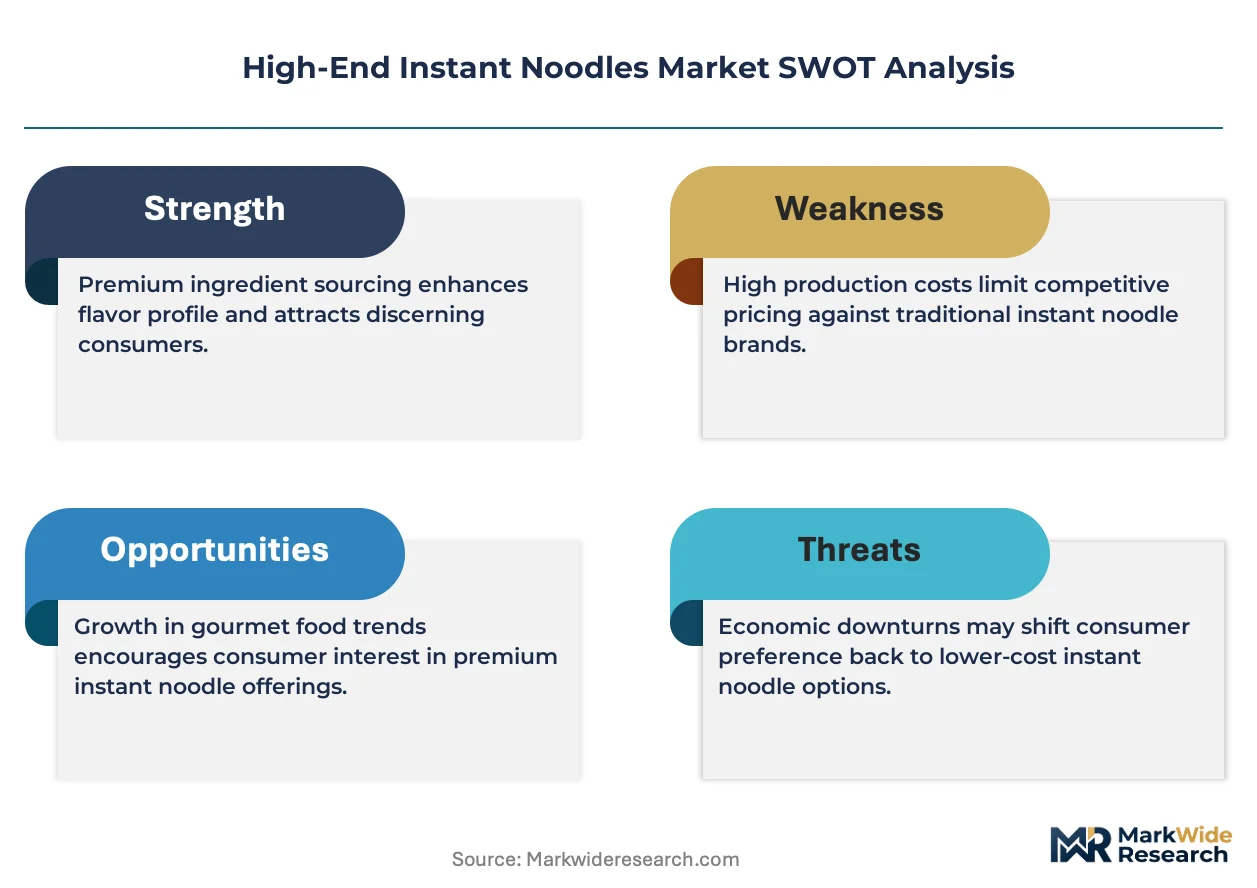
Specialty store distribution is narrowing as e-commerce platforms capture premium noodle sales. Nissin Foods Holdings leverages its R&D intensity to sustain innovation pipelines across Asian markets. Ajinomoto Co. anchors its position through umami technology leadership and backward integration into flavor compound production. Samyang Foods competes aggressively on viral spicy product lines that dominate social media-driven discovery channels.
High-end instant noodles denote wheat, rice, egg, or buckwheat-based products manufactured through steaming, flash-frying or air-drying processes, then paired with premium broth concentrates, freeze-dried proteins, and artisan flavor sachets for single-serve preparation in under five minutes. Wheat noodles occupy the largest volume share due to familiar texture profiles and scalable manufacturing, while buckwheat variants command the fastest expansion as health-positioned offerings attract gluten-avoidant consumers. Bowl packaging captures the highest margin pool by enabling complete meal solutions with included utensils and enhanced broth stability.
Japan's Consumer Affairs Agency enforces FOSHU and Foods with Nutrient Function Claims standards that shape permissible health-positioned marketing. South Korea's MFDS monitors sodium disclosure rules and additive thresholds that directly influence reformulation cycles. China's SAMR implements GB national food safety standards with escalating scrutiny on instant noodle labeling and oil quality specifications. Stakeholders must monitor how tightening sodium reduction mandates across East Asian regulators will force recipe architecture decisions before the next product development cycle.
Market Dynamics
Japan's FOSHU regulatory framework is forcing manufacturers to reformulate with functional ingredients, compressing traditional product development cycles while opening premium positioning for fortified variants.
Growth Catalysts
- Functional Food Mandates:Japan's Consumer Affairs Agency enforces FOSHU standards that reward manufacturers adding clinically validated nutrients, creating compliant premium tiers.
- Urban Millennial Demand:South Korea's dense metropolitan centers concentrate convenience-seeking consumers willing to pay for single-serve meal solutions with restaurant-quality broth profiles.
- Air-Drying Technology:Non-fried noodle production methods reduce oil content while preserving texture, aligning with health-positioned marketing claims in sodium-conscious markets.
Market Restraints
- Wheat Price Volatility:Input cost swings for durum and specialty wheat strains compress margin pools for mid-tier manufacturers lacking forward contracting capabilities.
- South Korean Supply Concentration:Samyang Foods and Nongshim control dominant share of spicy flavor innovation pipelines, creating barriers for new entrants seeking shelf placement.
- Sodium Disclosure Thresholds:South Korea's MFDS mandates front-of-package labeling that exposes reformulation gaps, forcing costly recipe architecture changes before revenue recovery.
Strategic Opportunities
- Buckwheat Gluten-Avoidant Positioning:Buckwheat variants command fastest expansion as health-conscious consumers in Japan and South Korea seek wheat alternatives with comparable mouthfeel.
- E-Commerce Premium Capture:Platform direct-to-consumer channels bypass specialty store gatekeepers, enabling smaller brands to build discovery through algorithmic recommendation engines.
- Freeze-Dried Protein Integration:Artisan protein sachets using lyophilization technology differentiate bowl-format offerings against standard fried-noodle competitors.
Industry Challenges
- Umami Compound Sourcing:Securing consistent supply of nucleotide-based flavor enhancers requires backward integration or captive relationships with Ajinomoto Co.'s production network.
- GB Standard Compliance:China's SAMR escalates scrutiny on oil quality specifications and additive disclosures, extending certification timelines for cross-border entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-End Instant Noodles Market |
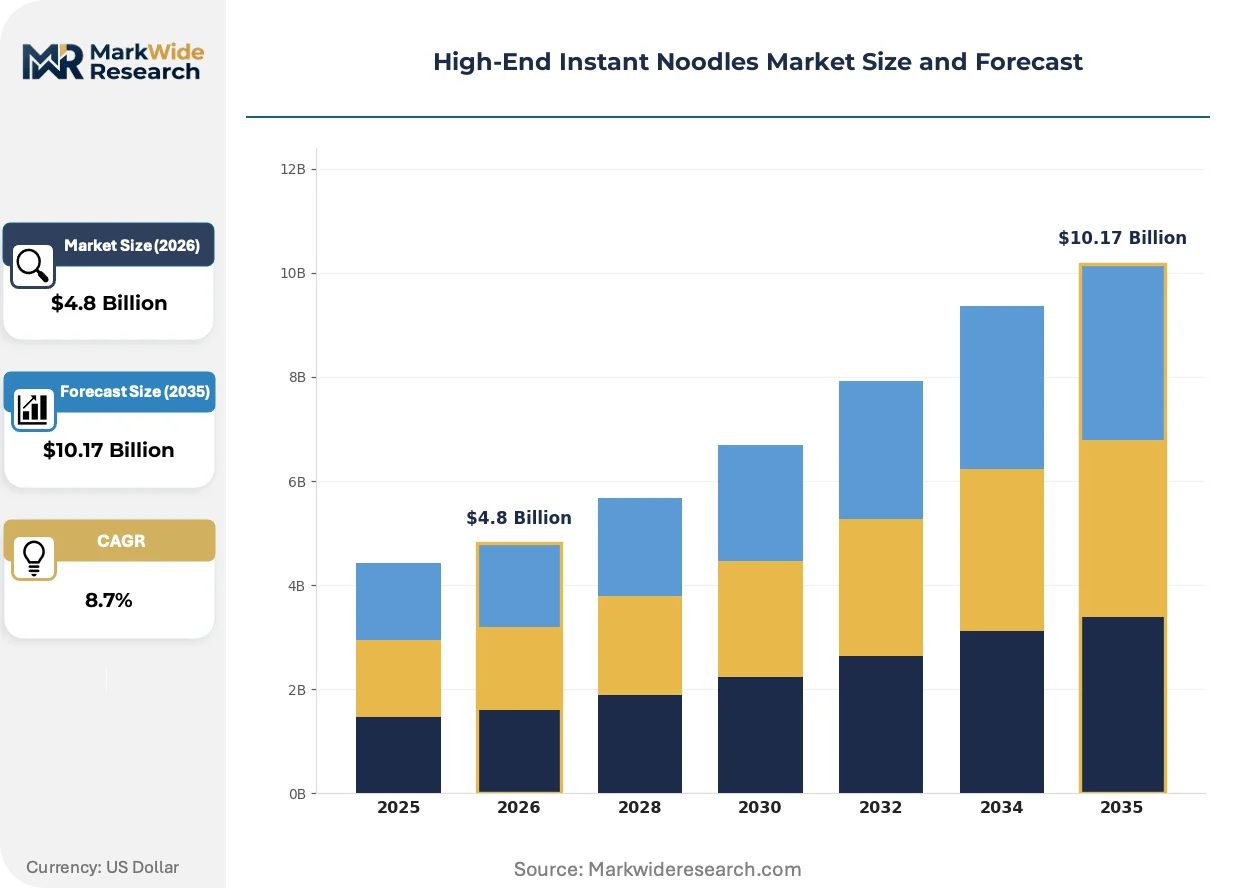
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rice Noodles, Egg Noodles, Wheat Noodles, Buckwheat Noodles Flavor Profile: Spicy, Savory, Sweet, Sour Packaging Type: Bowl, Cup, Sachet, Pouch Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores |
| Companies Covered | Nestlé S.A., Tingyi (International) Holdings Corp., Nissin Foods Holdings Co., Ltd., Ajinomoto Co., Inc., Samyang Foods, Nongshim Co., Ltd., PT Indofood CBP Sukses Makmur Tbk, Ottogi Corporation, Uni-President Enterprises Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-End Instant Noodles Market Emerging Trajectories
Reformulation pressures and channel migration are compressing traditional manufacturing assumptions while rewarding agile producers who can synchronize health claims with viral discovery mechanics.
Smart packaging embedded with freshness indicators and QR-linked preparation tutorials is digitizing the consumer experience for bowl-format products. Urban millennials in Seoul and Tokyo scan codes to access chef-curated customization options, collapsing the perceived gap between instant convenience and restaurant authenticity.
REACH chemical safety standards in Europe are restricting certain palm oil derivatives and synthetic antioxidants used in frying processes. Manufacturers serving export markets must validate alternative lipid stabilizers through ECHA-registered safety assessments, with wheat-noodle producers facing the steepest reformulation burden.
Social discovery now dominates trial generation for spicy flavor variants, with algorithmic recommendation engines on short-video platforms replacing traditional retail browsing. South Korean consumers aged 18-34 encounter new products through challenge-based content before encountering physical shelf placement, compressing the window between viral momentum and supply chain readiness.
High-End Instant Noodles Market Segmentation
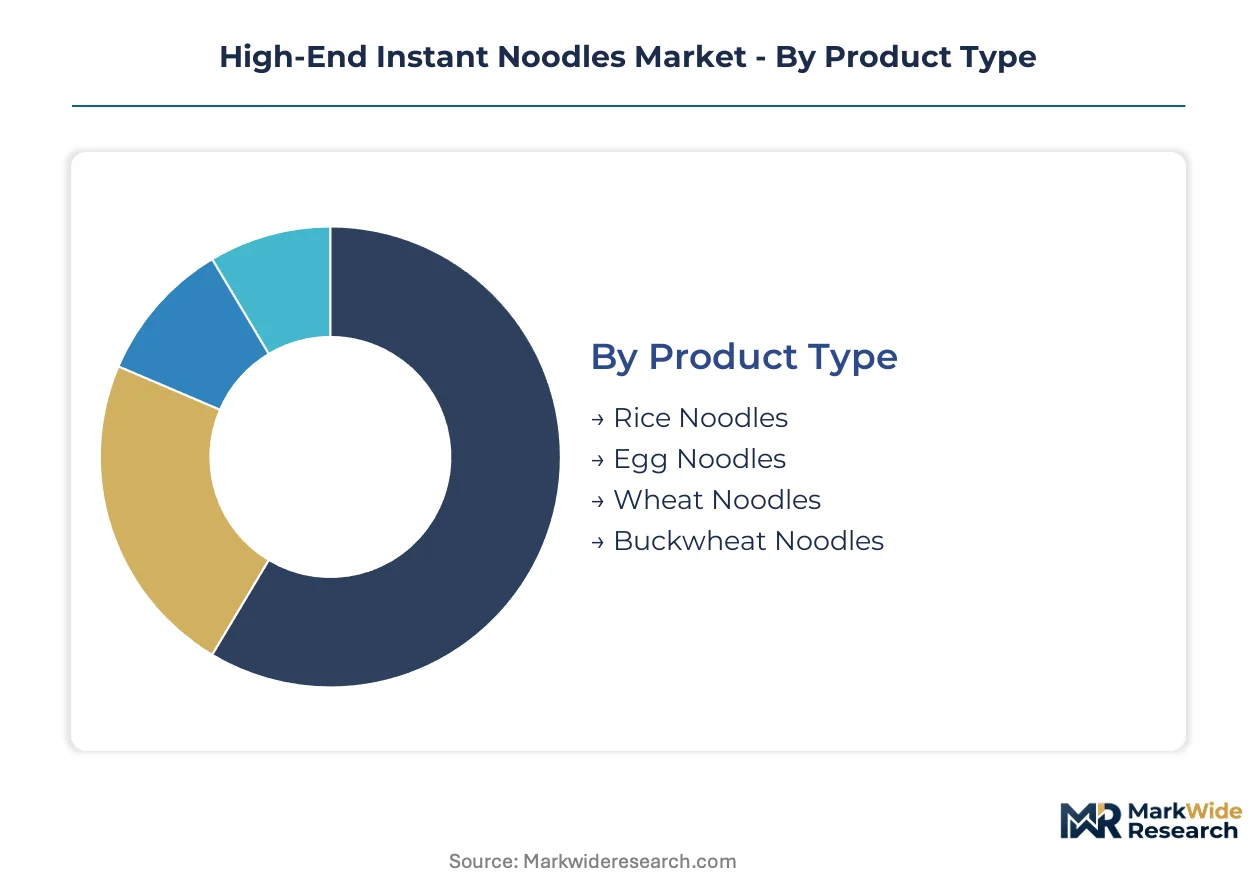
Segmentation in high-end instant noodles reveals how texture preferences, flavor intensity thresholds, and meal occasion requirements split demand across distinct consumer cohorts. Manufacturers align R&D pipelines and packaging investments to these fault lines, with cycle times varying dramatically between mature wheat formats and emerging buckwheat variants.
Product Type:
Wheat and buckwheat formats turn inventory fastest in Seoul and Tokyo convenience channels, while rice and egg noodles move more deliberately through specialty retail.
- Wheat Noodles:Manufactured from durum or high-protein wheat flour through steaming and flash-frying or air-drying processes. Urban millennials in South Korea's metropolitan clusters drive repeat purchase through familiar mouthfeel and scalable production economics that keep unit costs controlled.
- Buckwheat Noodles:Crafted from milled buckwheat groats with wheat flour binders for texture retention, these soba-style formats attract gluten-avoidant consumers in Japan seeking restaurant-authentic chew profiles without wheat dominance.
- Rice Noodles:Extruded from rice flour and starch blends, these translucent strands serve Southeast Asian flavor positioning in premium tiers where pho and laksa broth compatibility matters.
- Egg Noodles:Enriched with whole egg or egg powder for golden color and richer bite, these variants command loyalty in Hong Kong and Singapore where wonton noodle heritage shapes quality expectations.
Wheat noodles dominate installed base. Buckwheat noodles are where expansion concentrates.
Flavor Profile:
Cost tier stratification runs sharpest here, with spicy variants capturing premium shelf placement and savory formats anchoring volume turnover.
- Spicy:Chili oil, capsaicin extracts, and fermented pepper pastes deliver Scoville-calibrated heat levels. South Korea's MFDS sodium disclosure rules force reformulation trade-offs between heat intensity and clean-label positioning in Seoul convenience stores.
- Savory:Umami-dense broths built on kombu, bonito, and nucleotide enhancers satisfy daily consumption frequency in Japan where FOSHU functional claims add price premiums.
- Sweet:Mirin, brown sugar, and fruit-based glazes target younger demographics through dessert-positioned limited releases in Taiwan and Hong Kong.
- Sour:Rice vinegar, tamarind, and citrus infusions align with Thai and Vietnamese culinary associations, gaining traction in specialty Asian grocers across North American urban centers.
Savory flavors anchor volume throughput. Spicy profiles command the steepest expansion trajectory.
Packaging Type:
Margin pools diverge most dramatically across this dimension, with bowl formats justifying price multiples through complete meal solutions.
- Bowl:Rigid polypropylene or paperboard vessels with fitted lids, integrated fork/spoon compartments, and enhanced broth stability through double-wall insulation. Tokyo and Osaka office workers pay premiums for desk-ready consumption without additional dishware.
- Cup:Tapered paper or foam containers with peel-back foil lids, optimized for vending machine compatibility and hot water fill lines. South Korean train stations and convenience chains move these through high-velocity grab-and-go placement.
- Sachet:Multi-compartment foil pouches separating noodles from oil-based seasonings and dehydrated garnishes, favored by home pantry stockers in Japan seeking customization control.
- Pouch:Flexible laminated bags for bulk noodle packs without included broth bases, serving restaurant and foodservice channels in China where chefs build proprietary soup formulations.
Bowl packaging captures highest realized margins. Pouch formats serve downstream foodservice concentration.
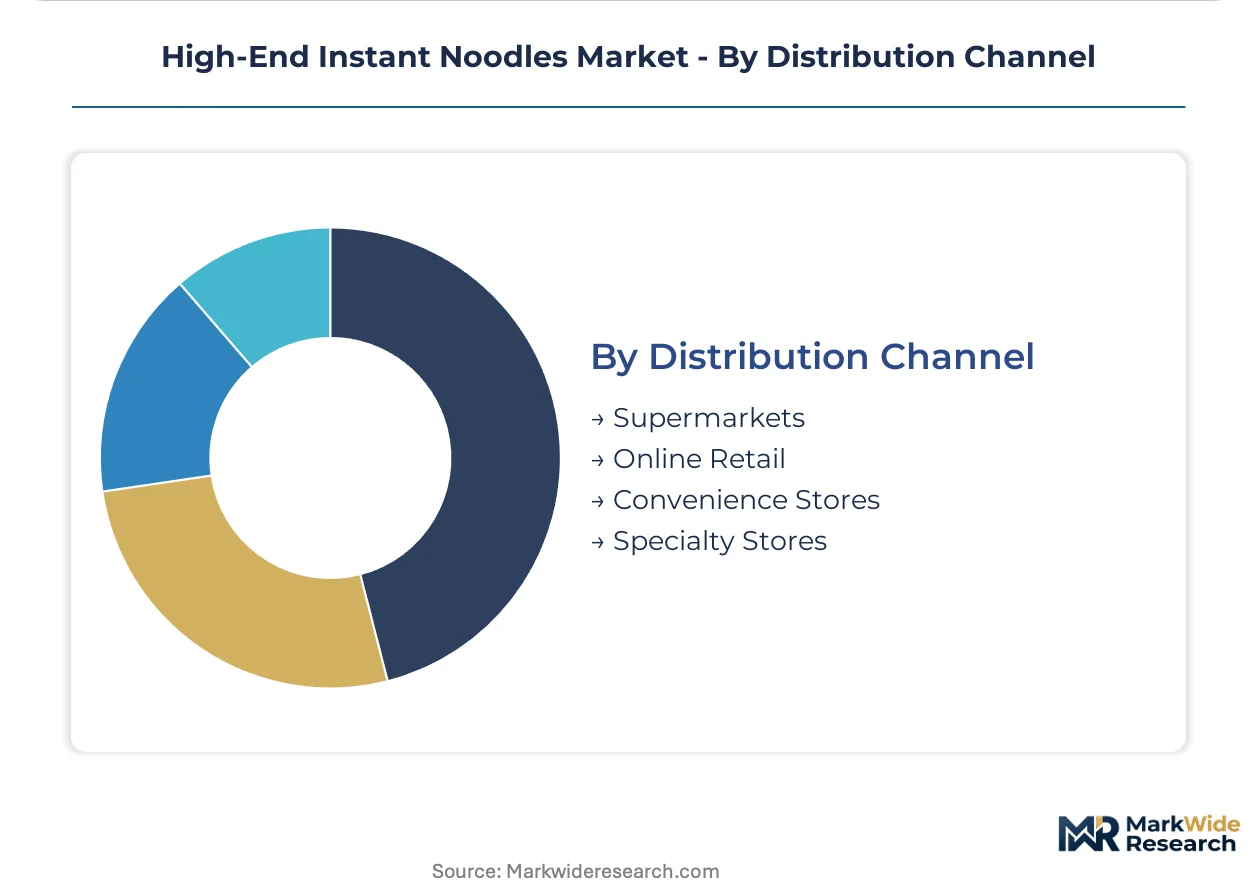
Distribution Channel:
Customer type stratification separates planned pantry replenishment from impulse trial generation.
- Supermarkets:Full assortment displays with promotional stacking drive family-sized multi-packs and seasonal flavor rotations. Japan's AEON and South Korea's E-Mart chains negotiate exclusive SKUs for store-brand premium tiers.
- Online Retail:Algorithmic recommendation engines and subscription boxes enable discovery of viral spicy variants before physical retail placement. China's Tmall and South Korea's Coupang capture cohorts aged 18-34 through challenge-driven content linkage.
- Convenience Stores:7-Eleven, Lawson, and CU chains optimize for single-serve bowl and cup formats in dense urban corridors where 24-hour availability supports late-night consumption occasions.
- Specialty Stores:Curated Asian grocers and import shops in Los Angeles, London, and Sydney stock limited-edition collaborations and regional exclusives for diaspora communities and adventurous food enthusiasts.
Supermarkets maintain widest SKU breadth. Online retail is climbing the fastest for new customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan anchors Northeast Asian distribution for premium noodle exports, handling containerized shipments of bowl-format products bound for North American and European retail channels. This maritime infrastructure underwrites South Korea's position as the primary launchpad for viral flavor innovations that propagate through social media channels before physical retail placement.
South Korea
Seoul's dense metropolitan corridors concentrate demand for single-serve meal solutions among office workers seeking desk-ready consumption. The MFDS enforces front-of-package sodium disclosure thresholds that expose reformulation gaps and force recipe architecture changes. The Busan-Ulsan industrial cluster hosts manufacturing facilities optimized for air-drying technology that reduces oil content while preserving texture integrity.
Japan
Tokyo and Osaka sustain premium pricing through FOSHU-compliant functional positioning that rewards clinically validated nutrient fortification. The Consumer Affairs Agency administers Foods with Nutrient Function Claims standards that shape permissible health-marketing language. The Kanto region's R&D intensity supports continuous innovation pipelines for umami-dense broth formulations built on nucleotide enhancers and kombu extracts.
China
Yangtze River Delta manufacturing hubs supply wheat noodle volume to domestic supermarkets while navigating escalating SAMR scrutiny on oil quality specifications. GB national food safety standards impose additive disclosure requirements that extend certification timelines for reformulated products. Shanghai's e-commerce logistics networks enable direct-to-consumer channels that bypass traditional retail gatekeepers for premium tier discovery.
United States
Los Angeles and New York specialty Asian grocers stock limited-edition collaborations for diaspora communities and adventurous food enthusiasts seeking authentic flavor profiles. The FDA monitors labeling compliance for imported instant noodle products while deferring to manufacturer country-of-origin standards for additive thresholds. California's import distribution centers handle containerized arrivals from Busan and Yokohama for West Coast market penetration.
Indonesia
Jakarta's urban millennial cohort drives trial generation for spicy flavor variants through mobile-first platform engagement before supermarket shelf placement. The national food and drug regulator enforces halal certification requirements that influence broth formulation decisions for export-oriented production. Java's manufacturing corridors concentrate wheat noodle capacity serving domestic convenience store chains and Southeast Asian export markets.
High-End Instant Noodles Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in flavor compound and packaging substrate supply. The vendor base organizes around three strategic archetypes: multinational conglomerates with diversified food portfolios, regional specialists dominating single geography through distribution depth, and viral-native challengers built on social media-driven discovery mechanics. Dominant competitive moves include backward integration into umami compound production and algorithmic recommendation engine partnerships that compress trial-to-purchase cycles.
Within the multinational tier, Nestlé S.A. and Nissin Foods Holdings Co., Ltd. exemplify platform-scale operations spanning multiple continents with diversified instant noodle portfolios. Ajinomoto Co., Inc. anchors the upstream specialist position through captive production of nucleotide-based flavor enhancers that supply competitor formulations. Samyang Foods occupies the viral-native archetype, having built dominant brand equity around challenge-driven spicy product lines that propagate through short-video platform algorithms before traditional retail placement.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Tingyi (International) Holdings Corp. |
| Nissin Foods Holdings Co., Ltd. |
| Ajinomoto Co., Inc. |
| Samyang Foods |
| Nongshim Co., Ltd. |
| PT Indofood CBP Sukses Makmur Tbk |
| Ottogi Corporation |
| Uni-President Enterprises Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta wheat processing corridor is compressing supplier margins and forcing tiered pricing concessions downstream, while Japanese air-drying facilities maintain premium positioning through functional certification premiums.
Pricing Analysis
Volume-discount tiering structures separate FOSHU-certified functional bowls from standard air-dried formats and economy flash-fried sachets. Price differentiation hinges on sodium disclosure compliance thresholds and umami compound sourcing depth. Pricing pressure stems from MFDS-mandated reformulation costs in South Korea. Home pantry stockers in Japan exhibit highest price sensitivity, while Tokyo office workers purchasing bowl formats show lowest elasticity.
Supply Chain Analysis
Extended payment terms from Busan-Ulsan manufacturers to specialty wheat suppliers are stabilizing input flows amid commodity volatility. Geographic supply concentrates in China, South Korea, and Japan. Raw material dependencies center on durum wheat, buckwheat groats, and nucleotide flavor enhancers. Single-source vulnerability around Ajinomoto's umami compound network poses structural risk. Distribution runs through e-commerce platforms and convenience store chains in dense metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based flavor customization services and chef-curated digital content layers are expanding faster than base product sales, creating attach-rate opportunities for manufacturers who bundle physical goods with recurring recipe access.
For Market Incumbents: Entrench position through backward integration into freeze-dried protein production and captive buckwheat sourcing from Hokkaido cooperatives. Viral-native challengers exploiting algorithmic discovery mechanics threaten shelf placement dominance. R&D intensity in Kanto-region facilities remains the critical defensive lever.
For New Entrants and Emerging Players: Build out white-space presence in North American specialty Asian grocers and European REACH-compliant export channels. Buckwheat gluten-avoidant positioning offers the most penetrable entry vector. Direct-to-consumer algorithmic targeting on short-video platforms provides the optimal go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with integrated digital content platforms and subscription flavor clubs. Long-term viability favors targets with FOSHU certification pipelines and air-drying technology assets. Monitor sodium disclosure threshold tightening across East Asian regulators as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Air-Drying Capacity Expansion | Non-fried production methods align with MFDS sodium disclosure mandates and health-positioned marketing claims. |
| FOSHU Certification Investment | Japan's Consumer Affairs Agency rewards clinically validated nutrient fortification with premium tier pricing permission. |
| E-Commerce Platform Integration | Algorithmic recommendation engines on Coupang and Tmall compress trial-to-purchase cycles for viral spicy variants. |
| Freeze-Dried Protein Backward Integration | Captive lyophilization technology differentiates bowl-format offerings against commodity fried-noodle competitors. |
| Buckwheat Sourcing Partnerships | Hokkaido and Gangwon Province groat suppliers anchor gluten-avoidant product line expansion with texture parity. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand managers at Nissin Foods and Samyang Foods, category buyers at AEON and E-Mart chains, umami compound procurement leads, and R&D directors specializing in air-drying technology. Secondary validation drew from MFDS sodium disclosure filings, Japan's Consumer Affairs Agency FOSHU registrations, SAMR GB standard updates, Nielsen retail audit data for Seoul and Tokyo convenience channels, and customs records for Busan Port noodle exports. Bottom-up SKU-level volume builds were triangulated against top-down category expenditure models.
Calibration against historical CAGRs and elasticity coefficients informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, flavor profile, packaging format, and distribution channel, with additional granularity on regulatory compliance tier. CAGRs were derived through regression analysis of premium convenience food adoption curves and urban millennial consumption frequency data. Forecast inputs incorporated wheat price volatility indices and e-commerce penetration trajectories for algorithmic discovery channels.
Stress conditions across wheat input costs, MFDS sodium threshold enforcement timelines, and REACH chemical safety standard expansions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about urbanization rates and premium convenience food preference shifts. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Sugar-Free Biscuits and Cookies Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market
Packaged Foods
Canned Soup Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Cookie Pucks Market
Packaged Foods
Canned Mushroom Market
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
Dried Soup Market
Packaged Foods
Injectable Cocoa Fillings Market
Packaged Foods
Global Packed Food Market
Packaged Foods
Packaged Corn on the Cob Market
Packaged Foods
Chestnut Flour Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
Middle-East and Africa Ready-To-Eat Food Market